
 Enterprise-Class Hybrid Storage Market | 2026-2036
Enterprise-Class Hybrid Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise-Class Hybrid Storage Market Insights
Enterprise storage engineering talent scarcity is unwinding legacy infrastructure refresh cycles as organizations struggle to staff hybrid cloud migration projects. Dell Technologies leverages its vertically integrated supply chain to sustain pricing power in all-flash array configurations. NetApp anchors its competitive position through software-defined storage architectures that span on-premises and hybrid cloud deployments. Huawei dominates procurement pipelines across Asia-Pacific state-owned enterprises despite Western market access constraints.
Enterprise-class hybrid storage denotes integrated storage platforms combining solid-state flash tiers with magnetic disk or tape media, typically delivering sub-millisecond latency for hot data and cost-optimized capacity for archival workloads through automated tiering algorithms. These systems serve primary commercial purposes including high-availability transaction processing, disaster recovery orchestration, and regulatory-compliant long-term data retention. All-flash arrays command the dominant revenue share within product type segmentation while hybrid flash arrays capture the fastest expansion trajectory among cost-sensitive mid-market buyers. Deployment model segmentation reveals hosted private cloud and hybrid cloud configurations as the primary margin pools, with colocation services experiencing accelerated uptake among telecommunications carriers seeking to defer capital expenditures.
FDA 21 CFR Part 11 validation requirements shape storage procurement for pharmaceutical manufacturing quality systems, while EU GDPR data-localization mandates and NIST SP 800-53 controls drive encryption and access-log specifications across government and financial end users. SEC cybersecurity disclosure rules now compel publicly traded manufacturing corporations to document data resilience architectures in regulatory filings. Stakeholders must monitor evolving sovereign data classification regimes to determine whether in-country infrastructure deployment or certified hybrid cloud configurations satisfy emerging compliance thresholds.
Market Dynamics
Enterprise storage procurement is fracturing along sovereignty fault lines as NIST cybersecurity frameworks and EU CSRD mandates force buyers to validate data residency and encryption standards before vendor selection.
Growth Catalysts
- Financial regulatory density:SEC cybersecurity disclosure rules compel publicly traded manufacturing corporations to document data resilience architectures, expanding audit-driven refresh cycles.
- EU CSRD disclosure mandates:Energy reporting requirements for enterprise IT infrastructure are reshaping procurement specifications toward certified efficient configurations.
- Flash tiering algorithms:Automated data placement between solid-state and magnetic media is reducing operational overhead for high-availability transaction processing workloads.
Market Restraints
- NAND flash supply concentration:Memory wafer fabrication gravity in South Korea and Taiwan creates input cost volatility and geopolitical exposure for array manufacturers.
- FDA 21 CFR Part 11 validation:Pharmaceutical quality system requirements impose 12-18 month certification timelines that compress vendor selection pools.
- Cloud object storage substitution:Hyperscale archival services are capturing secondary tier workloads previously assigned to on-premises hybrid arrays.
Strategic Opportunities
- Sovereign cloud configurations:Germany's data localization requirements and Japan's METI-guided infrastructure standards are creating premium deployment channels for certified hybrid architectures.
- Telecommunications carrier colocation:Hosted private cloud services allow network operators to defer capital expenditures while maintaining latency guarantees.
- AI/ML training data lakes:Converging high-throughput flash tiers with GPU compute fabrics is opening new performance-tier pricing segments.
Industry Challenges
- Enterprise storage engineering scarcity:Organizations struggle to staff hybrid cloud migration projects, unwinding legacy infrastructure refresh timelines.
- Multi-generational array integration:Automated tiering algorithms must reconcile metadata schemas across fifteen-year equipment lifecycles without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise-Class Hybrid Storage Market |
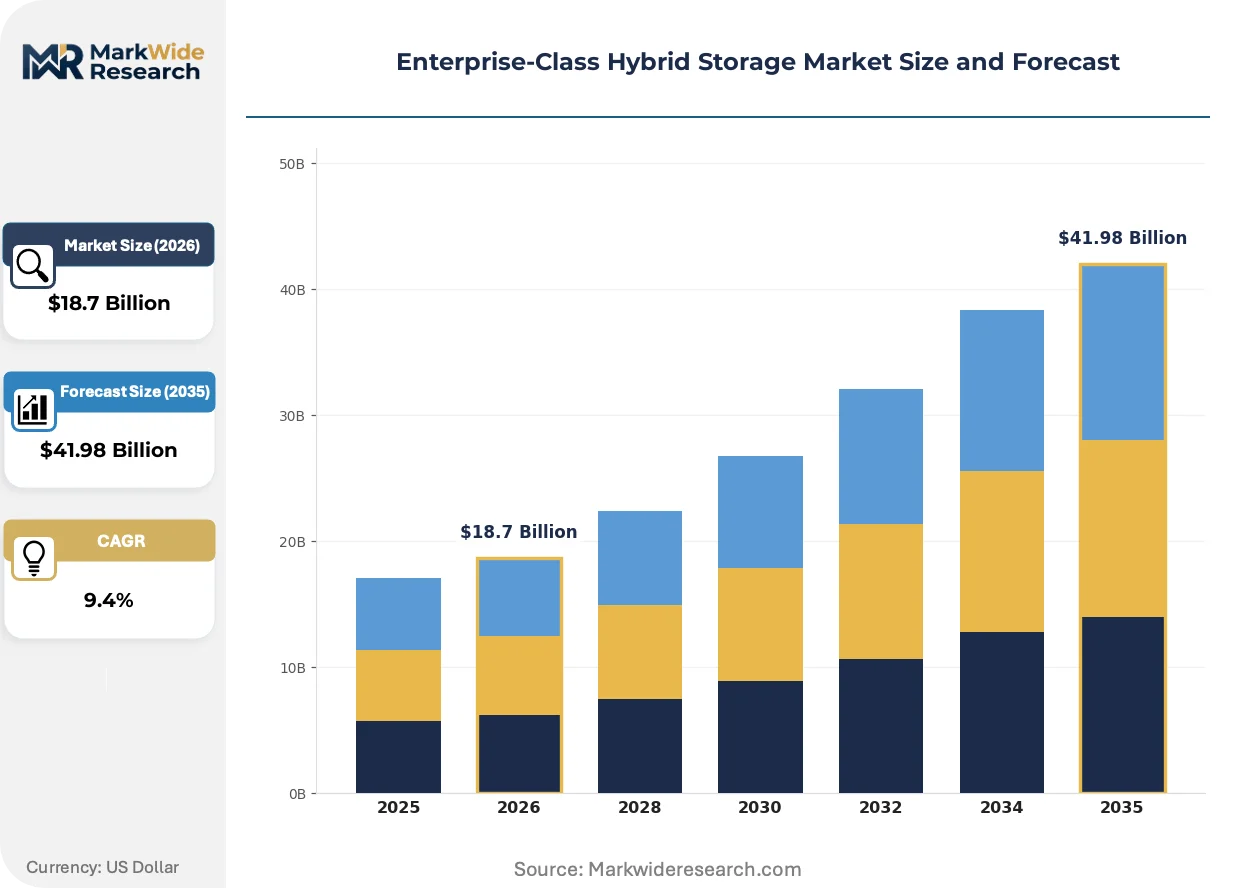
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Flash Arrays, Solid-State Hybrid Drives, Hybrid Flash Arrays, Tape Storage Systems Deployment Model: On-Premises, Hosted Private Cloud, Colocation, Hybrid Cloud Application: Data Backup & Recovery, Virtual Desktop Infrastructure, Big Data Analytics, Content Delivery End User: Financial Services, Telecommunications Carriers, Government Agencies, Manufacturing Corporations |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, IBM, NetApp, Hitachi Vantara, Huawei, Fujitsu, Pure Storage, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise-Class Hybrid Storage Market Trends and Innovations
Software-defined storage architectures are dissolving hardware-centric procurement patterns, enabling buyers to disaggregate controller intelligence from media enclosures and source components through multi-vendor contracts.
Computational storage drives with embedded processing capability are decomposing the traditional host-controller-storage hierarchy. Financial services firms deploying these devices for fraud detection analytics are compressing data movement latency by executing queries at the media layer. This topology is collapsing the distinction between storage and compute procurement categories.
EU CSRD sustainability disclosure mandates are forcing storage vendors to document embodied carbon and operational energy intensity across product lifecycles. Procurement teams in German manufacturing and French pharmaceuticals are now weighting environmental performance equally with latency specifications. Array manufacturers are responding with modular designs that isolate high-wear components for targeted replacement.
Consumption-based financing structures are displacing traditional capital purchase models for mid-market buyers. Managed service providers in the United States and Japan are offering guaranteed-IOPS contracts that bundle hardware, software, and operational support into single monthly obligations. This shift transfers technology obsolescence risk from end-users to vendors while accelerating refresh cycles.
Enterprise-Class Hybrid Storage Market Segmentation
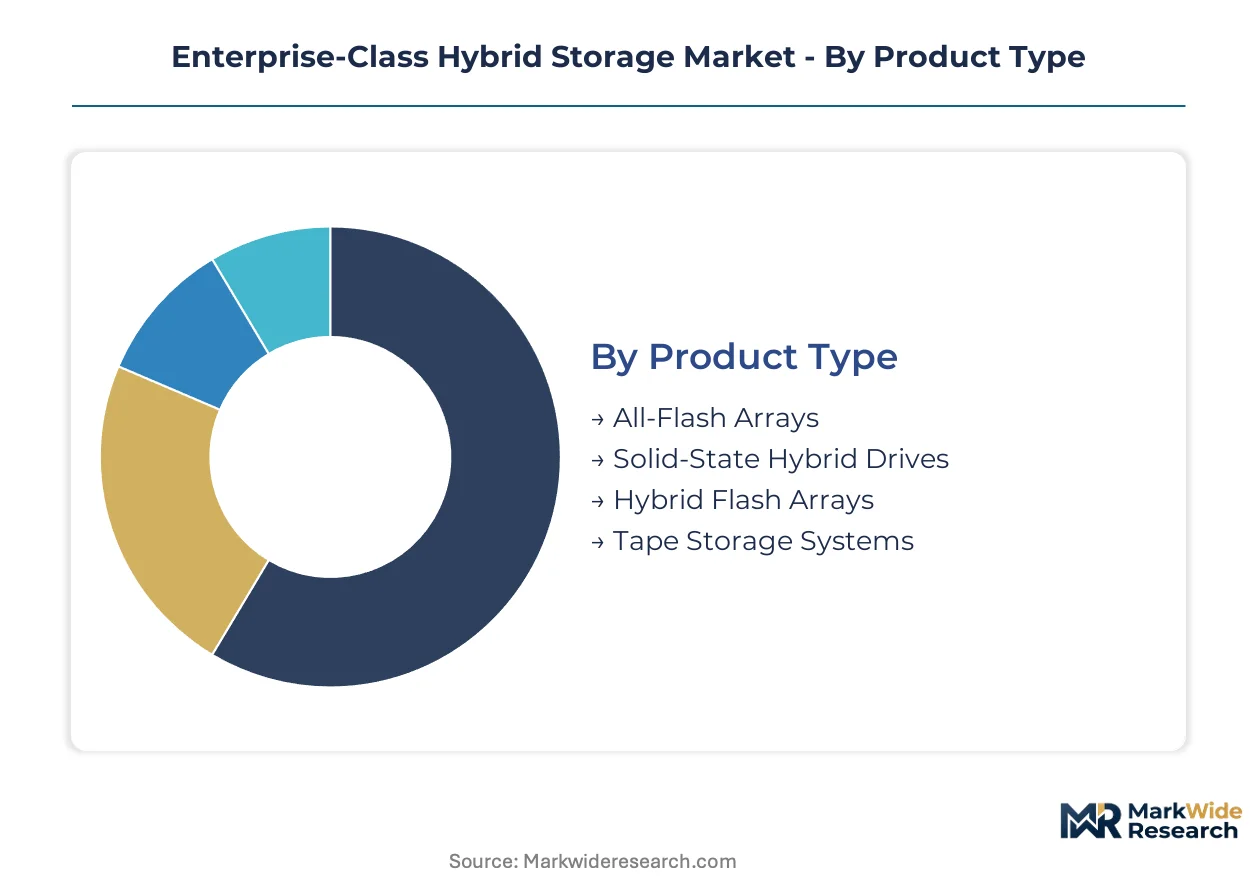
Segmentation in enterprise-class hybrid storage reveals how procurement criteria diverge across workload types and regulatory environments. Channel strategies must align with deployment complexity, as on-premises configurations require direct sales engineering while cloud-adjacent models flow through managed service providers.
Product Type:
Channel mix varies sharply by product architecture, with all-flash arrays commanding direct vendor relationships and hybrid configurations flowing through systems integrators.
- All-Flash Arrays:Pure solid-state architectures deliver sub-millisecond latency for high-frequency trading and real-time fraud detection. Financial services firms in the United States and Japan concentrate procurement here, driven by SEC disclosure mandates requiring documented data resilience for transaction systems.
- Hybrid Flash Arrays:Automated tiering between flash and magnetic media balances performance with cost per terabyte. Mid-market manufacturers across Germany favor these configurations as EU CSRD energy reporting requirements reshape specifications toward certified efficient platforms.
- Solid-State Hybrid Drives:Integrated single-device solutions combine NAND cache with spinning platters for entry-tier server deployments.
- Tape Storage Systems:Magnetic tape libraries provide air-gapped archival capacity for regulatory-mandated retention periods.
All-Flash Arrays dominate installed base. Hybrid Flash Arrays are where expansion concentrates.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models, with premium pricing attaching to latency-guaranteed hosted configurations.
- On-Premises:Customer-operated infrastructure within owned data centers delivers maximum control over encryption key management and physical access protocols. Government agencies in Japan and Germany mandate this model for sovereign data classification workloads.
- Hybrid Cloud:Integrated on-premises and public cloud orchestration enables workload portability across sovereignty boundaries. Financial services firms deploy these architectures to satisfy GDPR localization requirements while maintaining burst capacity.
- Hosted Private Cloud:Single-tenant infrastructure operated by third-party providers offers dedicated resource pools without capital deployment.
- Colocation:Customer-owned equipment housed in multi-tenant facilities allows telecommunications carriers to defer data center construction.
On-Premises retains the largest revenue footprint. Hybrid Cloud configurations are climbing the fastest.
Application:
Volume concentration maps to data gravity patterns, with backup workloads anchoring capacity procurement and analytics driving flash-tier acceleration.
- Data Backup & Recovery:Immutable snapshot repositories and disaster recovery orchestration consume the majority of hybrid array capacity. Manufacturing corporations facing SEC cybersecurity disclosure rules are expanding audit-driven refresh cycles for these systems.
- Big Data Analytics:High-throughput storage fabrics feed GPU clusters for machine learning training pipelines. Pharmaceutical quality systems under FDA 21 CFR Part 11 validation requirements deploy these configurations for manufacturing process analytics.
- Virtual Desktop Infrastructure:Persistent user profile storage and golden image distribution demand consistent low-latency response.
- Content Delivery:Edge-cached media libraries serve streaming and software distribution workloads.
Data Backup & Recovery commands the deepest installed base. Big Data Analytics is gaining share fastest.
End User:
Customer type determines specification rigor, with regulated industries imposing certification requirements that compress vendor selection pools.
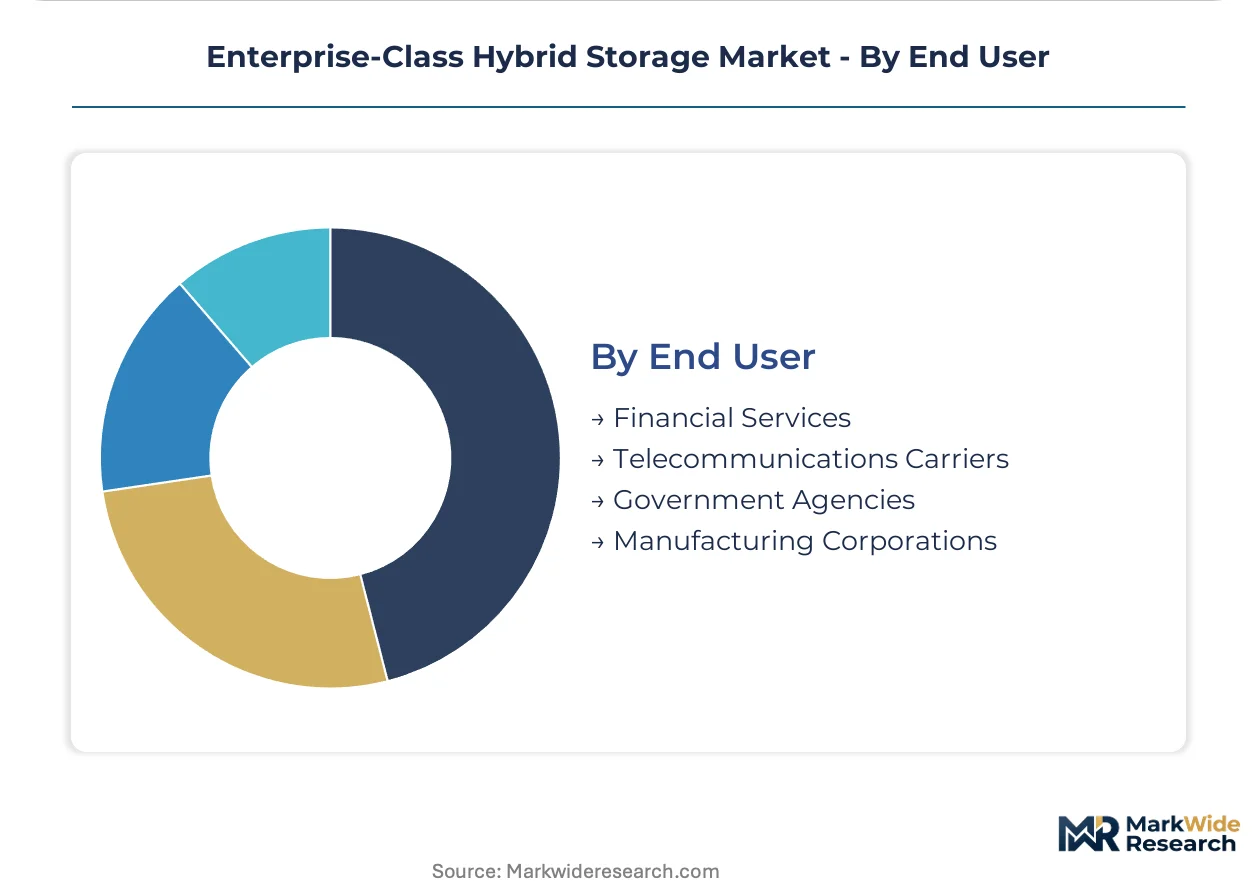
- Financial Services:Banks, insurers, and payment processors require sub-millisecond latency for transaction processing alongside comprehensive audit logging. NIST SP 800-53 controls and SEC disclosure rules drive encryption and access-log specifications across this segment.
- Government Agencies:Federal and state entities mandate data residency and supply chain provenance. Germany's data localization requirements and Japan's METI-guided infrastructure standards create premium deployment channels for certified hybrid architectures.
- Telecommunications Carriers:Network operators seek colocation and hosted private cloud services to defer capital expenditures.
- Manufacturing Corporations:Industrial firms balance operational technology integration with enterprise IT consolidation.
Financial Services anchors revenue concentration. Government Agencies are where premium pricing endures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure mandates and NIST cybersecurity frameworks anchor United States demand for enterprise-class hybrid storage, while EU CSRD energy reporting and Japan's METI-guided infrastructure standards shape procurement across other concentrated markets.
United States
Financial services firms drive all-flash array procurement for sub-millisecond transaction processing, while manufacturing corporations face SEC cybersecurity disclosure rules compelling documented data resilience architectures. FDA 21 CFR Part 11 validation requirements shape pharmaceutical quality system deployments. The New York financial district and Silicon Valley data center clusters host the densest hybrid cloud orchestration installations.
Germany
EU CSRD disclosure mandates are reshaping procurement specifications toward certified energy-efficient configurations among mid-market manufacturers. Sovereign data localization requirements under GDPR create premium deployment channels for certified hybrid architectures. The Frankfurt financial hub and Munich industrial corridor concentrate hosted private cloud adoption for automotive and precision engineering supply chains.
Japan
METI-guided infrastructure standards and financial regulatory density create premium deployment opportunities for latency-guaranteed configurations. Government agencies mandate on-premises infrastructure for sovereign data classification workloads. Tokyo's Kanto region anchors hyperscale data center construction, while Osaka's Kansai corridor hosts telecommunications carrier colocation facilities.
China
State-owned enterprises across telecommunications and financial services drive procurement pipelines for hybrid flash arrays despite Western market access constraints for foreign vendors. Dual carbon goals and national data security laws accelerate domestic infrastructure localization. Beijing-Tianjin-Hebei and the Yangtze River Delta concentrate government cloud and smart city storage deployments.
United Kingdom
Financial services regulatory density and GDPR localization requirements sustain demand for hybrid cloud configurations enabling workload portability across sovereignty boundaries. The Prudential Regulation Authority and Financial Conduct Authority impose audit logging and encryption specifications. London's financial district and Thames Valley technology corridor host the densest enterprise storage engineering talent pools.
Enterprise-Class Hybrid Storage Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated manufacturers commanding pricing power in all-flash configurations while software-defined specialists capture hybrid cloud orchestration margins. The vendor base stratifies across three tiers: diversified technology conglomerates with captive supply chains, pure-play storage architects, and regional system integrators. Dominant competitive moves include backward integration into NAND flash supply and consumption-based financing structures displacing capital purchase models.
Within the diversified technology tier, Dell Technologies and Hewlett Packard Enterprise occupy positions anchored by vertically integrated supply chains spanning controller silicon to enclosure assembly. NetApp exemplifies the software-defined archetype, with its architecture spanning on-premises and hybrid cloud deployments. Huawei sits within the Asia-Pacific state-owned enterprise channel despite Western market access constraints.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM |
| NetApp |
| Hitachi Vantara |
| Huawei |
| Fujitsu |
| Pure Storage |
| Lenovo |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with NAND flash foundries lock in supply access and price visibility for array manufacturers navigating South Korean and Taiwanese wafer fabrication concentration. These arrangements insulate vertically integrated vendors from spot market volatility while binding mid-tier competitors to inflexible cost structures during demand troughs.
Pricing Analysis
Geographic price spreads between Frankfurt and Dallas data center deployments reach three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU CSRD energy disclosure mandates and volume scale commitments to hyperscale cloud providers drive differentiation. Pricing pressure stems from cloud object storage substitution capturing archival tier workloads. Mid-market manufacturers exhibit highest price sensitivity, while financial services firms in Tokyo and New York accept premium latency guarantees.
Supply Chain Analysis
Strait of Malacca transit underwrites NAND flash module delivery schedules from South Korean fabrication plants to assembly facilities in Malaysia and Thailand. Controller silicon production concentrates in Taiwan, Japan, and the United States, with firmware development anchored in Israel and India. Single-source vulnerability around advanced node DRAM creates exposure for tier-one array configurations. Distribution runs through direct vendor relationships for all-flash deployments and systems integrator channels for hybrid configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face substitution defense imperatives as hyperscale cloud archival services displace on-premises secondary tier workloads previously captured by hybrid arrays.
For Market Incumbents: Fortify software-defined storage architectures spanning on-premises and hybrid cloud deployments to neutralize cloud-native substitute threats. Deepen backward integration into NAND flash supply through captive foundry relationships or long-term offtake structures with South Korean suppliers. Accelerate FDA 21 CFR Part 11 and EU CSRD certification pipelines to compress vendor selection pools for regulated pharmaceutical and manufacturing segments.
For New Entrants and Emerging Players: FDA 510(k) fast-track equivalency for storage systems serving pharmaceutical quality applications opens compressed procurement channels. Target telecommunications carrier colocation services in Japan and Germany where capital deferral preferences outweigh brand loyalty. Pursue consumption-based financing structures that transfer technology obsolescence risk from end-users to vendor balance sheets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors software-defined specialists with hybrid cloud orchestration capabilities over hardware-centric legacy architectures. Long-term viability hinges on AI/ML training data lake positioning where converged flash-compute fabrics command performance-tier pricing. Monitor sovereign cloud certification velocity across Germany and Japan as inflection indicator for premium deployment channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into NAND Supply | Captive wafer access insulates Dell Technologies and HPE from foundry pricing volatility. |
| Software-Defined Architecture Expansion | NetApp's cloud-spanning platforms capture hybrid orchestration margins from hardware-centric competitors. |
| Sovereign Cloud Certification Investment | EU CSRD and Japan METI compliance unlocks premium pricing in government and financial segments. |
| Consumption-Based Financing Launch | Managed service contracts transfer obsolescence risk while accelerating refresh cycles among mid-market buyers. |
| AI/ML Data Lake Convergence | Flash tier integration with GPU compute fabrics opens new performance-tier pricing segments. |
Research Methodology
Operator-level perspectives from enterprise storage architects, data center procurement officers, systems integration specialists, and hyperscaler infrastructure planners anchored the qualitative base. Primary interviews combined with secondary validation across SEC 10-K infrastructure disclosures, hyperscaler capex reports, FDA 510(k) device filings, and EU CSRD sustainability submissions. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across product tiers and deployment configurations.
Sensitivity analysis tested forecast robustness against NAND flash price volatility, sovereign cloud certification timeline slippage, and cloud substitution acceleration. Segmentation dimensions spanned product architecture, deployment model, end-user regulatory intensity, and regional data localization requirements. CAGRs derived from historical refresh cycle analysis and projected adoption curve inflections for hybrid cloud orchestration and AI/ML storage fabrics.
Decision-makers should treat outputs as directional under stable geopolitical access to South Korean and Taiwanese semiconductor supply; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as FDA validation timeline extensions and EU energy disclosure enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Global Portable Data Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
External Storage Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Powered Storage Devices Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Australia Data Center Storage Market
Data Storage
Storage Virtualization Market
Data Storage
Enterprise Storage System Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Storage Class Memory Market
Data Storage
North America SSD Caching Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Data Storage Devices Market