
 USB Key Market | 2026-2036
USB Key Market Size, Share, and Industry Trends Forecast 2026-2036
USB Key Market Analytics
A capital-intensity divergence between flash memory fabricators and assembly-only brands is redrawing competitive boundaries in the USB key sector. Samsung Electronics leverages captive NAND production to sustain margin control across high-speed USB and USB-C portfolios. Kingston Technology Corporation anchors its position through vertical control over controller firmware and custom security silicon. PNY Technologies navigates the mid-tier through channel dominance in North American retail and education verticals.
A USB key is a portable solid-state data storage device incorporating flash memory, a USB controller, and a standard-A or USB-C connector, typically operating via bus power without external drivers. The device stores, transfers, and secures digital assets across disconnected or air-gapped environments where network transmission is prohibited or impractical. USB-C product types are capturing disproportionate growth as laptop OEMs eliminate legacy ports, while AES 256-bit encryption levels command premium positioning in defense, healthcare, and financial applications. Standard USB remains the volume baseline in emerging markets and legacy enterprise fleets, though margin compression is accelerating at the 4GB and 8GB storage capacity tiers.
FCC electromagnetic emissions standards and NIST SP 800-111 encryption guidelines shape product certification requirements for US-bound USB keys, while GDPR data-protection mandates in Europe are driving corporate buyers toward hardware-encrypted units with remote management capability. The EU AI Act and emerging supply-chain disclosure rules under CSRD will add compliance layers for manufacturers sourcing memory from non-EU fabrication facilities. Stakeholders must monitor whether regulatory divergence between Washington and Brussels fragments certification regimes or creates harmonized transatlantic security standards.
Market Dynamics
The USB Key Market is experiencing a structural compression as port standardization eliminates legacy compatibility buffers while encryption mandates simultaneously elevate minimum performance floors. This dual pressure is forcing manufacturers to absorb certification costs across shrinking SKU diversity.
Growth Catalysts
- NIST SP 800-111:Federal encryption guidelines in the US are mandating AES 256-bit certification for government procurement, creating a baseline specification that commercial buyers increasingly mirror.
- Industrial automation clusters:German manufacturing hubs require ruggedized high-capacity keys for offline firmware updates in air-gapped production environments.
- USB-C connector transition:Laptop OEMs eliminating legacy ports are accelerating hardware refresh cycles across enterprise IT fleets.
Market Restraints
- NAND flash supply concentration:Captive production by integrated memory fabricators limits assembly-only brands' margin control and supply security.
- GDPR enforcement friction:Remote management capability requirements for hardware-encrypted units add firmware development burden without corresponding price elasticity.
- Cloud storage substitution:Enterprise file synchronization services are compressing demand for mid-capacity transfer keys in connected environments.
Strategic Opportunities
- EU AI Act compliance layers:Emerging supply-chain disclosure rules under CSRD create service revenue potential for audit-ready encryption key management platforms.
- Healthcare vertical penetration:HIPAA-covered entities in the US are expanding hardware-encrypted key procurement for medical imaging transport.
- Biometric-authentication convergence:Fingerprint sensor integration with hardware encryption is opening premium positioning in defense and financial applications.
Industry Challenges
- FCC certification timelines:Electromagnetic emissions testing for US-bound products creates launch delays that misalign with seasonal education procurement cycles.
- Controller firmware talent scarcity:Specialized security silicon development requires expertise concentrated among legacy semiconductor engineering pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Key Market |
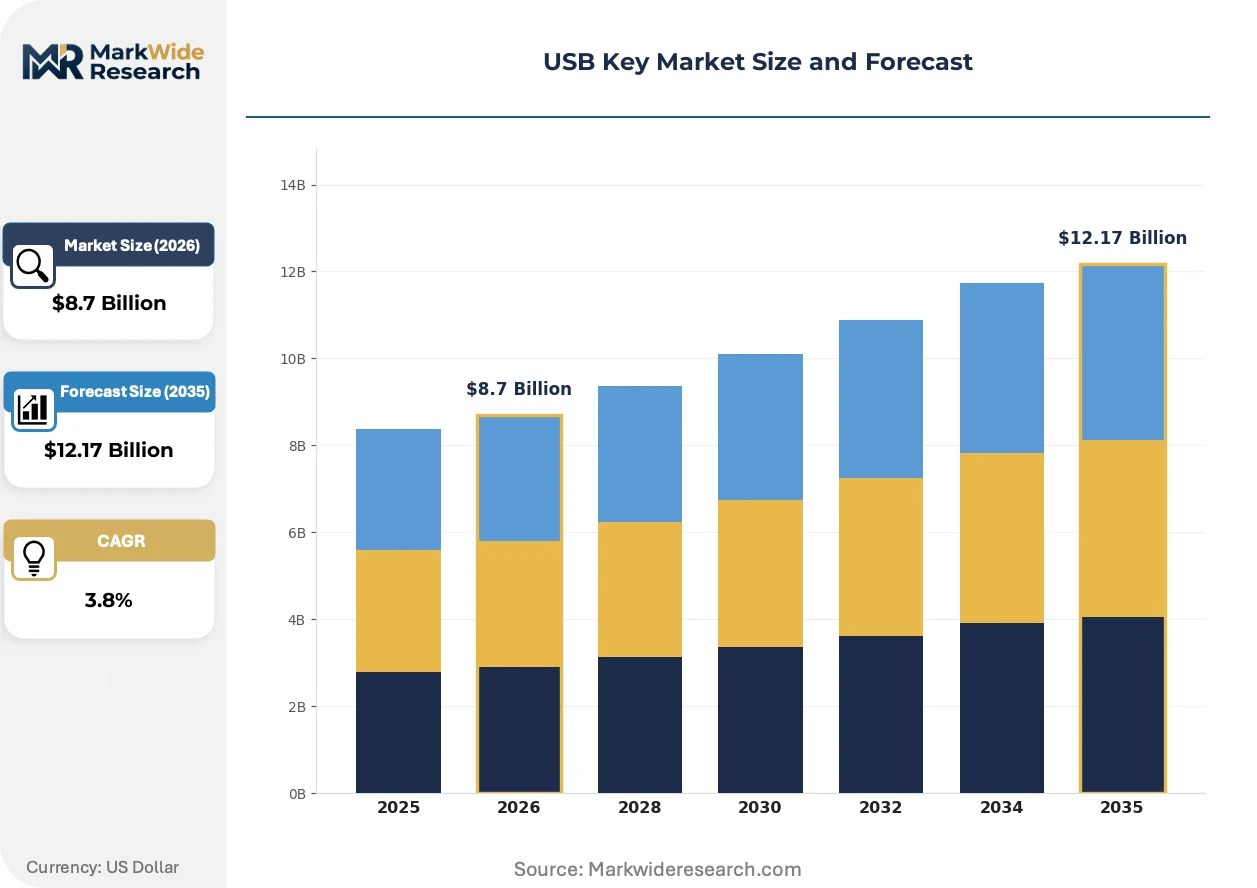
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard USB, High-Speed USB, Mini USB, USB-C Storage Capacity: 4GB, 8GB, 16GB, 32GB Application: Data Transfer, Backup Storage, Security, Multimedia Encryption Level: No Encryption, Basic Encryption, AES 128-bit, AES 256-bit |
| Companies Covered | Transcend Information, Inc, Netac, SanDisk LLC, Oyen Digital, Fanxiang, Kingston Technology Corporation, PNY Technologies, Inc., Micron Technology, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Key Market Evolving Landscape
Active port elimination by device manufacturers is collapsing compatibility windows faster than replacement cycles, forcing encryption key vendors to front-load R&D against obsolescence risk. This acceleration is compressing the viable lifespan of connector-dependent hardware.
Hardware-encrypted USB key architecture is bifurcating between fixed-function security controllers and programmable secure elements. Defense contractors and healthcare systems are adopting the latter for customizable key escrow policies. This technology divergence is bifurcating supplier tiers between firmware-integrated specialists and commodity assembly houses.
GDPR's data-protection mandates are reshaping corporate procurement specifications across Europe, with hardware-encrypted units now required for cross-border personnel transfers. Financial services firms in Frankfurt and London are deploying remote management capability as a standard fleet feature. Manufacturers are responding by embedding cellular or Wi-Fi modules for geofencing and remote wipe functionality.
Enterprise IT departments are consolidating vendor relationships around single-source encryption key suppliers with integrated device management platforms. Value-added resellers are losing attach revenue as direct procurement portals disintermediate traditional distribution. This pattern is most pronounced in North American healthcare systems undergoing HIPAA security rule refreshes.
USB Key Market Segmentation
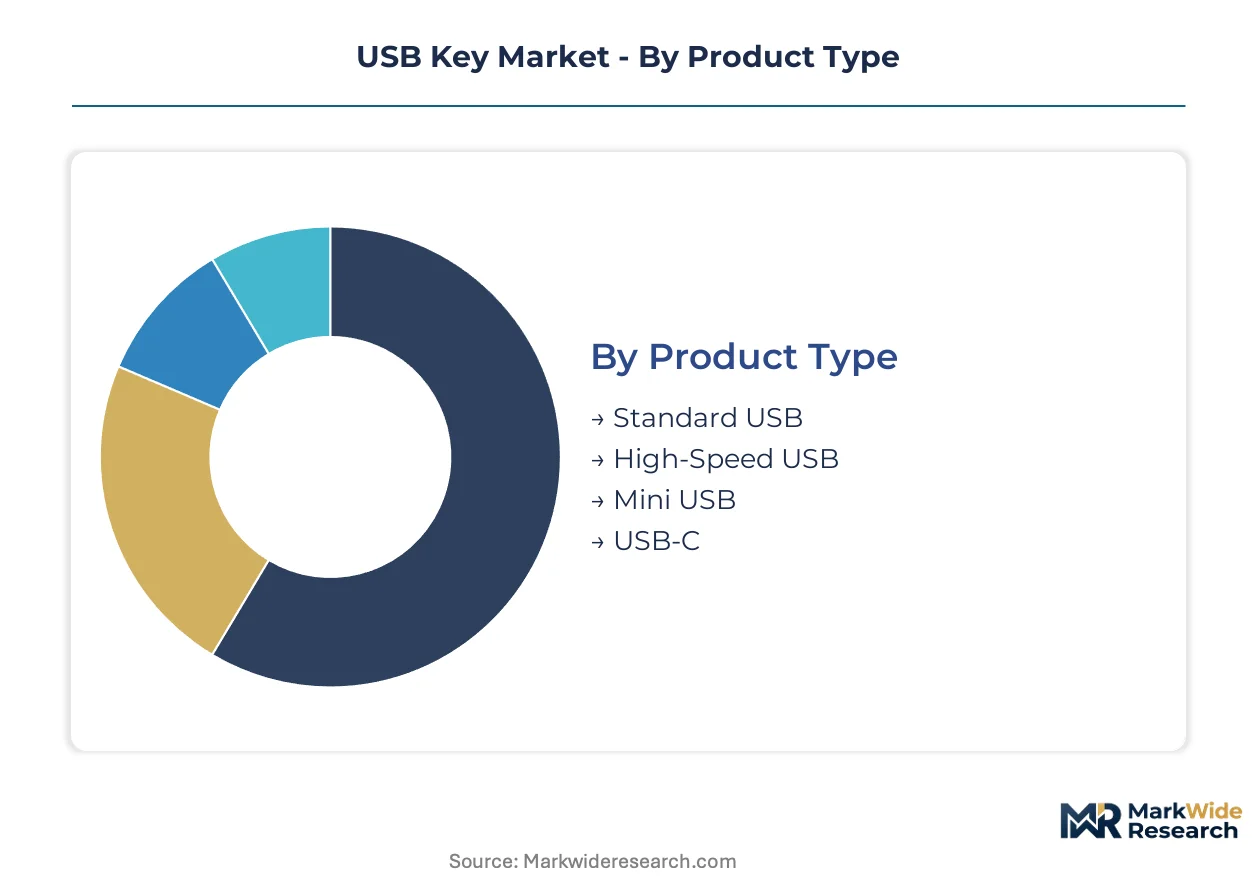
USB key segmentation reveals divergent vulnerability to cloud substitution and encryption mandates. Port standardization and capacity tier compression are forcing manufacturers to prioritize connector transition and security certification over legacy volume segments.
Product Type:
Cloud file-sharing services exert the strongest displacement pressure on legacy connector formats lacking hardware encryption integration.
- USB-C:Reversible connector architecture supports USB 3.2 and USB4 protocols with power delivery up to 100W. Laptop OEMs in Germany and the United States are eliminating legacy ports from enterprise fleet refreshes, compressing the viable sales window for backward-compatible alternatives.
- High-Speed USB:USB 3.0/3.1 Gen 1 and Gen 2 controllers enable transfer rates exceeding 400 MB/s. Healthcare systems in the United States undergoing HIPAA security rule refreshes are standardizing on high-speed encrypted variants for medical imaging transport.
- Standard USB:USB 2.0 Type-A connector dominates emerging market procurement where legacy infrastructure persists.
- Mini USB:Deprecated connector standard retained only in industrial automation legacy systems requiring backward compatibility.
USB-C holds the steepest expansion curve; Standard USB retains volume leadership in price-sensitive procurement channels.
Storage Capacity:
Margin compression intensifies at entry-level tiers where NAND flash oversupply and cloud substitution converge.
- 32GB:Quad-layer cell (QLC) and triple-level cell (TLC) NAND configurations support operating system boot environments and offline firmware repositories. German industrial automation clusters require ruggedized 32GB keys for air-gapped production line updates.
- 16GB:MLC and TLC architectures balance cost with reliability for enterprise documentation and compliance archiving. Financial services procurement in Frankfurt specifies 16GB as the minimum capacity for cross-border personnel data transfers under GDPR.
- 8GB:SLC and MLC options serve education sector licensing and software distribution.
- 4GB:Lowest viable production tier for promotional and embedded applications.
32GB commands the steepest expansion trajectory; 16GB anchors mid-tier enterprise procurement volume.
Application:
Security and backup segments demonstrate the strongest insulation from cloud substitution through regulatory mandates and air-gap requirements.
- Security:Hardware-encrypted implementations with secure element integration protect cryptographic keys and authentication credentials. Defense contractors in the United States are adopting programmable secure elements for customizable key escrow policies.
- Backup Storage:Offline cold storage configurations satisfy ransomware recovery and long-term archival requirements. HIPAA-covered entities are expanding hardware-encrypted key procurement for patient record redundancy.
- Data Transfer:General-purpose file movement between disconnected systems.
- Multimedia:Consumer content storage and playback applications.
Security applications gain share fastest; Data Transfer retains baseline volume across legacy enterprise fleets.
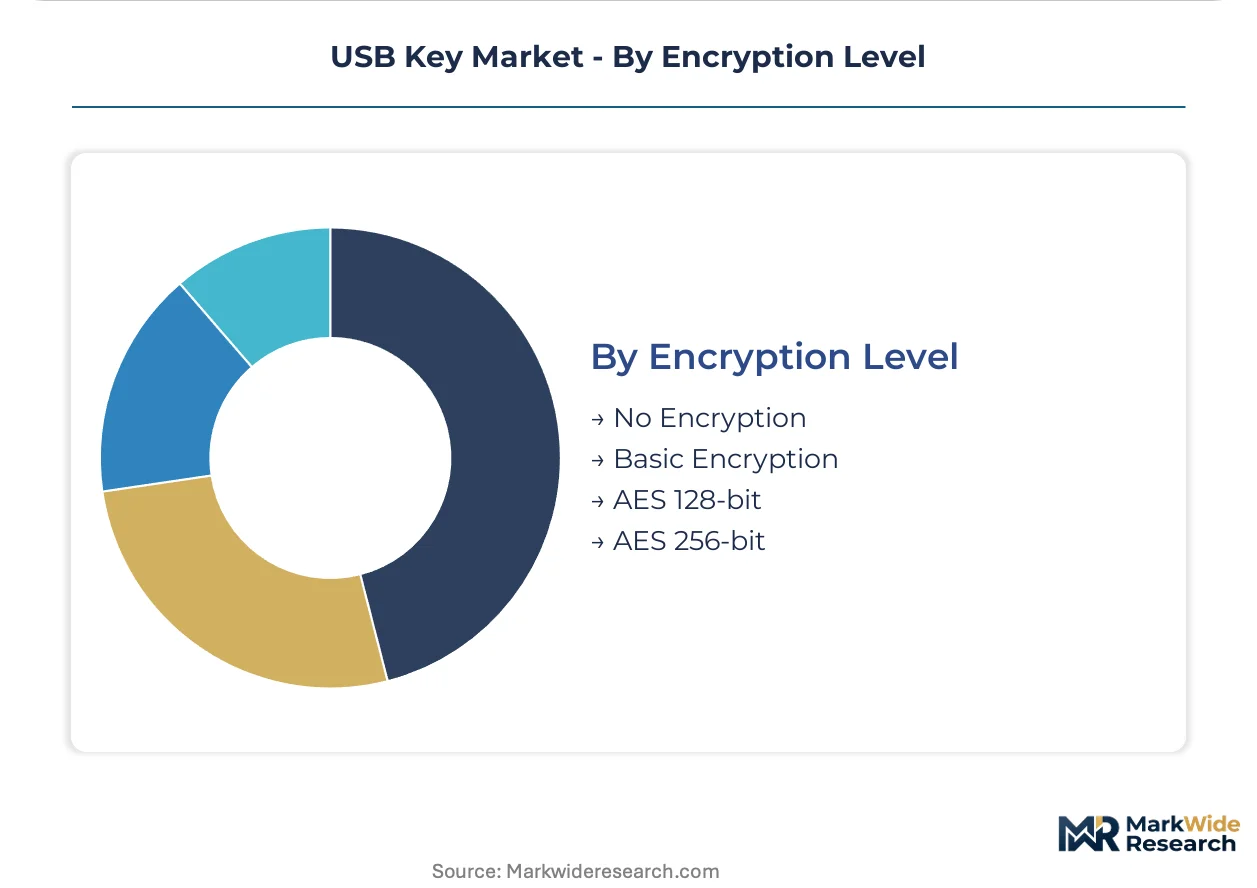
Encryption Level:
Federal and supranational certification requirements are collapsing demand for unencrypted and basic-encrypted tiers in regulated verticals.
- AES 256-bit:Hardware-implemented symmetric encryption meets NIST SP 800-111 guidelines for federal procurement and GDPR technical safeguards. AES 256-bit certification is becoming the de facto baseline for commercial buyers mirroring government specifications.
- AES 128-bit:Reduced-round hardware encryption serves mid-tier enterprise security requirements with lower computational overhead.
- Basic Encryption:Software-based or proprietary cipher implementations without third-party certification.
- No Encryption:Unencrypted flash storage for non-sensitive consumer applications.
AES 256-bit climbs the fastest; No Encryption retains residual volume in emerging market consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in emerging markets exhibit acute price sensitivity toward entry-capacity tiers, while German and US defense contractors absorb premium pricing for hardware-encrypted units without demand elasticity.
United States
Defense contractors and HIPAA-covered healthcare systems drive procurement of AES 256-bit encrypted keys with remote management capability. FCC electromagnetic emissions standards and NIST SP 800-111 encryption guidelines shape product certification requirements for US-bound shipments. Medical imaging transport applications in Boston and Minneapolis healthcare clusters are standardizing on high-speed encrypted variants.
Germany
Industrial automation clusters require ruggedized high-capacity keys for offline firmware updates in air-gapped production environments. GDPR enforcement and emerging CSRD supply-chain disclosure rules add compliance layers for hardware-encrypted fleet deployments. Manufacturing hubs in Stuttgart and Munich are consolidating procurement around programmable secure elements for customizable key escrow policies.
China
Domestic flash memory fabricators leverage captive NAND production to supply assembly partners serving both local consumption and export markets. MIIT standards and GB certification requirements govern connector interoperability and electromagnetic compatibility testing. Shenzhen and Dongguan electronics manufacturing clusters concentrate controller firmware development and security silicon integration.
Japan
Enterprise IT departments prioritize hardware-encrypted keys for cross-border personnel data transfers under tightening data sovereignty interpretations. METI industrial policy and JIS standards influence procurement specifications for government and critical infrastructure sectors. Tokyo and Osaka metropolitan areas anchor demand for biometric-authentication convergence in financial services applications.
South Korea
Electronics OEMs and semiconductor fabricators drive demand for high-speed USB-C keys supporting USB4 protocols and power delivery specifications. MFDS guidelines and national cybersecurity frameworks shape encryption requirements for sensitive data handling. Seoul Capital Area technology corridors concentrate procurement of premium-tier storage devices for corporate and government fleet refreshes.
USB Key Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the USB key sector. Captive NAND production and controller firmware expertise separate the upper tier from assembly-dependent competitors. Strategic archetypes include vertically integrated memory fabricators, security-focused controller specialists, and channel-dominant retail brands. Competitive moves concentrate on certification acceleration and biometric authentication integration.
Among integrated memory fabricators, Samsung Electronics and Micron Technology exemplify the captive-supply archetype through in-house NAND production. Kingston Technology Corporation anchors the security-specialist tier with vertical control over controller firmware. PNY Technologies occupies a position within the channel-dominant segment, leveraging North American retail and education vertical relationships.
| Leading Market Players |
|---|
| Transcend Information, Inc |
| Netac |
| SanDisk LLC |
| Oyen Digital |
| Fanxiang |
| Kingston Technology Corporation |
| PNY Technologies, Inc. |
| Micron Technology |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
QLC NAND substitution for TLC architectures in 32GB and 64GB tiers is simultaneously shifting procurement geography toward Chinese wafer fabricators and compressing per-gigabyte pricing economics across mid-capacity segments. This input transition rewards captive producers while squeezing margin recovery for assembly-only brands dependent on spot-market flash sourcing.
Pricing Analysis
Remote management service contracts and firmware update subscriptions drive lifetime value for hardware-encrypted fleet deployments. Three-tier pricing structure across premium, standard, and economy levels separates AES 256-bit certified units with biometric authentication from basic-encrypted variants and unencrypted consumer keys. Pricing pressure stems from NAND flash oversupply in QLC configurations and cloud storage substitution eroding mid-capacity transfer key demand. Education sector procurement in North America exhibits acute price sensitivity, while German industrial automation clusters and US defense contractors absorb premium positioning without demand elasticity.
Supply Chain Analysis
South Korea and China anchor captive NAND production, with Samsung Electronics and domestic Chinese fabricators supplying both proprietary portfolios and external assembly partners. Controller firmware development rests on Taiwanese semiconductor design houses and Shenzhen engineering clusters. Single-source vulnerability concentrates in advanced security controller silicon, where NIST SP 800-111 certification requirements limit qualified suppliers. Distribution runs through direct enterprise procurement portals disintermediating traditional value-added resellers, particularly in North American healthcare systems undergoing HIPAA security rule refreshes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USB Key Market is entering a cyclical recovery phase as port standardization forces enterprise hardware refresh cycles and encryption mandates elevate replacement frequency. NAND flash oversupply conditions and USB-C connector transition create a favorable procurement environment for buyers through the analysis window.
For Market Incumbents: Shield market position by accelerating NIST SP 800-111 and GDPR compliance certification to capture government and healthcare procurement locked out from uncertified competitors. Deepen backward integration into controller firmware development to offset margin compression from captive NAND producers. Secure channel control through integrated device management platforms that disintermediate value-added resellers in North American healthcare verticals. For New Entrants and Emerging Players: Remote wipe and geofencing capability gaps in mid-tier encrypted keys present white-space opportunities where incumbents under-serve compliance-conscious SMEs. Target European financial services firms in Frankfurt and London requiring CSRD-aligned supply-chain disclosure for hardware-encrypted fleet deployments. Pursue biometric-authentication convergence as a premium positioning wedge against established security specialists. For Investors and Strategic Acquirers: Capital is best deployed toward controller firmware specialists with NIST certification pipelines and programmable secure element architectures. Long-term viability hinges on regulatory divergence between Washington and Brussels creating sustained demand for dual-certified encryption platforms. Watch for FCC certification timeline bottlenecks as an inflection signal indicating supply constraints or consolidation pressure among assembly-dependent brands.| Strategic Initiative | Industry Significance |
|---|---|
| AES 256-bit Certification Acceleration | NIST SP 800-111 compliance unlocks federal procurement and healthcare vertical expansion. |
| Biometric Authentication Integration | Fingerprint sensor convergence captures premium positioning in defense and financial applications. |
| Remote Management Platform Development | Cellular and Wi-Fi module embedding satisfies GDPR geofencing requirements for cross-border transfers. |
| Controller Firmware Backward Integration | In-house security silicon development reduces dependency on qualified supplier concentration. |
| USB-C Connector Transition | USB4 protocol support aligns with laptop OEM port elimination in German and US enterprise fleets. |
Research Methodology
Operator-level perspectives from enterprise IT procurement officers, industrial automation engineers, healthcare biomedical technology managers, and encryption product firmware developers anchored the qualitative base. Primary interview insights combined with secondary validation from FCC equipment authorization databases, NIST SP 800-111 guidance documents, ETSI cybersecurity standards, and customs trade flow records. Bottom-up shipment modeling and top-down demand estimation triangulated across connector type, encryption tier, and regional regulatory cluster dimensions.
Sensitivity analysis tested forecast robustness against NAND flash price volatility, USB-C adoption curve acceleration, and encryption mandate enforcement intensity across the projection horizon. Segmentation modeling incorporated product type, storage capacity tier, application use case, and encryption certification level as core dimensions. CAGR derivation rested on replacement cycle analysis, enterprise fleet refresh patterns, and air-gapped environment persistence in industrial and defense verticals. Controller firmware talent scarcity and FCC certification timeline variability served as key uncertainty inputs.
Material uncertainties — NAND flash supply disruption, regulatory divergence between NIST and GDPR technical safeguard interpretations, and cloud storage substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding port standardization timelines and encryption mandate enforcement consistency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SAS Hard Disk Drives Market
Data Storage
Global Portable Data Storage Market
Data Storage
Solid State Array Market
Data Storage
Europe Flash Memory Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
NAND Flash Memory Market
Data Storage
HDD Head Assembly Market
Data Storage
Transparent Cache Market
Data Storage
Americas Flash Memory Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
Zoned Flash Market