
 Europe Flash Memory Market | 2026-2036
Europe Flash Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flash Memory Market Insights
Specialized semiconductor engineering talent is collapsing across European fabrication zones, tightening output timelines for advanced node production. Samsung Electronics leverages its vertical integration to sustain wafer supply continuity for European automotive clients. Micron Technology anchors its European presence through dedicated DDR and NAND assembly operations in Italy. SK Hynix competes by positioning high-bandwidth memory solutions toward continental data center operators.
Europe flash memory denotes non-volatile solid-state storage using floating-gate or charge-trap transistors organized in NAND or NOR architectures, typically fabricated at process nodes between 15nm and 176-layer 3D NAND stacks, retaining data without power for applications requiring high-speed read access and mechanical durability. Its primary commercial purpose spans enterprise storage arrays, mobile computing platforms, automotive control modules, and industrial edge devices where magnetic or optical media fail on shock tolerance or latency metrics. Embedded Flash segments lead in automotive ECU and industrial controller deployments where temperature cycling resilience commands premium positioning. 3D NAND technology is displacing planar architectures across data center SSD procurement as layer stacking improves bit-cost trajectories. Consumer Electronics end users still occupy substantial volume pools though margin compression intensifies on commoditized USB Flash Drives.
EU Chips Act funding frameworks and REACH chemical substance restrictions are reshaping material sourcing and cleanroom chemical protocols for European fabs. CE marking under the EU Radio Equipment Directive governs flash-integrated wireless IoT module market access. Germany's KBA type-approval requirements for automotive storage components add compliance layers for Tier-1 suppliers. Stakeholders must monitor how ECHA per- and polyfluoroalkyl substance restrictions alter etching chemistry availability before committing to capacity expansion timelines.
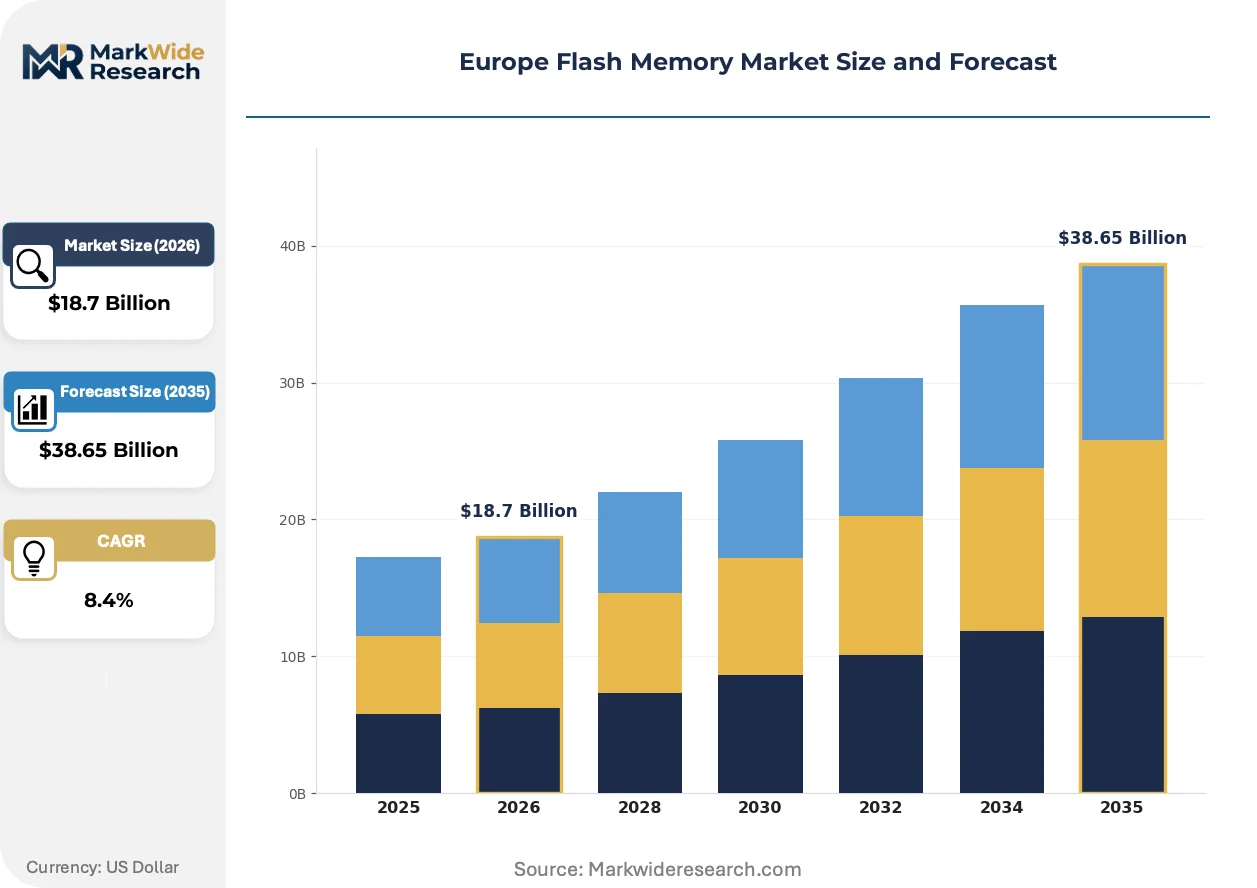
Market Dynamics
Automotive electrification is compressing qualification timelines for industrial-grade flash components as Tier-1 suppliers race to secure long-term wafer allocation from European fabrication facilities.
Growth Catalysts
- EU Chips Act capital deployment:Member state subsidies for domestic cleanroom construction are pulling 300mm wafer capacity toward Dresden and Leuven corridors.
- Automotive ECU consolidation:Domain controller architectures in electric vehicles are replacing discrete memory chips with higher-density embedded flash modules.
- Data center SSD refresh cycles:Hyperscale operators in Frankfurt and Amsterdam are accelerating replacement of planar NAND with 176-layer 3D NAND stacks.
Market Restraints
- Specialized etching chemical scarcity:ECHA per- and polyfluoroalkyl substance restrictions are constraining availability of fluorinated chemistries essential for sub-20nm patterning.
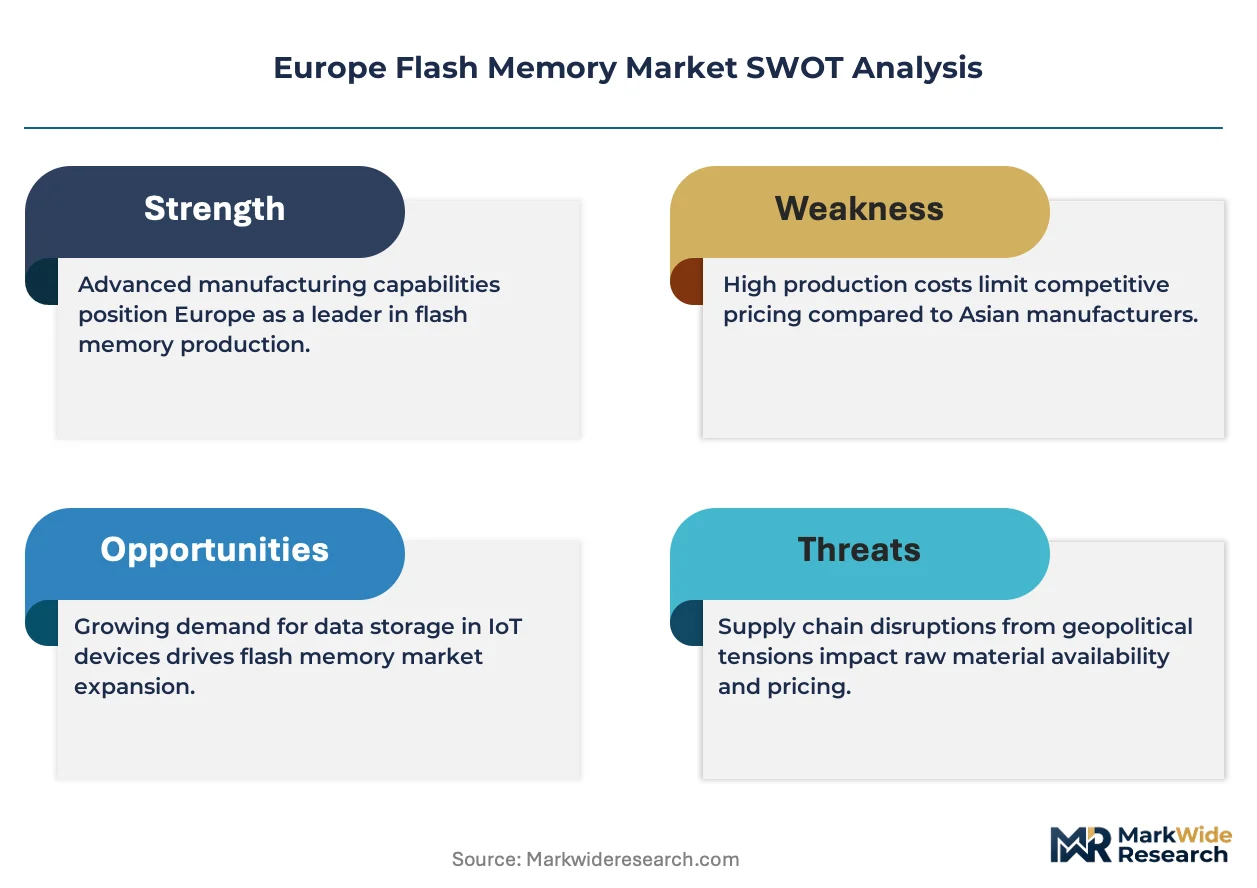
- Wafer fabrication concentration:Advanced node output remains concentrated in Asian foundry complexes, exposing European fabless designers to geopolitical logistics risk.
- Silicon substrate cost volatility:Polysilicon ingot pricing fluctuations are transmitting directly to wafer substrate costs for memory manufacturers.
Strategic Opportunities
- Eastern European packaging expansion:Romania and Bulgaria are attracting back-end assembly investment due to lower labor costs and EU structural fund access.
- Industrial edge AI inference:Factory automation controllers are integrating local flash storage for machine learning model caching without cloud dependency.
- REACH-compliant material substitution:Cleanroom chemical suppliers are commercializing bio-based photoresist alternatives that satisfy EU substance restrictions.
Industry Challenges
- Process engineering talent pipeline collapse:European technical universities are producing insufficient lithography and thin-film deposition specialists to staff planned capacity expansions.
- KBA automotive certification timelines:Germany's type-approval protocols for storage components in safety-critical systems extend qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flash Memory Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSD, USB Flash Drives, Memory Cards, Embedded Flash Technology: MLC, TLC, SLC, 3D NAND End User: Consumer Electronics, Automotive, Industrial, Data Centers Application: Mobile Devices, Computers, Cameras, IoT Devices |
| Companies Covered | Samsung Electronics, Micron Technology, SK Hynix, KIOXIA Europe GmbH, Infineon Technologies AG, Western Digital Corporation, STMicroelectronics, NXP Semiconductors, Texas Instruments, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flash Memory Market Trends and Innovations
Process node migration and regulatory chemistry mandates are forcing simultaneous retooling of fabrication equipment and cleanroom supply chains across European memory facilities.
Charge-trap flash technology is fragmenting the planar NAND replacement landscape. Automotive module suppliers are adopting charge-trap cells for their superior temperature cycling endurance. This architecture is fragmenting procurement patterns as buyers split volumes between floating-gate legacy suppliers and charge-trap specialists.
REACH chemical substance restrictions are mandating substitution of perfluorinated compounds in etching and cleaning processes. Memory fabs in the Netherlands and Germany are piloting aqueous-based cleaning chemistries to maintain process yields. CE marking under the Radio Equipment Directive is tightening for flash-integrated wireless modules as ECHA expands restricted substance lists.
Long-term supply agreements are displacing spot-market purchasing for automotive and data center buyers. Tier-1 automotive suppliers are locking five-year wafer supply contracts directly with foundry operators. This contracting shift is most pronounced in Germany where BMW and Volkswagen Group affiliates are securing dedicated capacity allocations.
Europe Flash Memory Market Segmentation
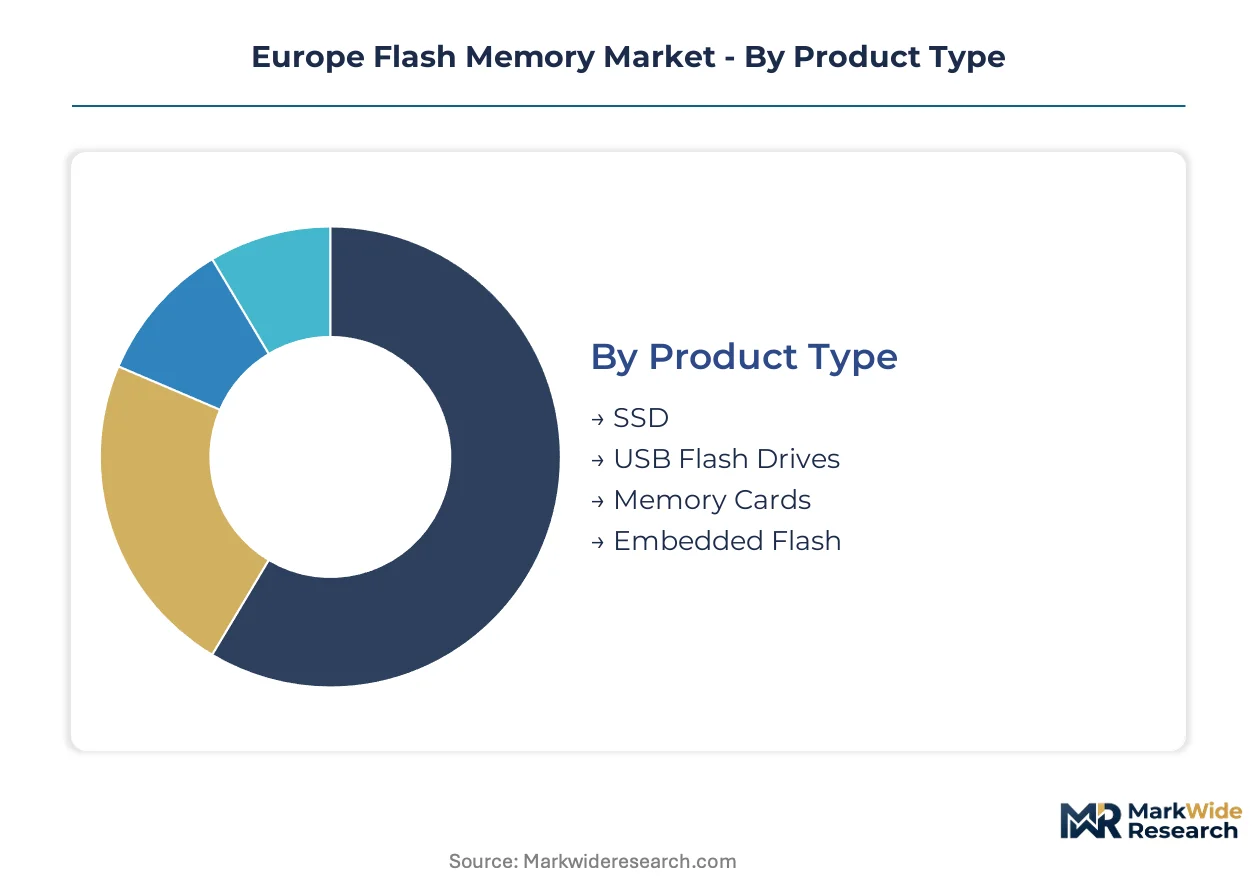
Flash memory segmentation in Europe reflects divergent compliance burdens across automotive safety systems and consumer portability mandates. Product architecture choices directly determine REACH chemical exposure, KBA certification pathways, and ECHA substance restriction applicability.
Product Type:
REACH substance restrictions and KBA automotive certification timelines differentiate procurement economics across form factors.
- SSD:Solid-state drives utilizing 176-layer 3D NAND stacks dominate data center procurement in Frankfurt and Amsterdam clusters. Hyperscale operators in these jurisdictions are accelerating planar-to-3D NAND refresh cycles to optimize bit-cost trajectories under EU energy efficiency directives.
- Embedded Flash:Non-volatile memory modules integrated directly onto automotive ECU substrates command premium positioning through Germany's KBA type-approval requirements. Domain controller architectures in electric vehicle platforms are consolidating discrete chips into higher-density embedded configurations, compressing Tier-1 supplier qualification timelines.
- Memory Cards:Removable storage formats for imaging and portable electronics face margin compression from commoditized supply.
- USB Flash Drives:Portable plug-and-play storage encounters pricing pressure from Asian assembly concentration and minimal regulatory differentiation.
Established volume favors SSD; emerging adoption favors Embedded Flash.
Technology:
Cell architecture selection determines endurance specifications, temperature resilience, and etching chemistry requirements under ECHA restrictions.
- 3D NAND:Vertical layer stacking technology achieves superior bit-density through charge-trap cell architectures rather than traditional floating-gate designs. Netherlands and Germany-based fabrication facilities are piloting aqueous cleaning chemistries to maintain yields as layer counts exceed 176 stacks.
- SLC:Single-level cell configurations store one bit per cell, delivering maximum write endurance for industrial controllers and automotive safety systems. Factory automation deployments across the Ruhr Valley and Lombardy are integrating SLC-based local storage for machine learning model caching without cloud dependency.
- TLC:Triple-level cell architectures balance density against endurance for mainstream consumer and enterprise applications.
- MLC:Multi-level cell technology occupies intermediate positioning between SLC reliability and TLC density.
Production scale concentrates in 3D NAND; steepest expansion trajectory belongs to SLC for edge AI inference.
End User:
Customer verticals impose distinct qualification protocols, from CE marking under the Radio Equipment Directive to KBA safety-critical system approvals.
- Automotive:Electric vehicle domain controllers and advanced driver-assistance systems demand industrial-grade temperature cycling resilience. BMW and Volkswagen Group affiliates are locking five-year wafer supply contracts directly with European foundry operators to secure dedicated capacity allocations.
- Data Centers:Hyperscale storage infrastructure in Frankfurt, Amsterdam, and Dublin corridors is displacing planar NAND with 176-layer 3D NAND stacks. EU Chips Act subsidies for domestic cleanroom construction are pulling 300mm wafer capacity toward Dresden to serve these installations.
- Industrial:Edge automation controllers require local flash storage for deterministic latency in factory environments.
- Consumer Electronics:Mobile and portable device integration faces margin erosion from standardized specifications.
Procurement commitment depth favors Automotive; infrastructure refresh velocity favors Data Centers.
Application:
Device integration patterns determine physical form factor, interface protocol, and environmental sealing requirements.
- Mobile Devices:Smartphones and tablets utilize embedded UFS and eMMC configurations with stringent space and power constraints. CE marking under the EU Radio Equipment Directive governs flash-integrated wireless module market access for these products.
- Computers:Client and enterprise computing platforms deploy NVMe and SATA SSD form factors with standardized interoperability requirements.
- IoT Devices:Sensor networks and connected infrastructure integrate low-density flash for firmware and data logging.
- Cameras:Professional and consumer imaging equipment relies on removable card formats with mechanical durability specifications.
Integration complexity favors Mobile Devices; standardization pressure favors Computers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs consume flash memory primarily for embedded ECU applications, while Dutch and Irish data center operators favor high-density SSD procurement, creating divergent demand profiles across the continent.
Germany
BMW and Volkswagen Group affiliates are locking five-year wafer supply contracts directly with European foundry operators to secure dedicated capacity allocations for electric vehicle domain controllers. Germany's KBA type-approval requirements for automotive storage components add compliance layers that extend qualification cycles by 18-24 months. The Dresden corridor is pulling 300mm wafer capacity through EU Chips Act subsidies to serve these installations.
Netherlands
Hyperscale operators in Amsterdam are accelerating replacement of planar NAND with 176-layer 3D NAND stacks to optimize bit-cost trajectories under EU energy efficiency directives. ECHA per- and polyfluoroalkyl substance restrictions are constraining availability of fluorinated chemistries essential for sub-20nm patterning at Dutch fabrication facilities. ASML's lithography equipment concentration in Veldhoven creates specialized maintenance talent pools for advanced node production.
France
CE marking under the EU Radio Equipment Directive governs flash-integrated wireless IoT module market access for industrial automation deployments across the Auvergne-Rhône-Alpes manufacturing belt. ANSM and CNIL oversight adds data localization requirements for connected device storage components. The Grenoble semiconductor cluster is piloting aqueous-based cleaning chemistries to maintain process yields under REACH compliance mandates.
Italy
Micron Technology anchors dedicated DDR and NAND assembly operations in the country to serve Mediterranean automotive and industrial markets. Lombardy factory automation deployments are integrating SLC-based local storage for machine learning model caching without cloud dependency. CE marking protocols and EU Green Deal carbon border adjustments are reshaping material sourcing for back-end packaging facilities.
Ireland
Data center infrastructure in Dublin corridors is displacing planar NAND with 176-layer 3D NAND stacks as hyperscale operators expand European cloud regions. GDPR data residency requirements are mandating local storage for sensitive workloads, tightening procurement specifications for encrypted flash modules. Intel's historical presence in Leixlip established specialized semiconductor engineering talent pipelines now attracting memory packaging investment.
Europe Flash Memory Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Korean and American conglomerates commanding wafer supply continuity through captive fabrication while European fabless designers concentrate on automotive-qualified embedded modules. The structure fragments across three strategic archetypes: vertically integrated memory fabricators with global wafer capacity, automotive-focused semiconductor specialists with KBA certification expertise, and industrial-edge component suppliers with temperature cycling resilience. Competitive moves center on long-term supply agreement lock-ins with Tier-1 automotive OEMs and strategic positioning for EU Chips Act subsidy access in Dresden and Leuven corridors.
Among vertically integrated memory fabricators, Samsung Electronics and SK Hynix represent the scale-driven archetype with upstream control over wafer supply chains, while Micron Technology occupies a position exemplifying dedicated regional assembly commitment through its Italian operations. These three anchors illustrate how geographic production footprint and supply chain configuration determine competitive access to European automotive and data center demand pools.
| Leading Market Players |
|---|
| Samsung Electronics |
| Micron Technology |
| SK Hynix |
| KIOXIA Europe GmbH |
| Infineon Technologies AG |
| Western Digital Corporation |
| STMicroelectronics |
| NXP Semiconductors |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
Ninety-day wafer inventory buffers at European automotive Tier-1 suppliers signal supply-chain rigidity that amplifies pricing power for captive foundry operators while squeezing margin flexibility at fabless module vendors serving spot-market buyers.
Pricing Analysis
Long-term offtake contracts dominate procurement between German automotive OEMs and European foundry operators, with BMW and Volkswagen Group affiliates locking five-year wafer supply agreements that insulate against spot-market volatility. Price differentiation separates KBA-certified embedded flash modules from commodity SSD tiers, with certification-grade automotive components commanding substantial premiums over data center equivalents. Cost compression in consumer-grade USB flash drives is intensifying because Asian assembly concentration erodes regional margin buffers. Data center hyperscalers exhibit lowest price sensitivity due to total-cost-of-ownership optimization, while portable electronics integrators face acute margin pressure from commoditized supply.
Supply Chain Analysis
Inventory positioning at Netherlands-based fabrication facilities reveals concentrated dependence on ASML lithography equipment with limited alternative sourcing pathways for extreme ultraviolet patterning systems. Advanced node wafer supply concentrates in South Korea, Taiwan, and the USA, with European automotive module vendors drawing from Taiwanese foundry output for leading-edge process nodes. Raw material dependencies center on high-purity silicon substrates, fluorinated etching chemistries, and noble gas feedstocks for ion implantation. Single-source vulnerability in extreme ultraviolet lithography equipment creates structural exposure for European memory expansion timelines. Distribution runs through direct foundry-to-OEM contracts for automotive volumes, with modular SSD procurement flowing through distributor channels serving data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from charge-trap flash architectures displacing floating-gate legacy positions in automotive temperature-cycling applications, requiring defensive repositioning around certification depth and supply continuity.
For Market Incumbents: Shield embedded flash market share by accelerating KBA certification pipelines for charge-trap cell architectures before domain controller consolidation locks in supplier selections. Deepen backward integration into 300mm wafer capacity at Dresden and Leuven corridors to reduce exposure to Asian foundry concentration. Prioritize REACH-compliant material substitution investments to preempt ECHA chemistry restrictions that could disqualify legacy etching processes.
For New Entrants and Emerging Players: Automotive firmware customization services represent an under-served layer where incumbent memory fabricants lack dedicated software engineering benches. Target Romania and Bulgaria packaging corridors for back-end assembly investment, leveraging EU structural fund access and lower labor cost bases against established Asian assembly concentrations. Pursue direct qualification relationships with mid-tier industrial automation OEMs in Lombardy and the Ruhr Valley as an alternative to contested Tier-1 automotive procurement channels.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU Chips Act subsidy allocation will concentrate viable capacity expansion among three to four integrated operators with demonstrated automotive certification expertise. Acquisition targets should emphasize fabless designers with existing KBA approval pipelines and embedded flash IP rather than commodity SSD vendors facing margin erosion. Monitor ECHA per- and polyfluoroalkyl substance restriction implementation timelines as the critical signal for which fabrication technologies retain process yield viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Wafer Supply Agreement | BMW and Volkswagen Group affiliates secure dedicated capacity allocations through five-year foundry contracts. |
| Charge-trap Cell Architecture Transition | Automotive module suppliers adopt temperature-cycling endurance superior to floating-gate legacy designs. |
| Eastern European Packaging Expansion | Romania and Bulgaria attract back-end assembly investment via EU structural fund access. |
| REACH-compliant Chemistry Substitution | Netherlands and Germany-based fabs pilot aqueous cleaning processes under ECHA restriction mandates. |
| Domain Controller Consolidation | Electric vehicle architectures displace discrete memory chips with higher-density embedded configurations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with semiconductor fabrication executives, automotive Tier-1 procurement directors, and data center infrastructure planners; and secondary validation through SEC 10-K filings, EU Chips Act funding disclosure databases, and ECHA regulatory consultation records. Bottom-up triangulation across wafer capacity announcements and top-down reconciliation against hyperscaler capex disclosures anchored volume estimates. Primary fieldwork concentrated on Dresden, Eindhoven, and Grenoble semiconductor clusters with supplementary input from Milan and Dublin packaging operations.
Across the analysis window, the forecasting framework modeled demand trajectories by product architecture, end-use vertical, and country-level regulatory exposure. Segmentation dimensions included cell technology tier, automotive certification status, and data center versus edge deployment patterns. CAGRs were derived from installed base replacement cycles for planar-to-3D NAND transitions and electric vehicle production ramp assumptions. Industry-specific inputs encompassed KBA type-approval timeline distributions and REACH chemical substitution cost curves.
Underlying assumptions cover EU Chips Act disbursement schedules and ECHA restriction implementation phasing, with deviation risk concentrated in fluorinated chemistry availability and lithography equipment delivery timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
HDD Head Assembly Market
Data Storage
Enterprise Hard Drive Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Ceph Storage Solutions Market
Data Storage
North America SSD Caching Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Distributed Storage System Market
Data Storage
APAC SSD Caching Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
OTG Pen Drive Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Global Portable Data Storage Market
Data Storage
Non-Volatile Memory Express (Nvme) Market