
 Solid State Drive (SSD) Market | 2026-2036
Solid State Drive (SSD) Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Drive (SSD) Market Intelligence
The capital-intensity divergence between captive NAND foundries and fabless controller houses is unwinding competitive stability in the SSD sector. Samsung Electronics leverages its vertical integration through in-house 3D NAND fabrication and controller design to sustain margin resilience across enterprise contracts. SK hynix / Solidigm anchors its position through advanced lithography investments that differentiate its QLC products in density-sensitive data center slots. Micron Technology competes by controlling DRAM and NAND supply concurrently, which extends its bargaining power with hyperscale buyers.
A solid state drive is a non-volatile storage device that uses integrated circuit assemblies to persistently store data, with NVMe interfaces achieving sequential read speeds exceeding 7,000 MB per second over PCIe Gen4 lanes. It replaces mechanical hard disk drives in applications requiring low latency, high throughput, and resistance to physical shock. NVMe SSD products now command the premium tier in enterprise procurement as cloud providers prioritize IOPS density per rack unit. QLC NAND technology is expanding fastest in cold storage and archival segments where cost-per-gigabyte margins outweigh endurance requirements. SATA SSD maintains residual strength in personal computing refreshes and legacy server upgrades where motherboard compatibility limits interface migration.
FCC equipment authorization rules shape radio-frequency emissions compliance for SSDs deployed in edge and mobile computing devices, while the EPA's electronics sustainability directives influence material recovery and restricted substance thresholds. China's GB standards and MIIT certification requirements govern encryption protocols and data security features for storage products sold into government and financial verticals. REACH and RoHS frameworks in Europe constrain halogenated flame retardants and heavy metals in PCB assemblies, pushing manufacturers toward halogen-free substrate materials. Stakeholders must monitor how emerging AI server rack power budgets and thermal densities will redefine form factor priorities and interface roadmaps.
Market Dynamics
AI training clusters are forcing hyperscale buyers to renegotiate storage procurement around petabyte-scale annual commitments, compressing supplier margins while locking in multi-year foundry offtake agreements that reshape competitive positioning among vertically integrated NAND producers.
Growth Catalysts
- MIIT Data Localization Mandates:China's tightened onshore storage rules require government and financial verticals to deploy domestic-certified SSD infrastructure, creating captive demand for locally manufactured QLC and TLC products.
- Hyperscale Cloud Expansion:Northern Virginia and Oregon campuses are driving petabyte-scale NVMe procurement as training workloads demand IOPS density per rack unit that only PCIe Gen4 enterprise SSDs deliver.
- QLC Density Gains:Advanced 3D NAND lithography enables cost-per-gigabyte advantages in cold storage segments where endurance requirements relax, opening archival and backup displacement opportunities against mechanical drives.
Market Restraints
- Captive NAND Concentration:Foundry capacity concentrates among Korean and US integrated producers, exposing buyers to supply disruption risk during lithography node transitions or geopolitical trade restrictions.
- Controller Silicon Costs:Fabless controller houses face wafer allocation competition from AI accelerators and mobile SoCs, inflating bill-of-materials for enterprise NVMe products.
- SATA Interface Persistence:Legacy server refresh cycles and personal computing motherboard compatibility constraints slow NVMe migration, fragmenting R&D across multiple interface roadmaps.
Strategic Opportunities
- Edge AI Inference Nodes:Low-power NVMe form factors for factory automation and autonomous vehicle sensor fusion remain underpenetrated, requiring thermal designs below 7W active power.
- IRA Clean Energy Credits:US domestic manufacturing incentives support captive NAND foundry expansion, reducing tariff exposure for hyperscale procurement contracts.
- Computational Storage Convergence:Processing-in-memory architectures integrated with SSD controllers enable near-data analytics, creating premium pricing for database acceleration appliances.
Industry Challenges
- Firmware Security Certification:GB standards and FIPS 140-3 validation timelines extend product qualification cycles by 8-14 months, delaying revenue recognition for new controller architectures.
- Advanced Packaging Talent Scarcity:3D NAND stacking and hybrid bonding expertise concentrates among Korean and Taiwanese engineering pools, constraining foundry expansion speed in other geographies.
- Legacy File System Integration:ZFS and ext4 optimization for QLC write amplification patterns requires software stack re-engineering that many enterprise IT organizations defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Drive (SSD) Market |
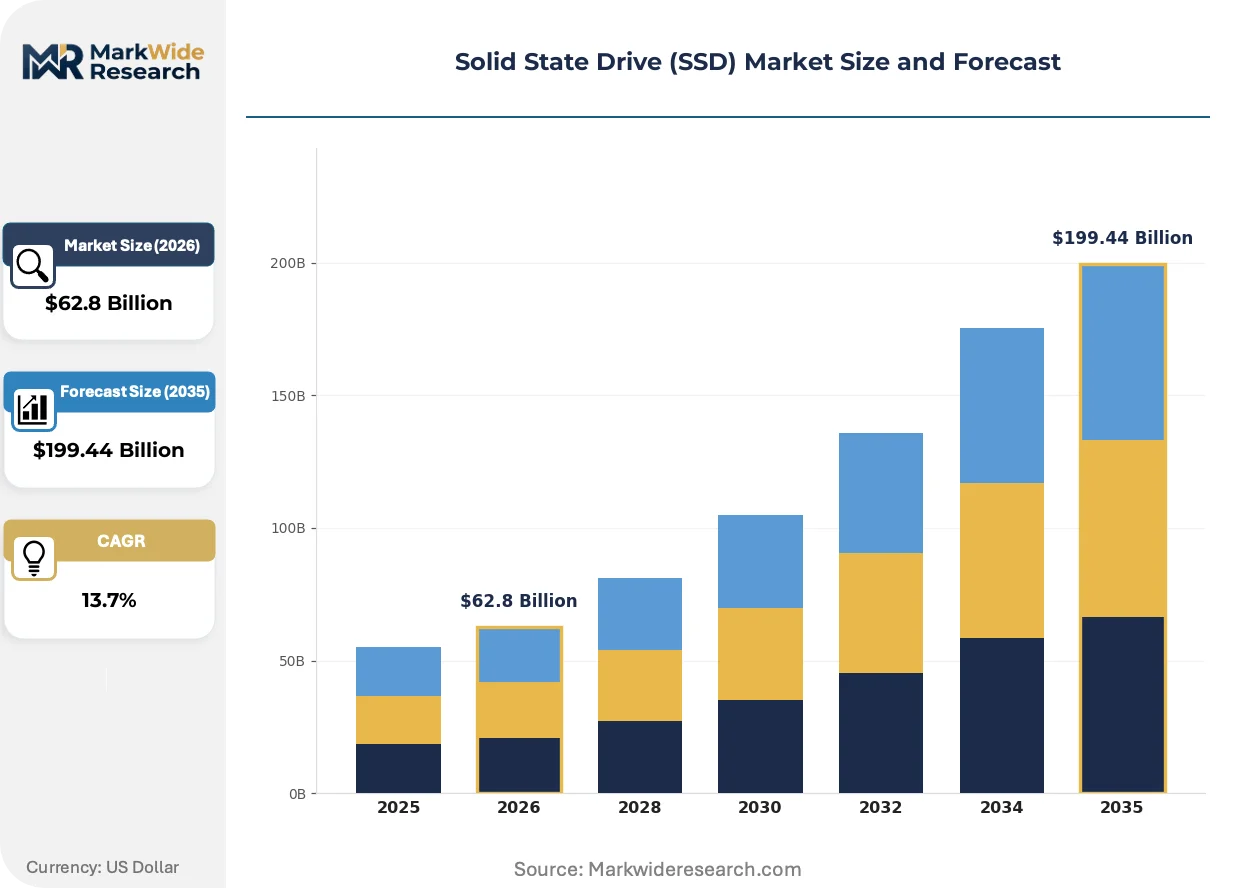
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $199.44 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SATA SSD, NVMe SSD, PCIe SSD, mSATA SSD, U.2 SSD Technology: 3D NAND, SLC NAND, MLC NAND, TLC NAND, QLC NAND Application: Personal Computing, Enterprise Servers, Data Centers, Media Production, Cloud Storage End User: Consumer Electronics, IT Service Providers, Content Creators, Colocation Facilities, High-Performance Computing |
| Companies Covered | Micron Technology, Kingston Technology, Samsung Electronics, Phison Electronics, ADATA, SK hynix / Solidigm, Kioxia Holdings, Seagate Technology, Western Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Drive (SSD) Market Strategic Shifts & Innovations
Storage architectures are splitting between performance-optimized and density-optimized paths as AI workloads diverge from traditional enterprise applications, forcing suppliers to maintain dual technology roadmaps without full volume scale in either track.
PCIe Gen5 NVMe controllers is bifurcating the enterprise installed base. Hyperscale cloud operators in the United States are adopting 14 GB/s sequential read devices for training checkpoint storage, while enterprise data centers extend Gen4 refresh cycles. This divergence compresses pricing power for mid-tier products that serve neither extreme.
REACH and RoHS frameworks in Europe are tightening restricted substance thresholds for halogenated flame retardants in SSD PCB assemblies. Manufacturers are migrating to halogen-free substrate materials and redesigning thermal interface materials. Enterprise and government verticals face compliance verification burdens that favor suppliers with pre-certified component libraries.
Annual petabyte-scale procurement commitments are displacing quarterly spot purchasing among hyperscale buyers. Cloud providers in Northern Virginia and Oregon now negotiate multi-year foundry offtake agreements directly with captive NAND producers. This concentration compresses distributor margins while locking fabless controller houses into exclusive silicon supply relationships.
Solid State Drive (SSD) Market Segmentation
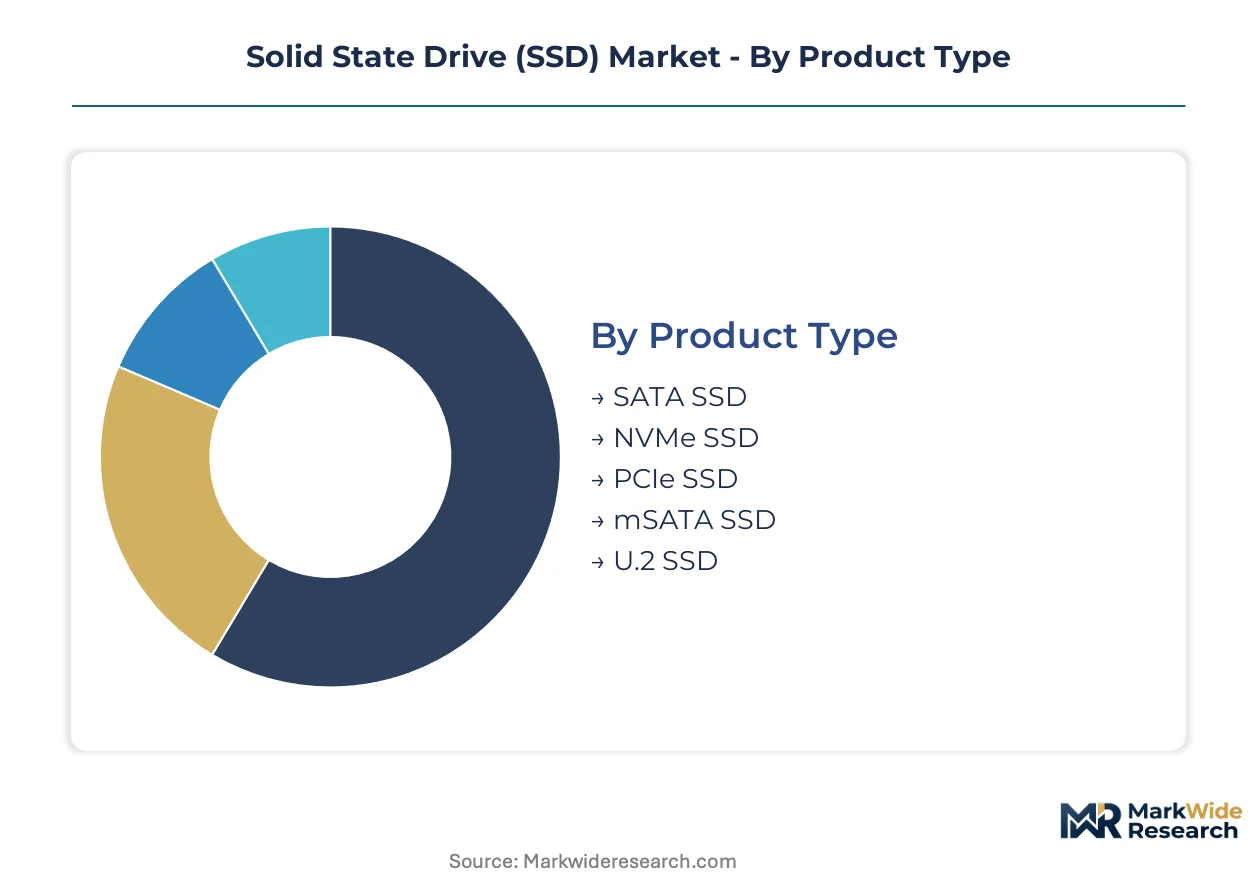
SSD procurement patterns diverge sharply across interface standards and NAND cell architectures, with hyperscale buyers prioritizing throughput density while legacy infrastructure sustains residual demand for backward-compatible form factors. Understanding these segment boundaries clarifies where foundry capacity allocation and controller R&D investments concentrate.
Product Type:
Domestic demand in China concentrates on SATA and mSATA variants for government verticals under MIIT localization rules, while NVMe and U.2 products flow primarily toward export-led hyperscale procurement in the United States and Europe.
- NVMe SSD:PCIe Gen4 and Gen5 interfaces achieve sequential read speeds exceeding 7,000 MB per second. Northern Virginia and Oregon cloud campuses drive petabyte-scale procurement as training workloads demand IOPS density per rack unit that only these devices deliver.
- SATA SSD:Legacy 6 Gb/s interface maintains compatibility with personal computing motherboards and aging server backplanes. Residual strength persists in refresh cycles where motherboard constraints limit interface migration, fragmenting supplier R&D roadmaps.
- PCIe SSD:Direct-attached storage without NVMe protocol overhead serves specialized HPC clusters requiring deterministic latency.
- mSATA SSD:Miniaturized form factor addresses industrial embedded systems and legacy laptop upgrade paths with space-constrained mounting.
- U.2 SSD:Hot-swappable 2.5-inch enterprise form factor bridges NVMe performance with SAS infrastructure backward compatibility in colocation facilities.
NVMe SSD holds the largest share; momentum sits with U.2 as hyperscale operators standardize on hot-swappable rack architectures.
Technology:
Cost tier stratification separates premium SLC deployments in military aerospace from density-optimized QLC procurement for cold archival, with TLC anchoring mainstream enterprise revenue.
- QLC NAND:Four-bit-per-cell architecture maximizes wafer yield for cost-per-gigabyte advantages. Cold storage and backup segments in data centers adopt these products where endurance requirements relax below one drive write per day.
- TLC NAND:Three-bit-per-cell technology balances density with sufficient program-erase cycles for mainstream enterprise workloads. IT service providers and colocation facilities specify these drives for mixed read-write virtualization environments.
- 3D NAND:Vertical stacking of memory cells enables terabit-scale die capacities without planar lithography shrinkage.
- SLC NAND:Single-bit-per-cell design delivers maximum endurance for military and aerospace applications with extreme temperature tolerance requirements.
- MLC NAND:Two-bit-per-cell legacy technology persists in industrial automation controllers requiring deterministic write latency.
TLC NAND holds the largest share; QLC NAND is climbing the fastest as hyperscale archival displaces mechanical drives.
Application:
Volume concentration tilts toward data centers and cloud storage, where annual petabyte commitments reshape supplier relationships, while media production remains fragmented across boutique post-production houses.
- Data Centers:Hyperscale facilities deploy NVMe over Fabrics architectures for disaggregated storage pools. AI training clusters force renegotiation of procurement around multi-year foundry offtake agreements that lock in supply security.
- Cloud Storage:Object storage backends and block storage services require QLC density for economically viable cold tier pricing. Providers in Northern Virginia negotiate directly with captive NAND producers, compressing distributor margins.
- Personal Computing:Gaming laptops and workstation refreshes sustain SATA and entry-level NVMe demand through retail channels.
- Enterprise Servers:Virtualization hosts and database servers specify mixed-use TLC drives with power-loss protection capacitors.
- Media Production:8K video editing workstations demand sustained write bandwidth for uncompressed RAW footage ingestion.
Data centers hold the largest share; cloud storage represents the steepest expansion trajectory as providers build dedicated archival tiers.
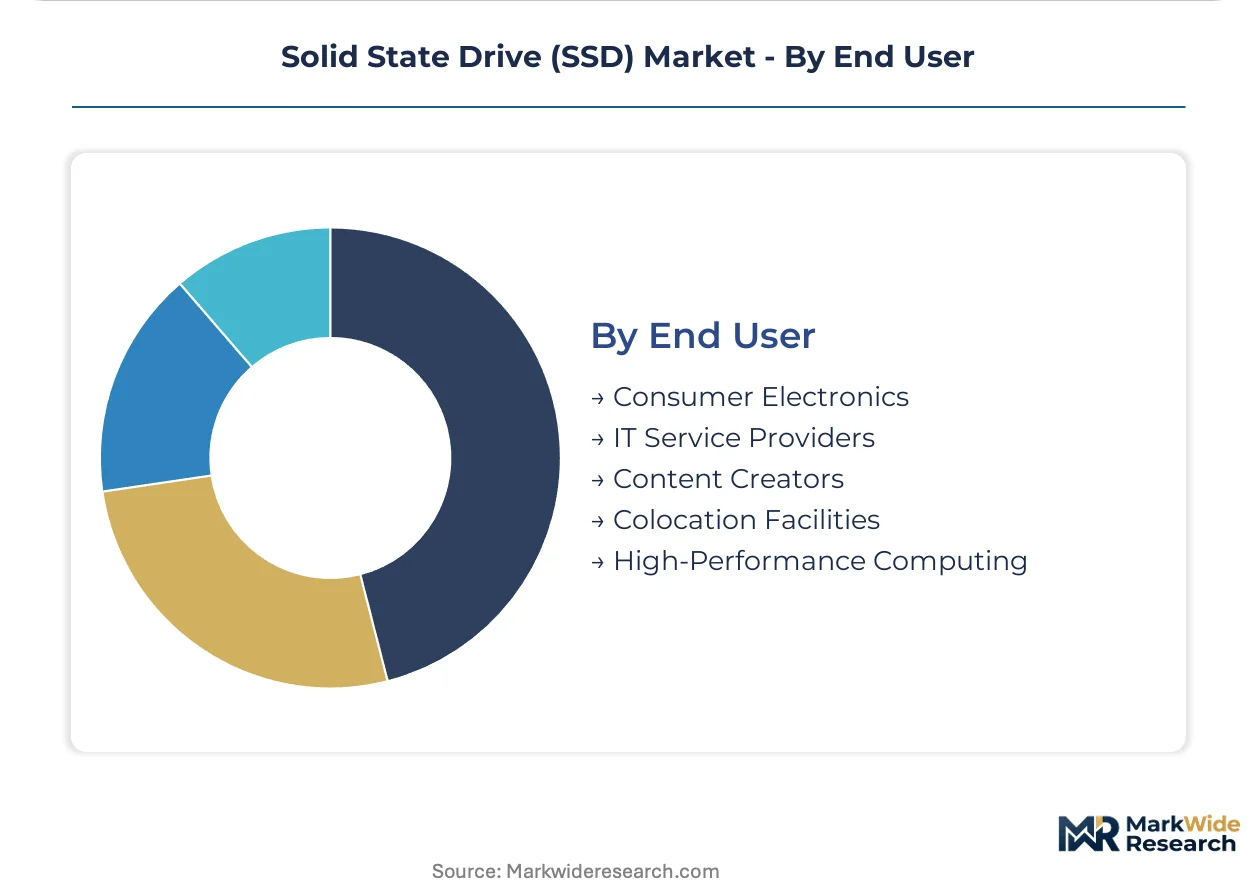
End User:
Customer type determines margin structure, with IT service providers and colocation facilities consolidating procurement power while content creators remain price-sensitive through retail channels.
- IT Service Providers:Managed infrastructure operators standardize on NVMe across multi-tenant environments to differentiate IOPS guarantees. These buyers leverage volume concentration to extract firmware customization and extended warranty terms.
- Colocation Facilities:Wholesale data center operators provision storage-as-a-service layers requiring hot-swappable U.2 form factors. Their procurement aggregates demand from enterprise tenants, creating scale sufficient for direct manufacturer negotiations.
- Consumer Electronics:OEM laptop and gaming console manufacturers specify cost-optimized DRAM-less NVMe controllers.
- Content Creators:Independent video editors and photographers purchase through retail channels with sensitivity to price-per-gigabyte metrics.
- High-Performance Computing:National laboratories and research institutes deploy parallel file systems built on PCIe Gen5 devices.
IT service providers hold the largest share; colocation facilities are gaining share fastest as enterprise IT outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in China by substantial margins, as hyperscale cloud operators in Northern Virginia negotiate petabyte-scale commitments directly with captive NAND producers while Chinese buyers face localization mandates that limit supplier choice.
United States
Hyperscale cloud campuses in Northern Virginia and Oregon drive petabyte-scale NVMe procurement for AI training workloads. The EPA's electronics sustainability directives influence material recovery thresholds for SSD assemblies sold into federal contracts. Greater Boston hosts HPC research institutes deploying parallel file systems on PCIe Gen5 devices.
China
MIIT data localization rules mandate onshore storage infrastructure for government and financial verticals, creating captive demand for domestic-certified QLC and TLC products. GB standards govern encryption protocols and data security features for storage products in sensitive applications. The Yangtze River Delta anchors domestic NAND fabrication capacity expansion.
South Korea
Advanced 3D NAND lithography investments differentiate QLC products in density-sensitive data center slots globally. The country's national technology regulator oversees semiconductor export control compliance for memory products. Seoul Capital Area engineering pools concentrate hybrid bonding expertise that constrains foundry expansion speed elsewhere.
Japan
METI industrial policy supports memory technology development through targeted R&D subsidies and supply chain security programs. JIS standards govern reliability specifications for enterprise SSD deployments in critical infrastructure. Kansai region manufacturing maintains legacy MLC NAND production for industrial automation controllers.
Germany
REACH and RoHS frameworks constrain halogenated flame retardants in SSD PCB assemblies, pushing manufacturers toward halogen-free substrate materials. The country's federal environmental agency enforces extended producer responsibility for electronics waste recovery. Bavaria hosts automotive OEMs specifying industrial-grade SSDs for autonomous vehicle sensor fusion systems.
Solid State Drive (SSD) Market Key Industry Players
Concentration sits with vertically integrated NAND producers who control foundry capacity and controller design simultaneously. Three Korean and US integrated manufacturers anchor supply security for hyperscale procurement. Strategic moves center on multi-year foundry offtake agreements and captive silicon allocation to cloud operators.
Within the integrated producer tier, Samsung Electronics, SK hynix / Solidigm, and Micron Technology exemplify archetypes that combine in-house 3D NAND fabrication with controller development. Samsung Electronics represents vertical integration through captive NAND and controller design. SK hynix / Solidigm occupies a position defined by advanced lithography specialization. Micron Technology anchors a model of concurrent DRAM and NAND supply control that extends bargaining power with hyperscale buyers. Fabless controller houses including Phison Electronics sit within a dependent tier facing wafer allocation competition from AI accelerators.
| Leading Market Players |
|---|
| Micron Technology |
| Kingston Technology |
| Samsung Electronics |
| Phison Electronics |
| ADATA |
| SK hynix / Solidigm |
| Kioxia Holdings |
| Seagate Technology |
| Western Digital |
| Others |
Cost & Logistics Intelligence
Multi-year foundry offtake agreements between hyperscale cloud operators and captive NAND producers lock in both wafer allocation security and price visibility across volatile lithography node transitions. These contracts compress spot-market liquidity while binding buyer and supplier into shared exposure on yield ramp economics and geopolitical tariff shifts.
Pricing Analysis
Configured-to-order pricing for firmware-customized enterprise NVMe drives commands substantial premiums over standard-catalog SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by endurance rating and FIPS 140-3 certification status. Cost compression in QLC cold storage tiers is intensifying because hyperscale buyers negotiate direct manufacturer contracts that bypass distribution markups. Content creators purchasing through retail channels exhibit highest price sensitivity, while colocation facilities with aggregated tenant demand show lowest sensitivity due to volume scale.
Supply Chain Analysis
Strategic stockpiling of NAND wafers and controller silicon dominates over just-in-time preferences as buyers hedge against lithography node transition disruptions. Foundry capacity concentrates in South Korea, the United States, and China, with advanced 3D NAND stacking expertise anchored in Korean and Taiwanese engineering pools. Supply chains draw from silicon wafers, rare earth elements for substrate materials, and specialized epoxy molding compounds. Single-source vulnerability around hybrid bonding equipment creates structural risk. Distribution runs through direct manufacturer relationships for hyperscale procurement and authorized distributors for mid-market enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SSD market sits in a cyclical recovery phase driven by AI training infrastructure buildouts that absorb excess NAND inventory and reset pricing floors. Memory demand cyclicality now amplifies through hyperscale capex synchronization rather than traditional PC refresh patterns.
For Market Incumbents: Shield margin structures by accelerating captive controller silicon allocation to cloud operators before fabless competitors secure wafer commitments. Deepen backward integration into advanced packaging capabilities to offset hybrid bonding talent scarcity. Lock in multi-year firmware development partnerships with IT service providers to raise switching costs against emerging controller houses.
For New Entrants and Emerging Players: Edge AI inference storage for factory automation and autonomous vehicle sensor fusion represents an under-served layer where thermal design constraints below 7W active power exclude incumbent enterprise-focused portfolios. Target computational storage convergence opportunities in database acceleration appliances where processing-in-memory architectures command premium positioning. Pursue direct OEM relationships with automotive Tier 1 suppliers rather than competing for hyperscale slots.
For Investors and Strategic Acquirers: The market sits at a capacity-absorption phase that favors vertically integrated producers with secured foundry offtake. Five-to-ten year viability hinges on lithography roadmap execution rather than short-term pricing. Acquisition targets should display captive NAND supply or specialized controller IP. Watch hyperscale cloud capex guidance revisions as the inflection signal for demand trajectory shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Offtake Agreement | Locks wafer allocation security for hyperscale cloud operators in Northern Virginia and Oregon. |
| Advanced Packaging Capability Buildout | Captures hybrid bonding expertise concentrated in Seoul Capital Area engineering pools. |
| FIPS 140-3 Firmware Certification Investment | Accelerates product qualification cycles for government and financial vertical procurement. |
| Edge AI Thermal Design Specialization | Addresses factory automation and autonomous vehicle sensor fusion power constraints below 7W. |
| Computational Storage Controller Development | Enables near-data analytics premium pricing for database acceleration appliances. |
Research Approach
Cross-validation between hyperscaler capex disclosures and foundry utilization reports anchors the qualitative findings on procurement pattern shifts. Primary interviews with NAND foundry planning officers, cloud infrastructure procurement leads, enterprise storage architects, and fabless controller engineering directors combined with secondary validation against SEC 10-K filings, customs trade data, and MIIT certification registries. Bottom-up segment sizing and top-down macroeconomic triangulation refined volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against alternative AI server deployment scenarios and lithography yield ramp assumptions. The modeling framework spans interface standards, NAND cell architectures, application verticals, and end-user concentration tiers throughout the forecast period. CAGRs derived from segment-level unit economics and pricing trajectory assumptions, with specific inputs including hyperscale cloud campus expansion timelines and QLC endurance specification adoption curves.
Forecasts assume regulatory continuity in EPA electronics sustainability directives and MIIT data localization mandates; material policy shifts would require re-modeling. Forecasts reflect assumptions on geopolitical trade restriction stability and AI training workload growth persistence. Revision becomes warranted when hyperscale cloud capex guidance or foundry capacity allocation announcements cross threshold deviations from modeled baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Data Storage Market
Data Storage
Optical Disk Market
Data Storage
Recordable Optical Disc Market
Data Storage
Next-Generation Storage Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
NAND Flash Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Storage and Management Market
Data Storage
AI Powered Storage Market
Data Storage
Ireland Data Center Storage Market
Data Storage
USB Key Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Blu-Ray Drive Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market