
 Enterprise Storage System Market | 2026-2036
Enterprise Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Storage System Market Intelligence
The transition from hybrid disk arrays to all-flash systems is unwinding the traditional price-performance calculus for enterprise data centers. Dell Technologies leverages its vast enterprise customer base and channel partnerships to drive its storage solutions. NetApp competes on data management software that spans on-premises and public cloud environments. Pure Storage sustains its market position through a dedicated focus on all-flash array innovation and subscription-based services.
Enterprise storage systems are centralized architectures designed for large-scale data retention, management, and retrieval. These systems utilize block, file, or object protocols to serve data from media like Solid State Drives (SSDs) or Hard Disk Drives (HDDs). While Storage Area Network (SAN) and Network Attached Storage (NAS) represent mature product types, Object Storage is expanding rapidly for cloud-native applications and big data analytics. The Solid State Drive technology segment continues to displace HDDs in primary storage tiers due to superior performance.
Regulatory frameworks like the EU's GDPR and the US's HIPAA mandate stringent data protection and residency rules. In parallel, directives from China's MIIT enforce data localization, compelling multinational firms to adopt region-specific storage strategies. These compliance obligations directly influence architectural choices for data backup and archiving. Enterprises must now balance the performance benefits of distributed architectures with the increasing complexity of cross-border data governance.
Market Dynamics
The central structural force shaping the enterprise storage market is the immense data gravity generated by artificial intelligence workloads. This requires a fundamental re-architecture of data centers, moving away from general-purpose systems toward high-performance, specialized storage infrastructure.
Growth Catalysts
- AI-Native Infrastructure:The development of AI-native applications necessitates low-latency, high-throughput storage, directly driving the adoption of all-flash arrays and NVMe-based systems for model training and inference workloads.
- Regulatory Compliance Mandates:Stringent regulations like Europe's GDPR and the US's HIPAA create persistent demand for robust data lifecycle management, backup, and archiving solutions that ensure data integrity and residency.
- Financial Services Adoption:The financial sector’s need for real-time fraud detection and high-frequency trading platforms requires extreme performance storage, fueling investment in the latest solid-state technologies.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for deploying all-flash arrays compared to traditional hard disk or hybrid systems remains a primary adoption barrier for cost-sensitive enterprises.
- Supply Chain Concentration:The global supply of high-performance NAND flash memory is heavily concentrated in South Korea and Taiwan, exposing the market to significant price volatility and geopolitical supply risks.
- Legacy System Integration:Significant technical complexity and cost are associated with integrating modern storage architectures with existing legacy applications and IT infrastructure, slowing down migration cycles.
Strategic Opportunities
- Emerging Data-Intensive Applications:The expansion of genomic sequencing, autonomous vehicle research, and smart city projects generates massive datasets, creating new demand for scalable object storage solutions.
- Storage-as-a-Service (STaaS):Offering on-premises storage infrastructure through a subscription-based, cloud-like consumption model presents an opportunity to capture customers seeking opex-based financial models.
- Underpenetrated Geographic Markets:As digitalization accelerates in regions like Southeast Asia and Latin America, there is a significant opportunity for vendors to establish a foothold by addressing nascent data center build-outs.
Industry Challenges
- Data Management Complexity:Managing data across hybrid environments that span on-premises data centers and multiple public clouds introduces significant operational complexity and security challenges for IT teams.
- Talent Scarcity:A persistent skills gap for data architects and storage engineers capable of designing, deploying, and managing sophisticated, software-defined storage systems hinders enterprise adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Storage System Market |
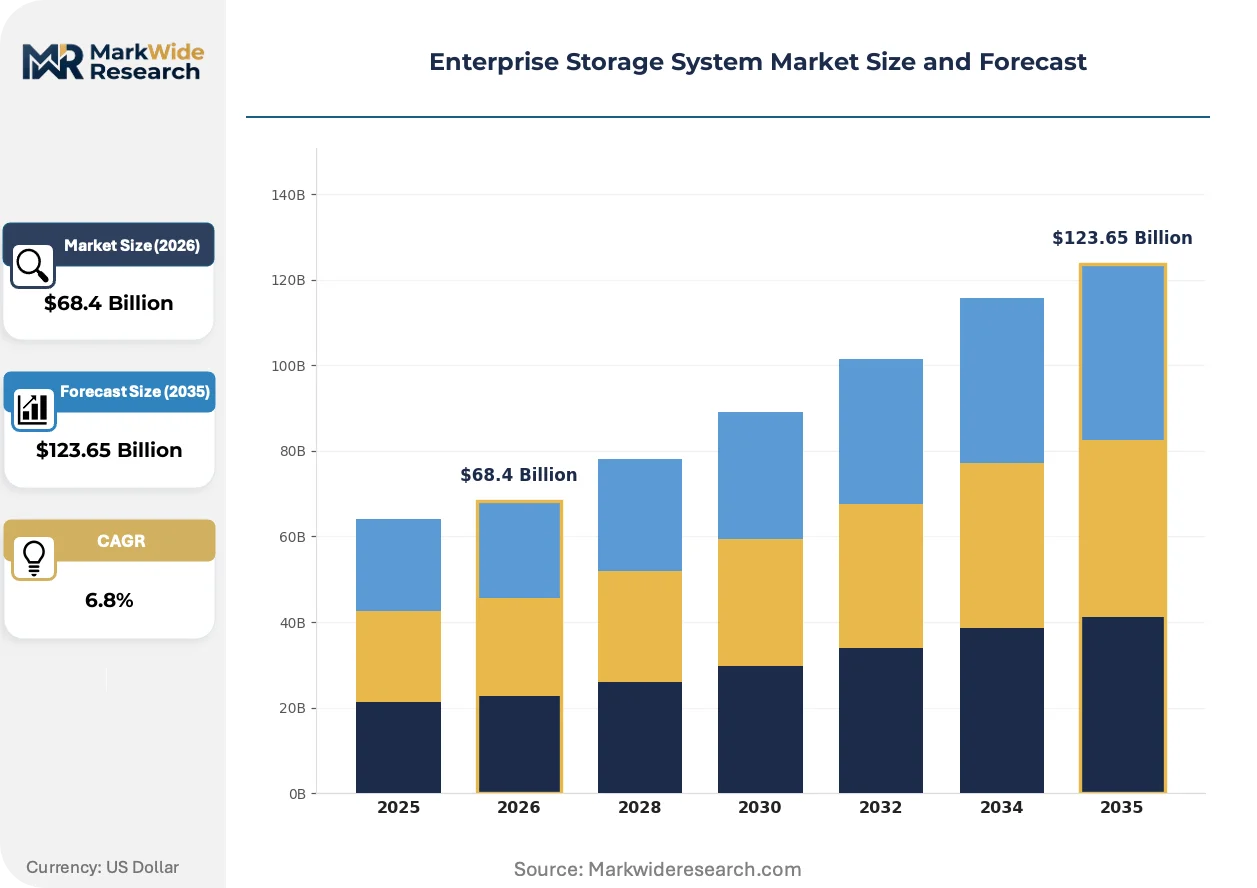
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Cloud Storage Arrays, Object Storage, Tape Storage Technology: Solid State Drive, Hard Disk Drive, NVMe, Hybrid Storage, Optical Storage, Flash Memory Application: Data Backup, Big Data Analytics, Virtualization, Content Delivery, Disaster Recovery, Archiving End User: Financial Services, Telecommunications, Government Agencies, Educational Institutions, Media & Entertainment, Manufacturing |
| Companies Covered | Pure Storage, IBM, NVIDIA, Huawei, DDN, Dell Technologies, Weka, Infinidat, NetApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Storage System Market Strategic Shifts & Innovations
The enterprise storage market is defined by specialization, as monolithic, one-size-fits-all architectures give way to tiered systems optimized for specific workloads. This evolution is driven by the distinct performance, capacity, and cost requirements of AI, analytics, and archival applications.
All-flash array technology, which utilizes Solid State Drives for data storage, delivers high-speed data access for performance-intensive workloads. The financial services and technology sectors are leading adopters for applications requiring real-time data processing. This adoption is bifurcating the market into a high-performance tier for active data and a distinct capacity tier for long-term retention.
Data localization mandates, including directives from China's MIIT and provisions within the EU's GDPR, require data to be stored within specific national or regional boundaries. This regulatory pressure compels multinational firms to shift from centralized architectures to distributed, in-country storage deployments. The cloud services segment is most impacted, responding by building region-specific data centers to offer residency guarantees.
A shift toward subscription-based consumption for on-premises hardware, known as Storage-as-a-Service (STaaS), is altering procurement patterns. This model replaces large, upfront capital investments with predictable operational expenses, challenging the traditional hardware refresh cycle. The trend is most visible in North America and Europe among enterprises seeking greater financial and operational flexibility.
Enterprise Storage System Market Segmentation
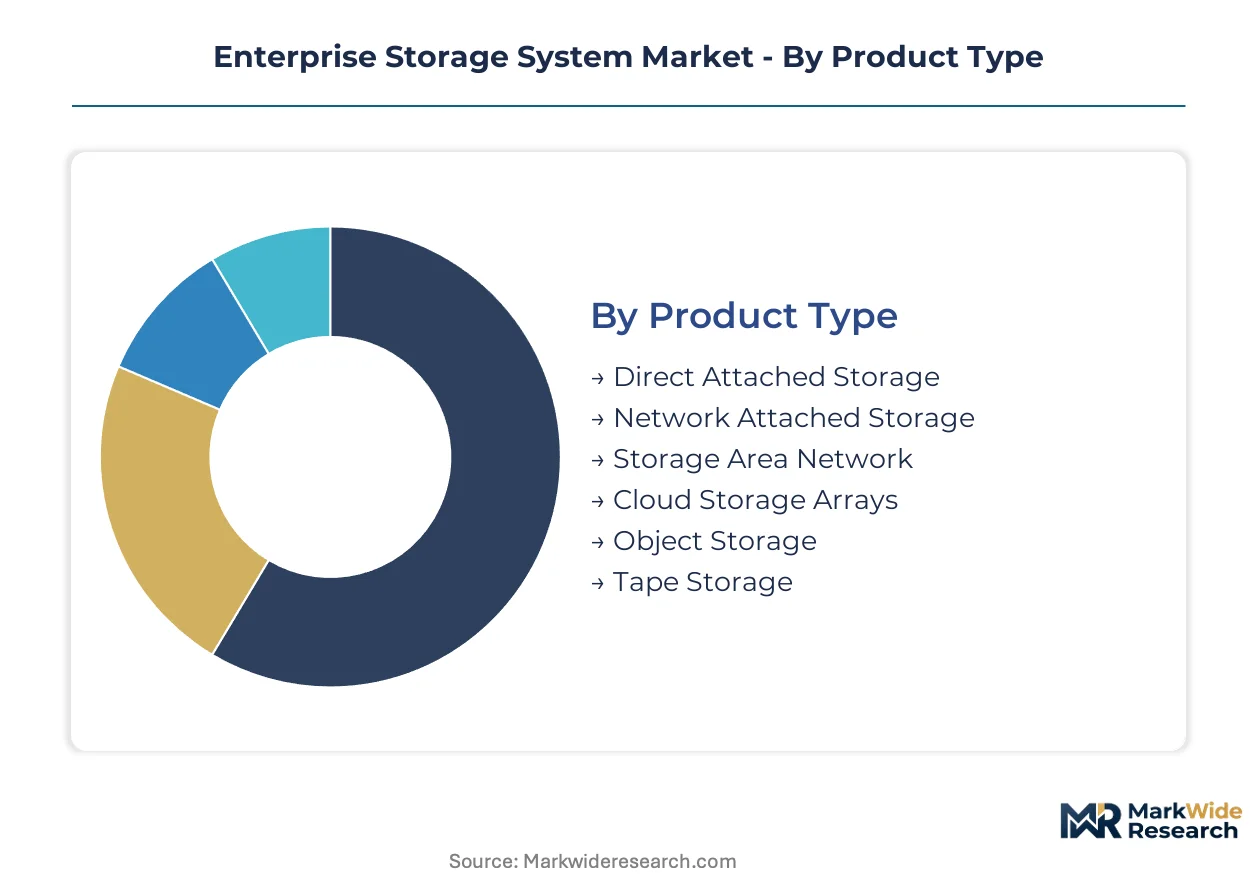
The enterprise storage system market's segmentation highlights the diverse technological and architectural requirements driven by modern data demands. This granular analysis reveals how specific product types, underlying technologies, applications, and end-user industries shape procurement decisions and innovation trajectories.
Product Type:
The Enterprise Storage System market's product type segmentation reveals significant substitution pressure as newer solutions challenge established architectures.
- Object Storage:Object Storage manages data as discrete units with metadata, ideal for unstructured data and massive scale. Cloud-native applications and big data analytics drive demand, requiring scalability.
- Storage Area Network (SAN):Storage Area Network (SAN) provides block-level data access over a dedicated network, delivering high performance for critical applications. Financial services rely on SAN for transaction processing and databases.
- Direct Attached Storage:Direct Attached Storage (DAS) connects directly to a server, offering simplicity for single-server applications.
- Network Attached Storage:Network Attached Storage (NAS) provides file-level access over a network, suitable for file sharing and collaboration.
- Cloud Storage Arrays:Cloud Storage Arrays integrate on-premises storage with public cloud services, supporting hybrid cloud strategies.
- Tape Storage:Tape Storage offers cost-effective, long-term data retention for archival and disaster recovery.
Storage Area Network (SAN) anchors the volume base while Object Storage gains share at the steepest rate.
Technology:
Technology segmentation reflects varied maturity levels and performance envelopes required by diverse enterprise workloads.
- Solid State Drive:Solid State Drive (SSD) uses non-volatile flash memory for storage, offering superior speed and lower latency than HDDs. Financial services and AI-native infrastructure adopt SSDs for performance-intensive operations.
- NVMe:NVMe (Non-Volatile Memory Express) is a high-performance interface protocol for SSDs, maximizing throughput and minimizing latency. AI model training and real-time analytics drive NVMe adoption.
- Hard Disk Drive:Hard Disk Drive (HDD) uses spinning platters for data storage, offering high capacity at a lower cost.
- Hybrid Storage:Hybrid Storage combines SSDs and HDDs, balancing performance and cost for varied workloads.
- Optical Storage:Optical Storage utilizes lasers to read and write data on discs, primarily for long-term archiving.
- Flash Memory:Flash Memory is non-volatile computer memory that can be erased and reprogrammed, forming the basis for SSDs.
Solid State Drive technology leads primary storage, with NVMe exhibiting the steepest expansion trajectory for high-performance workloads.
Application:
The application landscape for enterprise storage systems diversifies, driven by distinct performance and capacity demands of modern data processing.
- Big Data Analytics:Big Data Analytics processes vast datasets to uncover patterns, requiring high-throughput, low-latency storage for rapid ingestion and analysis. Financial services and scientific research drive demand.
- Archiving:Archiving involves long-term data retention for compliance, historical records, and legal discovery, demanding cost-effective, high-capacity, secure solutions. Regulatory mandates compel robust archiving strategies.
- Data Backup:Data Backup creates copies of data for restoration in case of loss, requiring reliable and efficient storage.
- Virtualization:Virtualization enables multiple virtual machines to share physical storage, optimizing infrastructure utilization.
- Content Delivery:Content Delivery applications distribute digital media efficiently, needing low-latency storage for rapid global access.
- Disaster Recovery:Disaster Recovery ensures business continuity by replicating data offsite, demanding resilient and accessible storage.
Big Data Analytics applications demand high-throughput storage, while Archiving solutions are critical for long-term data retention and compliance.
End User:
End-user segmentation highlights varying storage requirements and adoption rates across different industry verticals.
- Financial Services:Financial Services firms require ultra-low latency and high-performance storage for real-time analytics, fraud detection, and high-frequency trading. This sector drives investment in latest solid-state technologies.
- Manufacturing:Manufacturing companies utilize enterprise storage for managing operational data from IoT devices, CAD files, and supply chain logistics. Data integrity and rapid access are crucial for smart factory initiatives.
- Telecommunications:Telecommunications providers manage massive subscriber data and network traffic, requiring scalable and resilient storage infrastructure.
- Government Agencies:Government Agencies need secure, compliant storage for sensitive citizen data, public records, and surveillance.
- Educational Institutions:Educational Institutions store research data, student records, and digital learning content, demanding scalable and cost-effective solutions.
- Media & Entertainment:Media & Entertainment companies handle large video and audio files, requiring high-bandwidth storage for content creation and distribution.
Financial Services remains a primary adopter of high-performance storage, while Manufacturing firms increasingly invest in solutions for operational data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global enterprise storage system market exhibits varied regional dynamics, with strong domestic demand shaping local supply chains. While some regions demonstrate self-sufficiency, others remain net importers of advanced storage solutions. This balance influences infrastructure investment and technological priorities across key geographies.
United States
Demand for enterprise storage in the United States is driven by AI-native infrastructure and the financial services sector's need for real-time analytics. HIPAA regulations mandate stringent data protection for healthcare data, influencing storage architecture choices. Silicon Valley and Northern Virginia host major data center clusters, necessitating high-performance, low-latency storage solutions for cloud providers.
Germany
Germany's enterprise storage market is propelled by industrial IoT data from the manufacturing sector and strong GDPR compliance requirements. The EU's GDPR dictates strict data residency rules, compelling localized storage deployments. The Frankfurt data center hub continues to expand, serving as a critical nexus for European data exchange and storage infrastructure.
China
In China, massive data gravity from big data analytics and AI workloads fuels enterprise storage demand. MIIT directives enforce data localization, requiring multinational firms to establish in-country storage. Major technology hubs in Beijing and Shanghai are building out specialized data centers to support the nation's digital economy.
Japan
Japan's market sees demand from high-frequency trading platforms and scientific research, requiring ultra-low latency storage. METI guidelines encourage robust data protection and disaster recovery strategies for critical infrastructure. The Tokyo metropolitan area remains a primary concentration for financial data centers and advanced storage deployments.
United Kingdom
The United Kingdom's financial services industry and growing cloud-native application ecosystem drive significant enterprise storage investment. UK GDPR ensures strict data protection and residency requirements, impacting data backup and archiving solutions. London's financial district and surrounding tech corridors are central to the adoption of performance-intensive storage technologies.
Enterprise Storage System Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of enterprise storage solutions. The market structure remains tiered, with established technology conglomerates alongside nimble, innovation-driven startups. Strategic archetypes include diversified IT giants, specialized all-flash providers, and software-defined storage innovators. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand cloud integration capabilities.
Dell Technologies and IBM exemplify established IT infrastructure providers, offering broad portfolios spanning hardware and software solutions. Pure Storage and NetApp represent specialized vendors, with Pure Storage focusing on all-flash innovation and subscription models, while NetApp emphasizes data management software for hybrid cloud environments. These companies anchor different segments of the market, from traditional enterprise needs to cloud-native demands.
| Leading Market Players |
|---|
| Pure Storage |
| IBM |
| NVIDIA |
| Huawei |
| DDN |
| Dell Technologies |
| Weka |
| Infinidat |
| NetApp |
| Others |
Cost & Logistics Intelligence
Solid State Drive technology displacing Hard Disk Drives simultaneously reshapes global supply geography and pricing economics within the enterprise storage market. This fundamental shift concentrates component manufacturing in specific regions, influencing product costs and market accessibility.
Pricing Analysis
Enterprise data center operators anchor pricing structures, often favoring subscription-based models for operational flexibility. Price differentiation stems from performance tiers (NVMe versus standard SSD) and integrated data management software capabilities. Pricing pressure stems from continuous advancements in flash memory density, driving down per-gigabyte costs. Financial services firms exhibit lower price sensitivity for ultra-high performance solutions, while smaller enterprises remain highly cost-sensitive.
Supply Chain Analysis
Concentration of NAND flash memory production in South Korea and Taiwan underwrites the global enterprise storage supply chain. Key raw material dependencies include high-purity silicon and specialized controller chips. Geopolitical supply risks pose a structural risk, exposing the market to price volatility and potential component shortages. Distribution runs through a mix of direct sales channels and established IT solution providers, leveraging extensive customer bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enterprise storage market requires a substitution defense, as cloud-native architectures and all-flash systems present a continuous threat to traditional on-premises deployments.
For Market Incumbents: Compound existing channel partnerships to offer integrated hybrid cloud solutions, addressing complex data management across environments. Diversify portfolios beyond hardware, emphasizing software-defined storage and Storage-as-a-Service models. Invest in NVMe-oF and all-flash R&D to counter performance demands from AI-native infrastructure. Consolidate market share through strategic acquisitions of specialized software firms to expand cloud integration capabilities.
For New Entrants and Emerging Players: Lead with niche, high-performance solutions for emerging data-intensive applications like genomic sequencing or autonomous vehicle research. Target underpenetrated geographic markets in Southeast Asia and Latin America, addressing nascent data center build-outs. Offer specialized object storage solutions with a subscription-based, cloud-like consumption model. Focus go-to-market efforts on specific industry verticals requiring extreme performance, such as high-frequency trading platforms.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized innovation-driven firms with strong software capabilities. Long-term viability is strong, driven by immense data gravity from AI workloads. Acquisition targets should include companies focused on NVMe-based systems, advanced data management software, or Storage-as-a-Service platforms. The signal to watch is the adoption rate of opex-based storage models among enterprises seeking financial flexibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: NVMe-oF Solutions | Introduces high-performance storage for demanding AI and real-time analytics workloads. |
| Platform Integration: Hybrid Cloud Data Management | Enables seamless data management across on-premises and multi-cloud environments for enterprises. |
| Strategic Partnership: AI Solution Providers | Embeds storage solutions directly into AI infrastructure, optimizing performance for model training. |
| Acquisition of Specialist Firm: Object Storage Innovator | Expands capabilities in scalable, cost-effective storage for cloud-native applications and big data. |
| Geographic Expansion: Southeast Asia Data Centers | Captures demand in rapidly digitalizing regions with increasing data center build-outs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, industry association reports, technology journals, and government data. Primary interviews engaged storage architects, IT procurement officers, data center managers, and financial services IT leads. This approach ensures a robust, triangulated perspective, integrating both bottom-up and top-down insights across the enterprise storage ecosystem.
Segmentation dimensions modeled include product type, technology, application, end-user industry, and regional data residency requirements across the analysis window. Compound annual growth rates were derived from historical trends, market drivers, and competitive landscape analysis. Key industry-specific forecast inputs include projected AI workload growth and NAND flash memory cost curves over the projection horizon.
Forecasts assume regulatory continuity in the EU (GDPR), US (HIPAA), and China (MIIT); material policy shifts would require re-modeling. These projections reflect current market dynamics and anticipated technological advancements. Practitioners should keep alternative scenarios live as geopolitical events and rapid technological disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Serial EEPROM Market
Data Storage
Tape Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Germany Data Center Storage Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Universal Flash Storage Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
All Flash Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Flash Memory Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Distributed Storage System Market
Data Storage
Blu-Ray Optical Disk Market