
 Electrochromic Storage Devices Market | 2026-2036
Electrochromic Storage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electrochromic Storage Devices Market Intelligence
The rise of project financing models for large-scale architectural installations is reconfiguring market access for electrochromic smart window suppliers. Large, vertically integrated firms like Saint-Gobain leverage their extensive capital to fund these projects directly. In contrast, Gentex Corporation dominates the automotive sector by focusing on high-volume, standardized variable reflectance mirrors. Niche specialists such as ChromoGenics AB compete by offering customized solutions for specific European architectural projects.
Electrochromic storage devices are multifunctional systems that modulate their optical transmission or reflection upon electrical stimulation while also storing charge. Their operation relies on reversible electrochemical reactions, often involving ion intercalation into nanostructured electrodes like tungsten oxide. Smart windows for smart infrastructure developers constitute the primary application, driven by building energy efficiency goals. The development of flexible, polymer-based cells is opening new opportunities with consumer electronics makers for applications like adaptive displays.
Energy performance standards, such as those under the EU Green Deal and building codes set by US municipalities, directly influence demand. Concurrently, material composition is governed by frameworks like the EU's RoHS directive and China's GB standards for hazardous substances. Future competitiveness will depend on the ability to align product development with these evolving regional energy and environmental regulations.
Market Dynamics
The market's central dynamic is the direct linkage between building energy efficiency regulations and demand for smart windows. Mandates like the European Union's Green Deal create a non-discretionary pull for electrochromic technology in new construction and large-scale retrofits.
Growth Catalysts
- Energy Performance Mandates:Building codes in US municipalities and national frameworks like Germany's building energy act directly compel the adoption of dynamic glazing to meet stringent energy consumption targets in commercial and residential structures.
- Material Science Advances:The development of flexible, polymer-based electrochromic cells is enabling new form factors, expanding potential applications beyond flat glass into curved surfaces for automotive and consumer electronics.
- Retrofitting Incentives:Government-backed financial incentives for green retrofits in developed economies are accelerating the replacement of conventional windows in existing building stock, particularly within the commercial real estate sector.
Market Restraints
- High Upfront Cost:The initial investment for electrochromic smart windows remains substantially higher than for traditional high-performance glazing, limiting adoption in cost-sensitive construction projects without strong long-term energy savings models.
- Switching Speed and Durability:Performance limitations, including the time required to transition between transparent and opaque states and concerns about long-term cycling degradation, can deter specification in certain demanding applications.
- Material Sourcing Constraints:The supply of critical raw materials, such as high-purity tungsten oxide for electrode coatings, is concentrated among a few suppliers, creating potential price volatility and supply chain vulnerabilities.
Strategic Opportunities
- Automotive Integration:Expanding beyond variable reflectance mirrors to larger surfaces like sunroofs and side windows presents a significant volume opportunity, driven by demand for enhanced cabin comfort and energy efficiency in electric vehicles.
- IoT and Building Automation:The convergence of electrochromic devices with smart building management systems allows for automated, data-driven control of light and heat, creating value beyond simple manual adjustment.
- Consumer Electronics Displays:The development of low-power, flexible electrochromic films opens a new market for adaptive displays in smartwatches, e-readers, and other portable devices where energy efficiency and readability are critical.
Industry Challenges
- System Integration Complexity:Integrating electrochromic windows with diverse building automation systems, HVAC controls, and power infrastructure requires specialized expertise, creating installation and operational hurdles for contractors.
- Lack of Standardization:A deficit of universally accepted performance and communication protocol standards complicates the design, specification, and procurement process for architects and building engineers, slowing project timelines.
- Manufacturing Scale-Up:The high capital expenditure and complex processes required to establish and operate large-area glass coating facilities present a significant barrier to entry and limit the speed of capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrochromic Storage Devices Market |
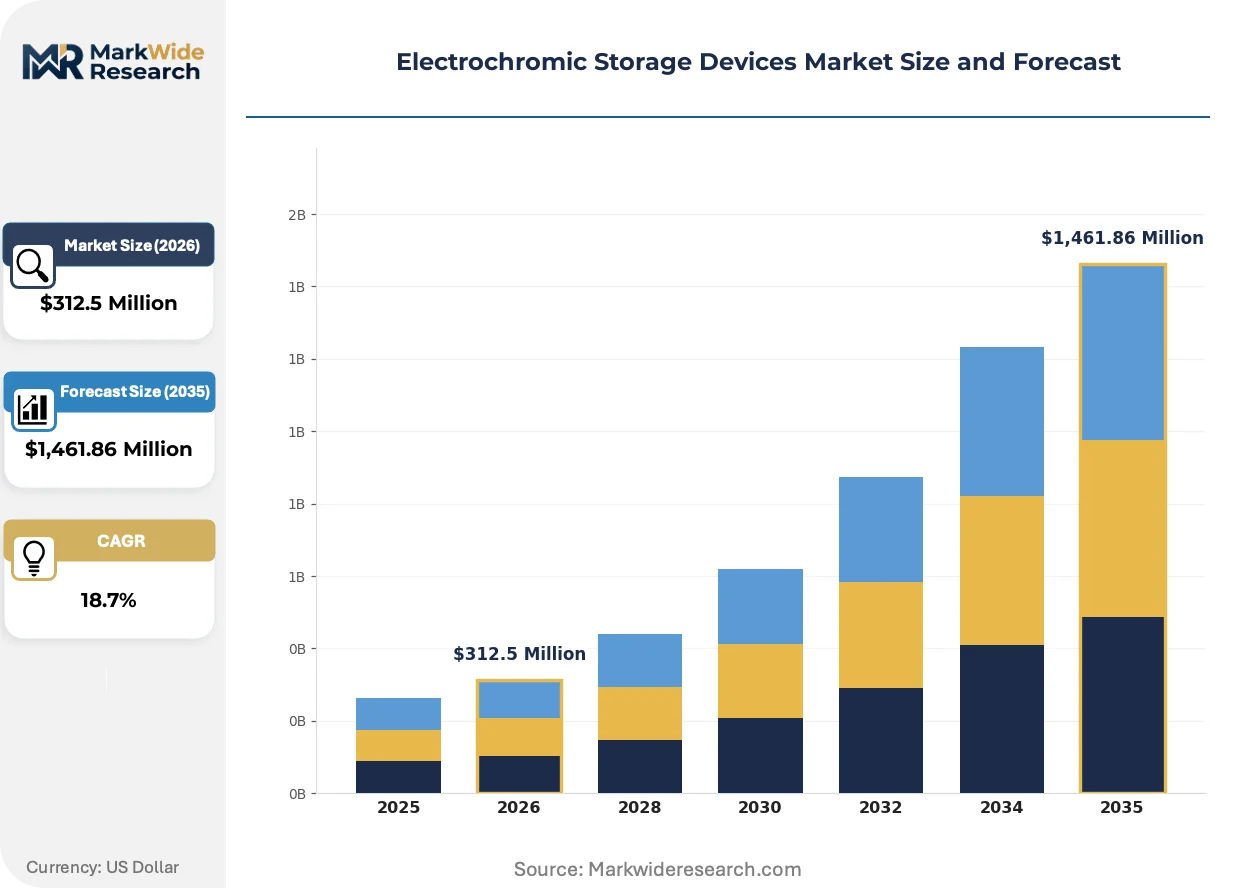
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Electrochromic Cells, Nanostructured Electrodes, Solid-State Electrochromic Devices, Polymer-Based Cells Technology: Redox Electrochromism, Ion Intercalation, Organic Electrochromism, All-Solid-State Electrochromism Application: Smart Windows, Adaptive Camouflage, Energy Storage Systems, Variable Reflectance Mirrors End User: Consumer Electronics Makers, Smart Infrastructure Developers, Aerospace Manufacturers, Defense Contractors |
| Companies Covered | AGC Inc., E Ink Holdings, Gentex Corporation, Polytronix Inc., Research Frontiers Inc., Saint-Gobain, ChromoGenics AB, Zhuhai Kaivo Optoelectronic Technology, View Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrochromic Storage Devices Market Strategic Shifts & Innovations
Product evolution is defined by the dual pursuit of enhanced performance in architectural glass and the creation of novel form factors for new industries. Material science, regulatory compliance, and shifting financing models are concurrently shaping the competitive landscape for electrochromic storage devices.
Flexible and Polymer-Based Devices
Polymer-based electrochromic cells provide optical modulation on flexible and non-planar substrates. Consumer electronics makers are beginning to adopt this technology for low-power adaptive displays and enclosures. This technology is hybridizing the functions of a static surface and a dynamic display, creating product categories beyond traditional architectural applications.
Material Composition and Environmental Compliance
The EU's RoHS directive governs the use of specific hazardous substances in electronic equipment. Its enforcement directly impacts the material science of electrochromic devices by restricting certain metals and compounds used in electrolytes and electrodes. Manufacturers targeting the European market must reformulate their products to ensure compliance, which influences global supply chain material choices.
Project-Based Financing Models
A shift toward large-scale, financed installations is altering market access for architectural projects. This model displaces the traditional direct capital equipment purchase by building owners, bundling the technology as part of a longer-term energy performance contract. This approach is gaining traction in the commercial real estate sectors of the United States and Germany.
Electrochromic Storage Devices Market Segmentation
Understanding the diverse segments within the electrochromic storage devices market reveals distinct demand patterns and technological requirements. Each category delineates specific product characteristics, underlying scientific principles, application areas, and target customer groups. This granular view helps identify key growth opportunities and competitive dynamics across the industry.
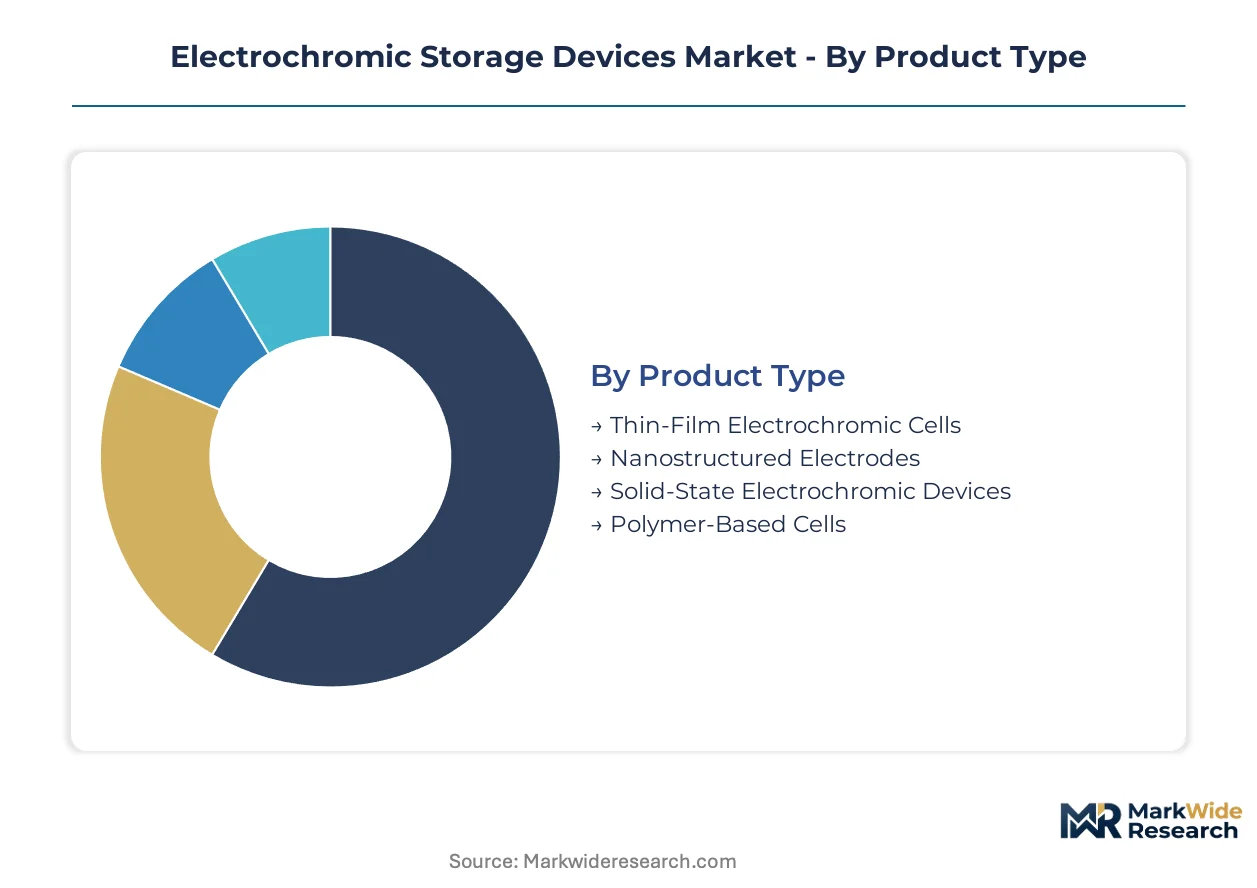
Product Type:
The product type segmentation highlights the diverse material and structural approaches enabling electrochromic functionality across a broad use-case spectrum.
- Polymer-Based Cells:These devices incorporate flexible polymer electrolytes and electrodes, allowing for lightweight, conformable, and large-area solutions. Consumer electronics makers seek these for adaptive displays and enclosures in portable devices, where flexibility and low power consumption are critical.
- Thin-Film Electrochromic Cells:Fabricated using vacuum deposition techniques, these cells offer high optical quality and precise control over light transmission. Smart infrastructure developers prioritize these for smart windows in commercial buildings, driven by stringent energy efficiency mandates in Germany and the United States.
- Nanostructured Electrodes:These leverage high surface area materials like tungsten oxide to enhance ion intercalation kinetics and improve switching speed.
- Solid-State Electrochromic Devices:Utilizing solid electrolytes, these offer improved durability and broader operating temperature ranges compared to liquid electrolyte systems.
Established volume favors Thin-Film Electrochromic Cells; emerging adoption favors Polymer-Based Cells.
Technology:
The underlying technological principles dictate performance characteristics and material compatibility for electrochromic applications.
- Ion Intercalation:This mechanism involves the reversible insertion of ions, often lithium or hydrogen, into an electrochromic host material like tungsten oxide, causing a change in optical properties. This technology underpins most commercial smart window applications, valued for its robust switching and memory effect.
- Redox Electrochromism:These systems rely on reversible oxidation-reduction reactions of organic or inorganic molecules that change color upon electron transfer. Automotive manufacturers utilize this principle for variable reflectance mirrors, providing glare reduction and enhanced driver comfort.
- Organic Electrochromism:This involves organic compounds that exhibit color changes under an electric field, often offering faster switching times and diverse color options.
- All-Solid-State Electrochromism:These devices integrate all components, including the electrolyte, in solid form, enhancing device stability and enabling flexible form factors.
Ion Intercalation technology currently dominates market share, while All-Solid-State Electrochromism shows the steepest expansion trajectory.
Application:
Application areas delineate the primary end-use cases and functional requirements for electrochromic devices.
- Smart Windows:These dynamic glazing solutions modulate light and heat transmission through electrical control, optimizing indoor comfort and energy consumption in buildings. Regulatory mandates like the EU Green Deal drive their adoption in commercial and residential construction, particularly in European markets.
- Variable Reflectance Mirrors:Integrated into automotive rearview and side mirrors, these devices automatically adjust their reflectivity to reduce glare from headlights. Automotive OEMs prioritize this application for enhancing driver safety and comfort in vehicles across North America and Asia.
- Adaptive Camouflage:This application involves dynamically changing the optical properties of surfaces to match environmental surroundings, primarily for military and defense purposes.
- Energy Storage Systems:Electrochromic materials are explored for their potential in hybrid systems that combine optical modulation with charge storage, offering multifunctional capabilities.
Smart Windows command the largest revenue share, with Adaptive Camouflage representing a niche but strategically important segment.
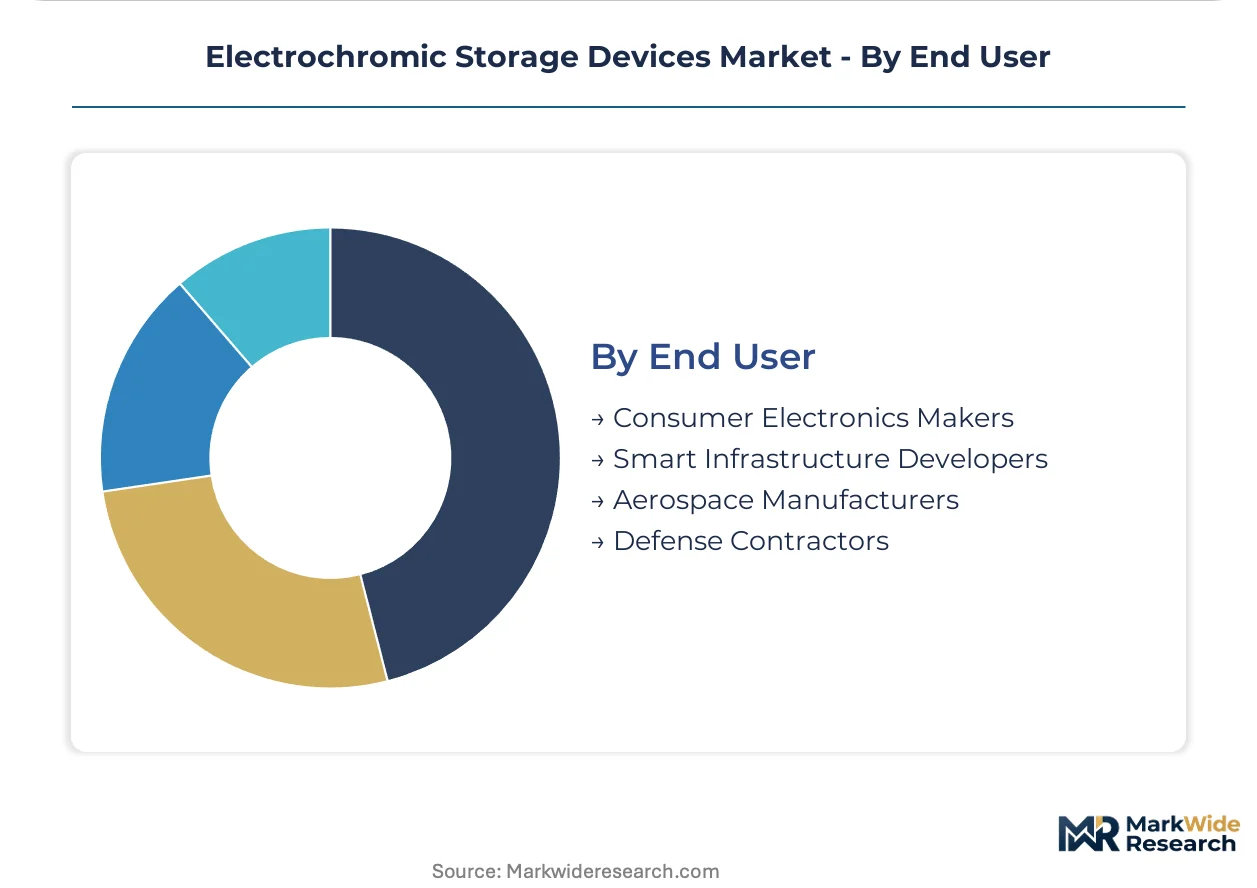
End User:
End-user segments reflect distinct procurement patterns and specific product integration needs across diverse industries.
- Smart Infrastructure Developers:These entities integrate electrochromic smart windows into commercial and residential buildings, focusing on energy efficiency, occupant comfort, and building automation system compatibility. European and North American developers lead adoption due to stringent building codes and green building certifications.
- Consumer Electronics Makers:This segment incorporates flexible and low-power electrochromic displays and surfaces into devices like smartwatches, e-readers, and specialized enclosures. Demand stems from the need for adaptive interfaces that enhance readability and extend battery life for portable electronics.
- Aerospace Manufacturers:These utilize electrochromic technology for cabin windows and glare control systems in aircraft, prioritizing lightweight solutions and high reliability.
- Defense Contractors:This group employs electrochromic devices for applications such as adaptive camouflage and stealth technology in military vehicles and equipment.
Smart Infrastructure Developers represent the largest customer base, while Consumer Electronics Makers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional demand for electrochromic storage devices, primarily smart windows, significantly influences global trade flows and manufacturing localization. Countries with stringent energy efficiency mandates drive substantial import volumes, while others focus on developing specialized materials or advanced manufacturing capabilities. This dynamic interplay shapes the competitive landscape for suppliers worldwide.
United States
Demand for smart windows in the United States stems from commercial building retrofits and new construction projects aiming for LEED certification. Building codes set by US municipalities, such as those in California, compel the adoption of energy-efficient glazing. Silicon Valley and other tech hubs actively explore electrochromic applications for adaptive displays in consumer electronics.
Germany
Germany exhibits strong demand for electrochromic smart windows, driven by the EU Green Deal and its national building energy act. These regulations mandate significant energy consumption reductions in both new and existing commercial structures. The Fraunhofer Institutes, particularly around Stuttgart, conduct advanced research into solid-state electrochromic materials and their integration.
China
China's market for electrochromic devices is expanding, fueled by rapid urbanization and government initiatives promoting green building technologies. GB standards for hazardous substances influence material composition, pushing manufacturers toward compliant solutions. Manufacturing clusters in the Yangtze River Delta focus on scaling up production for both architectural and automotive applications.
Japan
Japan's adoption of electrochromic technology is focused on enhancing energy efficiency in commercial buildings and developing advanced automotive applications. METI provides incentives for innovative energy-saving building materials, including dynamic glazing. Research institutions in Tokyo and Osaka are pioneering flexible polymer-based electrochromic films for next-generation displays.
France
France shows growing interest in electrochromic smart windows, supported by the EU Green Deal's directives for building energy performance. National regulations encourage the use of sustainable materials in construction projects. Major glass manufacturers near Paris are investing in R&D for large-area electrochromic coatings and advanced integration systems.
Electrochromic Storage Devices Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical materials and sub-assemblies. The market structure exhibits a tiered consolidation, with a few large, vertically integrated firms dominating architectural projects and a fragmented ecosystem of niche specialists. Strategic archetypes include large-scale glass manufacturers, automotive component suppliers, and specialized material science firms. Dominant competitive moves involve leveraging project financing models for large installations and strategic portfolio diversification into new application areas like consumer electronics.
Within the vertically integrated tier, Saint-Gobain exemplifies a firm utilizing extensive capital to fund large-scale architectural installations. Gentex Corporation represents a high-volume automotive component supplier, specializing in standardized variable reflectance mirrors. Niche specialists such as ChromoGenics AB occupy a position offering customized solutions for specific European architectural projects, focusing on bespoke requirements. These companies anchor different segments of the electrochromic storage devices market with distinct operational models.
| Leading Market Players |
|---|
| AGC Inc. |
| E Ink Holdings |
| Gentex Corporation |
| Polytronix Inc. |
| Research Frontiers Inc. |
| Saint-Gobain |
| ChromoGenics AB |
| Zhuhai Kaivo Optoelectronic Technology |
| View Inc. |
| Others |
Cost & Logistics Intelligence
Constrained manufacturing capacity in large-area glass coating facilities, particularly in China, drives supplier behavior by limiting output and supports premium pricing for specialized electrochromic products. This dynamic shapes market entry and expansion strategies.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing models for large-scale architectural installations. Price differentiation stems from customization levels for specific European architectural projects and the integration complexity with building automation systems. Pricing softness affects standard high-performance glazing due to high upfront costs, but premium tiers exist for advanced smart windows. Consumer electronics makers exhibit high price sensitivity for flexible displays, while smart infrastructure developers prioritize long-term energy savings.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming more prevalent for large-scale electrochromic installations, particularly for smart infrastructure developers. Supply concentrates in China for manufacturing scale-up and among a few suppliers for critical raw materials like high-purity tungsten oxide. This material sourcing constraint creates significant price volatility and supply chain vulnerabilities. Distribution runs through direct project sales for architectural applications and through OEM channels for automotive and consumer electronics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrochromic storage devices market presents a fragmentation opportunity as the demand-side shift toward flexible displays for consumer electronics creates distinct product niches. This allows specialized firms to carve out new market segments beyond traditional architectural applications.
For Market Incumbents: Harden market leadership by leveraging extensive capital to fund large-scale architectural project financing models, counteracting the high upfront cost barrier. Deepen vertical integration into critical material supply, such as tungsten oxide, to mitigate supply chain vulnerabilities. Further invest in R&D for next-generation solid-state electrochromic materials to stay ahead of emerging flexible display technologies.
For New Entrants and Emerging Players: Underpenetration in portable consumer electronics markets, particularly for adaptive displays and enclosures, offers a clear entry point. New entrants should target this white space by specializing in flexible, polymer-based electrochromic cells for smartwatches and e-readers. A go-to-market strategy focusing on low-power consumption and enhanced readability can rapidly build market share. Automotive integration beyond mirrors, into sunroofs and side windows, also represents a significant volume opportunity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across the polymer-based electrochromic cells sub-segment, signaling improved scalability for flexible applications. The market demonstrates strong long-term viability, driven by global energy efficiency mandates. Acquisition targets should focus on niche specialists with proprietary material science expertise in solid-state or polymer electrochromism, particularly those with established consumer electronics partnerships. The signal to watch is the commercialization rate of advanced flexible electrochromic films.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Scaling large-area glass coating facilities in China is critical for meeting growing demand in architectural and automotive applications. |
| Strategic Partnership with BMS Providers | Integrating electrochromic devices with smart building management systems enhances automated light and heat control for smart infrastructure developers. |
| Advanced Material R&D | Developing new polymer-based cells and alternative electrode materials reduces reliance on concentrated tungsten oxide supply and enables novel form factors. |
| Geographic Market Entry | Targeting emerging markets with new green building initiatives expands the addressable market for smart window solutions beyond developed economies. |
| Product Line Diversification | Expanding beyond variable reflectance mirrors into automotive sunroofs and side windows unlocks significant volume opportunities with automotive OEMs. |
Research Approach
Initial hypotheses were tested against primary input from smart infrastructure developers, automotive OEM procurement leads, consumer electronics makers, and material science researchers, then refined through iterative analysis. This approach combined in-depth interviews with extensive secondary validation from EU Green Deal directives, US municipal building codes, and scientific literature. Data triangulation utilized both bottom-up market sizing and top-down validation to ensure robust estimates.
The demand-supply balance over the analysis window informed the forecast framework, integrating historical trends with future projections. Segmentation dimensions modeled included product type, underlying technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from a blend of market adoption curves and material science advancement rates. Building energy efficiency mandates and raw material availability served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large vertically integrated firms or new material science specialists would shift outcomes. Projections reflect current regulatory landscapes and anticipated technological trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Storage Virtualization Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Powered Storage Devices Market
Data Storage
Data Center Ssds Market
Data Storage
Tape Storage Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Global Digital Storage Devices Market
Data Storage
All Flash Storage Market
Data Storage
NAND Flash Market
Data Storage
OTG Pen Drive Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Universal Flash Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market