
 Japan Data Center Storage Market | 2026-2036
Japan Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Storage Market Insights
Software-defined storage management is restructuring how Japanese enterprises consume capacity, shifting procurement from hardware ownership to operational expenditure models. Fujitsu Limited anchors its position through domestic manufacturing scale and deep integration with local systems integrators. Toshiba Corporation specializes in NAND flash innovation for high-performance tiers. Western Digital Corporation leverages vertical integration across HDD and flash technologies to compete on total cost of ownership.
Data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention, with specifications spanning IOPS density, latency thresholds from sub-millisecond to multi-second tiers, and endurance ratings measured in drive writes per day. These systems serve commercial and industrial computing by enabling transactional databases, analytics platforms, and backup archives. SSD deployments now lead performance-sensitive workloads in Japanese banking and IT services segments, while HDD maintains cost advantages in archival and cold storage tiers within government and healthcare end-user categories. Hybrid arrays that combine flash and spinning media are capturing growing share among enterprises optimizing across performance and capacity requirements.
METI enforces energy efficiency standards that shape storage procurement decisions, while JIS standards govern interoperability and reliability benchmarks for domestic deployments. The country's national data sovereignty framework restricts cross-border data flows, mandating localized storage infrastructure for sensitive sectors. Stakeholders must monitor evolving carbon accounting rules and assess how storage refresh cycles align with both performance requirements and sustainability compliance obligations.
Market Dynamics
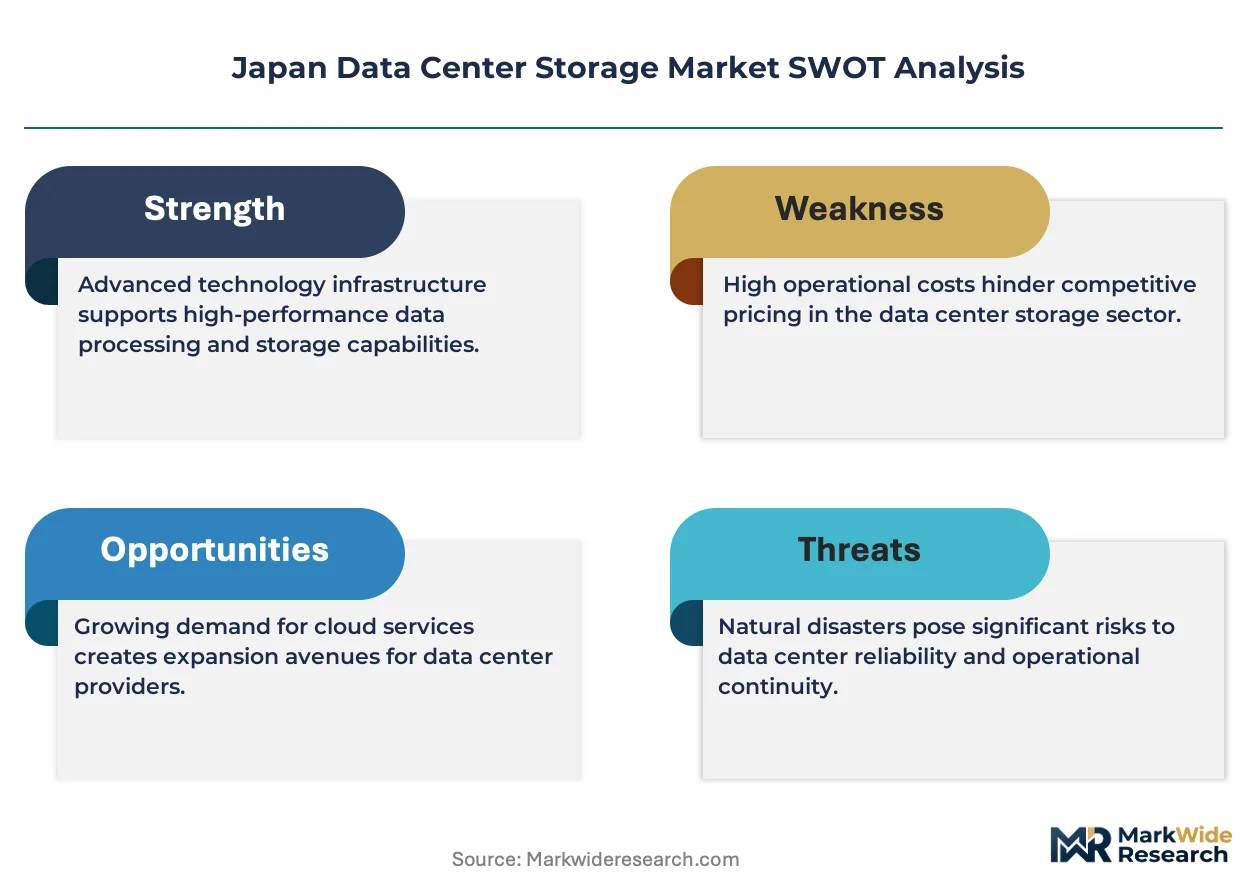
Software-defined storage architectures are restructuring procurement economics across Japanese enterprises, compressing hardware refresh cycles while expanding operational expenditure commitments. METI's Green Transformation policy mandates energy efficiency disclosures that favor flash-dominant configurations over spinning media in new facility deployments.
Growth Catalysts
- AI Training Workloads:Japanese cloud service providers are expanding storage procurement to support generative model development. Hyperscale facilities in the Greater Tokyo Area require petabyte-scale flash arrays for low-latency training data access.
- METI Green Transformation:Carbon accounting rules for data center operators accelerate replacement of legacy HDD infrastructure. Energy-efficient storage tiers qualify for preferential grid interconnection and tax treatment.
- Data Sovereignty Mandates:National restrictions on cross-border data flows mandate localized storage infrastructure for financial services and healthcare sectors. Domestic facility construction concentrates demand in certified hyperscale campuses.
Market Restraints
- NAND Flash Supply Concentration:Japanese end-users depend on concentrated overseas foundry output for high-performance SSD procurement. Geopolitical friction in Taiwan Strait shipping lanes introduces supply continuity risk.
- Capital Intensity of All-Flash Arrays:Per-terabyte acquisition costs for enterprise NVMe systems exceed hybrid alternatives by substantial margins. Mid-tier enterprises defer full flash conversions despite performance requirements.
- JIS Certification Timelines:Domestic reliability standards impose extended validation periods for new storage architectures. Foreign vendors face 6-12 month delays before commercial deployment authorization.
Strategic Opportunities
- Osaka-Kansai Data Center Cluster:Underdeveloped secondary market offers lower land and power costs versus saturated Tokyo corridor. METI regional development incentives support facility construction outside capital region.
- Computational Storage Convergence:Integration of processing capability within storage devices reduces data movement overhead. Financial services and genomics research segments demonstrate early adoption appetite.
- Subscription Management Platforms:Cloud-adjacent consumption models displace traditional capital purchase cycles. Systems integrators capture recurring revenue through capacity-as-a-service arrangements.
Industry Challenges
- Legacy Mainframe Integration:Banking and government sectors maintain decades-old transactional systems requiring specialized storage gateway architectures. Hybrid cloud connectivity demands custom engineering resources scarce in domestic labor pools.
- Carbon Footprint Verification:Supply chain emissions disclosure requirements extend to component-level sourcing. Vendors struggle to obtain certified lifecycle data from upstream memory and controller suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Storage Market |
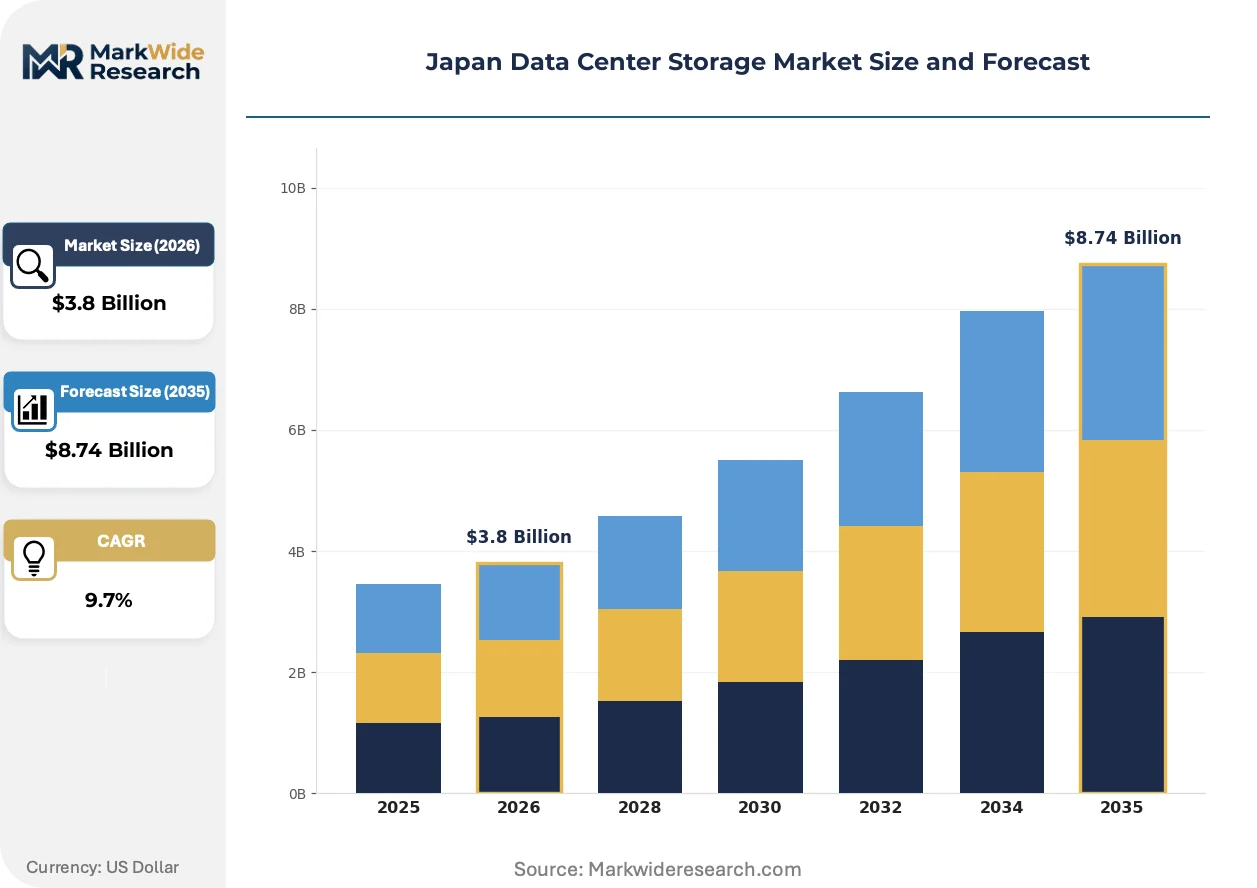
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSD, HDD, Tape, Hybrid Storage Deployment Model: On-Premises, Cloud, Hybrid, Colocation End User: IT Services, Banking, Healthcare, Government Capacity: 1TB, 10TB, 100TB, 1PB |
| Companies Covered | Toshiba Corporation, NetApp Inc, Fujitsu Limited, Lenovo Group Limited, Western Digital Corporation, NEC Corporation, Hewlett Packard Enterprise, Seagate Technology LLC, Hitachi Vantara LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Storage Market Trends and Innovations
Storage infrastructure across Japanese data centers is undergoing architectural transformation driven by artificial intelligence workload requirements and sustainability compliance pressures. Three convergent developments are restructuring competitive positioning and procurement patterns.
Computational storage drives with embedded processing capability are modularizing traditional server-storage boundaries. Financial institutions running real-time risk analytics have adopted these devices to reduce data movement latency. The technology is compressing conventional three-tier architectures into consolidated infrastructure stacks.
METI's Green Transformation policy mandates granular energy consumption reporting for data center operators exceeding specified power thresholds. Storage subsystem efficiency now directly influences facility-level carbon accounting and grid interconnection priority. Operators are responding by specifying flash-dominant configurations and liquid-cooled enclosures in new procurement tenders.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software platforms rather than discrete component sourcing. Systems integrators and cloud service providers now specify outcome-based capacity contracts with guaranteed latency and availability thresholds. This pattern concentrates procurement authority among hyperscale operators and their designated integration partners in the Greater Tokyo Area.
Japan Data Center Storage Market Segmentation
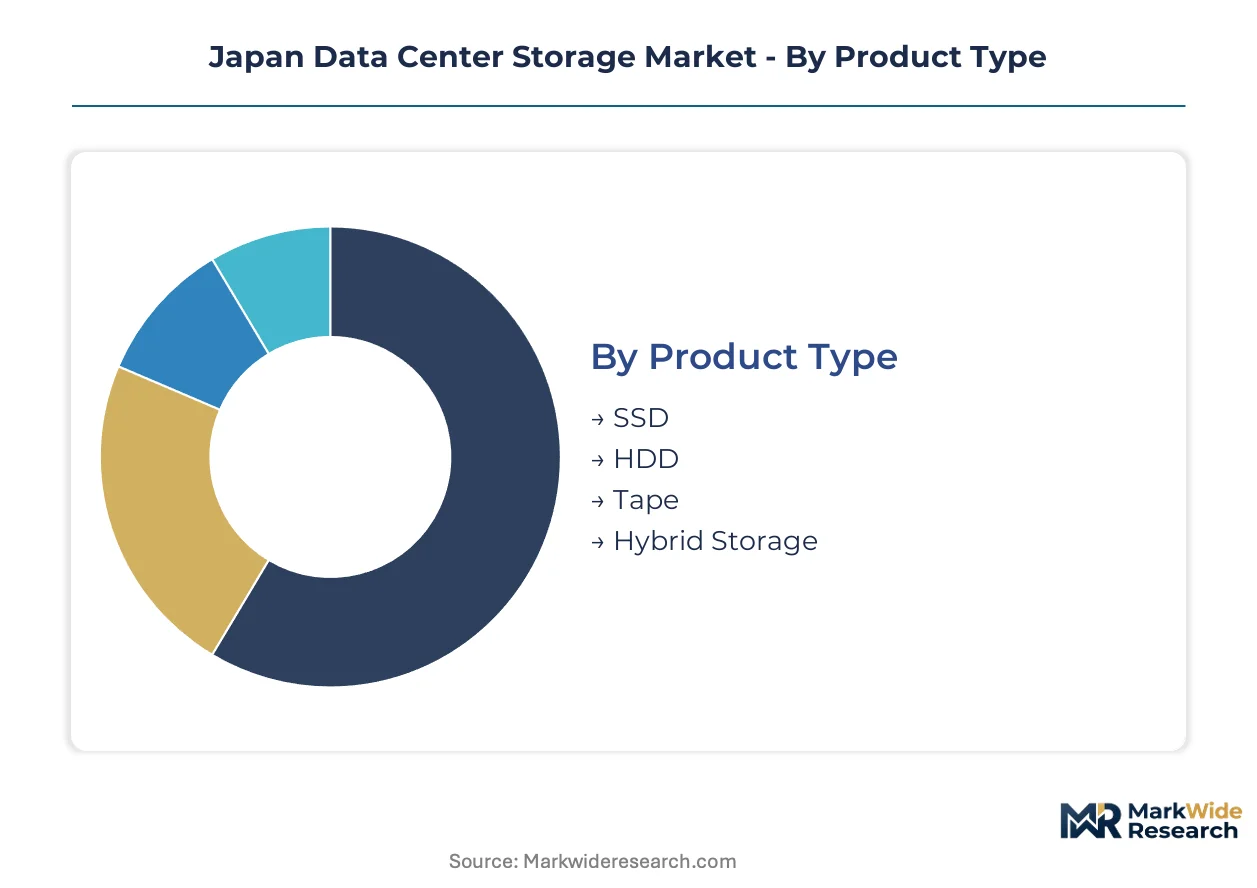
Storage procurement patterns across Japanese data centers diverge sharply by workload sensitivity, regulatory exposure, and infrastructure ownership models. Segment boundaries determine vendor selection criteria, pricing structures, and deployment timelines for facility operators.
Product Type:
Buyers in this category separate by latency tolerance, energy constraints, and archival retention requirements.
- SSD:NAND flash arrays deliver sub-millisecond access for transactional databases and AI training pipelines. Japanese banking and IT services segments specify NVMe configurations for real-time analytics, though per-terabyte premiums constrain mid-tier enterprise adoption.
- HDD:Electromechanical spinning media retains cost advantages for sequential access workloads and long-term archives. Government and healthcare end-users in Greater Tokyo continue procuring high-capacity drives for compliance-mandated retention, despite METI pressure to phase out power-intensive infrastructure.
- Tape:Magnetic cartridge systems serve air-gapped backup and disaster recovery for regulated sectors. Domestic financial institutions maintain tape libraries for immutable audit trails.
- Hybrid Storage:Tiered architectures combine flash caching with HDD capacity pools. Enterprises optimizing across performance and budget constraints favor these configurations for mixed workload environments.
SSD leads volumes today; hybrid storage is gaining share fastest.
Deployment Model:
Infrastructure control preferences and data sovereignty exposure separate buyers across this dimension.
- On-Premises:Captive facilities under direct enterprise management house sensitive transactional systems. Japanese banking and government sectors mandate on-site retention for sovereign data classification, requiring specialized storage gateway integration with legacy mainframe environments.
- Cloud:Hyperscale provider-managed capacity supports elastic AI training and development workloads. Japanese cloud service providers in Greater Tokyo are expanding petabyte-scale flash procurement for generative model infrastructure.
- Hybrid:Split architectures place latency-critical data on-premise while bursting analytics to cloud tiers. IT services vendors architect these configurations for clients navigating METI carbon accounting rules.
- Colocation:Third-party data center operators provide certified facilities with guaranteed power and connectivity. Osaka-Kansai cluster development is attracting colocation demand from enterprises seeking lower land costs versus saturated Tokyo corridors.
On-premises retains the largest installed base; cloud deployments are expanding most quickly.
End User:
Regulatory intensity and workload sophistication determine storage specification patterns across verticals.
- IT Services:Managed service providers provision multi-tenant infrastructure across client portfolios. These operators specify software-defined platforms with subscription consumption models to compress capital cycles.
- Banking:Financial institutions run real-time risk analytics on computational storage devices. JIS certification requirements and legacy system integration constraints extend procurement timelines for this segment.
- Healthcare:Medical imaging archives and electronic health record systems drive capacity demand. National data sovereignty mandates require localized infrastructure for patient data.
- Government:Public sector procurement favors domestic vendors and extended warranty terms. METI Green Transformation compliance accelerates flash-dominant refresh cycles in new facility tenders.
IT services leads current procurement volumes; banking shows the steepest expansion trajectory.
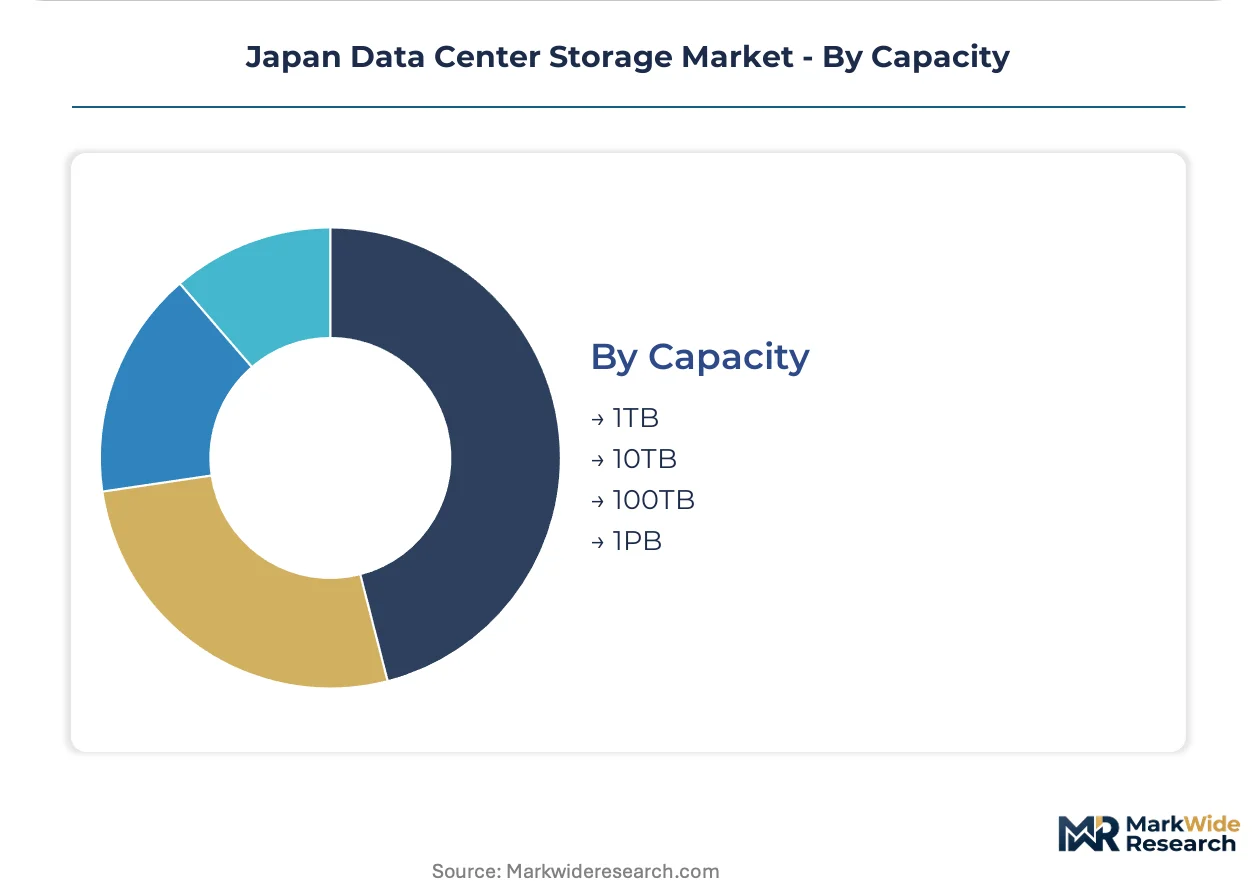
Capacity:
Scale economics and infrastructure generation separate buyers across capacity tiers.
- 1TB:Entry-level configurations serve edge computing nodes and small-scale development environments. Remote office deployments in Japan's secondary cities specify these units for cost-constrained scenarios.
- 10TB:Mid-range systems support departmental analytics and virtualized server consolidation. Enterprise refresh cycles increasingly favor this tier for hybrid array controller pairs.
- 100TB:High-density enclosures address consolidated primary storage for medium-scale data centers. Osaka-Kansai facility construction is driving demand in this segment.
- 1PB:Hyperscale configurations serve AI training datasets and multi-petabyte archival repositories. Greater Tokyo hyperscale campuses specify these systems for cloud service provider expansion.
10TB configurations dominate current shipments; 1PB systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between Japanese prefectures are redirecting data center investment toward secondary markets. METI's regional development incentives reduce compliance burdens outside the saturated Tokyo corridor. Facility operators exploit these arbitrage opportunities to secure lower land and power costs while maintaining proximity to end-user demand.
Kanto/Tokyo
Hyperscale cloud providers dominate storage procurement in the Greater Tokyo Area. METI enforces stringent carbon accounting rules that accelerate flash-dominant infrastructure refresh cycles. Saitama and Chiba prefectures host expanding colocation campuses serving financial services and IT services segments with petabyte-scale NVMe arrays.
Kansai/Osaka
Osaka-Kansai cluster development attracts enterprises seeking relief from Tokyo's land scarcity and premium power pricing. METI regional development incentives subsidize facility construction in this underdeveloped secondary market. Kyoto and Hyogo prefectures are emerging as certified hyperscale locations with lower operational expenditure profiles for archival and hybrid storage deployments.
Chubu/Nagoya
Manufacturing-heavy industrial bases in Aichi and Gifu prefectures generate demand for edge computing storage nodes. Local systems integrators provision 10TB hybrid arrays for smart factory analytics and supply chain optimization. METI Green Transformation compliance pressures are accelerating SSD adoption in these automotive and electronics manufacturing corridors.
Kyushu
Fukuoka and Saga prefectures leverage submarine cable landing stations for disaster recovery and backup storage facilities. Lower seismic risk profiles compared to eastern Japan attract archival tape and cold HDD deployments. National data sovereignty mandates require localized infrastructure for regional banking and healthcare data retention.
Hokkaido
Cool ambient temperatures reduce cooling energy burdens for hyperscale storage facilities in Sapporo and surrounding areas. METI incentives target this region for sustainable data center development with renewable energy integration. Government and research institutions are establishing 1PB-scale archival repositories for climate and genomic datasets.
Japan Data Center Storage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with domestic incumbents commanding sovereign-sensitive verticals while global vendors penetrate cloud-adjacent workloads. The vendor base concentrates around three tiers: integrated hardware-software platforms, component specialists, and systems integration partners. Strategic archetypes include domestic manufacturing champions, NAND flash innovators, and vertical integration specialists. Competitive dynamics center on JIS certification speed and METI sustainability compliance integration.
Among domestic manufacturing champions, Fujitsu Limited and Toshiba Corporation anchor the sovereign procurement tier. Western Digital Corporation occupies a position exemplifying vertical integration across electromechanical and solid-state technologies. These three entities represent distinct competitive vectors: domestic systems integration depth, NAND flash innovation specialization, and total cost of ownership optimization through captive supply control.
| Leading Market Players |
|---|
| Toshiba Corporation |
| NetApp Inc |
| Fujitsu Limited |
| Lenovo Group Limited |
| Western Digital Corporation |
| NEC Corporation |
| Hewlett Packard Enterprise |
| Seagate Technology LLC |
| Hitachi Vantara LLC |
| Others |
Pricing and Supply Chain Analysis
NVMe flash arrays command substantial premiums over hybrid configurations, a tier divergence that compresses distributor margins on high-performance SKUs while pushing systems integrators toward subscription-based capacity contracts. METI carbon accounting rules feed back into procurement economics, rewarding flash-dominant deployments with preferential grid interconnection that offsets acquisition cost differentials across facility operator budgets.
Pricing Analysis
Direct-to-OEM channels handle hyperscale buyer demand with volume-scaled discounts that bypass traditional distributor markups. Three-tier pricing structure across premium NVMe, standard hybrid, and economy HDD levels tracks JIS certification grade and energy efficiency rating. Cost compression in mid-tier hybrid arrays is intensifying because cloud service providers consolidate procurement around integrated hardware-software platforms. Government and healthcare segments show highest price sensitivity due to fixed-budget procurement cycles, while banking institutions prioritize latency guarantees over per-terabyte cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand with dedicated allocation agreements that secure priority fab output. NAND flash supply concentrates in South Korea, Taiwan, and USA foundry complexes, with Japanese end-users drawing from concentrated overseas wafer output. Raw material dependencies span silicon wafers, rare earth elements for controller chips, and specialty gases for fabrication processes. Single-source vulnerability in Taiwan Strait shipping lanes introduces supply continuity exposure. Distribution runs through authorized systems integrators and cloud service provider procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Osaka-Kansai facility construction offers land and power cost arbitrage against saturated Tokyo corridors, with METI regional incentives reducing compliance burdens for secondary market entrants.
For Market Incumbents: Extend JIS certification pipelines to compress 6-12 month validation delays that foreign competitors face. Deepen backward integration into NAND controller design to reduce exposure to Taiwan Strait logistics chokepoints. Anchor procurement relationships with Greater Tokyo hyperscale operators through guaranteed latency SLA contracts that lock out challenger vendors. For New Entrants and Emerging Players: Computational storage convergence offers a technology-first wedge into financial services real-time analytics segments underserved by legacy three-tier architectures. Target Osaka-Kansai colocation demand where land scarcity pressures are weakest. Pursue outcome-based capacity-as-a-service arrangements that displace capital purchase cycles among mid-tier enterprises. For Investors and Strategic Acquirers: Consolidation pressure builds where systems integrators lack captive supply relationships and face margin compression from hyperscale direct procurement. Long-term viability favors vertically integrated platforms with domestic manufacturing footprints and METI sustainability compliance integration. Watch JIS certification timeline acceleration as inflection signal for foreign vendor market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Osaka-Kansai Facility Expansion | Secondary market development captures METI regional incentives and lower operational expenditure profiles. |
| Computational Storage Integration | Embedded processing capability reduces data movement overhead for financial risk analytics workloads. |
| JIS Certification Acceleration | Compressed validation timelines unlock commercial deployment authorization for new storage architectures. |
| Subscription Platform Development | Capacity-as-a-service models displace traditional capital purchase cycles among enterprise buyers. |
| Liquid-Cooled Enclosure Deployment | METI Green Transformation compliance qualifies facilities for preferential grid interconnection status. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned data center facility operators, systems integrators, cloud service provider procurement teams, and METI policy officials. Secondary validation drew from hyperscaler capex disclosures, customs import records for storage components, JIS standards documentation, and facility construction permit databases. Bottom-up shipment tracking and top-down facility capacity estimates were cross-referenced for triangulation.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions spanned product type, deployment model, end-user vertical, and capacity tier, with regional prefecture clusters as an additional geographic dimension. CAGRs were derived from facility construction pipeline analysis and storage refresh cycle patterns. AI training workload intensity and METI carbon accounting enforcement served as industry-specific demand drivers.
The model holds under stable NAND supply conditions and sustained METI incentive frameworks; deviation in Taiwan Strait logistics or Green Transformation policy acceleration would shift procurement timing and vendor selection patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Portable Storage Device Control Software Market
Data Storage
SSD Controller Market
Data Storage
Data Storage Market
Data Storage
Australia Data Center Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Transparent Caching Market
Data Storage
Data Center Ssds Market
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Multiprotocol Storage Market
Data Storage
Zoned Flash Market
Data Storage
Blu-Ray Drive Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Tape Storage Market
Data Storage
North America SSD Caching Market