
 Splicing Tapes Market | 2026-2036
Splicing Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Splicing Tapes Market Intelligence
Asian petrochemical feedstock availability is hardening the cost position of regional adhesive producers. Nitto Denko Corporation leverages its polymer synthesis capabilities to control specialty acrylic formulations. Tesa SE anchors European supply through backward integration into release liner substrates. 3M Company dominates North American distribution via direct technical service teams embedded with automotive OEMs.
Splicing tapes are pressure-sensitive adhesive constructions engineered for joining discontinuous material webs, typically featuring carrier films of polyester, polyimide, or glass cloth with coated chemistries rated for dielectric strength and shear resistance. Acrylic-based formulations deliver broad temperature tolerance and UV stability for outdoor electrical insulation, while silicone-based grades withstand sustained exposure above 180°C in aerospace wire harnessing. Rubber-based products occupy mature, price-sensitive industrial packaging segments where peel adhesion requirements are moderate. Hot melt adhesives represent the fastest-expanding chemistry for temporary splicing in high-speed converting operations due to instant green strength and solvent-free processing.
REACH registration requirements in Europe, OSHA hazard communication standards in the United States, and GB standards compliance in China collectively constrain formulation choices and market entry for non-compliant suppliers. The EU F-Gas Regulation indirectly shapes demand by accelerating transitions to electrical systems requiring more robust insulation and splicing materials. Stakeholders must monitor evolving substance restriction lists and polymer recycling mandates to anticipate reformulation cycles and qualification timelines.
Market Dynamics
Automotive electrification and 5G telecommunications buildouts are compressing qualification timelines for dielectric splicing materials, forcing adhesive formulators to validate silicone and acrylic chemistries against stricter thermal cycling and signal integrity standards simultaneously.
Growth Catalysts
- Automotive electrification:Battery pack manufacturers in Germany and the United States are specifying polyimide carrier films with silicone adhesives rated for 180°C continuous operation in high-voltage harnessing.
- REACH substance restrictions:ECHA's evolving candidate list is disqualifying legacy solvent-based acrylics, redirecting procurement toward waterborne and hot-melt alternatives with documented SVHC compliance.
- Telecommunications infrastructure:China's MIIT spectrum allocations for millimeter-wave 5G are mandating low-dielectric-loss splicing tapes for fiber-to-the-antenna deployments.
Market Restraints
- Petrochemical feedstock volatility:Asian acrylic acid and silicone monomer supply concentration exposes formulators to naphtha-cracking margin compression and force majeure disruptions.
- Specialty release liner scarcity:European glass cloth and fluorosilicone-coated paper substrate capacity is tightening lead times for aerospace-grade constructions.
- Technical performance ceilings:Rubber-based formulations face hard limits in dielectric strength and thermal aging that disqualify them from emerging EV battery applications.
Strategic Opportunities
- India wire harnessing localization:PLI scheme incentives for automotive component manufacturing are creating captive demand for temperature-rated splicing materials with BIS certification.
- Hot-melt chemistry convergence:UV-curable and moisture-cure hybrid adhesives are opening temporary splicing applications in high-speed converting previously served by solvent systems.
- EU F-Gas Regulation tailwind:Refrigeration system electrification is expanding demand for hermetic motor lead splicing with extended thermal endurance ratings.
Industry Challenges
- Polymer synthesis talent scarcity:Formulation chemists with expertise in silane-terminated polyurethane and fluorinated acrylic copolymers command premium compensation and extended recruitment cycles.
- Multi-jurisdiction qualification burden:Simultaneous UL, VDE, and GB standard testing for a single product variant extends time-to-revenue by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Splicing Tapes Market |
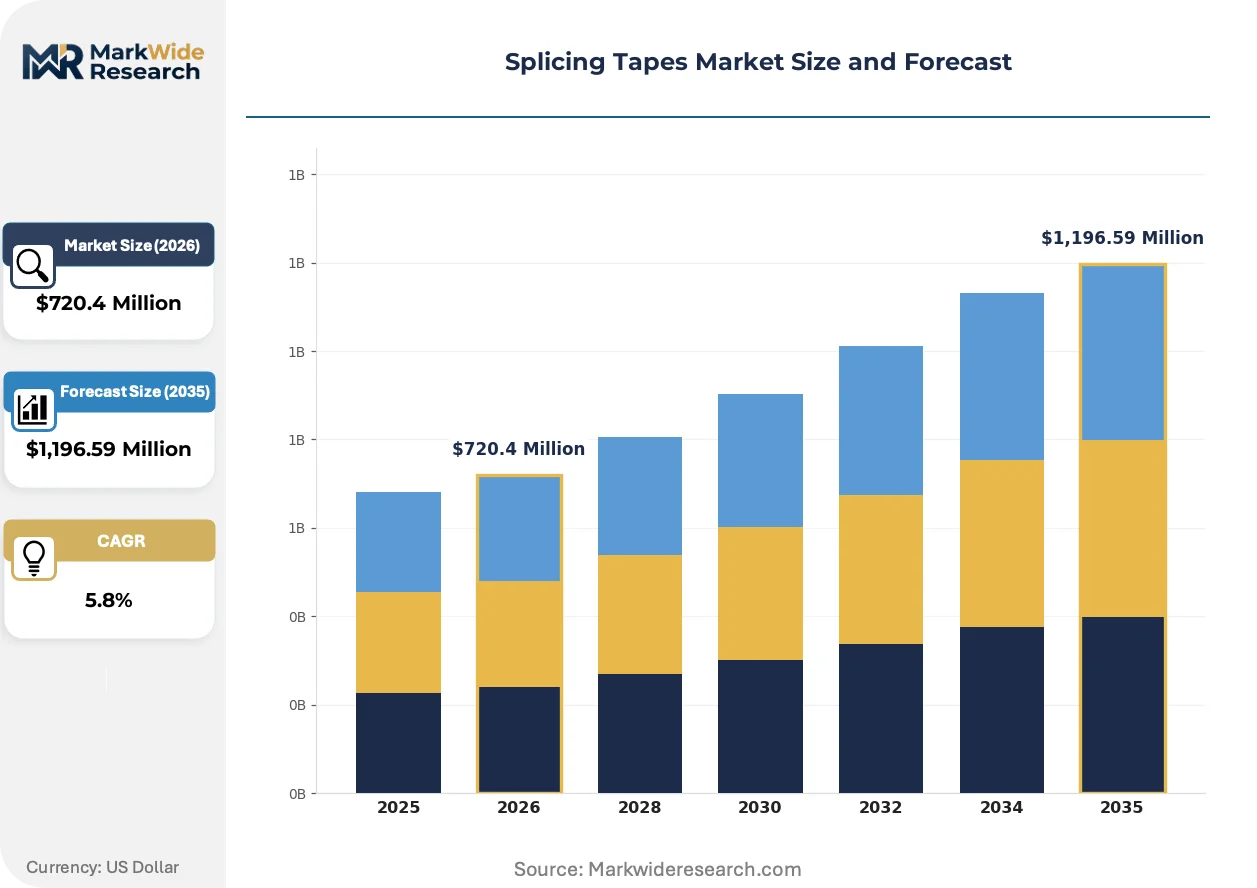
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,196.59 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber-Based, Acrylic-Based, Silicone-Based, Hot Melt, Water-Based Application: Wire & Cable Jointing, Electrical Insulation, Industrial Packaging, Automotive Assembly, Signage Mounting End User Industry: Telecommunications, Electronics Assembly, Aerospace Manufacturing, Consumer Goods Fabrication, Construction Installation Type: Permanent Bonding, Temporary Splicing, High-Temperature Resistance, Cold-Weather Use |
| Companies Covered | 3M Company, tesa SE, Nitto Denko Corporation, Avery Dennison Corporation, Intertape Polymer Group, Shurtape Technologies, Scapa Group plc, Lintec Corporation, ORAFOL Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Splicing Tapes Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine performance benchmarks across electrical insulation and web-converting applications, compressing the viable formulation window for incumbent adhesive platforms.
Laser-activated adhesive platforms are integrating photothermal curing mechanisms that enable on-demand bonding without thermal damage to sensitive substrates. Medical device cable manufacturers in Switzerland and Minnesota are piloting these systems for miniaturized lead configurations. The technology is integrating precision placement capabilities that eliminate mechanical fixation hardware from catheter and endoscope assemblies.
EU F-Gas Regulation phase-down schedules are accelerating transitions from mechanical compression to electrical drive systems in commercial refrigeration and heat pumps. This regulatory pressure is expanding the addressable market for high-temperature splicing tapes in hermetic motor terminations and inverter-fed compressor leads. German and Italian HVAC OEMs are now specifying 200°C-rated silicone constructions as standard for R-290 propane systems.
Consolidated procurement by automotive tier-one suppliers is displacing fragmented distributor purchasing with direct material qualification programs and annual volume commitments. Web-converting operations in the United States and Japan are consolidating tape specifications to reduce SKU complexity and secure preferential pricing. This concentration is most visible in lithium-ion cell manufacturing, where CATL and LG Energy Solution are qualifying single-source splicing constructions for electrode winding and tab bonding operations.
Splicing Tapes Market Segmentation
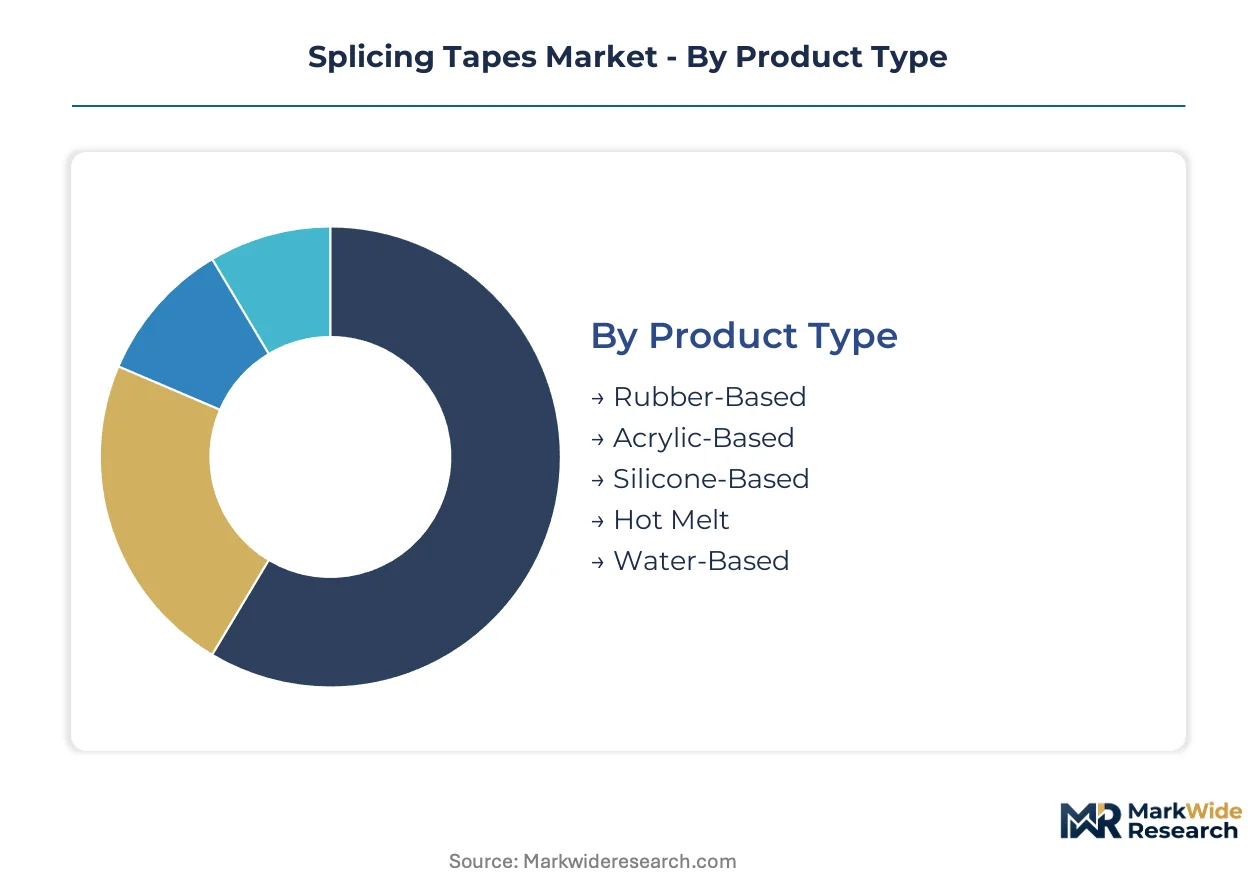
Splicing tape specifications diverge sharply across electrical, thermal, and mechanical performance requirements. Buyer priorities in automotive electrification, telecommunications infrastructure, and aerospace manufacturing create distinct procurement criteria that reshape formulation strategies and carrier film selections.
Product Type:
Buyers in this category differentiate primarily by operating temperature range and dielectric endurance requirements rather than unit cost.
- Silicone-Based:Polydimethylsiloxane adhesives bonded to polyimide or glass cloth carriers deliver continuous operation at 180-200°C with minimal thermal degradation. German automotive OEMs specify these constructions for high-voltage battery harnessing where thermal cycling resistance determines warranty exposure.
- Acrylic-Based:Cross-linked acrylic copolymers provide UV stability and broad temperature tolerance from -40°C to 150°C on polyester film carriers. China's MIIT spectrum allocations for millimeter-wave 5G are accelerating procurement of low-dielectric-loss acrylic grades for fiber-to-the-antenna installations.
- Rubber-Based:Natural and synthetic rubber adhesives on crepe paper or film carriers serve mature industrial packaging segments where moderate peel adhesion satisfies cost-sensitive buyers.
- Hot Melt:Thermoplastic block copolymers enable instant green strength without solvent emissions, gaining traction in high-speed converting operations across Japan and the United States.
- Water-Based:Acrylic emulsion adhesives with reduced VOC profiles address REACH compliance constraints in European electrical insulation applications.
Volume sits with acrylic-based formulations; growth tilts toward silicone-based grades.
Application:
End-use environments dictate adhesive chemistry selection through dielectric strength thresholds and exposure severity.
- Wire & Cable Jointing:Dielectric-rated constructions with specified breakdown voltage and elongation properties join discontinuous conductor runs in power distribution and telecommunications infrastructure. German grid operators and Chinese tower contractors are standardizing silicone-polyimide laminates for medium-voltage underground cable repairs.
- Electrical Insulation:Multi-layer adhesive systems with controlled dissipation factors isolate live conductors from grounded enclosures across switchgear, motors, and transformers. The EU F-Gas Regulation is expanding this segment through hermetic motor electrification in commercial refrigeration systems.
- Industrial Packaging:Lower-specification rubber and hot-melt products secure corrugated seams and pallet unitization where temporary holding strength suffices.
- Automotive Assembly:Temperature-rated splicing materials with documented thermal aging performance qualify for battery pack, inverter, and electric motor lead terminations under OEM direct material programs.
- Signage Mounting:UV-stable acrylic constructions on clear polyester film enable exterior graphic applications with clean removability requirements.
Revenue concentrates in wire and cable jointing; steepest expansion trajectory appears in automotive assembly.
End User Industry:
Industry-specific certification regimes and performance documentation requirements segment procurement behavior.
- Telecommunications:Low-loss dielectric specifications for millimeter-wave signal integrity drive material selection for 5G infrastructure deployments.
- Electronics Assembly:Cleanroom-compatible, low-outgassing adhesive systems serve semiconductor packaging and display manufacturing in South Korea and Taiwan.
- Aerospace Manufacturing:Flame-retardant, smoke-density-rated constructions with documented traceability satisfy FAA and EASA certification requirements for wire harnessing.
- Consumer Goods Fabrication:Cost-optimized hot-melt and rubber-based products address high-volume converting with moderate performance thresholds.
- Construction:Weather-resistant acrylic and butyl rubber formulations seal building envelope penetrations and temporary electrical installations.
Electronics assembly commands premium pricing; telecommunications infrastructure is gaining share fastest.
Installation Type:
Duration of service and environmental exposure severity determine adhesive platform selection.
- Permanent Bonding:Structural acrylic and silicone systems with documented shear strength and thermal aging data support multi-decade service life in electrical infrastructure.
- Temporary Splicing:Repositionable hot-melt and low-tack rubber formulations enable process-stage joining in converting operations with clean removal requirements.
- High-Temperature Resistance:Silicone and polyimide constructions rated above 180°C address aerospace engine compartments and EV battery thermal management zones.
- Cold-Weather Use:Plasticized acrylic and synthetic rubber grades maintain tack and flexibility below -20°C for Arctic and high-altitude installations.
Permanent bonding dominates installed base; high-temperature resistance is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in East Asia and the US Gulf Coast anchors adhesive production economics for splicing tape manufacturers serving automotive electrification and telecommunications infrastructure buildouts.
United States
Automotive OEMs in Michigan and Ohio are specifying polyimide-silicone constructions for EV battery harnessing under NHTSA safety guidelines. OSHA hazard communication standards constrain solvent-based formulation options. Technical service teams embedded with Detroit-area manufacturers compress qualification cycles for high-voltage insulation materials.
Germany
REACH registration requirements through ECHA are disqualifying legacy acrylic chemistries from electrical insulation applications. Bavarian automotive suppliers and North Rhine-Westphalia industrial tape converters are transitioning to waterborne and hot-melt alternatives. KBA vehicle certification protocols mandate documented thermal aging data for battery pack splicing materials.
China
MIIT spectrum allocations for millimeter-wave 5G infrastructure are accelerating procurement of low-dielectric-loss acrylic grades. Guangdong and Jiangsu province manufacturers dominate PET film carrier production. GB standards compliance for wire and cable jointing applications creates qualification barriers for non-domestic suppliers.
Japan
METI industrial standards for high-temperature electrical insulation support silicone-based formulation demand from automotive and aerospace wire harnessing. Chubu region chemical manufacturers control specialty monomer supply for pressure-sensitive adhesives. Nagoya-area automotive tier-one suppliers consolidate procurement through direct material qualification programs.
India
PLI scheme incentives for automotive component manufacturing are creating captive demand for temperature-rated splicing materials with BIS certification. Tamil Nadu and Maharashtra wire harnessing clusters are localizing supply chains for EV production. CEA electrical safety regulations mandate dielectric testing for medium-voltage cable repair applications.
Splicing Tapes Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue hot-melt chemistry convergence and UV-curable hybrid platforms. The vendor base stratifies between integrated polymer manufacturers controlling upstream monomer supply and specialized converters dependent on merchant adhesive feedstocks. Three archetypes dominate: backward-integrated chemical conglomerates with captive resin production, regional converters with formulation expertise but limited raw material control, and niche specialists serving aerospace and medical certification requirements. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among diversified adhesive conglomerates, 3M Company and tesa SE exemplify integrated market positions through direct technical service deployment and backward integration into release liner substrates. Nitto Denko Corporation anchors the Asia-Pacific supply structure through polymer synthesis capabilities. These three entities represent distinct geographic anchoring strategies—North American distribution dominance, European regulatory compliance leadership, and East Asian feedstock proximity—without implying equivalent scale or segment focus across their operations.
| Leading Market Players |
|---|
| 3M Company |
| tesa SE |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Intertape Polymer Group |
| Shurtape Technologies |
| Scapa Group plc |
| Lintec Corporation |
| ORAFOL Europe GmbH |
| Others |
Cost & Logistics Intelligence
Backward integration into release liner substrates and captive silicone monomer production anchors pricing power for established adhesive conglomerates while exposing merchant-dependent converters to margin compression during feedstock volatility. Tesa SE's in-house glass cloth coating capabilities and Nitto Denko's polymer synthesis control create cost positions that regional formulators cannot replicate without capital-intensive capacity additions.
Pricing Analysis
Warranty-backed technical service bundling separates premium-tier suppliers from unbundled commodity sellers in this market. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-packaging tiers reflects differentiation by UL/VDE certification level and documented thermal aging data. Pricing pressure stems from Asian acrylic acid supply concentration and force majeure disruptions that compress naphtha-cracking margins. Automotive OEM procurement teams exhibit lowest price sensitivity due to warranty exposure, while industrial packaging buyers prioritize unit cost over performance documentation.
Supply Chain Analysis
Silicone monomer supply rests on Japanese and German specialty chemical producers with limited merchant market availability. Acrylic acid feedstock draws from South Korean and Chinese petrochemical complexes with naphtha-cracking exposure. Polyimide film carriers hinge on DuPont and Ube Industries capacity concentrated in the United States and Japan. Single-source vulnerability in aerospace-grade glass cloth substrates tightens lead times for qualified constructions. Distribution runs through direct technical service teams for automotive OEMs and industrial distributors for packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over silicone monomer synthesis and release liner substrate production determines qualification access and margin retention. Players without upstream leverage face displacement as automotive OEMs consolidate procurement under direct material programs.
For Market Incumbents: To counter hot-melt chemistry convergence from emerging adhesive specialists, incumbents should deepen captive supply of silane-terminated polyurethane resins and expand technical service embedding with Detroit and Stuttgart automotive clusters. Certification investment in simultaneous UL, VDE, and GB standard pre-qualification compresses time-to-revenue for new product variants.
For New Entrants and Emerging Players: India's PLI-scheme automotive component manufacturers represent an underserved buyer archetype seeking BIS-certified temperature-rated splicing materials with localized supply chains. New entrants should prioritize hot-melt and UV-curable hybrid platforms for high-speed converting applications in Japan and the United States, leveraging solvent-free processing to bypass REACH compliance barriers that disqualify legacy acrylic suppliers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified adhesive conglomerates seeking polymer synthesis capabilities and aerospace certification portfolios. Long-term viability favors targets with documented thermal aging databases and direct OEM qualification relationships rather than distributor-dependent revenue. The signal to watch is consolidation in automotive wire harnessing procurement as CATL and LG Energy Solution advance single-source splicing specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer Production | Nitto Denko's polymer synthesis capabilities control specialty formulations unavailable to merchant-dependent competitors. |
| Direct Technical Service Team Deployment | 3M's embedded Detroit-area engineers compress qualification cycles for high-voltage battery harnessing materials. |
| Simultaneous Multi-Jurisdiction Certification | Pre-qualified UL, VDE, and GB constructions reduce time-to-revenue by 14-18 months for new product variants. |
| Hot-Melt Chemistry Platform Development | Solvent-free processing addresses ECHA substance restrictions while opening temporary splicing applications in high-speed converting. |
| Regional Supply Chain Localization | Tamil Nadu and Maharashtra wire harnessing clusters create captive demand for BIS-certified materials under India's PLI scheme. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with adhesive formulation chemists, automotive Tier 1 procurement managers, wire harnessing plant engineers, and industrial tape distribution channel heads. Secondary sources included ECHA REACH registration databases, UL certification directories, MIIT spectrum allocation notices, and SEC 10-K disclosures from diversified adhesive conglomerates. Bottom-up demand modeling across end-use applications triangulated against top-down petrochemical feedstock flow analysis.
Segment-level granularity modeled adhesive chemistry, carrier film material, application environment, and end-user industry certification requirements across the projection horizon. CAGRs derived from volume-weighted average growth rates across modeled segments, calibrated to automotive electrification buildout schedules and 5G infrastructure deployment timelines. Industry-specific inputs included thermal cycling test data from battery pack manufacturers and dielectric loss specifications from fiber-to-the-antenna contractors.
Revisions become necessary when ECHA substance restriction list updates, MIIT spectrum reallocation decisions, or force majeure disruptions in Asian petrochemical feedstock supply materialize. Forecasts reflect assumptions about qualification timeline compression and procurement consolidation trends. A small set of named triggers—regulatory chemistry bans, automotive OEM platform standardization shifts, and aerospace certification requirement changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
PVC Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
UV Tapes Market
Tapes
Europe Packaging Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Shipping Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
ESD Tapes and Labels Market
Tapes
Global Printed Tape Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Spacer Tapes Market
Tapes
High Bond Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Moisture Barrier Tapes Market