
 Automotive Tapes Market | 2026-2036
Automotive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tapes Market Intelligence
The accelerating transition to electric vehicles is recalibrating demand for automotive tapes, shifting focus from traditional powertrain applications to battery pack assembly and thermal management. 3M leverages its material science portfolio to develop specialized tapes for EV battery applications. tesa SE competes on providing solutions for wire harnessing and surface protection in modern vehicle architectures, while Nitto Denko Corporation specializes in high-performance products for electronics and sensor mounting.
Automotive tapes are engineered adhesive systems designed to bond, seal, and protect components within a vehicle's demanding operational environment. These products often feature specific properties such as high shear strength, resistance to UV radiation, and vibration damping capabilities. Demand for double-sided foam tapes is expanding for exterior body attachments and trim. Within applications, tapes for electrical components and wire harnessing represent a high-growth area, driven by increasing vehicle electronic content.
Product formulations are governed by regulations like the EU's REACH directive, which restricts certain chemical substances. In the United States, EPA rules on volatile organic compounds (VOCs) influence adhesive chemistry, pushing for solvent-free solutions. China's GB standards impose strict performance and safety requirements for materials used in vehicles. Suppliers must now navigate diverging regional standards for material safety and end-of-life vehicle recyclability.
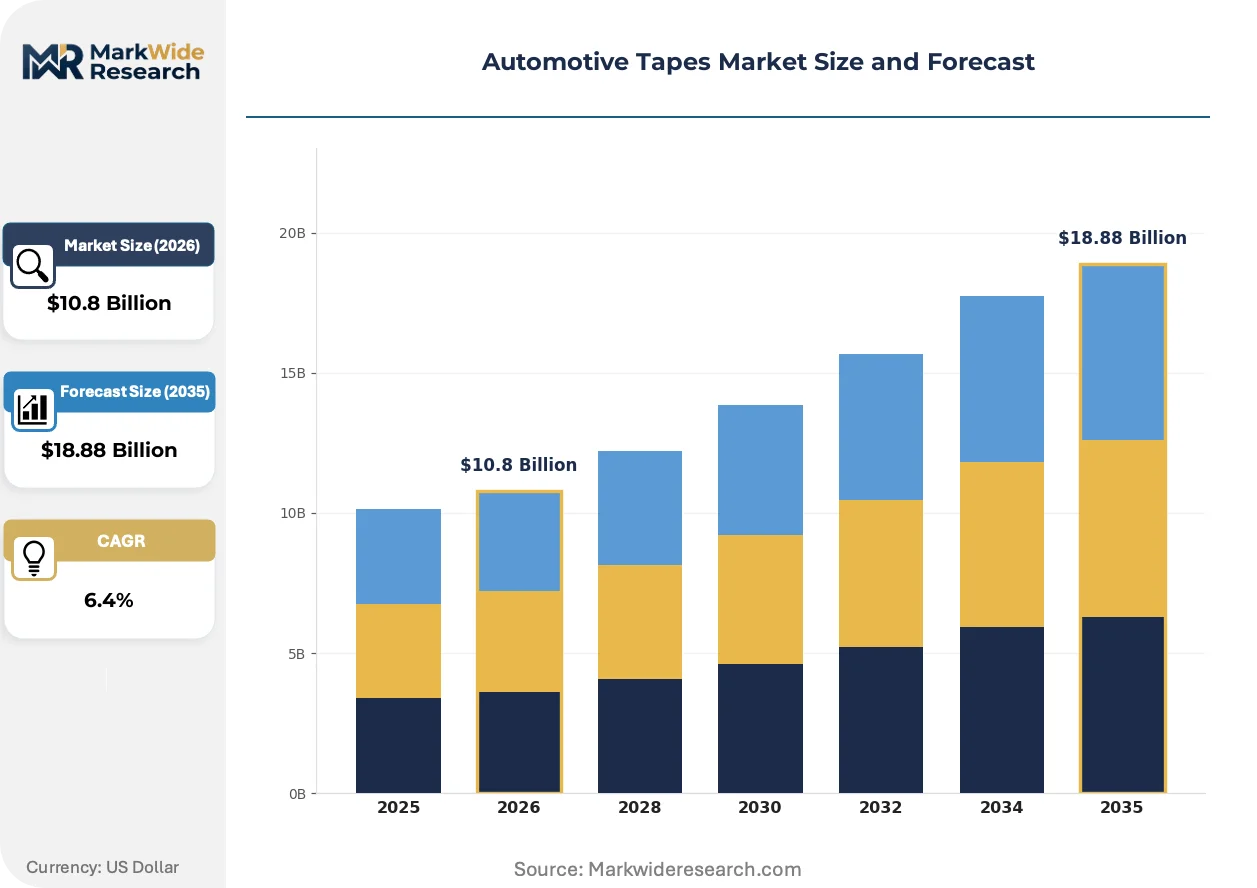
Market Dynamics
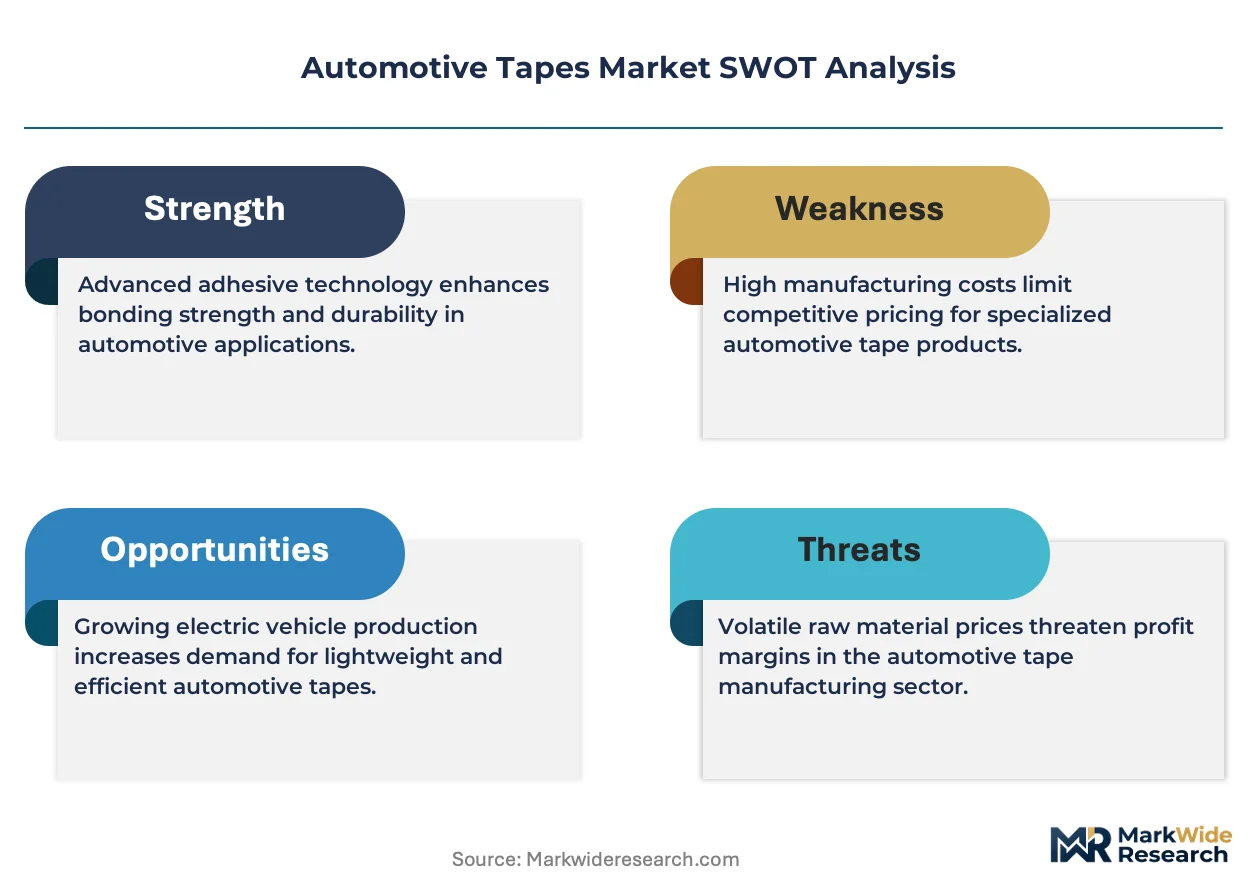
The automotive industry's pivot to electric vehicles serves as the central force reshaping the tape market. Demand is shifting from applications in internal combustion engines to complex requirements within battery systems, including cell-to-cell bonding, thermal interface materials, and electrical insulation, fundamentally altering product development priorities.
Growth Catalysts
- Regulatory Lightweighting Mandates:Regulations like the EU's CO2 emission performance standards for new cars compel automakers to reduce vehicle weight. This drives the substitution of heavier mechanical fasteners with lightweight adhesive bonding tapes for body panels, trim, and structural components.
- EV Battery Pack Complexity:The design of electric vehicle battery packs requires specialized tapes for thermal management, vibration damping, and electrical insulation. Demand for flame-retardant and dielectric tapes is expanding directly with EV production volumes.
- Manufacturing Concentration in China:China's dominance in electric vehicle manufacturing creates a highly concentrated zone of demand for automotive tapes. The country's aggressive EV targets and integrated supply chains pull in significant investment and product development from tape suppliers.
Market Restraints
- Raw Material Price Volatility:The market is sensitive to price fluctuations in key feedstocks like acrylic monomers, silicone polymers, and specialized release liners. Unpredictable input costs can compress supplier margins and create pricing instability for automotive OEMs.
- Diverging Chemical Regulations:Navigating disparate chemical safety regulations, such as the EU's REACH and the EPA's VOC rules in the United States, complicates global product formulation and distribution. This increases compliance costs and can delay market entry for new adhesive systems.
- Competition from Alternative Joining Methods:In certain high-stress structural applications, advanced welding techniques and mechanical fasteners remain the preferred joining methods due to long-standing engineering validation and perceived reliability, limiting tape penetration in those specific areas.
Strategic Opportunities
- Tapes for Autonomous Vehicle Sensors:The integration of LiDAR, radar, and camera systems in advanced driver-assistance systems (ADAS) and autonomous vehicles creates a need for specialized tapes. These products must offer secure mounting with properties like low outgassing and signal transparency.
- Sustainable and Recyclable Adhesives:There is a significant opportunity to develop tapes based on bio-based or recycled raw materials. Adhesives that facilitate easier component disassembly can help OEMs meet circular economy goals and end-of-life vehicle regulations.
- Penetration in Emerging Auto Hubs:Expanding local supply and technical support in growing automotive manufacturing centers, such as Mexico and Vietnam, presents an opportunity. These regions are attracting new OEM investments but may be underserved by high-performance tape suppliers.
Industry Challenges
- Complex Certification Pathways:Suppliers face long and costly validation processes to get products specified by automotive OEMs. Each tape must pass rigorous testing for performance under extreme temperatures, chemical exposure, and mechanical stress, specific to each carmaker's standards.
- Application Knowledge Gaps:Effective use of high-performance tapes requires specialized knowledge of surface preparation, application pressure, and curing conditions. A shortage of trained technicians on the assembly line can lead to bonding failures and quality control issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tapes Market |
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tapes, Single-Sided Tapes, Fabric Tapes, Foam Tapes End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Interior Trim, Exterior Body, Windows, Electrical Components Technology: Polymer-Based, Adhesive Bonding, Pressure-Sensitive, Thermal-Activated |
| Companies Covered | Avery Dennison Corporation, Lohmann GmbH & Co. KG, 3M, Lintec Corporation, Sika AG, Nitto Denko Corporation, Henkel AG & Co. KGaA, Gellytech, tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tapes Market Strategic Shifts & Innovations
Material science innovation is converging with application-specific engineering to address the dual pressures of vehicle electrification and regulatory-driven sustainability. Product development now focuses on creating multi-functional solutions that simplify complex vehicle architectures, particularly within battery and electronics systems.
Multi-functional tapes that combine several properties into a single product are gaining traction. Automotive OEMs and their tier-one suppliers are rapidly adopting these solutions for EV battery pack assembly. This technology is unifying previously separate components for structural bonding, thermal dissipation, and electrical insulation, which simplifies manufacturing and reduces the overall bill of materials.
The European Union's End-of-Life Vehicles (ELV) Directive is directly influencing adhesive chemistry. The directive's emphasis on material circularity and ease of disassembly is pushing manufacturers to engineer tapes that allow for debonding on demand. The segments most affected are interior trim, display modules, and battery enclosures, where component recovery for recycling or reuse is a primary concern.
Automotive OEMs are altering their procurement models, moving toward co-development partnerships with tape suppliers early in the vehicle design cycle. This collaborative approach replaces a transactional purchasing process, embedding material science expertise to solve challenges like lightweighting or thermal management from the outset. This trend is most visible within EV startups and the advanced engineering divisions of established automakers in Germany and the United States.
Automotive Tapes Market Segmentation
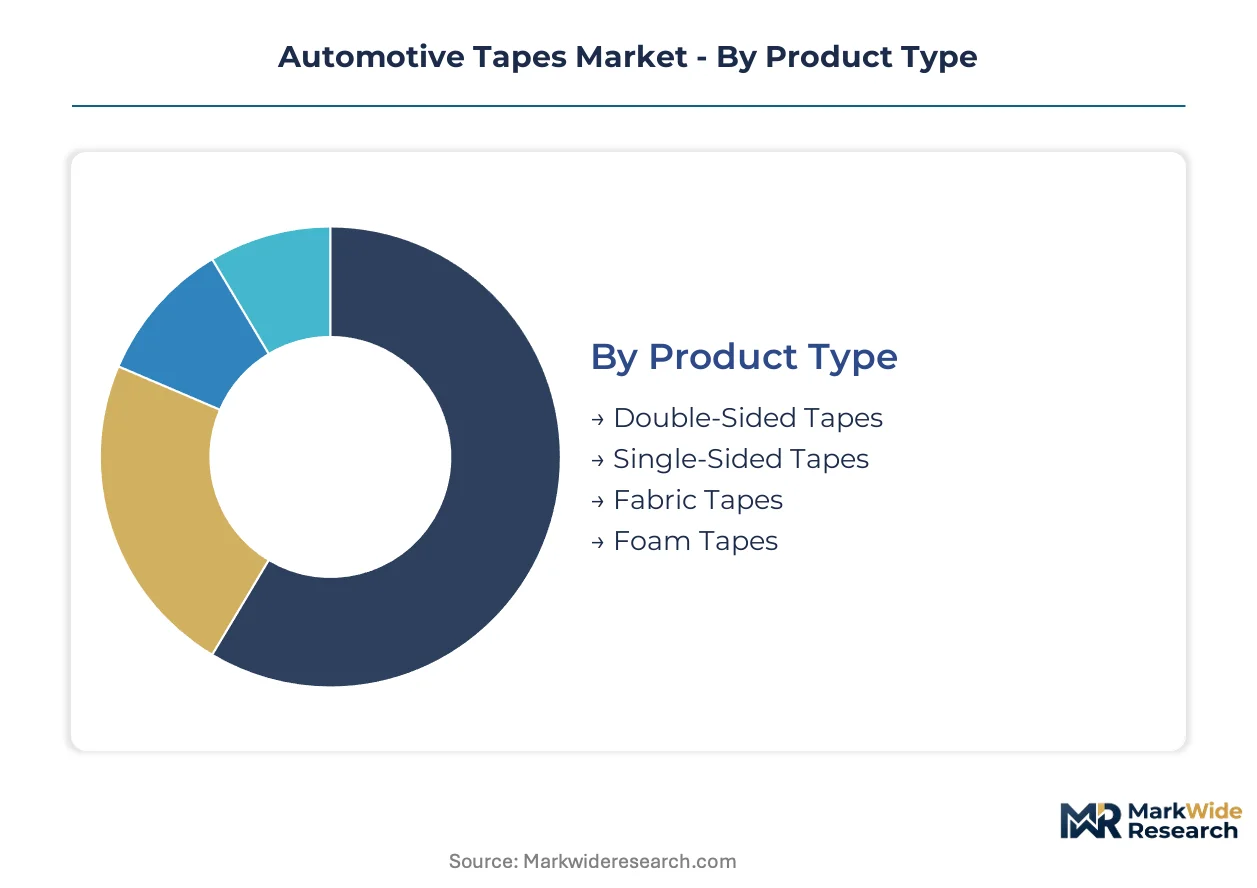
The automotive tapes market segmentation reveals distinct product functionalities and application areas crucial for vehicle manufacturing. Understanding these segments helps identify where material science advancements are most impactful and where demand for specialized adhesive solutions is intensifying. This breakdown offers insights into the evolving landscape driven by electrification and lightweighting mandates.
Product Type:
The product type segmentation differentiates tapes based on their structural design and intended integration depth within vehicle assemblies, ranging from standalone sealing elements to embedded bonding solutions.
- Double-Sided Tapes:These products feature adhesive on both sides, often with a carrier material, enabling strong, permanent bonds between two surfaces. Demand concentrates in electric vehicle battery systems for cell-to-cell bonding and module assembly, driven by thermal management requirements.
- Foam Tapes:Comprising a foam core coated with adhesive, these tapes offer conformability, gap-filling, and vibration damping properties. The market sees significant demand for exterior body attachments and trim, supporting lightweighting initiatives and aesthetic integration.
- Single-Sided Tapes:These tapes have adhesive on one surface, primarily used for sealing, masking, protection, or bundling applications within vehicle interiors.
- Fabric Tapes:Constructed with a textile backing, fabric tapes provide high tensile strength and abrasion resistance, commonly employed for wire harnessing and cable management in complex vehicle architectures.
Volume placements concentrate in Double-Sided Tapes; the faster expansion belongs to Foam Tapes.
End User:
End user segmentation reflects the distinct procurement channels and technical requirements across the automotive supply chain, from initial vehicle design to post-production services.
- OEMs:Original Equipment Manufacturers directly integrate tapes into new vehicle production lines, requiring extensive validation and co-development for specific applications. Their procurement strategies increasingly favor early engagement with tape suppliers for advanced material solutions.
- Tier-1 Suppliers:These large component manufacturers supply sub-assemblies to OEMs, driving demand for tapes in their own production processes, particularly for complex modules like battery packs and ADAS systems. Their focus includes performance consistency and supply chain reliability.
- Aftermarket Providers:This segment includes businesses supplying tapes for vehicle repair, maintenance, and customization post-sale, emphasizing ease of application and broad compatibility.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, using tapes for various bonding, sealing, and protective applications before delivery to dealerships.
The largest market share is held by OEMs, while Tier-1 Suppliers exhibit the most dynamic growth.
Application:
The application segmentation categorizes automotive tapes based on their specific functional role within different vehicle areas, often correlating with varying environmental demands and performance criteria.
- Electrical Components:Tapes in this segment provide insulation, bundling, and protection for wiring harnesses, sensors, and electronic control units, crucial for modern vehicle electronic content. This area is experiencing high growth due to increasing electrification and ADAS integration.
- Exterior Body:Tapes for exterior body applications are used for bonding trim, emblems, and body panels, demanding high shear strength, weather resistance, and UV stability. Lightweighting mandates drive the substitution of mechanical fasteners in this segment.
- Interior Trim:Tapes are utilized for attaching decorative elements, headliners, and seating components within the vehicle cabin, prioritizing aesthetic integration and low VOC emissions.
- Windows:This application involves tapes for bonding windshields, side windows, and sunroofs, requiring strong adhesion, sealing properties, and resistance to environmental factors.
The dominant application remains Interior Trim, with Electrical Components showing the most significant recent expansion.
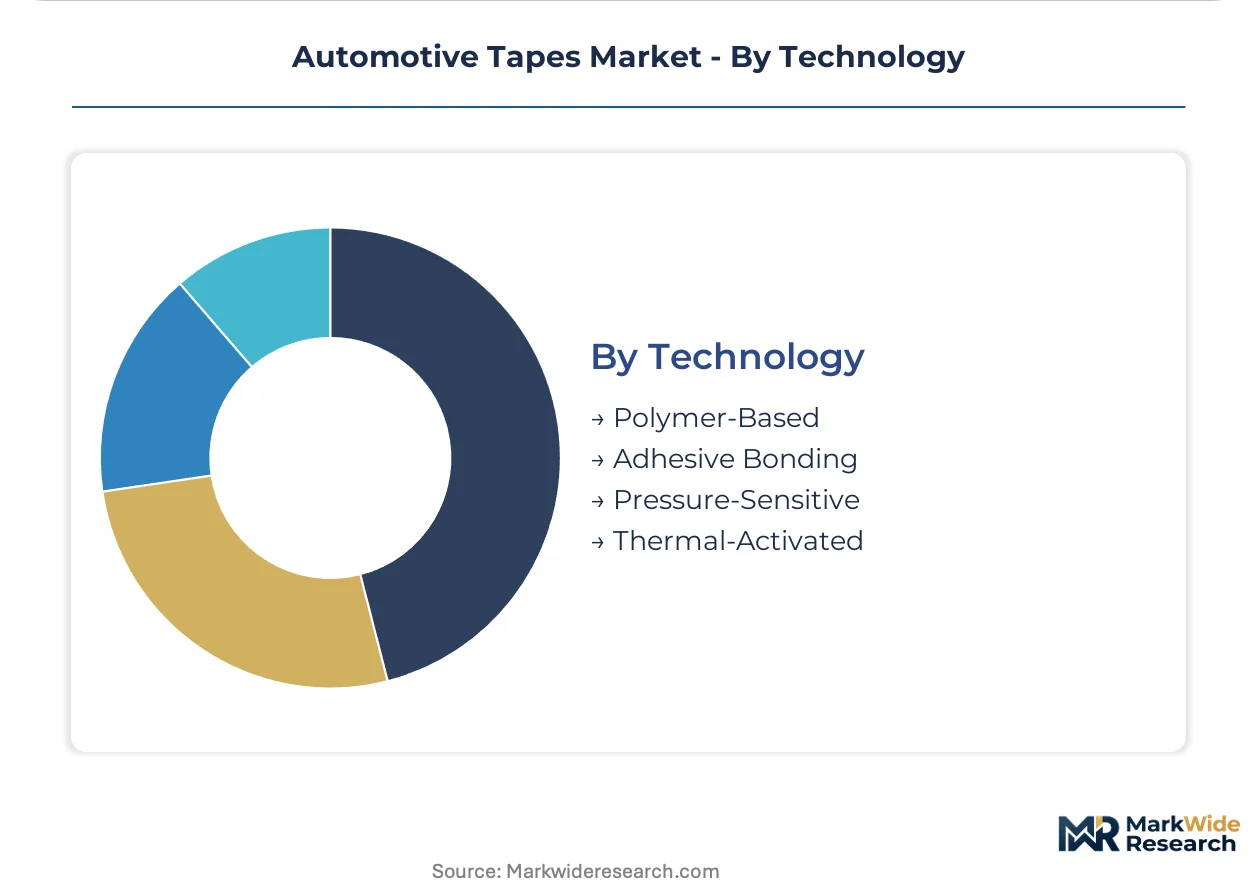
Technology:
The technology segmentation delineates tapes based on their underlying adhesive chemistry and bonding mechanisms, impacting performance characteristics and suitability for diverse automotive environments.
- Adhesive Bonding:This technology encompasses a wide range of chemical formulations designed to create strong, durable bonds between substrates, often replacing traditional mechanical fasteners. It is central to vehicle lightweighting strategies and structural integrity in modern automotive designs.
- Pressure-Sensitive:These tapes form a bond when pressure is applied, requiring no solvent, water, or heat activation, offering ease of application and immediate adhesion. Demand is strong for assembly line efficiency and versatile component attachment.
- Polymer-Based:This category refers to tapes where the adhesive or carrier material is derived from various polymer chemistries, providing specific properties like flexibility, temperature resistance, or dielectric strength.
- Thermal-Activated:These adhesives require heat to initiate or strengthen the bonding process, typically used for applications demanding high bond strength and resistance to extreme conditions.
Adhesive Bonding solutions comprise the largest volume, and Pressure-Sensitive technologies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's aggressive EV targets and integrated supply chains within its Free Trade Zones create a highly concentrated zone of demand for automotive tapes. These zones attract significant investment and product development from tape suppliers. This focus reconfigures regional demand patterns for specialized adhesive solutions.
China
Demand for automotive tapes in China is driven by the country's dominance in electric vehicle manufacturing and battery production. China's GB standards impose strict performance and safety requirements for materials used in vehicles, particularly for EV components. Production clusters in the Yangtze River Delta, like Shanghai, see intense activity for advanced battery pack assembly tapes.
Germany
Germany's automotive industry, pivoting towards premium electric vehicles, creates strong demand for high-performance tapes in thermal management and lightweighting. The EU's CO2 emission performance standards compel German automakers to reduce vehicle weight, favoring adhesive bonding. Automotive R&D centers in Stuttgart and Munich are developing next-generation tape solutions for advanced driver-assistance systems.
United States
The United States' growing electric vehicle production, particularly for trucks and SUVs, fuels demand for robust tapes in battery systems and exterior applications. EPA rules on volatile organic compounds influence adhesive chemistry, pushing for solvent-free solutions in manufacturing. Michigan's automotive corridor, including Detroit, is seeing increased investment in tape solutions for EV battery module production.
Mexico
Mexico's expanding automotive manufacturing base, attracting significant OEM investments, drives demand for automotive tapes in assembly operations. The country's favorable trade agreements, such as USMCA, support a robust supply chain for vehicle components. Production facilities in Nuevo León and Bajío Region utilize tapes for wire harnessing and body panel attachment in export-oriented vehicles.
India
India's emerging EV market and ambitious localization initiatives are stimulating demand for automotive tapes in battery insulation and structural bonding. The PLI scheme for automotive components encourages domestic manufacturing of advanced materials. Chennai and Pune, major automotive hubs, are witnessing increased adoption of tapes for vehicle lightweighting and electronic content.
Automotive Tapes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the automotive tapes market. The industry exhibits a tiered structure, with global chemical conglomerates occupying the premium end and regional players competing on cost and localized service. Strategic archetypes include diversified material science giants and specialized adhesive solution providers, each targeting distinct value propositions. Companies pursue strategic partnerships, portfolio diversification, and geographic expansion to capture new opportunities in electric vehicle applications and emerging automotive hubs.
Within the diversified material science giant archetype, 3M and Henkel AG & Co. KGaA exemplify companies leveraging broad portfolios across multiple industries. Nitto Denko Corporation, a Japanese entity, also sits within this tier, focusing on high-performance products for electronics and sensor mounting. tesa SE, a German-based company, occupies a strong position as a specialized adhesive solution provider with a focus on automotive applications. These companies anchor innovation in areas like thermal management and lightweighting, particularly for electric vehicle platforms, and influence global material standards.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Lohmann GmbH & Co. KG |
| 3M |
| Lintec Corporation |
| Sika AG |
| Nitto Denko Corporation |
| Henkel AG & Co. KGaA |
| Gellytech |
| tesa SE |
| Others |
Cost & Logistics Intelligence
Electric vehicle battery system integration, a significant production-method transition, simultaneously reshapes cost economics and supply concentration for automotive tapes. This shift demands specialized materials, influencing both pricing power and the geographic footprint of key suppliers.
Pricing Analysis
Lead times for highly specialized automotive tapes, particularly those requiring OEM validation, command a premium, while standard product inventory may see discounting. The dominant pricing model remains contract-based long-term offtake, driven by the extensive certification processes required for vehicle components. Price differentiation stems from the quality grade of adhesive formulations, specific OEM certification levels, and the customization required for unique application areas like EV battery thermal management. Pricing pressure on raw materials, such as acrylic monomers and silicone polymers, creates upward cost pressures for suppliers. Aftermarket providers typically exhibit the highest price sensitivity, whereas OEMs, involved in co-development, demonstrate lower sensitivity for validated solutions.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke logistics patterns characterize the automotive tape supply chain, ensuring timely delivery to manufacturing clusters. Geographic supply concentrates in China, driven by its EV production dominance, alongside Germany for premium automotive applications and the United States for electric trucks. The industry draws from raw material dependencies on acrylic monomers, silicone polymers, and specialized release liners. A structural supply chain risk involves raw material price volatility, which can impact production costs and supplier margins. Distribution runs primarily direct-to-OEM and Tier-1 suppliers, supported by localized technical service centers for application assistance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive tapes market is navigating a technology-transition phase, with advanced adhesive solutions for electric vehicles replacing traditional applications in internal combustion engine systems.
For Market Incumbents:Lock in long-term co-development agreements with major automotive OEMs, especially for next-generation EV platforms, to secure future demand. Invest heavily in R&D for multi-functional tapes that combine structural bonding, thermal management, and electrical insulation, countering the threat from alternative joining methods. Pursue strategic backward integration into key raw material production to mitigate supply chain volatility. Emphasize global certification investment to meet diverging regional regulations like EU REACH and China's GB standards.
For New Entrants and Emerging Players:Launch via specialized technical support and application engineering services, targeting complex EV battery assembly in underserved emerging auto hubs. Focus on white-space opportunities such as specialized tapes for autonomous vehicle sensors requiring low outgassing properties or bio-based adhesives for circular economy initiatives. The most penetrable segment for new entrants involves niche applications within Tier-1 suppliers seeking specific performance enhancements for sub-assemblies. Offer customized solutions that simplify manufacturing processes for specific EV components.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized adhesive solution providers with strong intellectual property in high-growth EV applications or sustainable materials. The long-term viability of the automotive tapes market remains strong over the next 5-10 years, driven by vehicle electrification and lightweighting mandates. Target acquisition archetypes include companies with advanced material science capabilities in thermal interface materials or flame-retardant tapes. A key signal to watch is the increasing adoption of co-development partnerships between OEMs and tape suppliers, indicating a shift towards integrated material solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | This reduces environmental impact and aligns with global sustainability regulations for adhesive production. |
| Joint Venture for EV Integration | This accelerates development of specialized tapes for complex electric vehicle battery systems. |
| Product Launch: Multi-functional Tapes | This simplifies vehicle assembly processes and reduces the overall bill of materials for OEMs. |
| Geographic Manufacturing Footprint Expansion | This enhances local supply capabilities for automotive production centers like China and Mexico. |
| Platform Standardization with OEMs | This streamlines tape specifications across global vehicle platforms, ensuring consistent performance. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational market understanding. This was validated through primary interviews with industry stakeholders, including OEM procurement managers, Tier-1 engineering leads, material scientists, and supply chain directors. Secondary sources comprised industry reports, company annual filings, regulatory databases such as REACH and EPA, and automotive production statistics. The analysis employed both bottom-up and top-down triangulation to ensure comprehensive data coverage.
Market granularity at the product type, end user, application, technology, and regional EV production volumes was modeled across the analysis window. The analytical framework integrated historical performance with projected trends, factoring in technological advancements and regulatory shifts. Compound annual growth rates were derived through rigorous regression analysis and expert consensus. Industry-specific forecast inputs included electric vehicle production targets and lightweighting material adoption rates.
Raw material price shocks, sudden regulatory shifts, and rapid EV technology changes are the dominant revision risks for the automotive tapes market. Forecasts reflect assumptions documented within the study's scope and parameters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Strapping Tapes Market
Tapes
Heat Sealing Tape Market
Tapes
Lacing Tape Market
Tapes
Paper Masking Tapes Market
Tapes
Tissue Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Shipping Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Umbilical Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Thermal Transfer Tapes Market
Tapes
Correction Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
Industrial Tapes Market
Tapes
Nano Tapes Market
Tapes
Filament Tapes Market