
 Toilet Roll Converting Lines Market | 2026-2036
Toilet Roll Converting Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Roll Converting Lines Market Analytics
Multi-source equipment procurement is consolidating among large tissue producers seeking standardized line configurations. Fabio Perini leverages its Italian engineering heritage to dominate high-speed rewinding segments. Bretting Manufacturing anchors North American supply through specialized folding and packaging integration. PCMC competes on servo-control retrofit expertise for legacy mechanical lines.
Toilet roll converting lines constitute integrated machinery systems that transform parent tissue jumbo reels into finished consumer rolls through unwinding, perforating, rewinding, cutting, and packaging stages, typically operating at speeds exceeding 600 meters per minute. These systems serve consumer goods manufacturers supplying retail, commercial, and institutional hygiene channels. Rewinding machines command the largest installed base due to their centrality in every production line, while servo control technology captures expanding share as converters replace mechanical drives for precision and changeover speed. Automation solutions including robotic packaging and vision-based inspection represent the fastest-growing technology segment where margin pools deepen from software and service attach rates.
CE marking under the EU Machinery Directive governs equipment safety and electromagnetic compatibility for European installations, while China's SAMR enforces GB standards on electrical safety and energy consumption ratings for domestic and exported machinery. The US OSHA machinery guarding standards influence line design for American tissue mills, particularly regarding roll-handling automation. Stakeholders must weigh total cost of ownership against regulatory compliance breadth when selecting suppliers for multi-territory deployments.
Market Dynamics
GB standards issued by China's SAMR are accelerating equipment replacement cycles as hygiene manufacturers face mandatory energy efficiency and electrical safety upgrades, compressing capital deployment timelines across Southeast Asian manufacturing clusters.
Growth Catalysts
- Private-label retail expansion:Supermarket chains across Indonesia, Vietnam, and Thailand are demanding automated converting capacity to supply house-brand tissue products, pulling investment toward high-speed rewinding systems.
- Servo-control retrofit mandates:Mechanical drive replacement is accelerating as converters pursue precision tolerances and rapid changeover capabilities to serve just-in-time retail replenishment.
- CE marking harmonization:The EU Machinery Directive's safety and electromagnetic compatibility requirements are enabling European equipment suppliers to access cross-border tender processes in emerging markets.
Market Restraints
- Steel and aluminum input volatility:Frame and roller fabrication costs fluctuate with commodity markets, squeezing margins for equipment builders with fixed-price contract exposure.
- Italian engineering concentration:High-speed rewinding technology remains concentrated among a narrow supplier base in Northern Italy, creating single-source risk for tier-one tissue producers.
- Mechanical-to-servo transition friction:Legacy maintenance workforces lack electrical troubleshooting competency, slowing adoption curves in markets with limited technical training infrastructure.
Strategic Opportunities
- Robotic packaging integration:Vision-guided palletizing and case-packing systems represent attach-rate expansion for automation vendors serving tissue converters with labor-cost pressures.
- India's PLI scheme alignment:Machinery imports for domestic tissue manufacturing qualify under production-linked incentive frameworks, attracting greenfield facility investment.
- Servo-mechanical convergence:Hybrid drive architectures combining mechanical reliability with electronic precision are opening mid-market segments previously priced out of full servo configurations.
Industry Challenges
- Commissioning engineer scarcity:Field installation and line optimization expertise is concentrated among aging specialists, constraining deployment velocity for multi-line orders.
- OSHA guarding retrofit complexity:North American tissue mills face downtime-intensive modifications to meet roll-handling automation standards on legacy installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Roll Converting Lines Market |
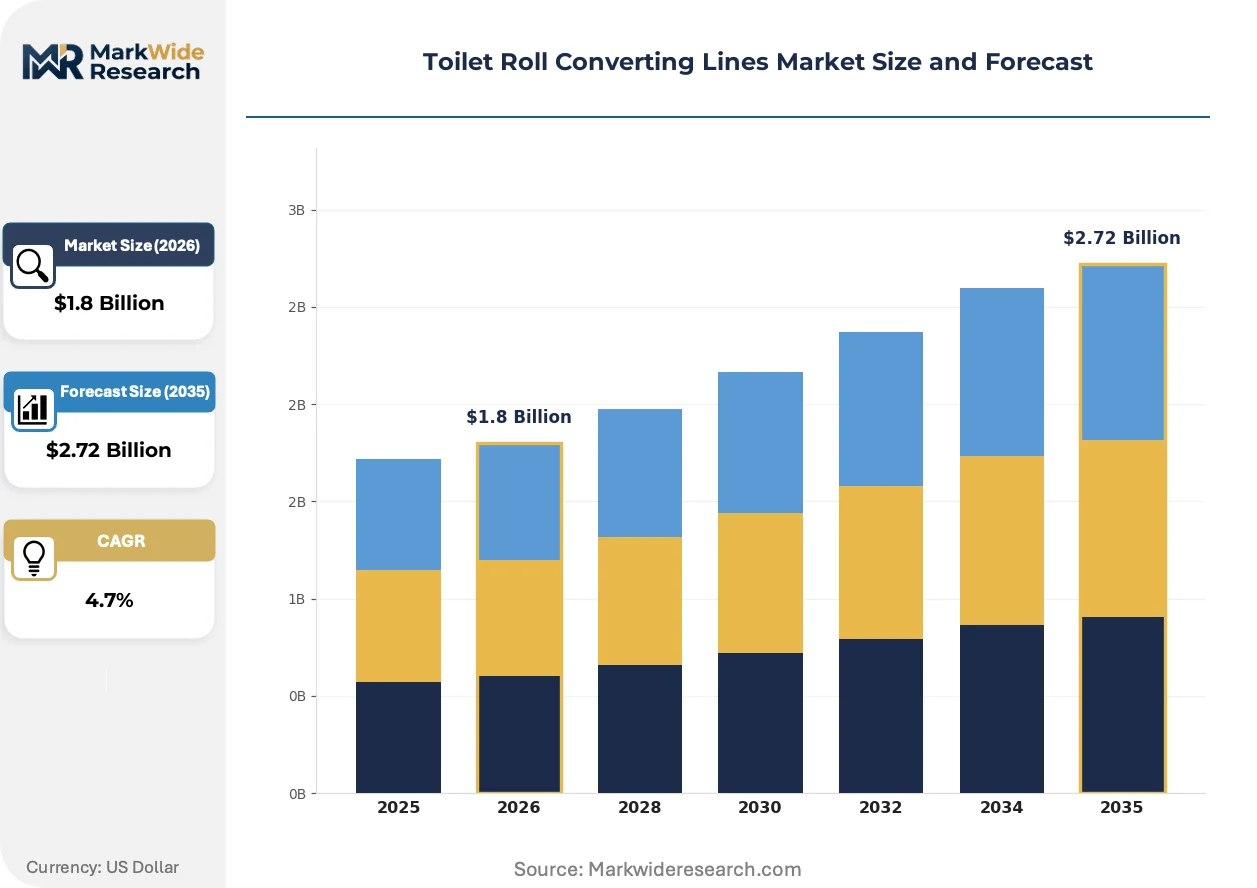
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rewinding Machines, Packaging Machines, Cutting Machines, Inspecting Equipment Technology: Servo Control, Automation Solutions, Mechanical Systems, Electrical Systems End User: Manufacturers, Distributors, Retailers, Exporters Application: Industrial Use, Commercial Use, Household Use, Institutional Use |
| Companies Covered | Fabio Perini, Bretting Manufacturing, PCMC, BaoSuo Paper Machinery, A.Celli Group, Gambini S.p.A, Futura S.p.A., Kawanoe Zoki, Mtorres, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Roll Converting Lines Market Evolving Landscape
Digital thread technologies are threading through converting operations, compressing the gap between parent reel tracking and finished goods serialization while reshaping how equipment suppliers monetize software and service layers.
Machine vision inspection systems are absorbing quality-control functions previously executed by manual sampling protocols. Tier-one tissue producers in Germany and the Netherlands are deploying camera arrays at slitters and rewinders to detect perforation defects and core alignment errors in real time. This technology is absorbing margin pools from offline laboratory testing while enabling 100% lot traceability demanded by retail audit requirements.
REACH substance restrictions on lubricants and hydraulic fluids are forcing formulation changes in converting line maintenance protocols. Equipment suppliers must certify component compatibility with bio-based alternatives, adding documentation burden but creating differentiation for compliant system integrators. European installations face the tightest compliance windows, with OEMs pre-qualifying fluid specifications to accelerate customer acceptance testing.
After-sales service unbundling is altering how converters procure maintenance coverage. Large tissue groups in Brazil and Mexico are negotiating performance-based contracts with uptime guarantees rather than traditional time-and-materials arrangements. This shift transfers operational risk to equipment vendors while concentrating service revenue among suppliers with remote diagnostics capability and regional parts depots.
Toilet Roll Converting Lines Market Segmentation
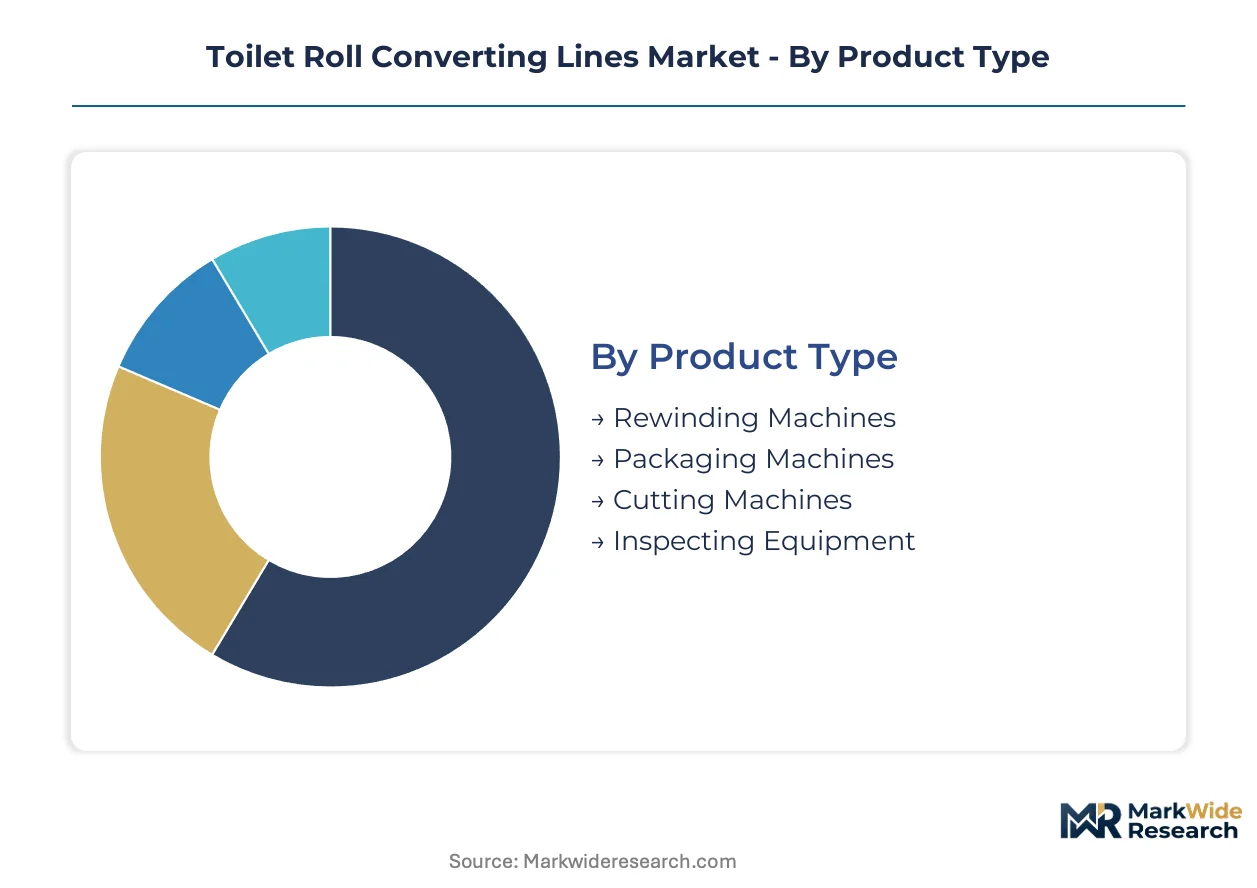
Toilet roll converting lines fragment across four structural dimensions that determine procurement priorities. Equipment buyers weight capital recovery timelines against throughput requirements when mapping segments to facility expansion plans.
Product Type:
Capital intensity peaks with integrated lines combining multiple process stages, while standalone units attract modular upgrade strategies.
- Rewinding Machines:These systems form the core converting stage, transforming parent jumbo reels into perforated logs through precision tension control and core insertion. Demand clusters in Southeast Asian manufacturing zones where greenfield tissue mills seek 600+ meter-per-minute throughput to serve retail private-label contracts.
- Packaging Machines:Robotic case-packing and palletizing units command premium investment but deliver labor substitution economics. Brazilian and Mexican tissue groups are driving performance-based service contracts with uptime guarantees, transferring operational risk to automation vendors.
- Cutting Machines:Slitting and log-cutting equipment bridges rewinding and finished goods handling.
- Inspecting Equipment:Vision-based quality systems detect perforation defects and core alignment errors in real time.
Rewinding machines absorb the bulk of installed capacity; packaging machines are expanding most quickly.
Technology:
Technology selection determines maintenance workforce requirements and changeover flexibility across multi-SKU operations.
- Servo Control:Electronic drive systems replace mechanical linkages with precision motor control, enabling rapid format changes and tighter tolerances. Germany and Netherlands-based tier-one producers deploy these retrofits to meet just-in-time retail replenishment demands.
- Automation Solutions:Robotic packaging and vision-based inspection represent the steepest expansion trajectory as margin pools deepen from software and service attach rates.
- Mechanical Systems:Legacy drive architectures persist where electrical troubleshooting competency remains scarce.
- Electrical Systems:Power distribution and motor control infrastructure underpins all electronic upgrades.
Servo control dominates new line specifications; automation solutions are gaining share fastest.
End User:
End-user category shapes procurement scale and service contract structures.
- Manufacturers:Hygiene product producers across Indonesia, Vietnam, and Thailand anchor equipment demand through automated capacity expansion for house-brand tissue programs.
- Distributors:Regional supply chain intermediaries seek flexible line configurations.
- Retailers:Supermarket chains with captive private-label manufacturing invest directly in converting assets.
- Exporters:Cross-border tissue traders prioritize standardized line configurations for multi-territory compliance.
Manufacturers command the dominant share of order books; exporters are scaling fastest.
Application:
Application context dictates line speed, packaging format, and regulatory compliance breadth.
- Industrial Use:High-volume tissue mills serving retail channels require CE-marked equipment meeting EU Machinery Directive safety and electromagnetic compatibility standards.
- Commercial Use:Away-from-home tissue producers target institutional procurement contracts.
- Household Use:Consumer roll specifications dominate volume throughput planning.
- Institutional Use:Healthcare and hospitality channels demand specialized core sizes and packaging formats.
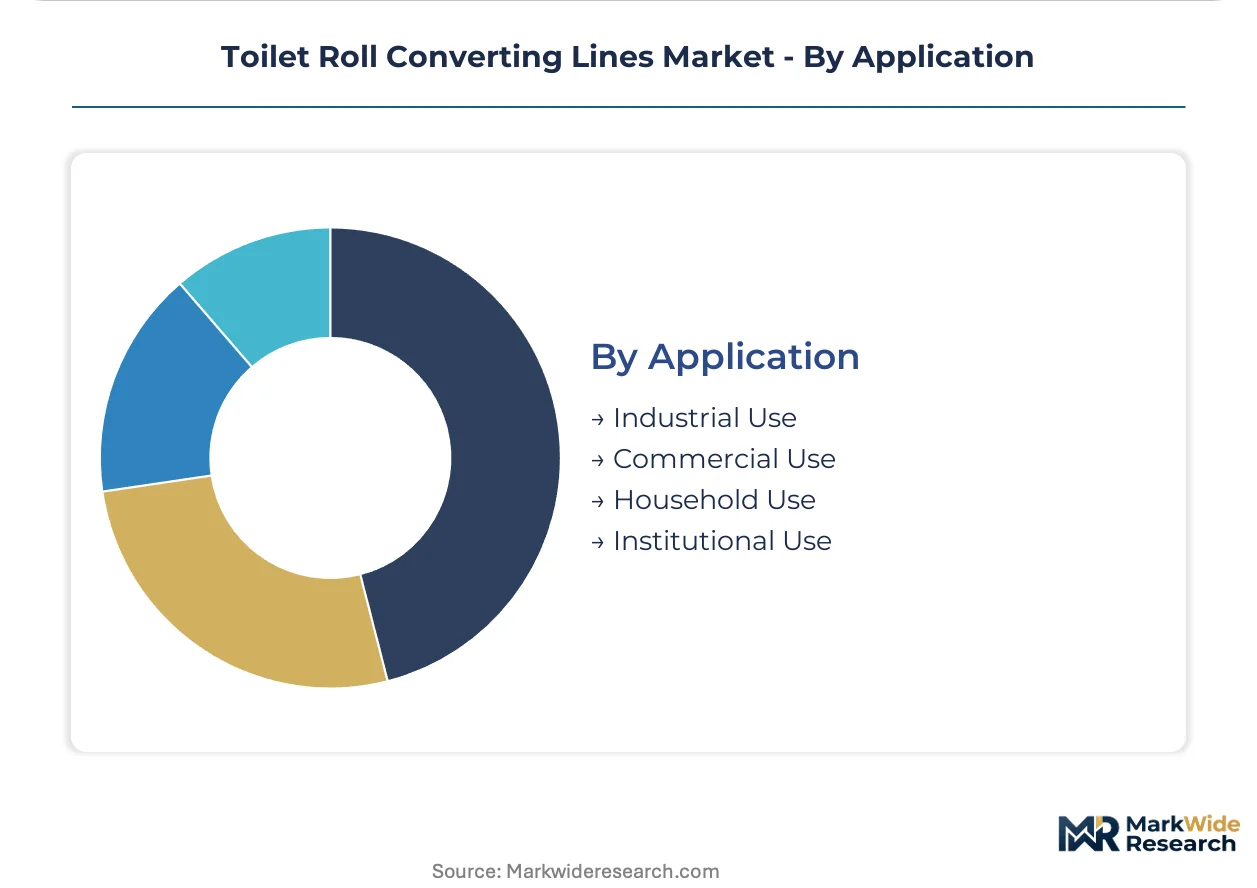
Industrial use captures the majority of capital deployment; institutional use is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parent tissue jumbo reel supply from Indonesian pulp mills anchors Southeast Asian converting capacity expansion. Chinese machinery exports under GB standards certification accelerate replacement cycles in Vietnam and Thailand. Italian engineering clusters in Lucca supply high-speed rewinding systems to tissue producers worldwide.
China
Domestic tissue manufacturers in Fujian and Guangdong provinces deploy automated converting lines to capture private-label contracts from supermarket chains. SAMR's GB standards enforcement mandates energy efficiency ratings and electrical safety upgrades, compressing capital equipment replacement timelines. The Yangtze River Delta manufacturing corridor concentrates greenfield investments where export proximity and port infrastructure support cross-border shipment logistics.
Indonesia
Retail private-label expansion by supermarket chains in Jakarta and Surabaya pulls investment toward high-speed rewinding capacity. The national standards body enforces machinery safety protocols aligned with ASEAN harmonization frameworks. Batam and Bintan industrial zones attract equipment procurement from tissue producers seeking duty-advantaged export positioning to Singapore and Malaysia.
Vietnam
Just-in-time retail replenishment requirements from domestic supermarket networks accelerate servo-control retrofits on legacy mechanical lines. The Ministry of Science and Technology implements energy labeling schemes for imported industrial machinery. Ho Chi Minh City and Binh Duong Province manufacturing clusters concentrate converting capacity where labor costs and ASEAN trade agreement access intersect.
Thailand
House-brand tissue programs by Bangkok-based retail conglomerates drive demand for integrated packaging and palletizing automation. The Industrial Standards Institute mandates CE-equivalent safety certifications for European-origin equipment imports. Eastern Economic Corridor zones in Chonburi and Rayong host expanding converting facilities serving both domestic consumption and regional export markets.
Italy
Engineering heritage in Lucca's tissue machinery district sustains dominance in high-speed rewinding technology for global export. CE marking under the EU Machinery Directive enables Italian suppliers to access cross-border tender processes in emerging Asian markets. Northern Italian equipment builders concentrate servo-control development and field commissioning expertise that tier-one tissue producers rely upon for precision tolerance requirements.
Toilet Roll Converting Lines Market Competitive Landscape
Global majors compete with regional champions across equipment standardization and service reach. The vendor base organizes around three tiers: Italian engineering houses with heritage positioning, North American integrators specializing in packaging automation, and Asian fabricators competing on capital cost recovery timelines. Two strategic archetypes dominate competitive behavior: technology licensors monetizing servo-control intellectual property, and system integrators bundling robotic packaging with uptime-guaranteed service contracts. Geographic expansion through distribution partnerships and vertical integration into after-sales service represent the dominant competitive moves.
Among Italian engineering specialists, Fabio Perini S.p.A., Gambini S.p.A., and Futura S.p.A. occupy positions exemplifying the heritage-driven archetype where Lucca-based manufacturing tradition translates into high-speed rewinding market presence. Bretting Manufacturing Co., Inc. represents North American positioning focused on folding and packaging integration capabilities. PCMC anchors the servo-control retrofit specialization segment where legacy mechanical line upgrades generate recurring service revenue. BaoSuo Paper Machinery Co., Ltd. sits within the Asian fabricator tier competing on equipment cost structures for emerging market capital deployment. A.Celli Group exemplifies diversified machinery portfolio positioning spanning tissue and nonwoven converting applications.
| Leading Market Players |
|---|
| Fabio Perini |
| Bretting Manufacturing |
| PCMC |
| BaoSuo Paper Machinery |
| A.Celli Group |
| Gambini S.p.A |
| Futura S.p.A. |
| Kawanoe Zoki |
| Mtorres |
| Others |
Value Network & Pricing Analysis
Family-owned Italian engineering specialists in Lucca's tissue machinery district anchor supply-side discipline through generational ownership structures that resist price erosion while maintaining captive control over servo-control intellectual property and field commissioning expertise.
Pricing Analysis
Warranty and service bundling unbundling is reshaping how converters procure maintenance coverage, with Brazilian and Mexican tissue groups negotiating performance-based contracts with uptime guarantees rather than traditional time-and-materials arrangements. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European systems with full servo configurations from mid-market hybrid architectures and basic mechanical lines. Pricing pressure stems from steel and aluminum input volatility squeezing margins for equipment builders with fixed-price contract exposure. Emerging market manufacturers exhibit highest price sensitivity due to compressed capital recovery timelines, while tier-one European tissue producers prioritize precision tolerance and changeover speed over acquisition cost.
Supply Chain Analysis
Commissioning engineer scarcity in Northern Italy and aging specialist concentrations across Lucca's engineering clusters constrain deployment velocity for multi-line orders and inflate field service premiums. Equipment fabrication draws from Chinese steel rolling mills for frame components, German precision motor suppliers for servo drives, and Italian machining centers for high-speed rewinding assemblies. Single-source vulnerability concentrates in Northern Italy's narrow supplier base for high-speed rewinding technology. Distribution runs through direct OEM relationships for tier-one tissue producers, regional distribution partnerships for mid-market buyers, and machinery import agents serving emerging Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's SAMR enforcement of GB standards on energy efficiency and electrical safety creates a barrier-to-entry moat for equipment suppliers with pre-certified component portfolios and documentation capabilities.
For Market Incumbents: Hedge against Italian engineering concentration risk by cultivating secondary servo-control development partnerships in Germany or Japan, while accelerating backward integration into robotic packaging modules to capture attach-rate expansion from automation demand. CE marking harmonization investments defend position against emerging Asian fabricators competing on capital cost recovery timelines. For New Entrants and Emerging Players: Regional distribution partners in Vietnam and Indonesia offer the most penetrable channel for mid-market hybrid drive architectures, where legacy mechanical line retrofits outpace greenfield servo deployments. Target just-in-time retail replenishment requirements from domestic supermarket networks as the specific go-to-market angle, emphasizing rapid format change capabilities over maximum throughput specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor servo-control retrofit specialists with established regional parts depot networks in Southeast Asia, where SAMR-mandated replacement cycles compress capital deployment timelines. Long-term viability hinges on software and service revenue attach rates rather than equipment shipment volumes. Watch commissioning engineer availability as the inflection indicator for deployment velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Mechanical Convergence Development | Hybrid architectures open mid-market segments previously priced out of full servo configurations in Vietnam and Thailand. |
| Robotic Packaging Integration | Vision-guided palletizing systems transfer operational risk to vendors through performance-based contracts with Brazilian tissue groups. |
| GB Standards Pre-Certification | SAMR compliance documentation accelerates customer acceptance testing for equipment exports to Chinese domestic manufacturers. |
| Regional Parts Depot Expansion | Ho Chi Minh City and Jakarta depots enable uptime-guaranteed service contracts demanded by large tissue groups. |
| Digital Thread Technology Deployment | Parent reel tracking to finished goods serialization deepens software margin pools from tier-one producers in Germany and Netherlands. |
Research Methodology
Document review covered equipment supplier technical specifications, SAMR and EU Machinery Directive regulatory filings, and ASEAN harmonization framework documents, complemented by interviews with plant engineers at Indonesian tissue mills, procurement leads at Vietnamese retail private-label manufacturers, aftermarket service heads at Italian OEMs, and maintenance directors at Brazilian converting facilities. Secondary validation drew from customs machinery import records, industrial standards institute certifications, and trade association capacity surveys. Bottom-up line deployment counts triangulated against top-down capital expenditure estimates from hygiene product manufacturers.
Installed base projections and revenue segmentation across rewinding machines, packaging automation, servo-control retrofits, and mechanical systems emerged from equipment shipment tracking and service contract value analysis throughout the projection horizon. The analytical framework modeled technology substitution curves, regulatory compliance-driven replacement cycles, and regional manufacturing cluster formation patterns. CAGRs derived from parent tissue capacity expansion pipelines, retail private-label penetration rates, and energy efficiency mandate implementation schedules across the analysis window.
Caveats apply where steel and aluminum commodity volatility, commissioning engineer availability constraints, or mechanical-to-servo transition friction in markets with limited technical training infrastructure could materially shift the outlook. Forecasts reflect assumptions regarding SAMR enforcement consistency, ASEAN trade agreement stability, and tier-one tissue producer consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Box Sealing Machines Market