
 Cloth Self-Adhesive Tapes Market | 2026-2036
Cloth Self-Adhesive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Cloth Self-Adhesive Tapes Market Outlook
Southeast Asia is tilting toward cloth tape manufacturing as Vietnam and Thailand add coating and slitting capacity to serve regional electronics assemblers. 3M leverages its materials science heritage to sustain premium positioning in automotive-grade reinforced tapes. Nitto Denko anchors Asian supply chains with localized production of acrylic-based cloth tapes for white goods manufacturers. tesa SE differentiates through controlled distribution to European industrial distributors.
Cloth self-adhesive tapes consist of woven cotton, polyester, or blended fabric backings coated with pressure-sensitive adhesives, typically achieving peel strengths between 3 and 8 N/cm depending on adhesive chemistry and backing construction. These tapes serve industrial bonding, masking, splicing, and protective applications where conformability and hand-tearability outweigh the dimensional stability of film alternatives. Single-sided cloth tapes occupy the largest volume share across automotive wire harnessing and construction masking, while specialty variants command margin pools in aerospace-grade flame-retardant specifications. Acrylic-based adhesive chemistry is gaining share from rubber-based formulations in electrical and white goods applications due to superior thermal aging resistance and reduced volatile organic compound profiles.
EPA regulations in the United States constrain solvent-based adhesive emissions during tape coating operations, compelling domestic manufacturers to invest in hot melt and waterborne acrylic systems. REACH registration requirements in Europe restrict certain phthalate plasticizers historically used in rubber-based cloth tape formulations, redirecting formulation investment toward compliant polymer architectures. China's GB standards for packaging materials and SAMR product quality certifications shape import access and domestic procurement specifications. Stakeholders must monitor adhesive chemistry transitions and regional certification reciprocity to align capacity investments with evolving compliance thresholds.
Market Dynamics
REACH chemical restrictions and EPA emissions controls are compressing formulation options across solvent-based adhesive systems, redirecting capital toward hot-melt and waterborne acrylic coating lines.
Growth Catalysts
- Wire harness bundling:Automotive assembly lines in Germany and Mexico are expanding cloth tape procurement for electrical system organization and vibration dampening.
- Solvent-free acrylic formulations:REACH registration requirements are pushing European manufacturers toward compliant polymer architectures with reduced volatile organic compound profiles.
- Electronics manufacturing clusters:China's eastern manufacturing corridor generates concentrated demand for reinforced cloth tapes in protective packaging and component masking.
Market Restraints
- Petrochemical input volatility:Acrylic monomer and synthetic rubber feedstock costs fluctuate with crude oil derivatives, compressing margin predictability for coating operations.
- Coating capacity concentration:Southeast Asian slitting and coating facilities in Vietnam and Thailand create geographic supply risk for regional electronics assemblers.
- Film tape substitution:Polyester and polyimide film alternatives with superior dimensional stability displace cloth tapes in high-temperature electrical applications.
Strategic Opportunities
- Aerospace flame-retardant specifications:Specialty cloth tape variants meeting FAA fire-resistance standards command premium positioning in aircraft interior applications.
- White goods manufacturing localization:Appliance producers in Mexico and Eastern Europe seek qualified regional suppliers to reduce import dependency from Asian coating centers.
- Waterborne adhesive convergence:Hot-melt coating technology paired with waterborne acrylic chemistry enables EPA-compliant domestic production for US industrial distributors.
Industry Challenges
- Formulation chemistry expertise:Solvent-to-waterborne adhesive transitions require polymer scientists familiar with pressure-sensitive rheology and substrate wet-out behavior.
- Multi-jurisdiction certification timelines:Simultaneous GB standard compliance in China, CE marking in Europe, and SAMR quality certifications extend product launch cycles.
- Legacy equipment retrofit costs:Existing coating lines designed for solvent-based systems demand capital-intensive dryer and exhaust modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloth Self-Adhesive Tapes Market |
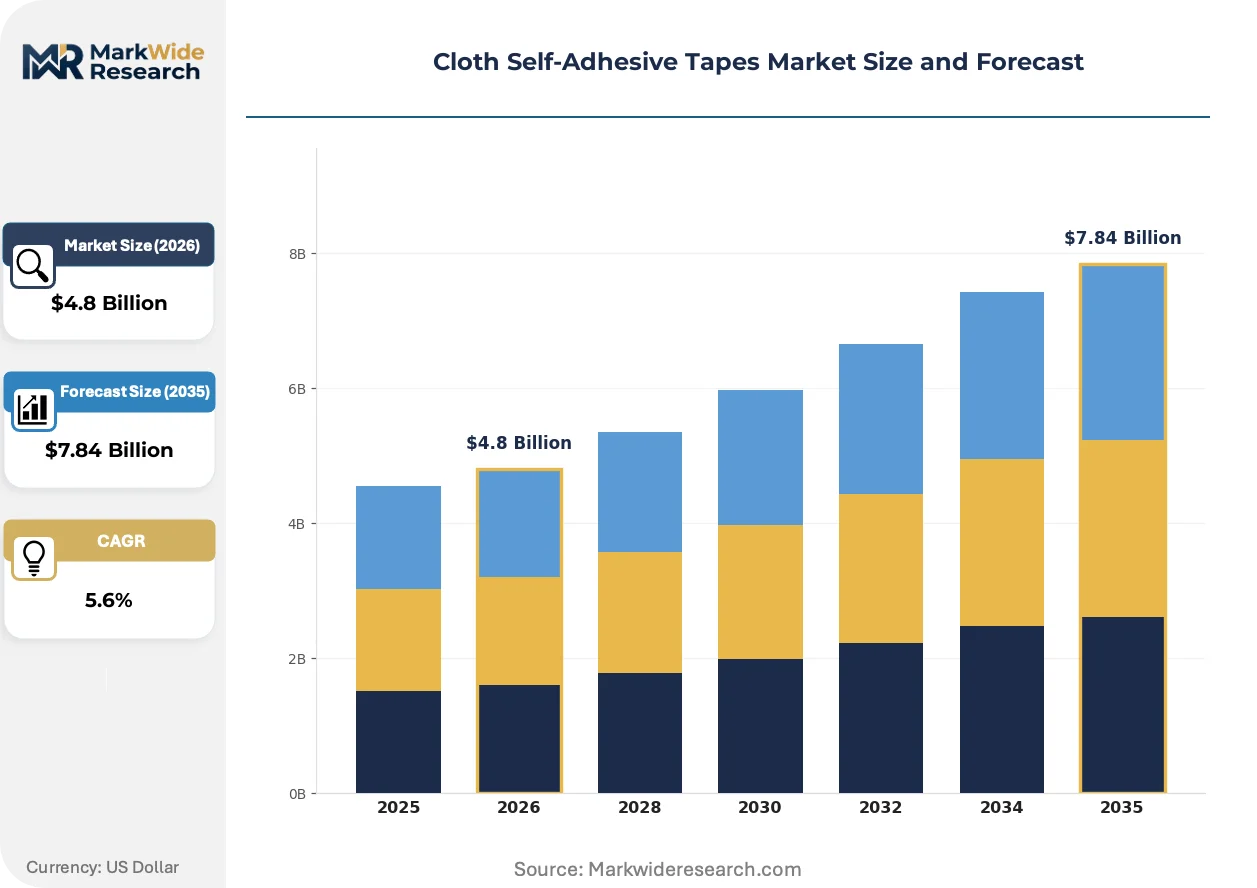
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
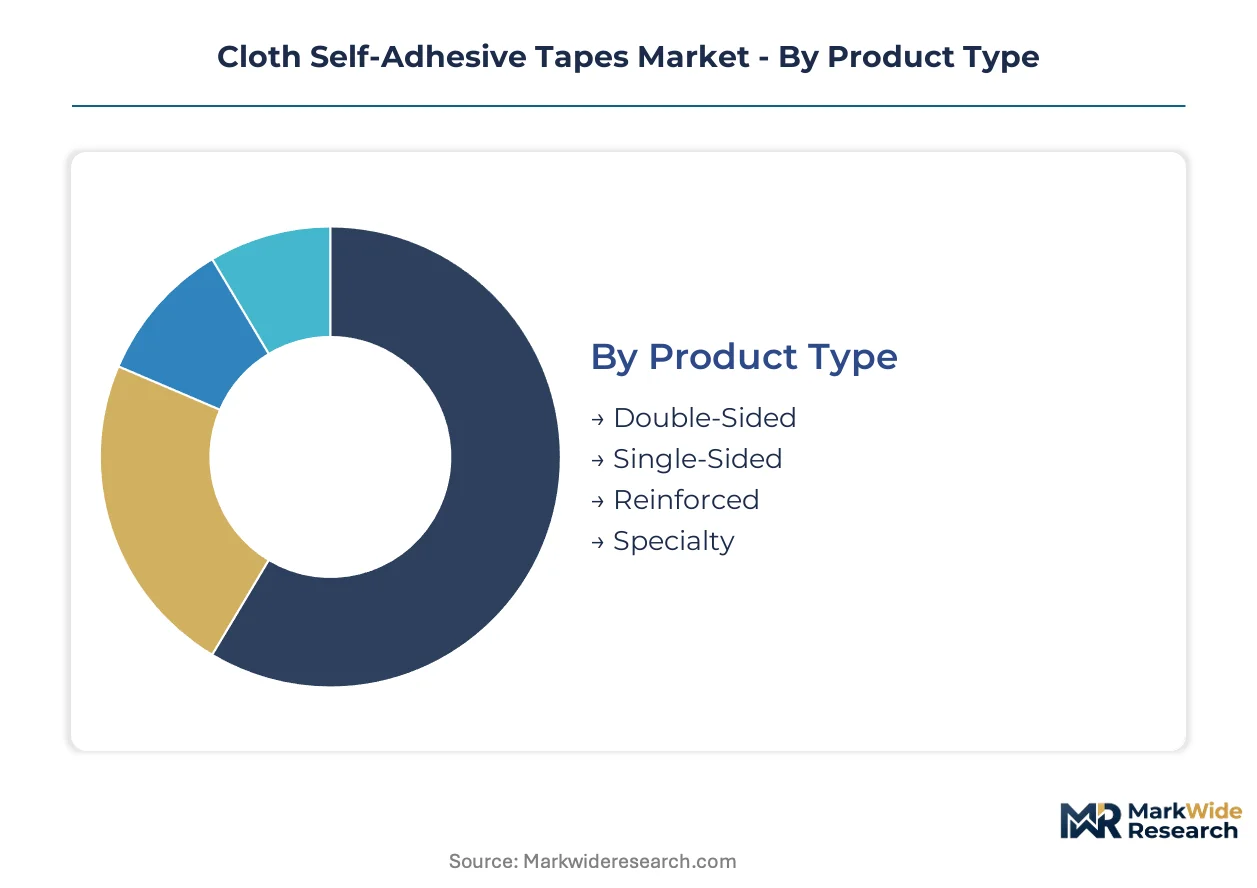
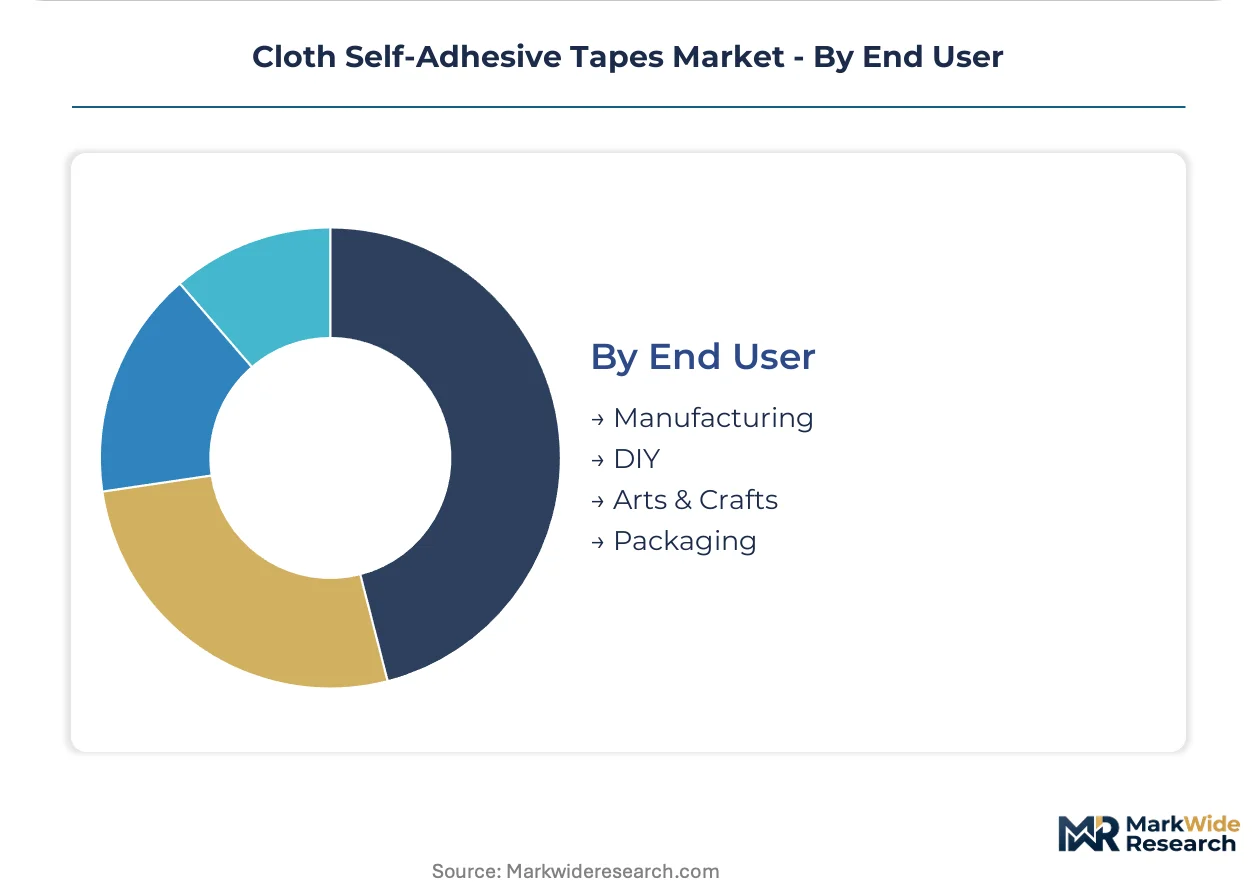
| Segmentation | Product Type: Double-Sided, Single-Sided, Reinforced, Specialty Application: Automotive, Construction, Electrical, White Goods Adhesive Type: Rubber-Based, Acrylic-Based, Silicone-Based, Hot Melt End User: Manufacturing, DIY, Arts & Crafts, Packaging |
| Companies Covered | 3M, Nitto Denko Corporation, Avery Dennison Corporation, tesa SE, Intertape Polymer Group, LINTEC Corporation, Berry Global Inc., Scapa Group, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloth Self-Adhesive Tapes Market Strategic Shifts
Adhesive chemistry transitions and regional regulatory divergence are fragmenting competitive positioning, rewarding manufacturers with flexible formulation capabilities and multi-certification portfolios.
Hot-melt coating technology is collapsing the cost structure of waterborne acrylic production. Tier-one automotive suppliers in Germany and Mexico are qualifying these systems for wire harness applications at accelerated validation cycles. The technology is collapsing energy consumption and solvent recovery infrastructure requirements, enabling smaller coating operations to achieve automotive-grade certification.
REACH Annex XVII restrictions on phthalate plasticizers are eliminating rubber-based formulations from European electrical applications. ECHA registration deadlines have forced reformulation investments toward compliant polymer architectures. White goods manufacturers in Poland and Italy are switching specification sheets to acrylic-based cloth tapes to ensure supply continuity.
Direct procurement from coating mills is compressing distributor margins in industrial tape channels. Large electronics contract manufacturers in China's Pearl River Delta are establishing approved vendor lists with slitting operations rather than branded distributors. This pattern is most visible in consumer appliance and computing hardware supply chains where volume consolidation enables price leverage.
Cloth Self-Adhesive Tapes Market Segmentation
Cloth self-adhesive tape purchasing decisions pivot on backing construction, adhesive chemistry, and end-use certification requirements. Manufacturers configure coating lines around specific segment combinations to capture margin pools in automotive wire harnessing and electronics masking.
Product Type:
Cost tier determines manufacturing complexity and qualification barriers for coating operations.
- Single-Sided:Cotton or polyester woven backings carry one adhesive face for general-purpose bonding and masking. Automotive assembly lines in Germany and Mexico source high volumes for wire harness bundling where hand-tearability accelerates installation throughput.
- Reinforced:Scrim or filament-embedded backings deliver tensile strength for heavy-duty splicing and pallet stabilization. China's eastern manufacturing corridor consumes reinforced grades for protective packaging of electronics exports facing rough handling.
- Double-Sided:Pressure-sensitive adhesive coats both faces for permanent bonding of carpet, trim, and insulation materials.
- Specialty:Flame-retardant and aerospace-grade variants meet FAA fire-resistance standards for aircraft interior applications.
Single-sided holds installed capacity. Reinforced is rotating up the share rankings.
Application:
End-use specifications fragment demand across certification regimes and performance thresholds.
- Automotive:Wire harness bundling and interior trim fixation require thermal aging resistance and vibration dampening. Tier-one suppliers in Germany and Mexico are qualifying hot-melt acrylic systems at accelerated validation cycles.
- Electrical:Insulation and coil winding applications demand solvent-free acrylic formulations to satisfy REACH Annex XVII phthalate restrictions. White goods manufacturers in Poland and Italy have switched specification sheets to compliant polymer architectures.
- Construction:Masking and surface protection during painting and renovation trades.
- White Goods:Appliance assembly lines use cloth tapes for component masking and temporary fixation during powder coating.
Automotive commands premium positioning. Electrical is gaining share fastest as regulatory deadlines force specification changes.
Adhesive Type:
Chemistry selection shapes compliance posture and thermal performance envelopes.
- Acrylic-Based:Synthetic polymer adhesives deliver superior UV resistance and thermal aging characteristics. EPA emissions controls in the United States are redirecting coating investment toward waterborne acrylic systems that eliminate solvent recovery infrastructure.
- Rubber-Based:Natural and synthetic rubber adhesives offer aggressive tack and conformability at lower cost. ECHA registration deadlines are eliminating phthalate-plasticized formulations from European electrical applications.
- Hot Melt:Thermoplastic adhesive systems enable high-speed coating without solvent emissions.
- Silicone-Based:Premium chemistry for extreme temperature applications in aerospace and industrial ovens.
Acrylic-based holds formulation investment. Hot melt is climbing the fastest as coating technology matures.
End User:
Customer type determines order scale, specification rigor, and channel configuration.
- Manufacturing:Industrial purchasers in automotive, electronics, and appliance sectors demand certified batches and approved vendor lists. Direct procurement from coating mills is compressing distributor margins in China's Pearl River Delta.
- Packaging:Logistics and fulfillment operations source reinforced grades for carton sealing and pallet stabilization. Vietnam and Thailand are adding slitting capacity to serve regional electronics assemblers.
- DIY:Retail consumers purchase through hardware and home improvement channels for repair and maintenance tasks.
- Arts & Crafts:Hobbyist applications favor decorative colors and easy hand-tearability over industrial performance metrics.
Manufacturing concentrates volume procurement. Packaging is expanding most quickly as e-commerce fulfillment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating capacity clusters in Germany, China, and the United States, with secondary slitting operations scaling in Vietnam and Thailand to serve electronics supply chains. Each geography shapes distinct procurement patterns through regulatory frameworks and end-use concentration.
United States
Automotive wire harness bundling drives volume procurement from assembly plants in Michigan and Ohio. EPA emissions controls constrain solvent-based coating operations, redirecting capital toward hot-melt and waterborne acrylic systems. Industrial distributors in the Midwest and Southeast regions manage inventory for tier-one automotive suppliers seeking domestic qualification.
Germany
Tier-one automotive suppliers in Bavaria and Baden-Württemberg specify cloth tapes for electrical system organization and interior trim fixation. REACH Annex XVII restrictions on phthalate plasticizers eliminate rubber-based formulations from electrical applications. Coating mills in the Ruhr industrial corridor invest in compliant polymer architectures to maintain supply continuity for white goods manufacturers.
China
Electronics contract manufacturers in the Pearl River Delta and Yangtze River Delta generate concentrated demand for reinforced cloth tapes in protective packaging and component masking. GB standards for packaging materials and SAMR product quality certifications shape import access and domestic procurement specifications. Direct procurement from coating mills is compressing distributor margins across the eastern manufacturing corridor.
Mexico
Automotive assembly lines in Nuevo León and the Bajío Region expand cloth tape procurement for wire harness bundling as OEMs localize production. The country's proximity to US distribution networks enables just-in-time delivery for tier-one suppliers. Appliance manufacturers in Mexico seek qualified regional suppliers to reduce import dependency from Asian coating centers.
Vietnam
Electronics assemblers in Ho Chi Minh City and Hanoi drive regional demand for slitting and coating capacity expansion. The country's manufacturing zones attract secondary processing operations to serve consumer appliance and computing hardware supply chains. Vietnamese facilities face geographic supply risk concentration as regional electronics production scales.
Cloth Self-Adhesive Tapes Market Competitive Environment
Materials science conglomerates and specialized adhesive coating houses split the market between premium specification-grade supply and volume-driven industrial distribution. The competitive structure rewards manufacturers with multi-certification portfolios and flexible formulation capabilities across solvent-free acrylic systems. Two dominant strategic moves are reshaping positioning: direct mill procurement relationships that bypass traditional distribution channels, and hot-melt coating technology investments that collapse energy consumption and qualification timelines for automotive-grade certification.
Within the materials science tier, 3M anchors premium positioning through its heritage in industrial adhesive development. Nitto Denko Corporation and tesa SE exemplify the regional supply chain integration archetype, with localized production networks serving automotive and white goods manufacturers across their respective home markets. These three entities represent distinct competitive vectors: technology leadership, Asian supply chain density, and European industrial distribution control.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| tesa SE |
| Intertape Polymer Group |
| LINTEC Corporation |
| Berry Global Inc. |
| Scapa Group |
| Lohmann GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Acrylic monomer concentration in Asian petrochemical corridors positions coating mills in China and South Korea to capture margin pools in automotive-grade tape supply. REACH compliance costs and EPA emissions controls compress formulation options, redirecting buyer procurement toward qualified solvent-free suppliers who command premium positioning.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European electrical applications, eliminating phthalate-plasticized rubber formulations and forcing specification migration toward compliant acrylic systems. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace grades from automotive-qualified batches and general-purpose masking tapes. Price differentiation hinges on certification grade and volume scale, with tier-one automotive suppliers least sensitive due to qualification switching costs. Cost compression in standard grades is intensifying because direct mill procurement from electronics contract manufacturers bypasses traditional distributor markups.
Supply Chain Analysis
Petrochemical feedstock supply draws from China, South Korea, and Saudi Arabia for acrylic monomer and synthetic rubber inputs. Coating capacity rests on woven cotton and polyester textile backings sourced from Bangladesh, Vietnam, and domestic Chinese mills. Single-source vulnerability concentrates in solvent-based adhesive precursor supply as ECHA registration deadlines eliminate non-compliant European production. Distribution runs through industrial distributors in Germany and the United States, with direct mill relationships expanding in China's Pearl River Delta electronics corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks automotive production cycles, with wire harness bundling demand inflecting with OEM assembly line utilization rates in Germany and Mexico.
For Market Incumbents: Build certification moats around multi-jurisdiction compliance portfolios spanning REACH, EPA, and GB standards. Film tape substitution in high-temperature electrical applications threatens rubber-based formulation share; defend through accelerated hot-melt acrylic qualification with tier-one automotive suppliers. Channel control through approved vendor lists with electronics contract manufacturers secures volume commitment against distributor disintermediation. For New Entrants and Emerging Players: White goods manufacturing localization in Mexico and Eastern Europe represents the most penetrable entry point, with appliance producers actively seeking qualified regional suppliers to reduce Asian import dependency. Secondary slitting operations in Vietnam and Thailand serving regional electronics assemblers offer lower capital barriers than integrated coating mills. A go-to-market angle anchored on SAMR certification assistance for Chinese market access differentiates against incumbent distributors lacking regulatory navigation expertise. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hot-melt coating technology adoption, collapsing energy consumption and solvent recovery infrastructure requirements for smaller operations. Long-term viability favors coating houses with flexible formulation capabilities across waterborne acrylic and hot-melt systems rather than legacy solvent-dependent assets. Acquisition targets should demonstrate automotive-grade certification and existing approved vendor list status with tier-one suppliers. The signal to watch is qualification timeline compression for hot-melt systems as German and Mexican automotive suppliers accelerate validation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Coating Capacity Addition | Enables EPA-compliant domestic production for US automotive wire harness suppliers without solvent recovery infrastructure. |
| Backward Integration into Acrylic Monomer Supply | Reduces petrochemical input volatility exposure for coating operations facing margin compression from crude oil derivative fluctuations. |
| Multi-Certification Portfolio Investment | Captures premium positioning across REACH-compliant European electrical and SAMR-certified Chinese packaging applications simultaneously. |
| Direct Mill Procurement Relationship Development | Bypasses distributor margin compression in China's Pearl River Delta electronics supply chains through approved vendor list status. |
| Aerospace Flame-Retardant Specification Qualification | Accesses FAA-certified premium tier for aircraft interior applications with higher margin pools than automotive-grade commodity supply. |
Study Parameters
A spread of perspectives from coating mill operations managers, tier-one automotive supplier procurement leads, electronics contract manufacturer supply chain directors, and industrial tape distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, chemical industry association reports, SEC 10-K filings of materials science conglomerates, and automotive production databases. Bottom-up segment sizing across adhesive chemistry, backing construction, and end-use certification tiers was triangulated against top-down market value estimates.
Demand-supply balance modeling across the analysis window incorporated automotive assembly line expansion schedules, electronics manufacturing cluster growth in China's eastern corridor, and white goods localization timelines in Mexico and Eastern Europe. Segmentation dimensions included product type, adhesive chemistry, application certification requirements, and end-user procurement scale. CAGRs were derived from volume trajectory analysis adjusted for substitution effects from film tape alternatives and regulatory-driven formulation transitions. Forecast inputs included petrochemical feedstock cost indices and coating capacity utilization rates across German, Chinese, and US production hubs.
Stress conditions across acrylic monomer price volatility, REACH enforcement stringency, and automotive production cycle downturns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory deadline adherence and qualification timeline compression for hot-melt coating systems. Cross-checking against IHS Markit vehicle production data and chemical industry capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Pipe Marking Tape Market
Tapes
Moisture Barrier Tapes Market
Tapes
Lacing Tape Market
Tapes
Filmic Tapes Market
Tapes
Carbon Tapes Market
Tapes
Acetate Cloth Tape Market
Tapes
Reflective Tape Market
Tapes
Pouch Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
Release Tape Market
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Replica Tapes Market
Tapes
Strapping Tapes Market
Tapes
Removal Strips Market
Tapes
Spacer Tapes Market