
 Plastic Corrugated Sheets Market | 2026-2036
Plastic Corrugated Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Corrugated Sheets Market Outlook
Modular packaging configurations is recalibrating buyer choice across the plastic corrugated sheets landscape as brands seek stackable, collapsible container systems over fixed-format boxes. Coroplast leverages its North American manufacturing footprint to dominate standardized totes for retail distribution networks. Palram Industries Ltd. differentiates through architectural-grade multi-wall panels that serve dual-use signage and construction applications. Simona AG anchors European supply with specialized extrusion capabilities for chemical-resistant sheet grades.
Plastic corrugated sheets are extruded thermoplastic panels featuring hollow fluted cores bonded between flat facings, typically manufactured from polypropylene or polyethylene resin through continuous profile extrusion at widths up to three meters and thicknesses spanning two to ten millimeters. These lightweight, impact-resistant structures serve primarily as protective packaging substrates, temporary building envelopes, and reusable shipping platforms across industrial supply chains. Polypropylene material grades lead volume owing to superior fatigue resistance and broader temperature tolerance, while recycled materials represent the fastest-expanding category as brand sustainability mandates intensify procurement screening. Packaging applications command the largest value share given the segment's integration into closed-loop automotive and electronics logistics systems, though construction adoption accelerates fastest as temporary cladding and concrete forming panels displace plywood on job sites.
REACH chemical registration requirements in Europe restrict certain additive packages, compelling reformulation toward halogen-free flame retardants in construction-targeted sheets. FDA food-contact regulations govern polyethylene-based designs deployed in agricultural produce harvesting and retail display, while EPA industrial emissions standards shape extrusion plant siting and capital allocation decisions in the United States. Stakeholders must monitor evolving extended producer responsibility frameworks and biobased content thresholds that will determine material qualification for major account contracts.
Market Dynamics
Automotive logistics networks are forcing a packaging reset as returnable container systems displace single-use corrugated cardboard across tiered supplier bases. This operational mandate cascades through electronics and agricultural supply chains, compressing specification cycles and favoring extruders with rapid tooling turnaround.
Growth Catalysts
- REACH chemical registration:ECHA's additive restrictions are accelerating halogen-free flame-retardant adoption in construction-grade sheets, opening specification doors with European building contractors.
- Closed-loop automotive logistics:OEM container standardization programs are mandating polypropylene totes for inbound parts sequencing, locking in multi-year supply agreements with qualified extruders.
- China's agricultural greenhouse expansion:Provincial subsidy schemes for protected cultivation are driving multi-wall panel demand for climate-controlled growing environments.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in the US Gulf Coast and Middle East are compressing margin visibility for integrated and merchant sheet producers alike.
- Recycled-content contamination thresholds:FDA food-contact specifications for polyethylene harvesting containers limit post-consumer resin incorporation, capping sustainability claims in fresh produce logistics.
- Concrete forming plywood:Treated softwood panels retain cost advantage on short-cycle commercial pours, delaying plastic corrugated penetration in general contracting.
Strategic Opportunities
- India's cold-chain infrastructure buildout:FSSAI-mandated temperature compliance for dairy and pharmaceutical distribution is creating first-mover advantage for insulated corrugated box suppliers.
- Digital printing integration:UV-curable inkjet systems are converging with anti-static sheet grades, enabling variable-data branding on retail-ready packaging without separate label application.
- EU Green Deal biobased thresholds:Emerging public procurement rules will favor polypropylene formulations with certified renewable content, rewarding early polymer sourcing partnerships.
Industry Challenges
- Extrusion die maintenance specialization:Hollow-flute profile complexity requires tool-and-die craftsmen with thermoplastic flow simulation expertise, a skill set concentrated among aging workforces in Germany and Japan.
- Multi-standard certification overlap:Simultaneous UL fire-rating, FDA food-contact, and automotive OEM qualification timelines stretch quality engineering resources across 18-24 month approval windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Corrugated Sheets Market |
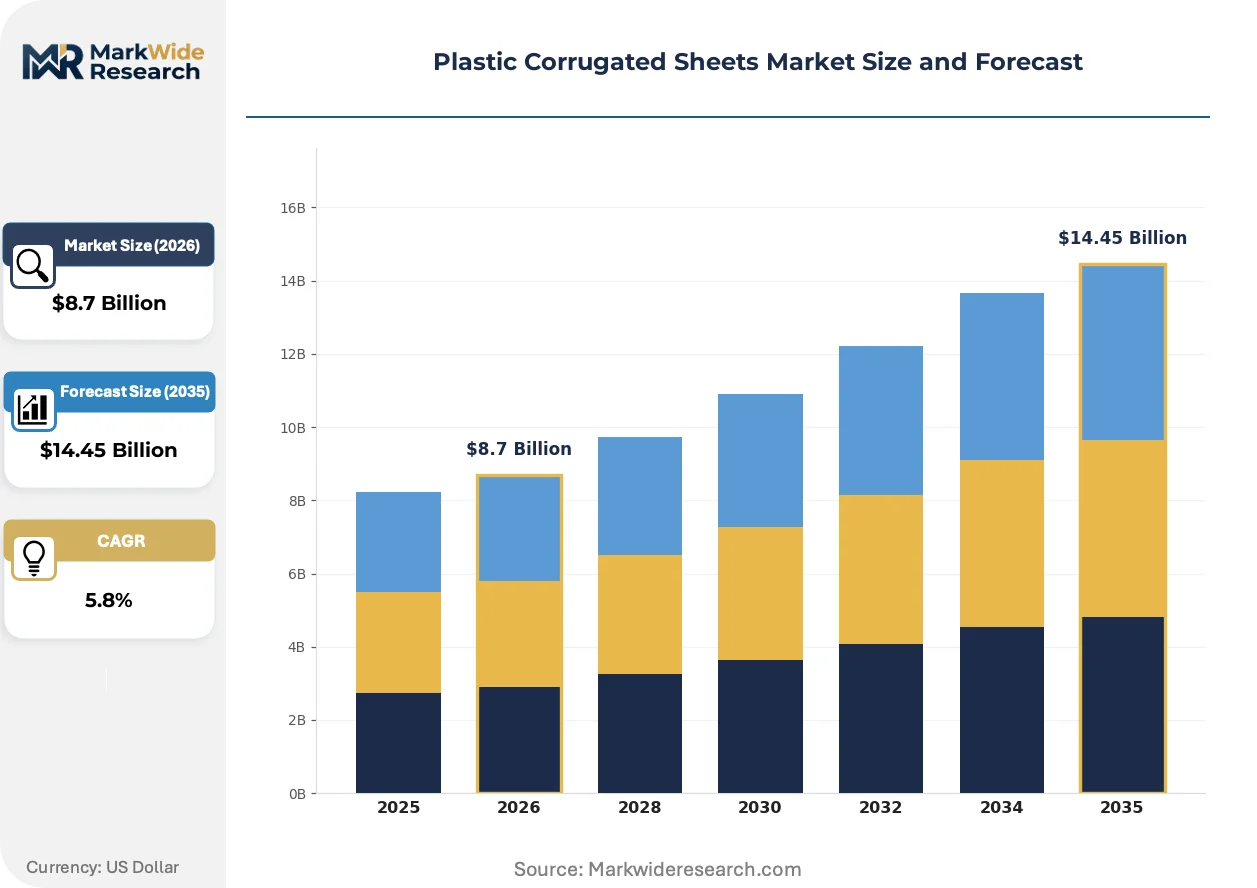
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
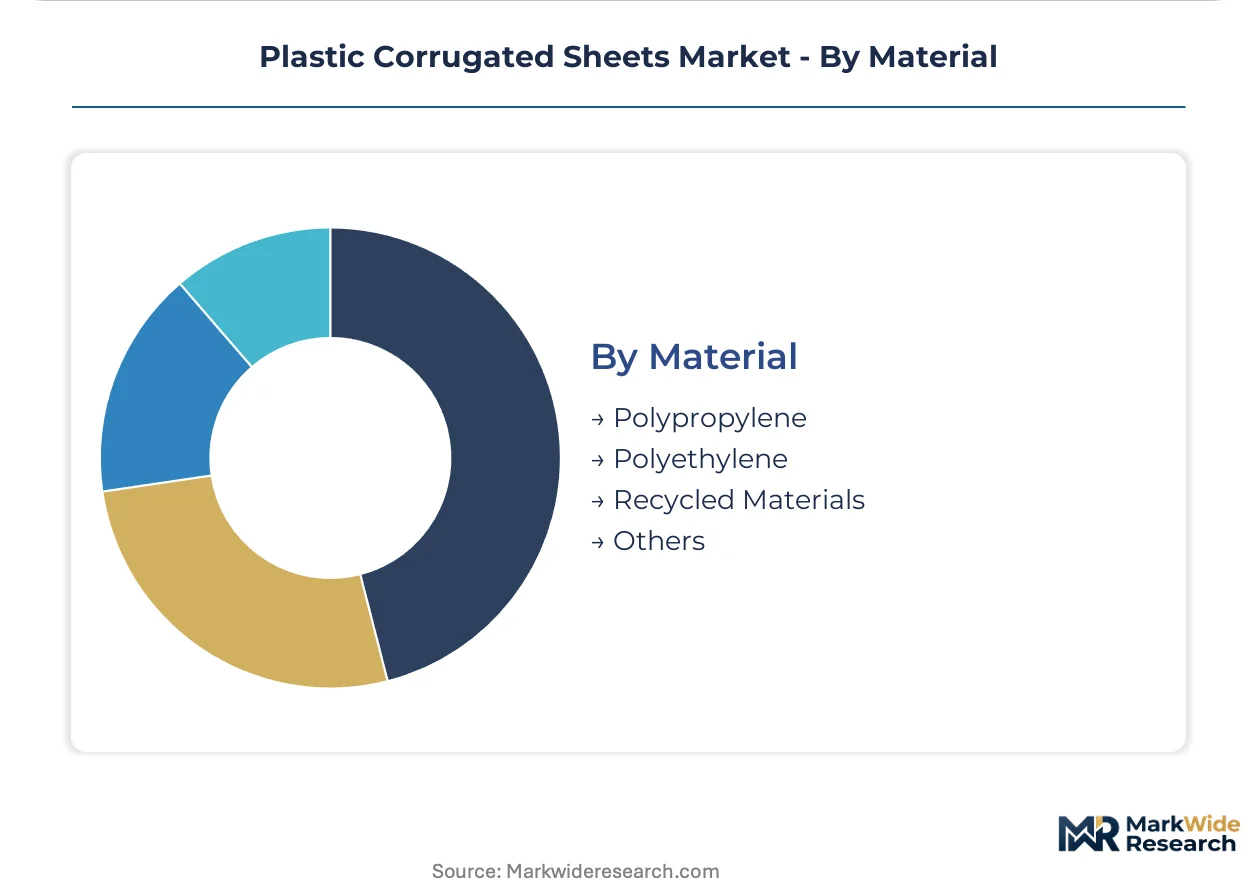
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Multi-wall Application: Packaging, Construction, Agriculture, Signage End User: Retail, Automotive, Electronics, Consumer Goods Material: Polypropylene, Polyethylene, Recycled Materials, Others |
| Companies Covered | Simona AG, Palram Industries Ltd., Coroplast, Inteplast Group, Mitsubishi Chemical Group, Primex Plastics Corporation, Plaskolite, LLC, Corplex, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Corrugated Sheets Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine performance benchmarks across packaging and construction applications. Extruders are racing to qualify formulations that satisfy divergent durability, sustainability, and compliance mandates.
Co-extruded barrier layers with ethylene-vinyl alcohol cores are rewriting shelf-life expectations for agricultural produce containers. Berry packers in California and Spain are adopting these structures for export-grade raspberry and blueberry shipping, replacing wax-impregnated corrugated fiberboard. The technology is compressing the premium packaging tier by eliminating secondary moisture barriers.
REACH authorization requirements for legacy flame-retardant additives are forcing construction-sheet reformulation across European extrusion plants. ECHA's sunset dates for halogenated compounds are compelling investment in phosphorus-nitrogen synergist systems. German and Dutch building distributors are now screening supplier portfolios for pre-registered alternative chemistries to avoid supply interruption.
Automotive tier-one suppliers are consolidating container procurement through pooled fleet operators rather than direct mill purchasing. This third-party logistics concentration is visible most acutely in Volkswagen Group and Toyota Motor supplier parks across Mexico and Kentucky, where standardized tote pooling reduces capital tie-up. The shift is compressing direct sales relationships and favoring extruders with fleet-scale volume capacity.
Plastic Corrugated Sheets Market Segmentation
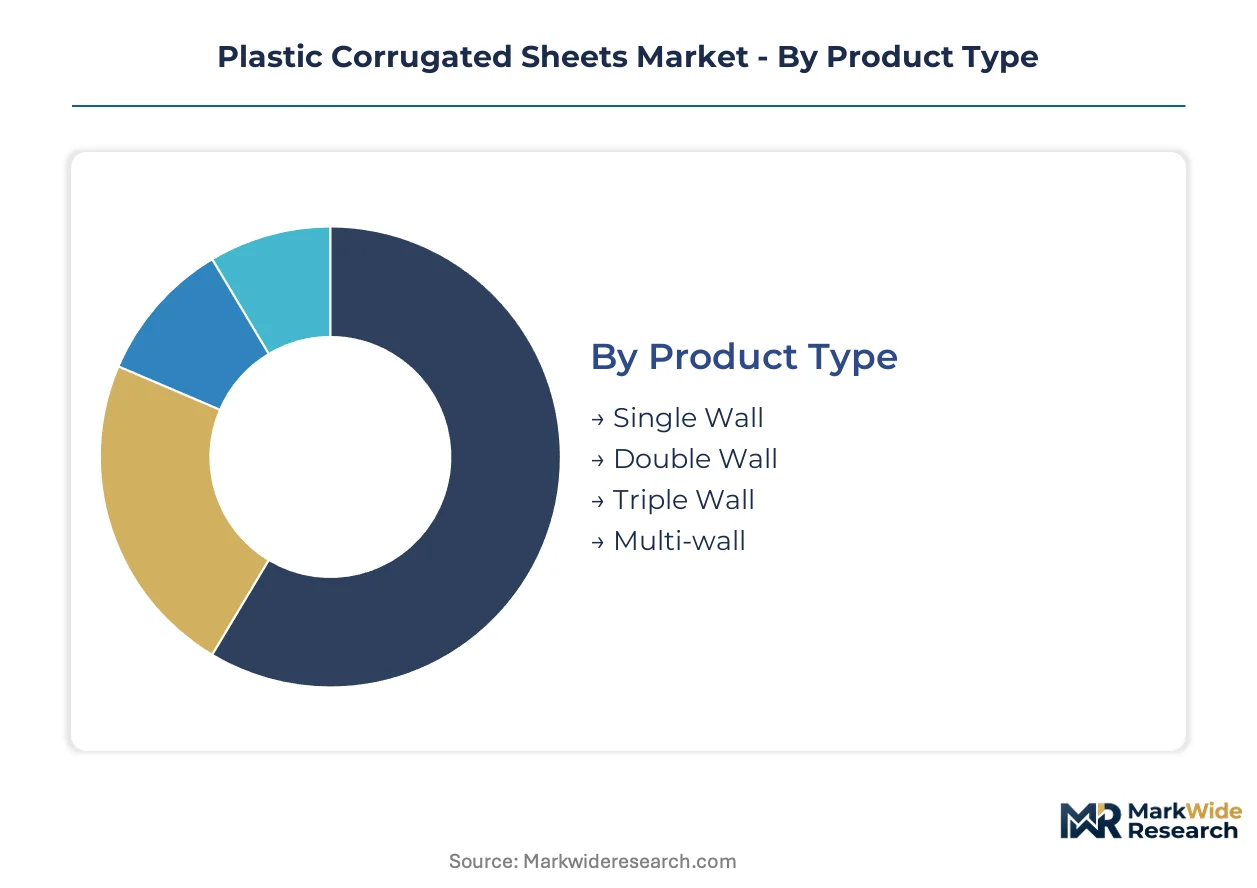
Segmentation in plastic corrugated sheets reveals how technical specifications, regulatory constraints, and end-use durability requirements fragment procurement patterns across industries. Buyers prioritize wall thickness for load-bearing applications, material grade for chemical compliance, and recyclability credentials for sustainability mandates.
Product Type:
Cost tier differentiation separates commodity buyers from specification-driven purchasers in this category.
- Single Wall:Two-millimeter fluted cores bonded between flat facings deliver lightweight protection for document shipping and retail display fixtures. Electronics distributors in Shenzhen and Guadalajara specify these grades for ESD-sensitive component transport where weight minimization reduces freight spend.
- Double Wall:Twin hollow chambers separated by internal ribs create four-millimeter structures with enhanced compressive strength. Automotive tier-one suppliers in Kentucky and Lower Saxony deploy these totes for engine component sequencing lines where 50-kilogram stacking loads are standard.
- Triple Wall:Six-millimeter profiles with triple-flute construction serve heavy industrial dunnage and export crating for machinery.
- Multi-wall:Architectural-grade panels exceeding eight millimeters integrate UV-stabilized outer skins for greenhouse cladding and temporary building envelopes.
Single Wall leads volumes today; Multi-wall is gaining share fastest.
Application:
Application selection tracks directly to replacement cycles—disposable packaging versus multi-year infrastructure deployment.
- Packaging:Returnable container systems for closed-loop automotive and electronics logistics dominate procurement volumes. OEM standardization programs at Volkswagen Group and Toyota Motor facilities across Mexico mandate polypropylene totes with 500+ use cycles, locking extruders into fleet-scale supply agreements.
- Construction:Temporary cladding and concrete forming panels displace plywood on commercial job sites where moisture resistance accelerates reuse. German contractors specify REACH-compliant halogen-free grades for scaffold enclosure and weather protection during envelope installation.
- Agriculture:Multi-wall greenhouse panels capture provincial subsidy schemes for protected cultivation in Shandong and Jiangsu provinces.
- Signage:UV-printable surfaces serve retail point-of-purchase displays and political campaign boards with six-month outdoor durability.
Packaging commands the largest value position; Construction is expanding most quickly.
End User:
Customer type determines specification stringency—from food-contact compliance to ESD protection and automotive OEM qualification timelines.
- Retail:Produce harvesting containers and shelf-ready display boxes require FDA food-contact certification for polyethylene grades. California berry packers specify co-extruded EVOH barrier layers for export-grade raspberry shipping, replacing wax-impregnated fiberboard.
- Automotive:Inbound parts sequencing totes demand VDA standard footprints and anti-static formulations. Pooled fleet operators now consolidate procurement across Volkswagen and Toyota supplier parks, compressing direct mill relationships.
- Electronics:ESD-dissipative sheet grades protect semiconductor components during Asian contract manufacturing distribution.
- Consumer Goods:E-commerce shipping boxes and furniture protection prioritize cost minimization over multi-cycle durability.
Automotive leads procurement scale; Retail is climbing the fastest.
Material:
Margin structure and sustainability credentials differentiate resin selection as brand mandates intensify procurement screening.
- Polypropylene:Superior fatigue resistance and temperature tolerance spanning minus twenty to plus one hundred degrees Celsius dominate automotive and industrial applications. Simona AG anchors European supply with specialized extrusion capabilities for chemical-resistant grades meeting REACH additive restrictions.
- Polyethylene:FDA food-contact approval for agricultural produce harvesting and retail display drives specification in fresh logistics. Post-consumer resin incorporation faces contamination thresholds that cap sustainability claims.
- Recycled Materials:Fastest-expanding category as extended producer responsibility frameworks and biobased content thresholds determine contract qualification.
- Others:Bio-based polypropylene and specialty compounds serve niche architectural and medical packaging requirements.
Polypropylene leads volumes today; Recycled Materials is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plastic corrugated sheet extrusion first achieved industrial scale in Germany during the 1970s, with specialized thermoplastic profile technology later migrating to North American and Asian manufacturing bases. Regional demand patterns now track automotive logistics networks, agricultural subsidy programs, and construction material substitution cycles across distinct national regulatory environments.
China
Electronics export corridors from Shenzhen and Dongguan consume single-wall grades for ESD-sensitive component transport, while Shandong and Jiangsu provincial governments subsidize multi-wall greenhouse panel installations for protected cultivation. GB standards for plastic building materials govern flame-retardant specifications in construction applications. The Yangtze River Delta cluster hosts the densest concentration of extrusion capacity serving both domestic agricultural demand and export packaging for contract manufacturers.
Germany
Automotive container standardization programs at Volkswagen Group and BMW facilities in Lower Saxony and Bavaria mandate REACH-compliant polypropylene totes with 500-plus use cycles. ECHA additive restrictions for halogenated flame retardants are compelling reformulation toward phosphorus-nitrogen systems in construction-grade sheets. The Ruhr industrial corridor anchors specialized extrusion capabilities for chemical-resistant grades, with tool-and-die craftsmanship concentrated in aging workforces across Baden-Württemberg.
United States
FDA food-contact regulations govern polyethylene harvesting containers for California berry packers, while EPA industrial emissions standards shape extrusion plant siting decisions in the Southeast. Toyota Motor supplier parks in Kentucky and Volkswagen Group facilities in Tennessee are consolidating procurement through pooled fleet operators. The Midwest automotive corridor drives standardization of returnable container systems, compressing direct mill relationships toward third-party logistics concentration.
India
FSSAI-mandated temperature compliance for dairy and pharmaceutical distribution is creating specification demand for insulated corrugated box suppliers in Maharashtra and Gujarat. Central government PLI scheme incentives for cold-chain infrastructure are accelerating warehouse construction in the Delhi-NCR region. Karnataka's electronics manufacturing cluster near Bangalore is adopting ESD-dissipative grades for semiconductor component protection, mirroring Chinese export corridor patterns.
Japan
METI industrial standards for reusable shipping platforms govern automotive logistics procurement by Toyota Motor and Honda Motor suppliers in Aichi Prefecture. JIS certification requirements for plastic building materials restrict construction-grade sheet specifications in Tokyo and Osaka metro construction markets. The Chubu region around Nagoya maintains specialized extrusion expertise for high-fatigue-resistance polypropylene grades, with technical workforce aging similar to German patterns.
Plastic Corrugated Sheets Market Competitive Environment
The competitive structure tilts toward integrated resin-to-sheet producers with captive polypropylene supply and specialized tool-and-die engineering capabilities. Market concentration is moderate, with regional champions dominating national procurement channels while global accounts fragment across multiple qualified suppliers. Three archetypes define positioning: resin-integrated multinationals with automotive OEM qualification, regional extrusion specialists with rapid tooling turnaround, and construction-focused fabricators with architectural-grade multi-wall capabilities. Capacity expansion and strategic partnerships for recycled-content sourcing represent the dominant competitive moves as sustainability mandates intensify procurement screening.
Among North American fabricators, Coroplast occupies a position exemplifying standardized tote production for retail distribution networks, while Inteplast Group represents resin-integrated scale advantages in automotive logistics supply. German-based Simona AG anchors European chemical-resistant grade supply with specialized extrusion capabilities meeting REACH additive restrictions. These three companies illustrate how geographic proximity to automotive OEM clusters and regulatory compliance specialization determine contract qualification for multi-year fleet agreements.
| Leading Market Players |
|---|
| Simona AG |
| Palram Industries Ltd. |
| Coroplast |
| Inteplast Group |
| Mitsubishi Chemical Group |
| Primex Plastics Corporation |
| Plaskolite, LLC |
| Corplex |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
Pooled fleet operators consolidating procurement for Volkswagen Group and Toyota Motor supplier parks command volume-leveraged contract structures that compress spot-market premiums and lock extruders into multi-year offtake agreements with limited renegotiation windows.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between automotive OEMs and qualified extruders, with pricing stratifying across REACH-compliant premium grades, FDA-certified food-contact tiers, and commodity standard grades without certification overhead. Price differentiation centers on flame-retardant additive packages and recycled-content thresholds, with REACH-registered halogen-free formulations commanding substantial premiums over legacy grades. Cost compression in standard-grade single-wall sheeting is intensifying because Chinese export-oriented extruders are expanding capacity for electronics packaging demand. Tier-one automotive suppliers exhibit lowest price sensitivity due to OEM qualification lock-in, while fresh produce distributors in California and Spain face acute margin pressure from waxed fiberboard substitution economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand through qualified supplier programs, while distribution through building-material distributors and third-party logistics operators serves fragmented construction and agricultural segments. Extrusion capacity concentrates in Germany, China, and the United States, with specialized tool-and-die craftsmanship concentrated in aging workforces across Baden-Württemberg and Aichi Prefecture. Raw material supply draws from naphtha-cracker propylene output in the US Gulf Coast and Middle East, coupled with post-consumer resin streams for sustainability-mandated grades. Single-source vulnerability in specialized die maintenance expertise creates bottleneck risk for rapid tooling turnaround. Distribution runs through regional fabricators who convert master rolls into finished containers and panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in plastic corrugated sheets rest on halogen-free flame-retardant premiumization and captive recycled-content sourcing that deflects propylene feedstock volatility.
For Market Incumbents: Acquire specialized tool-and-die engineering capabilities in Germany or Japan to secure rapid tooling turnaround for automotive qualification timelines. Simultaneously deepen backward integration into post-consumer resin sorting and reprocessing to meet emerging biobased content thresholds in EU public procurement. These moves counter the threat of pooled fleet operators compressing direct mill relationships through third-party logistics concentration. For New Entrants and Emerging Players: Pooled cold-chain logistics operators in India represent the most accessible channel partner type for insulated corrugated box penetration. Target Maharashtra and Gujarat dairy distribution networks where FSSAI temperature compliance mandates are creating first-mover specification windows. White-space opportunity exists in co-extruded EVOH barrier grades for export-oriented berry packers in California and Spain seeking waxed fiberboard displacement. For Investors and Strategic Acquirers: Resin-integrated chemical conglomerates with captive polypropylene supply are the most active acquirer in this space, seeking extrusion specialists with automotive OEM qualification. The viable acquisition window favors targets with REACH pre-registration for phosphorus-nitrogen flame-retardant systems and established supplier park proximity to Volkswagen Group or Toyota Motor facilities. Watch for ECHA sunset date enforcement on halogenated additives as the inflection signal for premium-grade supply scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Sourcing | Captive post-consumer feedstock secures EU Green Deal biobased procurement qualification. |
| REACH-Compliant Flame-Retardant Reformulation | Phosphorus-nitrogen systems unlock German construction distributor specification doors ahead of ECHA deadlines. |
| Pooled Fleet Operator Partnership | Third-party logistics concentration at Kentucky and Tennessee supplier parks compresses customer acquisition cost. |
| Co-Extruded Barrier Layer Qualification | EVOH-core structures capture California berry packer demand from wax-impregnated fiberboard. |
| Tool-and-Die Craftsmanship Acquisition | German and Japanese die simulation expertise removes automotive qualification timeline bottlenecks. |
Study Parameters
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each regional cluster combining interviews with automotive tier-one procurement directors, extrusion plant managers, building-material distributors, cold-chain logistics operators, and regulatory affairs specialists with secondary validation. Secondary sources include ECHA additive restriction documentation, FDA food-contact guidance, EPA industrial emissions filings, FSSAI cold-chain regulations, and customs trade data for propylene derivative flows. Bottom-up volume modeling and top-down value reconciliation provided triangulation across data streams.
Granularity-level modeling disaggregated demand across product type dimensions including single-wall through multi-wall constructions, application segments spanning packaging, construction, agriculture, and signage, material grades from virgin polypropylene to certified recycled content, and end-user categories differentiated by qualification stringency. CAGRs were derived from segment-level volume build-ups applied against pricing trajectories over the projection horizon. Industry-specific forecast inputs incorporated automotive OEM container standardization program timelines and provincial greenhouse subsidy scheme disbursement patterns in Shandong and Jiangsu.
Revisions become necessary when ECHA accelerates halogenated flame-retardant sunset dates, when naphtha-cracker outages disrupt propylene feedstock availability, or when FDA tightens post-consumer resin contamination thresholds for food-contact applications. Forecasts reflect documented assumptions regarding REACH pre-registration completion rates and biobased content certification adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Vials Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market