
 Envelope Paper Market | 2026-2036
Envelope Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Envelope Paper Market Analysis
Modular mailer configurations that combine paper-based cushioning with adhesive-free closures is restructuring how fulfillment buyers evaluate unit economics. International Paper leverages its North American pulp network to sustain cost-advantaged supply to major retailers. Mondi Group anchors European demand through specialized kraft and wove grades engineered for automated insertion lines. WestRock competes via integrated containerboard-to-converted-envelope operations that compress lead times for direct-mail agencies.
Envelope paper denotes wood-pulp-derived sheet stock, typically 60–150 gsm basis weight, calendered or uncalendered, sized for printability and fold endurance, then converted into sealed containers for document protection or lightweight goods shipment. Its commercial purpose centers on providing tamper-evident, brandable, and machinable enclosures for postal and courier systems. Kraft grades dominate volume flows due to inherent tear strength and recyclability alignment with retailer sustainability scorecards. Lightweight segments gain share as postal operators impose dimensional-weight pricing that penalizes heavier substrates. Direct mail applications retain premium margin pools despite digital substitution, driven by targeted campaign personalization and higher response-rate economics.
FDA indirect food-contact rules, EPA forestry certification requirements, and EU REACH substance restrictions collectively govern fiber sourcing, chemical additive limits, and cross-border shipment compliance for envelope paper producers. These frameworks elevate compliance costs for uncertified mills while creating preferential market access for operators with chain-of-custody documentation. Stakeholders must monitor evolving extended-producer-responsibility schemes and postal-operator packaging specifications that will determine which substrate grades retain network eligibility.
Market Dynamics
Postal automation mandates and dimensional-weight pricing are compressing demand toward lighter, machine-readable substrates while EU Green Deal compliance requirements filter uncertified suppliers from European procurement networks.
Growth Catalysts
- E-commerce fulfillment surge:Padded mailer demand from logistics hubs is pulling kraft linerboard volumes into envelope-grade specifications.
- REACH chemical compliance:EU substance restrictions favor mills with chain-of-custody documentation, creating preferential access for certified operators.
- Automated insertion systems:Direct-mail agencies are retooling for high-speed wove grades that reduce jam rates and labor touchpoints.
Market Restraints
- Pulp input volatility:Northern bleached softwood kraft price swings compress margin predictability for non-integrated converters.
- Digital substitution pressure:Electronic billing and virtual document workflows erode transactional envelope volumes in corporate accounts.
- Recycling contamination limits:MRF operators reject mixed-fiber padded mailers, constraining post-consumer feedstock availability for mills.
Strategic Opportunities
- Extended producer responsibility schemes:France's packaging waste regulations create first-mover advantage for fiber-based alternatives to plastic mailers.
- Pharmaceutical cold-chain compliance:Insulated paper-based envelopes with phase-change liners are penetrating temperature-sensitive drug distribution.
- Adhesive-free closure patents:Friction-lock and tear-strip mechanisms eliminate hot-melt application steps, reducing energy and VOC exposure.
Industry Challenges
- Calendering precision gaps:Thin-gauge specialty grades require surface smoothness tolerances that legacy equipment cannot hold consistently.
- Cross-border customs friction:FSC and PEFC certification recognition varies between national forest stewardship bodies, delaying shipment clearances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Envelope Paper Market |
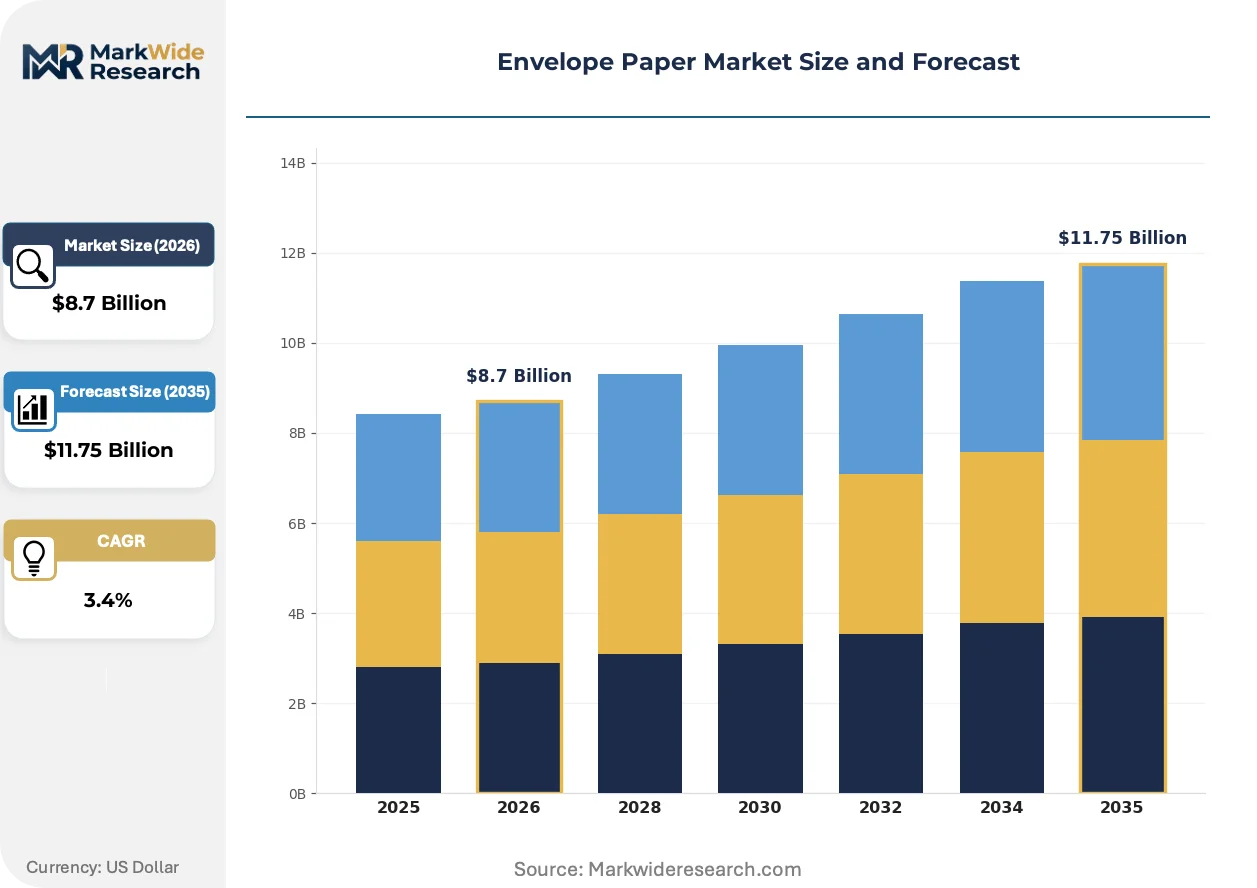
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wove, Laid, Kraft, Glassine Thickness: Heavyweight, Lightweight, Standard, Mediumweight Color: White, Brown, Neutrals, Pastels End User: Office Supplies, Retail, Packaging, Direct Mail |
| Companies Covered | Glatfelter, Cenveo Worldwide Limited, International Paper, Koehler Paper SE, Nippon Paper Industries, Mondi Group, LINTEC Corporation, WestRock, Domtar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Envelope Paper Market Emerging Trajectories
Material science advances and postal regulatory tightening are reconfiguring substrate specifications and closure mechanisms across commercial and protective mailer segments.
Water-based barrier coatings is converging with grease-resistant envelope applications, replacing polyethylene laminations that contaminate recycling streams. Food-contact and cosmetic sample distributors are specifying these grades for direct-mail campaigns. The structural consequence is compressing lead times for converters that maintain in-house coating capacity versus those sourcing treated stock externally.
EU Green Deal packaging waste targets are forcing minimum recycled content thresholds into national transposition laws. German postal procurement specifications now require 80% post-consumer fiber in standard white envelopes. Premium wove segments are responding with mass-balance accounting systems that track certified fiber through multi-supplier networks.
Consolidated buying desks at major retailers are unbundling envelope procurement from broader print services contracts. Direct negotiation with integrated mills is displacing distributor intermediaries for volume accounts. This pattern is most visible in North American e-commerce fulfillment, where Amazon and Walmart logistics teams specify mailer grades directly with International Paper and WestRock supply managers.
Envelope Paper Market Segmentation
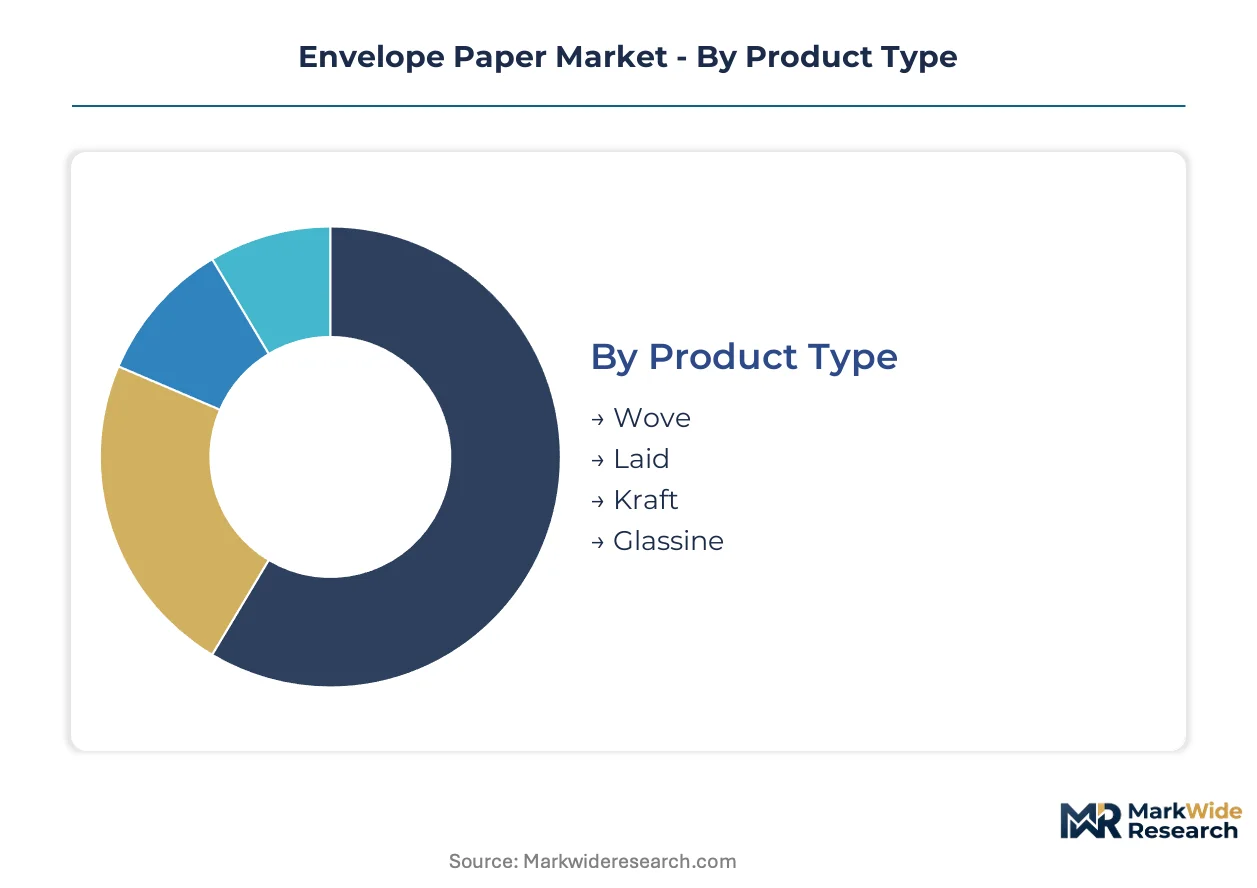
Envelope paper segmentation reveals how substrate specifications align with divergent performance requirements across postal automation, brand aesthetics, and sustainability mandates. Understanding these category boundaries enables procurement teams to match grade selection with insertion line compatibility and recycling stream compliance.
Product Type:
Surface texture and fiber composition define machinability, print receptivity, and tear resistance across postal and fulfillment applications.
- Wove:Uniform, smooth surface formed on woven wire mesh delivers high-resolution print fidelity for direct-mail campaigns. German postal automation lines specify wove grades for optical character recognition compatibility at insertion speeds exceeding 30,000 units per hour.
- Kraft:Unbleached long-fiber pulp construction provides tear strength and puncture resistance for padded mailers. E-commerce fulfillment centers in the United States specify kraft linerboard converted to self-seal mailers to meet retailer sustainability scorecards demanding 100% recyclable substrates.
- Laid:Chain-line watermark pattern from laid wire manufacturing conveys premium document presentation. Legal and financial correspondence in the United Kingdom retains laid stock for ceremonial contracts despite higher unit costs.
- Glassine:Dense, translucent sheet produced through supercalendering offers grease resistance and moisture barrier properties. Pharmaceutical sample distribution in France specifies glassine windows for tamper-evident unit-dose packaging.
Kraft leads on scale through e-commerce volume pull; glassine leads on momentum through pharmaceutical compliance expansion.
Thickness:
Basis weight selection directly determines postal tariff classification, insertion jam rates, and protective cushioning capacity.
- Lightweight:Sub-70 gsm constructions minimize dimensional-weight charges imposed by postal operators. Japanese direct-mail agencies specify lightweight wove to optimize per-piece postage economics on high-volume campaigns.
- Standard:70–90 gsm range balances rigidity with machinability for general business correspondence. Office supply distributors in Canada stock standard-weight white envelopes as the default SKU for corporate procurement contracts.
- Mediumweight:90–120 gsm grades provide enhanced opacity and handling stiffness for document sets. Australian government tender documents specify mediumweight stock to prevent show-through on multi-page submissions.
- Heavyweight:Exceeding 120 gsm, these grades accommodate rigid inserts and repeated handling cycles. Italian luxury goods houses commission heavyweight laid envelopes for event invitations and certificate presentation.
Standard thickness dominates procurement volume; lightweight configurations are climbing fastest under postal pricing pressure.
Color:
Color specification intersects with fiber sourcing, bleaching chemistry, and brand identity requirements.
- White:Fully bleached kraft or sulfite pulp provides maximum print contrast and color accuracy. Swedish retail chains specify optical-brightener-free white envelopes to align with Nordic Swan ecolabel restrictions.
- Brown:Unbleached natural kraft signals sustainability positioning without chemical processing. German packaging waste regulations favor brown kraft for single-use mailers through simplified recyclability certification.
- Neutrals:Beige, gray, and cream tones reduce bleaching intensity while maintaining professional presentation. Dutch financial services firms specify neutral-toned wove for client statements to differentiate from transactional white stock.
- Pastels:Tinted through stock dyeing or surface coating for seasonal campaigns and event marketing. Brazilian direct-mail agencies deploy pastel pink and blue envelopes for healthcare and infant product promotions.
White commands volume leadership through universal compatibility; brown is gaining share fastest under extended producer responsibility schemes.
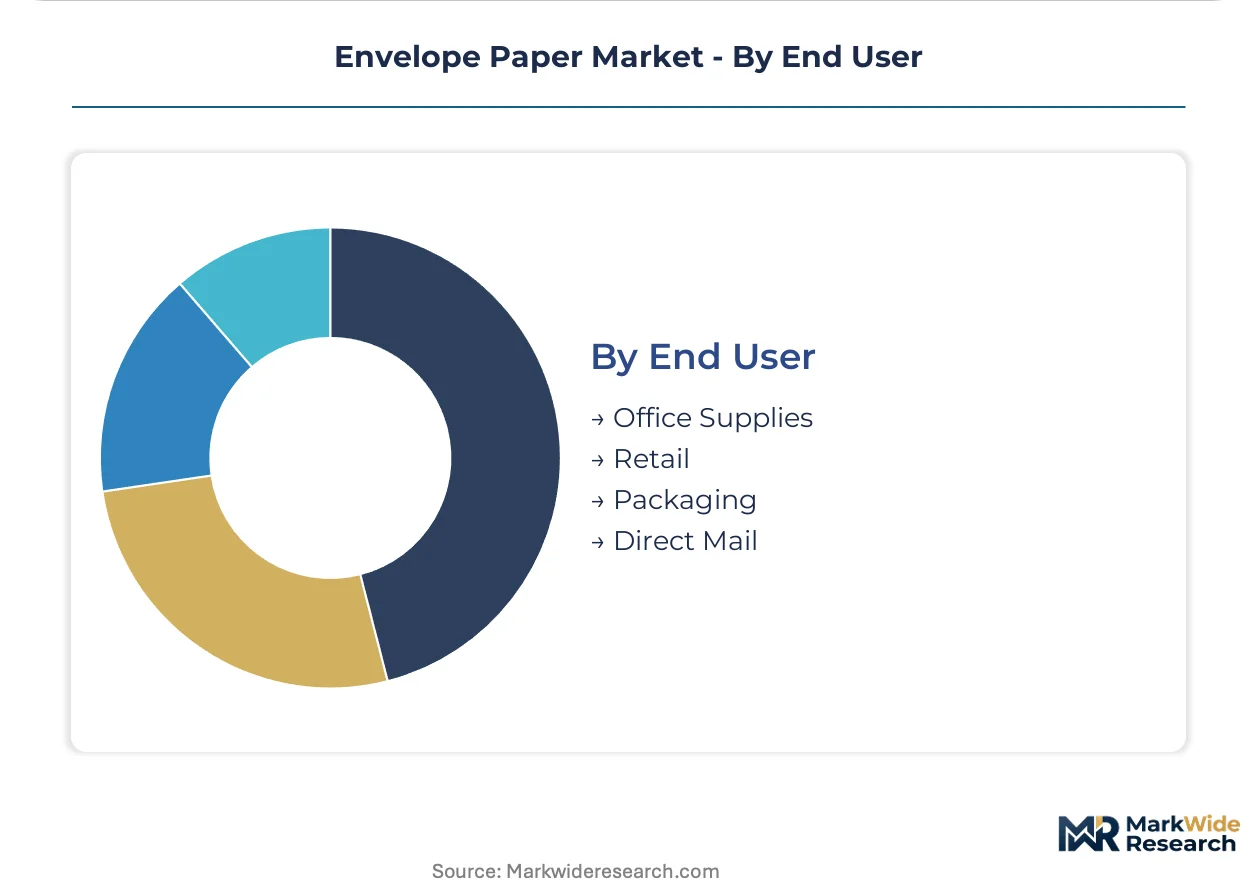
End User:
Demand concentration varies sharply between declining transactional segments and expanding protective packaging applications.
- Packaging:Converted mailers and padded envelopes for e-commerce shipment represent the steepest expansion trajectory. Fulfillment centers in the United States negotiate directly with integrated mills for kraft mailer specifications that satisfy Amazon and Walmart packaging guidelines.
- Direct Mail:Targeted advertising and statement mailings retain premium margin pools despite digital substitution. Variable-data printing capabilities in the United Kingdom enable hyper-personalized campaigns that sustain response-rate economics.
- Office Supplies:Standard business envelopes for internal correspondence and billing face structural decline. Corporate accounts in Canada accelerate electronic billing migration, compressing transactional envelope procurement volumes.
- Retail:Gift card carriers, loyalty program mailers, and promotional inserts require seasonal flexibility and rapid turnaround. French cosmetics distributors specify recyclable padded mailers for sample distribution under EU Green Deal packaging waste targets.
Packaging leads on momentum through e-commerce infrastructure buildout; direct mail retains margin leadership through personalization technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Envelope paper manufacturing originated in European papermaking centers during the 19th century, with industrial-scale production later scaling across North American pulp networks and Asian packaging hubs.
Germany
Postal automation mandates and EU Green Deal compliance requirements drive specification of 80% post-consumer fiber grades. REACH substance restrictions filter uncertified mills from procurement networks. The Rhine-Main industrial corridor hosts specialized converters engineering wove grades for insertion speeds exceeding 30,000 units per hour.
United States
E-commerce fulfillment centers specify kraft mailer grades directly with integrated mills to satisfy retailer sustainability scorecards. EPA forestry certification requirements elevate compliance costs for uncertified operations. The Southeast pulp belt sustains cost-advantaged supply chains for major logistics buyers.
Japan
Lightweight wove specifications optimize per-piece postage economics on high-volume direct-mail campaigns. METI standards govern fiber sourcing transparency for cross-border shipments. The Kanto region maintains precision calendering capacity for thin-gauge specialty grades.
France
Extended producer responsibility schemes create first-mover advantage for fiber-based alternatives to plastic mailers. ANSM pharmaceutical regulations drive glassine specifications for tamper-evident unit-dose packaging. The Île-de-France cluster concentrates cosmetics sample distribution operations.
China
Dual carbon goals and GB standards reshape material sourcing requirements for export-oriented converters. SAMR packaging waste directives align domestic production with EU import specifications. The Yangtze River Delta anchors integrated containerboard-to-converted-envelope operations serving cross-border e-commerce.
Envelope Paper Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and coating capability dimensions. The vendor base stratifies between integrated pulp-to-paper operators and non-integrated converters exposed to input volatility. Three archetypes dominate: North American integrated giants with captive pulp supply, European specialty mills with chain-of-custody documentation, and Asian scale producers serving regional packaging demand. Competitive moves concentrate on M&A for coating capacity and strategic partnerships for recycled fiber sourcing.
Among integrated North American operators, International Paper and WestRock occupy positions as scale-driven suppliers to major retailer logistics teams. Within the European specialty tier, Mondi Group exemplifies mills engineering kraft and wove grades for automated insertion compliance. Koehler Paper SE represents German precision manufacturers serving pharmaceutical and direct-mail specifications.
| Leading Market Players |
|---|
| Glatfelter |
| Cenveo Worldwide Limited |
| International Paper |
| Koehler Paper SE |
| Nippon Paper Industries |
| Mondi Group |
| LINTEC Corporation |
| WestRock |
| Domtar |
| Others |
Supply Flow & Price Mechanics
Captive pulp supply from integrated North American operators anchors both cost position and contract pricing power against spot-market-exposed converters. This backward integration into kraft linerboard production insulates major suppliers from Northern bleached softwood kraft volatility while enabling multi-year offtake agreements with Amazon and Walmart logistics teams. EU REACH compliance costs filter uncertified mills from German procurement networks, concentrating pricing leverage among chain-of-custody-certified operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified wove grades for pharmaceutical direct-mail from commodity kraft mailer specifications. Price differentiation centers on certification tier and volume scale, with automated insertion-compatible grades commanding premiums over general correspondence stock. Cost compression in lightweight segments is intensifying because postal operators impose dimensional-weight penalties that favor substrate downgauging. E-commerce fulfillment buyers exhibit highest price sensitivity, while pharmaceutical sample distributors prioritize compliance documentation over unit cost.
Supply Chain Analysis
Pulp supply rests on Canadian and Scandinavian softwood forests, with kraft linerboard feedstock drawing from Southeastern US containerboard mills. Chemical additive dependencies include sizing agents, optical brighteners, and water-based barrier coatings subject to EU REACH substance restrictions. Single-source vulnerability concentrates in specialty calendering equipment for thin-gauge wove grades, where German and Japanese engineering houses dominate precision manufacturing. Distribution runs through integrated mill-direct channels for volume accounts, with distributor intermediaries retaining role in seasonal retail and small-format office supply procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal packaging waste targets and extended producer responsibility schemes generate structural demand pull for certified fiber-based alternatives to plastic mailers.
For Market Incumbents: Extend coating capacity investments to capture water-based barrier specification demand from food-contact and cosmetic sample distributors. Defensive consolidation should prioritize automated insertion-compatible wove grade producers in the Rhine-Main corridor to secure pharmaceutical direct-mail positioning against emerging Asian specialty mills. Certification investment in mass-balance accounting systems represents the critical lever for maintaining German postal procurement eligibility under tightening recycled content thresholds.
For New Entrants and Emerging Players: Pharmaceutical cold-chain distributors represent an underserved buyer archetype seeking insulated paper-based envelopes with phase-change liner integration. White-space entry should target French cosmetics sample distribution networks where ANSM regulations drive glassine specifications and incumbent capacity constraints create procurement bottlenecks. Go-to-market positioning through adhesive-free closure patent licensing offers differentiation without capital-intensive calendering equipment investment.
For Investors and Strategic Acquirers: Roll-up economics work for European specialty converters because fragmented ownership of coating capacity and chain-of-custody documentation creates consolidation synergies. Long-term viability over the mid-decade horizon hinges on positioning within EU Green Deal-compliant supply chains as extended producer responsibility schemes expand beyond France and Germany. Acquisition targets should exhibit mass-balance fiber tracking capabilities and in-house water-based barrier coating lines. The signal to watch is German postal operator specification tightening on post-consumer fiber thresholds, which will accelerate capacity obsolescence among uncertified operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Linerboard | Captive pulp supply insulates margin from spot volatility and secures retailer sustainability scorecard compliance. |
| Water-Based Barrier Coating Capacity Expansion | In-house coating capability compresses lead times versus external sourcing for EU Green Deal-aligned food-contact specifications. |
| Mass-Balance Certification Investment | Chain-of-custody documentation unlocks German postal procurement requiring 80% post-consumer fiber thresholds. |
| Adhesive-Free Closure Patent Development | Friction-lock mechanisms eliminate hot-melt energy costs and VOC exposure while differentiating against conventional self-seal mailers. |
| Automated Insertion Grade Engineering | Wove grades optimized for 30,000 units per hour compatibility capture direct-mail agency retooling demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with mill procurement managers, direct-mail agency operations directors, postal operator specification engineers, and pharmaceutical packaging compliance leads with secondary validation. Secondary sources included customs and trade data for kraft linerboard flows, SEC filings from integrated paper producers, EU ECHA REACH substance restriction updates, and German postal procurement specification documents. Bottom-up grade-level volume estimates triangulated against top-down market sizing from pulp production and conversion capacity data.
Segment-weighting across product type, thickness, color, and end-user dimensions informed the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of postal automation adoption, e-commerce fulfillment infrastructure buildout, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated dimensional-weight pricing implementation schedules and extended producer responsibility scheme rollout timelines across EU member states.
Inputs from trade associations and regulatory filings were available through the study window; gaps in real-time postal operator procurement specification updates introduce uncertainty bands around adoption rate assumptions. Forecasts reflect documented assumptions on fiber substitution elasticities and recycling stream contamination limits. A small set of triggers including REACH substance restriction amendments and postal tariff reclassification warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
France Paper Packaging Market