
 Vinyl Electrical Tapes Market | 2026-2036
Vinyl Electrical Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Electrical Tapes Market Analytics
The capital-intensity divergence between integrated film-coating operations and commodity converters is unwinding competitive stability across the vinyl electrical tapes sector. 3M Company leverages captive resin compounding and multilayer extrusion capacity to sustain premium positioning in flame-retardant grades. Nitto Denko Corporation anchors its position through precision adhesive formulation leadership serving Japanese automotive OEMs. Avery Dennison Corporation competes via global distribution density and private-label partnerships with regional electrical distributors.
Vinyl electrical tapes are pressure-sensitive adhesive tapes constructed from plasticized polyvinyl chloride film backing coated with synthetic rubber or acrylic adhesives, engineered to provide electrical insulation, mechanical protection, and moisture sealing across operating temperatures typically ranging from -18°C to 105°C. These tapes serve critical functions in wire harnessing, cable jacket repair, and phase identification within electrical infrastructure and transportation systems. Insulating tapes occupy the largest volume share due to universal deployment in building and utility maintenance, while flame-retardant technology commands superior margins driven by stringent safety codes in commercial construction and mass transit applications. Pressure-sensitive technology dominates manufacturing throughput, though high-temperature formulations are expanding fastest as electric vehicle power electronics and charging infrastructure demand thermal resilience beyond conventional PVC limits.
UL 510 certification requirements in the United States, CE marking under the EU Low Voltage Directive, and China's GB/T 13542 standards collectively define product compliance thresholds that filter market access and shape R&D investment priorities. The EPA's evolving stance on phthalate plasticizers and REACH restrictions on certain chlorinated compounds are pressuring reformulation toward non-phthalate plasticizer systems and bio-based alternatives. Stakeholders must monitor regulatory divergence between jurisdictions while evaluating adhesive platform transitions that preserve electrical and mechanical performance across increasingly segmented end-use specifications.
Market Dynamics
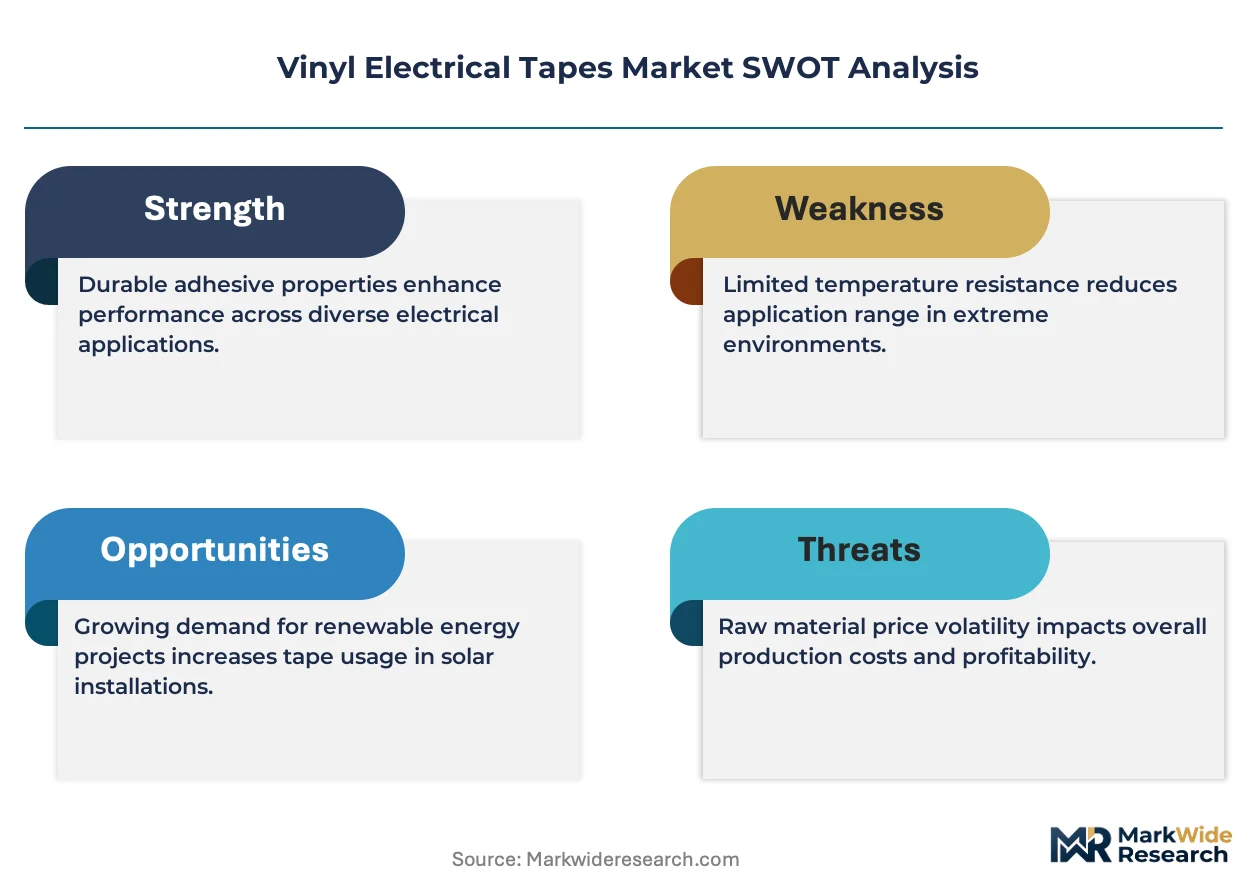
Electric vehicle wire harnessing is accelerating tape consumption intensity beyond historical norms, while phthalate plasticizer restrictions under EPA and REACH frameworks are forcing adhesive reformulation investments that favor integrated compounders over commodity converters.
Growth Catalysts
- Electric vehicle power electronics:High-voltage battery systems and motor controllers require thermal-grade insulation tapes rated above 105°C, expanding addressable specifications for manufacturers with multilayer extrusion capabilities.
- China's GB/T 13542 tightening:Certification requirements for electrical insulation materials are filtering out regional converters, consolidating procurement toward certified suppliers serving Southeast Asian electronics clusters.
- Flame-retardant building codes:Commercial construction safety mandates in mass transit and high-occupancy structures are displacing standard-grade tapes with halogen-free and low-smoke formulations.
Market Restraints
- Plasticizer input volatility:Epoxidized soybean oil and non-phthalate alternatives trade at premiums to traditional DINP/DIDP, compressing margins for non-integrated converters dependent on spot resin markets.
- Resin supply concentration:Specialty PVC suspension resins for electrical-grade films concentrate among Asian petrochemical complexes, exposing Western tape manufacturers to freight and duty cost swings.
- Silicone tape substitution:High-temperature applications above 150°C increasingly specify silicone self-fusing tapes, capping PVC tape expansion in aerospace and heavy industrial maintenance.
Strategic Opportunities
- India's electronics manufacturing incentives:PLI scheme subsidies for mobile phone and component production are concentrating assembly capacity near Noida and Chennai, creating localized demand for wire harnessing tapes.
- Recyclable mono-material construction:Single-polymer tape designs compatible with automated sorting and mechanical recycling align with EU Green Deal circular economy mandates and brand sustainability commitments.
- Digital distributor platforms:Electrical supply marketplaces are disintermediating traditional two-step distribution, enabling direct manufacturer relationships with mid-sized industrial maintenance contractors.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation expertise bridging acrylic, synthetic rubber, and hot-melt platforms is concentrating at integrated compounders, constraining independent converter R&D velocity.
- Multi-jurisdiction certification timelines:Simultaneous UL 510, CE marking, and GB standard compliance requires 18-24 month validation cycles, delaying product launches for specification-driven segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Electrical Tapes Market |
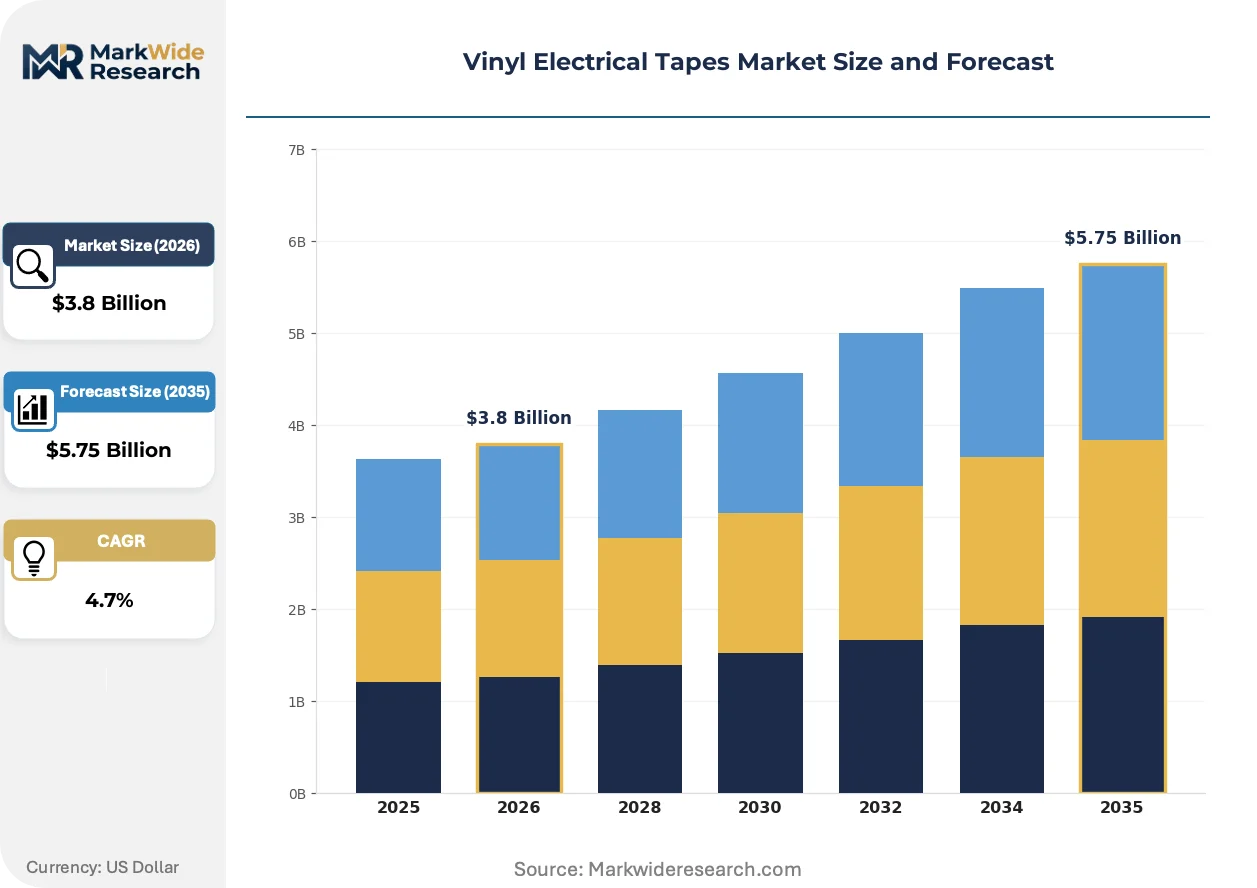
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Conductive, Insulating End User: Construction, Automotive, Electronics, HVAC Application: Wire Harnessing, Insulation, Bundling, Repair Technology: Pressure-Sensitive, Flame-Retardant, High-Temperature, Weather-Resistant |
| Companies Covered | 3M Company, Nitto Denko Corporation, Avery Dennison Corporation, HellermannTyton, Teraoka Seisakusho Co., Ltd., Plymouth Rubber Europa, S.A., Electro Tape Specialties, Inc., Parafix Tapes & Conversions Ltd, Pro Tapes & Specialties, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Electrical Tapes Market Evolving Landscape
Adhesive platform transitions and thermal performance upgrades are fragmenting product architectures, while regulatory divergence between jurisdictions is multiplying compliance SKUs and reshaping manufacturing footprints.
Multilayer co-extruded film constructions are decomposing the traditional single-layer PVC backing standard. Tier-1 automotive suppliers specify these structures for electric vehicle high-voltage harnesses requiring simultaneous flame retardancy, abrasion resistance, and hand-tearability. The technology is decomposing commodity converter margins by requiring captive extrusion assets that smaller regional players cannot replicate.
REACH Annex XIV authorization procedures for certain chlorinated plasticizers are accelerating substitution toward bio-based and non-phthalate systems. Compounders serving European OEMs must reformulate adhesive platforms without sacrificing tack retention or dielectric strength. German automotive harness manufacturers are qualifying Asian suppliers with pre-certified non-phthalate portfolios to compress validation timelines.
Maintenance procurement through integrated supply contracts is consolidating purchasing authority at national electrical distributors. Facility managers at US utility and transit operators now specify certified tape SKUs through preferred supplier agreements rather than spot market purchases. This concentration is visible across Midwestern utility cooperatives standardizing on flame-retardant grades with pre-negotiated volume pricing.
Vinyl Electrical Tapes Market Segmentation
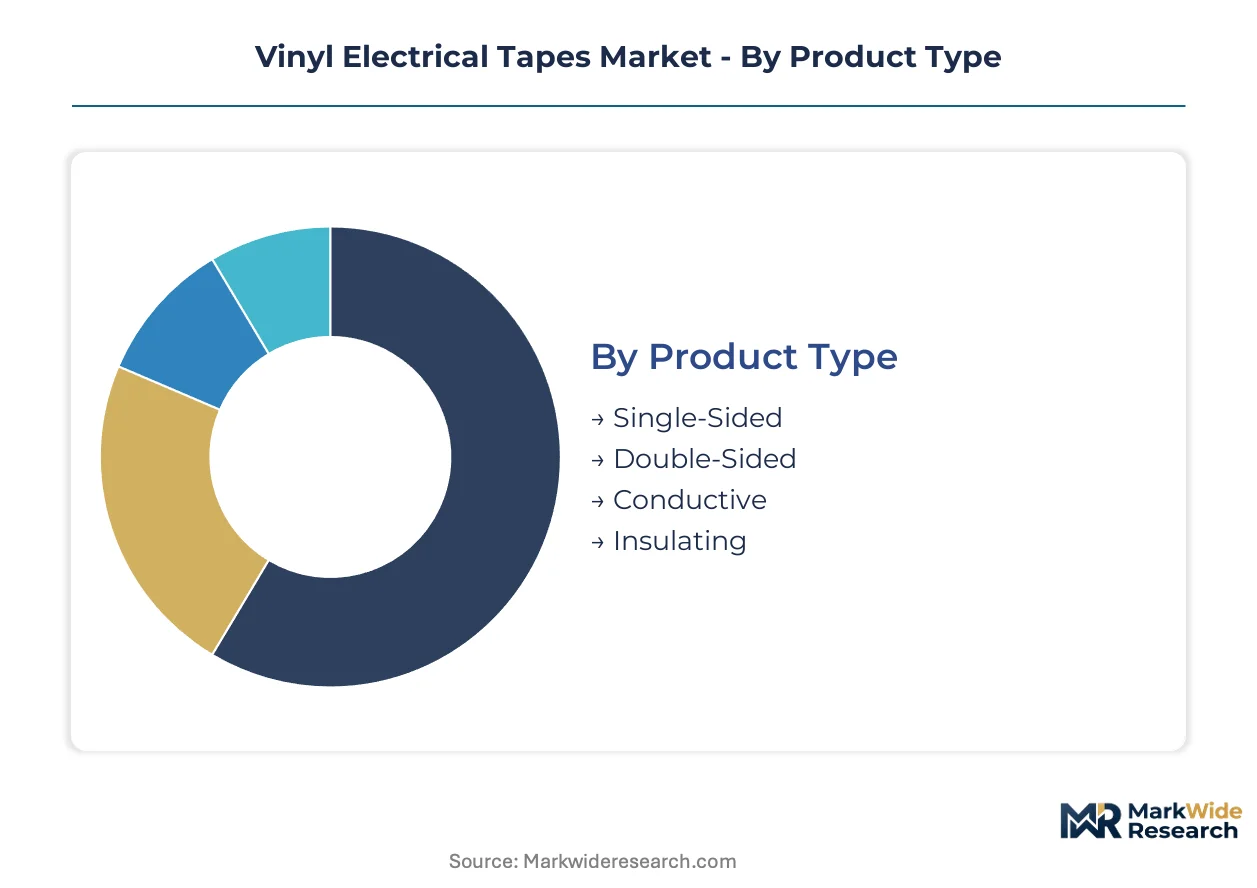
Segmentation in vinyl electrical tapes reveals divergent margin structures across adhesive platforms and end-use specifications. Product architecture and certification requirements fragment manufacturing economics, while application intensity varies sharply between mature building maintenance and emerging electric vehicle harnessing.
Product Type:
Domestic consumption concentrates in single-sided and insulating grades for building electrical work, while double-sided and conductive variants serve export-led electronics and automotive contract manufacturing.
- Single-Sided:Standard PVC film backing with one adhesive surface dominates volume throughput in building wire maintenance and general electrical repair. Demand concentrates in North American and European distributor inventories serving residential and commercial contractors, constrained by phthalate plasticizer reformulation costs.
- Insulating:Dielectric-grade formulations with specified breakdown voltage ratings anchor utility and industrial procurement specifications. Wire harnessing in electric vehicle manufacturing is accelerating consumption intensity beyond historical replacement-cycle norms.
- Double-Sided:Adhesive-coated both sides for bonding applications in electronics assembly and gasket fabrication.
- Conductive:Carbon-filled or metal-coated variants for EMI shielding and static dissipation in sensitive electronic environments.
Single-sided commands the established base. The steepest expansion runs through insulating grades.
End User:
Cost-tier stratification separates specification-driven automotive and electronics segments from price-sensitive construction and maintenance procurement.
- Automotive:OEM wire harness specifications demand flame-retardant and thermal-grade tapes with documented lot traceability. Electric vehicle high-voltage systems are expanding addressable specifications toward 125°C+ continuous operation ratings.
- Electronics:Precision adhesive tolerances and clean-room compatibility requirements concentrate procurement among certified Asian contract manufacturers. Southeast Asian assembly clusters are tightening incoming material certification under China's GB/T 13542 influence.
- Construction:Volume-driven procurement through electrical distributors serving residential and commercial building trades.
- HVAC:Refrigeration line insulation and motor lead protection in climate control equipment manufacturing.
Construction anchors volume throughput. Electronics and automotive segments are climbing the fastest on value per meter.
Application:
Application intensity per installation varies tenfold between simple jacket repair and complex multi-branch harnessing with phase identification requirements.
- Wire Harnessing:Systematic taping of bundled conductors with abrasion protection and moisture sealing. Electric vehicle power electronics demand multilayer constructions combining flame retardancy, thermal resilience, and hand-tearability.
- Insulation:Dielectric protection for splices and terminations in building and utility infrastructure. Mass transit and high-occupancy building codes are displacing standard grades with low-smoke halogen-free formulations.
- Bundling:Mechanical organization of cable runs without primary electrical insulation requirements.
- Repair:Field maintenance of damaged cable jackets in industrial and utility settings.
Insulation captures the replacement-driven core. Wire harnessing is gaining share fastest on electric vehicle production scaling.
Technology:
Technology platforms fragment by thermal ceiling and regulatory compliance burden, with premium formulations requiring captive compounding assets.
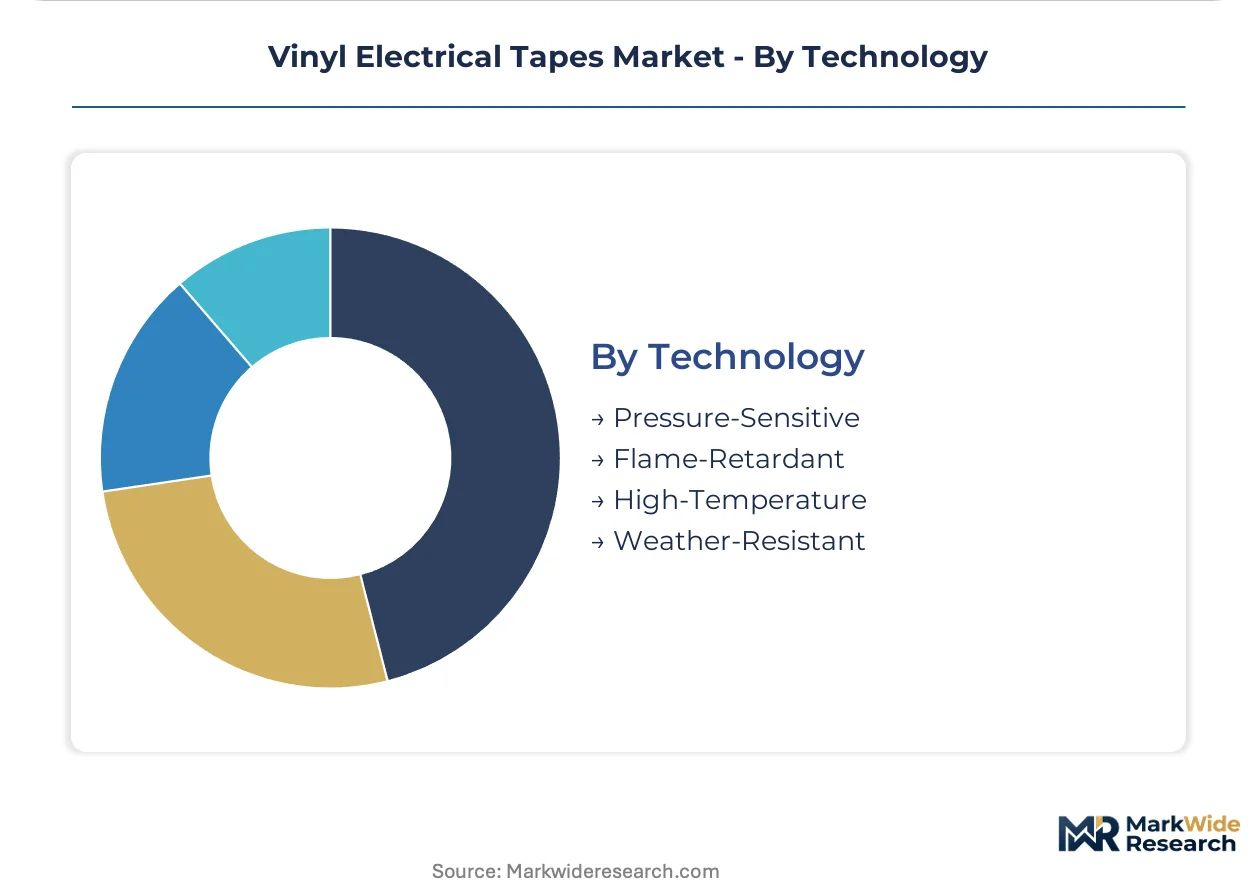
- Pressure-Sensitive:Acrylic or synthetic rubber adhesive systems applied without heat activation dominate manufacturing throughput and SKU proliferation. Building maintenance and general electrical work concentrate demand in mature distributor channels.
- Flame-Retardant:Halogen-free and low-smoke formulations command specification premiums in commercial construction, mass transit, and data center applications. REACH restrictions on chlorinated compounds are forcing adhesive platform transitions at integrated compounders.
- High-Temperature:Formulations rated above 105°C continuous operation for electric vehicle inverters and charging infrastructure. Silicone tape substitution above 150°C caps PVC expansion in aerospace and heavy industrial segments.
- Weather-Resistant:UV-stable plasticizer systems and adhesive platforms for outdoor utility and telecommunications applications.
Pressure-sensitive technology holds the volume base. Flame-retardant and high-temperature segments are expanding most quickly on code tightening and electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in vinyl electrical tapes tilt toward net importing in Western industrial economies while Asian manufacturing clusters generate trade surpluses. Freight costs and duty exposure from specialty PVC resin concentration in Asian petrochemical complexes reshape procurement geography. Certification divergence between UL 510, CE marking, and China's GB/T 13542 standards fragments regional product specifications and validation timelines.
United States
Utility infrastructure maintenance and electric vehicle assembly plants in Michigan, Tennessee, and South Carolina drive insulating tape consumption. EPA scrutiny of phthalate plasticizers under TSCA forces reformulation investments at compounders serving distributor channels. Midwestern utility cooperatives concentrate procurement through standardized flame-retardant SKU agreements with national electrical distributors.
Germany
Automotive wire harness manufacturers for premium OEMs specify thermal-grade tapes rated above 105°C continuous operation. REACH Annex XIV authorization procedures for chlorinated plasticizers accelerate adhesive platform transitions toward bio-based alternatives. Industrial clusters in Baden-Württemberg and Bavaria qualify Asian suppliers with pre-certified non-phthalate portfolios to compress validation cycles.
China
GB/T 13542 tightening for electrical insulation materials filters out regional converters and consolidates procurement toward certified suppliers. Yangtze River Delta and Pearl River Delta electronics manufacturing clusters absorb tape volumes for export-led wire harnessing and cable assembly. MIIT oversight of product certification aligns with dual carbon goals pressuring sustainable material transitions.
India
PLI scheme subsidies for mobile phone and component production concentrate assembly capacity near Noida and Chennai, generating localized wire harnessing tape demand. BIS certification requirements for electrical insulation materials create compliance barriers for uncertified imports. Domestic converter capacity expansion lags behind electronics manufacturing growth, sustaining import dependence for specification-grade products.
Japan
Precision adhesive tolerances for automotive OEM supply chains anchor demand for high-performance insulating grades. METI guidance on chemical substance management influences plasticizer selection in adhesive formulations. Kansai and Chubu industrial corridors maintain captive relationships between harness manufacturers and tape compounders with JIS-standard certification.
Vinyl Electrical Tapes Market Competitive Landscape
Concentration sits with integrated compounders possessing captive resin compounding and multilayer extrusion assets that commodity converters cannot replicate. The vendor base stratifies across three tiers: multinational chemical conglomerates with full backward integration, regional specialists with formulation expertise but dependent resin sourcing, and price-focused distributors private-labeling undifferentiated grades. Dominant competitive moves include capacity expansion in Southeast Asian tape finishing facilities and strategic partnerships between compounders and automotive harness manufacturers to compress qualification timelines.
Among diversified materials conglomerates, 3M Company and Nitto Denko Corporation exemplify the integrated compounder archetype through control over adhesive formulation and film backing production. Avery Dennison Corporation occupies a position bridging formulation capability with global distribution density. Regional specialists including HellermannTyton and Teraoka Seisakusho Co., Ltd. represent the precision-application tier serving specification-driven automotive and electronics segments with certified product portfolios.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| HellermannTyton |
| Teraoka Seisakusho Co., Ltd. |
| Plymouth Rubber Europa, S.A. |
| Electro Tape Specialties, Inc. |
| Parafix Tapes & Conversions Ltd |
| Pro Tapes & Specialties, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between integrated compounders and automotive harness manufacturers lock in both specialty PVC resin access and price visibility across multiyear production cycles. These contracts insulate Tier-1 suppliers from spot market volatility in epoxidized soybean oil and non-phthalate plasticizer alternatives while compressing margin flexibility for non-integrated regional converters dependent on distributor spot purchases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in vinyl electrical tapes. Price differentiation rests on UL 510 certification grade and volume scale, with flame-retardant thermal-grade formulations commanding substantial premiums over commodity insulating grades. Cost compression in the economy tier is intensifying because regional converters face stranded inventory from phthalate reformulation mandates. Construction distributors exhibit highest price sensitivity, while automotive harness manufacturers prioritize lot traceability and certification continuity over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among Western tape manufacturers facing resin supply concentration in China, South Korea, and Japan. Specialty PVC suspension resins for electrical-grade films draw from Asian petrochemical complexes, exposing non-integrated compounders to tariff exposure from duty swings on imported resin. Distribution runs through national electrical distributors consolidating procurement authority under integrated supply contracts with utility and transit operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone self-fusing tape substitution above 150°C threatens PVC tape expansion in aerospace and heavy industrial maintenance, forcing incumbents to defend specification-driven segments through thermal performance upgrades and certification moats.
For Market Incumbents: Compound formulation expertise in non-phthalate adhesive platforms to offset REACH Annex XIV pressure on chlorinated plasticizers. Expand captive multilayer extrusion capacity in Southeast Asian tape finishing facilities to serve China's GB/T 13542 tightening. Deepen backward integration into specialty resin compounding to isolate margin compression from spot plasticizer markets. For New Entrants and Emerging Players: Pre-certified non-phthalate portfolios offer a certification fast-track for qualification with German automotive harness manufacturers seeking compressed validation timelines. Target India's PLI-subsidized electronics clusters near Noida and Chennai where domestic converter capacity lags behind wire harnessing demand. Pursue direct relationships with digital distributor platforms disintermediating traditional two-step electrical supply channels. For Investors and Strategic Acquirers: Capital is best deployed toward integrated compounders with captive resin production and multilayer extrusion assets that commodity converters cannot replicate. Long-term viability hinges on exposure to electric vehicle power electronics specifications requiring 125°C+ continuous operation ratings. Watch for inflection when GB standard harmonization accelerates cross-border certification consolidation among Asian suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of specialty PVC suspension resins insulates margin from Asian petrochemical price swings. |
| Non-Phthalate Adhesive Platform Transition | REACH-compliant formulations preserve European OEM access without sacrificing dielectric performance. |
| Southeast Asian Capacity Expansion | Regional tape finishing facilities compress logistics costs for China's Yangtze River Delta electronics clusters. |
| Pre-Certified Portfolio Development | Simultaneous UL 510, CE marking, and GB standard readiness shortens 18-24 month validation cycles. |
| Digital Distributor Platform Partnership | Direct manufacturer relationships with mid-sized industrial maintenance contractors bypass traditional channel markups. |
Research Methodology
Cross-validation between primary interviews with tape compounders, automotive harness procurement leads, and electrical distributor category managers anchors the qualitative findings. Secondary validation draws from customs trade data, SEC filings of diversified materials conglomerates, and MIIT certification registries. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across adhesive platform transitions and thermal performance upgrades.
Sensitivity analysis tests forecast robustness across the projection horizon against plasticizer input volatility and electric vehicle production scaling assumptions. Segmentation dimensions modeled include adhesive technology, thermal rating tier, end-use industry, and regional certification cluster. CAGRs derive from regression analysis of historical consumption intensity patterns and forward-looking specification shifts in wire harnessing applications.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle penetration or accelerated silicone tape substitution would require recalibration. Forecasts reflect documented assumptions on resin supply concentration and regulatory divergence timelines. Revision becomes warranted when GB standard harmonization or REACH Annex XIV expansion crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Holographic Tear Tape Market
Tapes
Acoustic Tape Market
Tapes
Custom Printed Tape Market
Tapes
Splicing Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Aerospace Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Release Tape Market
Tapes
Acetate Cloth Tape Market
Tapes
Tapes Market
Tapes
Breathable Tape Market
Tapes
Paper Gummed Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Duct Tapes Market
Tapes
Washi Tapes Market