
 Europe Packaging Tapes Market | 2026-2036
Europe Packaging Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Packaging Tapes Market Foresight
German adhesive tape production is restructuring around solvent-free coating lines and recycled-content backings to meet circular-economy mandates. Tesa SE leverages its Stuttgart R&D base to sustain technology leadership in thin-film acrylic systems for precision electronics bundling. Henkel AG & Co. KGaA anchors European supply through its Düsseldorf headquarters and broad hot-melt adhesive portfolio. Avery Dennison differentiates via specialized pressure-sensitive tapes for pharmaceutical cold-chain integrity.
Europe packaging tapes comprise flexible substrates coated with pressure-sensitive adhesives, typically measuring 25–75 micrometers in total caliper, designed to seal corrugated fiberboard cases and unitize palletized loads through shear-resistant bonding. Polypropylene dominates material consumption due to its tensile strength and cost efficiency in high-volume logistics, while paper tapes gain share in retail and food-service channels seeking plastic reduction. Water-based acrylic adhesives lead the adhesive-type split because of favorable emissions profiles under REACH and F-Gas Regulation compliance, though hot-melt systems retain volume in automated e-commerce fulfillment where instant bond formation matters.
EMA and ECHA frameworks govern chemical migration limits and substance restrictions in tapes contacting food and pharmaceuticals, while the EU Packaging and Packaging Waste Regulation mandates recyclability design standards that reshape substrate and adhesive selection. CE marking requirements under the Construction Products Regulation also influence industrial-grade tape specifications for heavy-load strapping applications. Stakeholders must monitor how the EU Green Deal's evolving extended-producer-responsibility rules will redefine cost structures for multi-layer tape constructions that complicate mechanical recycling streams.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing substrate and adhesive redesign across European converting operations, compressing development cycles as recyclability mandates harden into enforceable standards.
Growth Catalysts
- E-commerce automation:Automated fulfillment centers in Germany and the Netherlands consume pressure-sensitive tapes at throughput velocities that sustain volume expansion across polypropylene and paper-backed formats.
- REACH compliance:Water-based acrylic adhesive systems gain preferential positioning as converters eliminate solvent-borne chemistries to meet emissions thresholds under the F-Gas Regulation.
- Pharmaceutical cold-chain:Temperature-indicating and tamper-evident tape formats penetrate secondary packaging for biologics distribution, driven by EMA serialization requirements.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices oscillate with naphtha and propylene monomer contract movements, compressing converter margins on standard-grade carton-sealing tapes.
- Recyclability design constraints:Multi-layer laminates combining polyethylene facestocks with hot-melt adhesives face mechanical recycling rejection under emerging EU extended-producer-responsibility sorting protocols.
- Paper tape performance ceiling:Cellulose-based backings exhibit moisture sensitivity and lower tensile modulus that limits substitution rates in heavy-load pallet unitization.
Strategic Opportunities
- Mono-material construction:All-polypropylene tape systems with compatible adhesive chemistries qualify for closed-loop recycling streams under revised EU Packaging and Packaging Waste Regulation design-for-recycling criteria.
- Poland and Czech Republic manufacturing:Greenfield coating capacity in Central European logistics corridors captures automotive and electronics export packaging demand with lower labor cost structures than Western European sites.
- Digital print integration:Variable-data printing on tape surfaces enables brand authentication and supply-chain traceability, converging security functions with primary sealing applications.
Industry Challenges
- Adhesive formulation expertise:Shortages of polymer chemists familiar with UV-curable and bio-based hot-melt systems constrain R&D throughput at mid-sized European converters.
- CE marking complexity:Industrial strapping tapes for construction applications face extended conformity assessment timelines under the Construction Products Regulation, delaying commercialization of high-tensile grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Packaging Tapes Market |
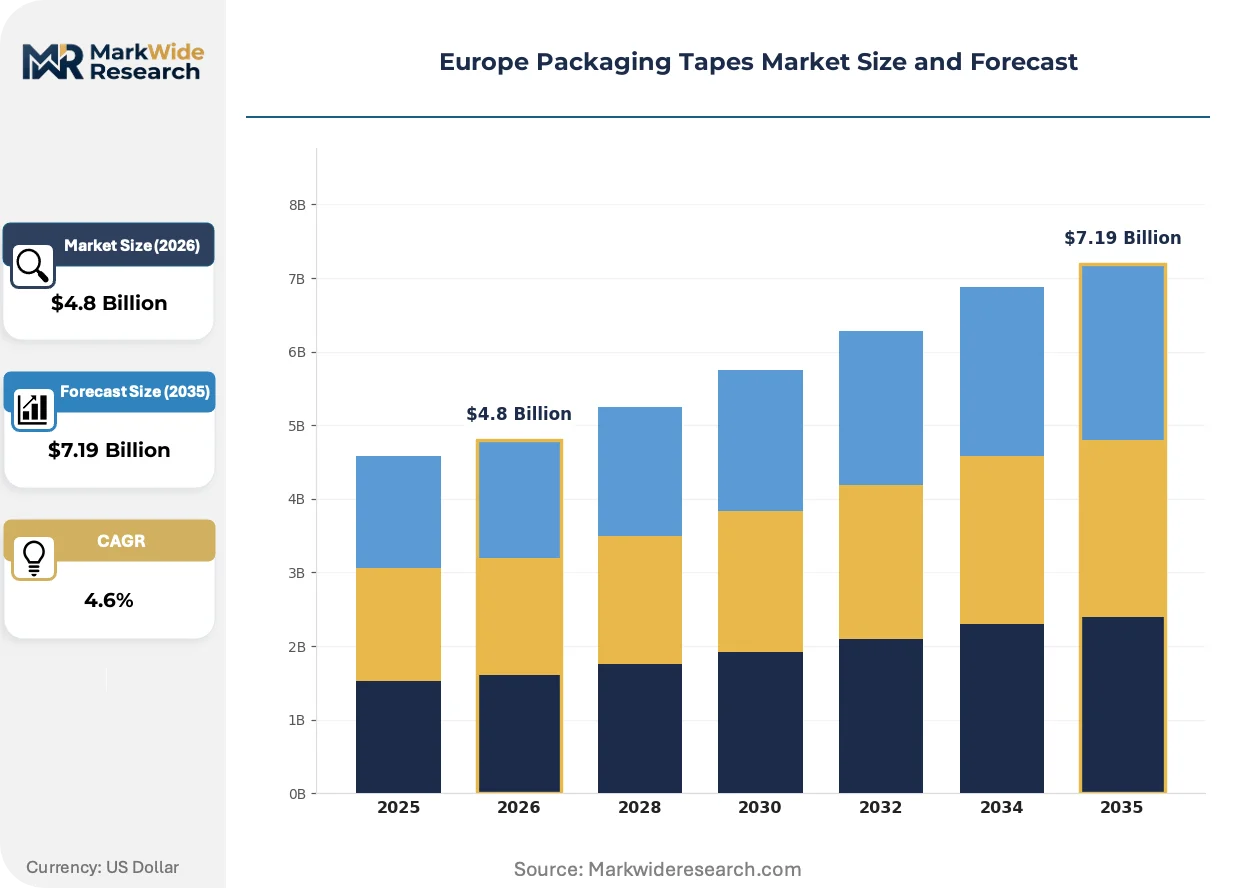
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, PVC, Paper, Cotton Application: E-commerce, Retail, Logistics, Manufacturing Adhesive Type: Hot Melt, Water-Based, Solvent-Based, Acrylic End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics |
| Companies Covered | 3M, Avery Dennison, Henkel AG & Co. KGaA, Nitto Denko Corporation, Tesa SE, Intertape Polymer Group, Berry Global, Scapa Group, Advance Tapes International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Packaging Tapes Market Shifts & Advancements
Adhesive chemistry and substrate engineering are converging around circular-economy specifications, with regulatory pressure and brand-owner sustainability commitments accelerating format experimentation beyond traditional polypropylene dominance.
Thin-film acrylic systems with sub-25-micrometer calipers are unifying precision electronics bundling with reduced material intensity. Stuttgart-area R&D clusters prototype these formats for automotive sensor packaging and medical device kitting. The technology is compressing adhesive consumption per sealed unit while maintaining shear resistance under temperature cycling.
REACH substance restrictions and the EU Green Deal's packaging waste targets are mandating solvent-free coating line conversions. German and French converters retrofit thermal drying systems to UV or electron-beam curing to eliminate volatile organic compound emissions. Pharmaceutical and food-contact tape grades face the steepest compliance timelines under ECHA substance evaluation protocols.
Consolidated buying desks at pan-European e-commerce platforms now specify performance metrics rather than product codes, compressing supplier lists to converters with documented carbon footprints and recyclability certifications. This specification shift favors integrated manufacturers with in-house extrusion and coating capabilities over merchant adhesive buyers. The pattern is most pronounced in German and Benelux distribution hubs serving cross-border fulfillment networks.
Europe Packaging Tapes Market Segmentation
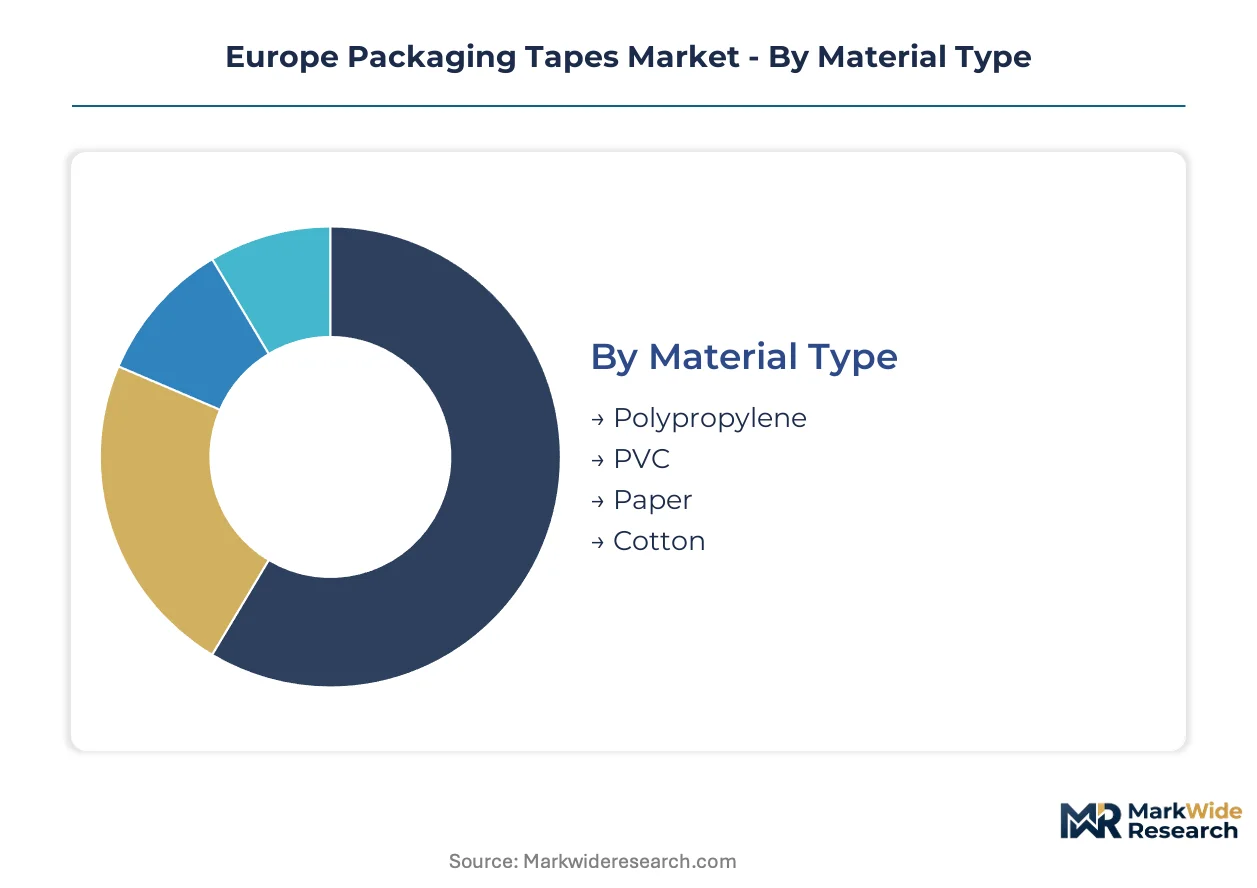
Packaging tape procurement in Europe splits across material science, adhesive chemistry, and end-use compliance requirements. Buyers prioritize tensile performance, recyclability credentials, or regulatory clearance depending on their operational environment.
Material Type:
Cost sensitivity and circular-economy mandates differentiate buyers across substrate selection.
- Polypropylene:Biaxially oriented polypropylene film delivers tensile strength above 30 N/cm with moisture resistance for pallet unitization. German automotive export hubs consume this grade for heavy-load strapping where shear resistance under temperature cycling matters. REACH compliance favors its mono-material recyclability against multi-layer alternatives.
- Paper:Kraft paper backings with reinforced fiberglass threads serve retail and food-service channels seeking plastic reduction under EU Packaging and Packaging Waste Regulation. Moisture sensitivity limits substitution rates in Benelux distribution centers with uncontrolled humidity.
- PVC:Polyvinyl chloride film retains share in pharmaceutical serialization tapes requiring tamper-evident fracture patterns. ECHA substance evaluation protocols constrain new capacity investment.
- Cotton:Woven cotton fabric backings supply premium hand-tearable formats for artisanal food packaging and craft retail. French organic certification schemes drive niche specification.
Volume sits with polypropylene; growth tilts toward paper.
Application:
Automation intensity and throughput velocity shape specification requirements.
- E-commerce:Automated case sealers operating at 40+ cartons per minute demand hot-melt adhesive systems with instant tack and clean release. Dutch fulfillment centers specify low-noise unwinding for operator ergonomics at high velocity.
- Logistics:Cross-dock operations and pallet consolidation favor polypropylene tapes with synthetic rubber adhesives for cold-temperature adhesion. Polish freight corridors prioritize cost efficiency over premium performance grades.
- Retail:Shelf-ready packaging and display sealing use printable paper tapes with water-based acrylics for brand presentation. Scandinavian retailers mandate carbon footprint documentation upstream.
- Manufacturing:In-process bundling of components and subassemblies requires clean-removal tapes that leave no residue on painted or plated surfaces. Stuttgart-area automotive suppliers specify silicone-free formulations.
E-commerce commands the largest throughput volumes; manufacturing applications show the steepest expansion trajectory for specialized grades.
Adhesive Type:
Emissions compliance and bond formation speed determine chemistry selection.
- Water-Based:Acrylic emulsion adhesives dominate food-contact and general packaging under F-Gas Regulation emissions thresholds. French converters retrofit thermal drying lines to reduce volatile organic compound output.
- Hot Melt:Synthetic rubber block copolymers deliver instant tack for automated e-commerce lines where dwell time is minimal. German coating operations face feedstock volatility in styrene-isoprene-styrene resins.
- Acrylic:Solvent-free UV-curable acrylics serve precision electronics bundling with optical clarity and aging resistance. EMA migration limits govern pharmaceutical contact applications.
- Solvent-Based:Natural rubber solutions in hydrocarbon carriers retain niche use for extreme-temperature logistics. REACH authorization requirements restrict new formulation deployment.
Water-based systems hold volume leadership; UV-curable acrylics are gaining share fastest in premium segments.
End User:
Regulatory scrutiny and product integrity requirements stratify demand.
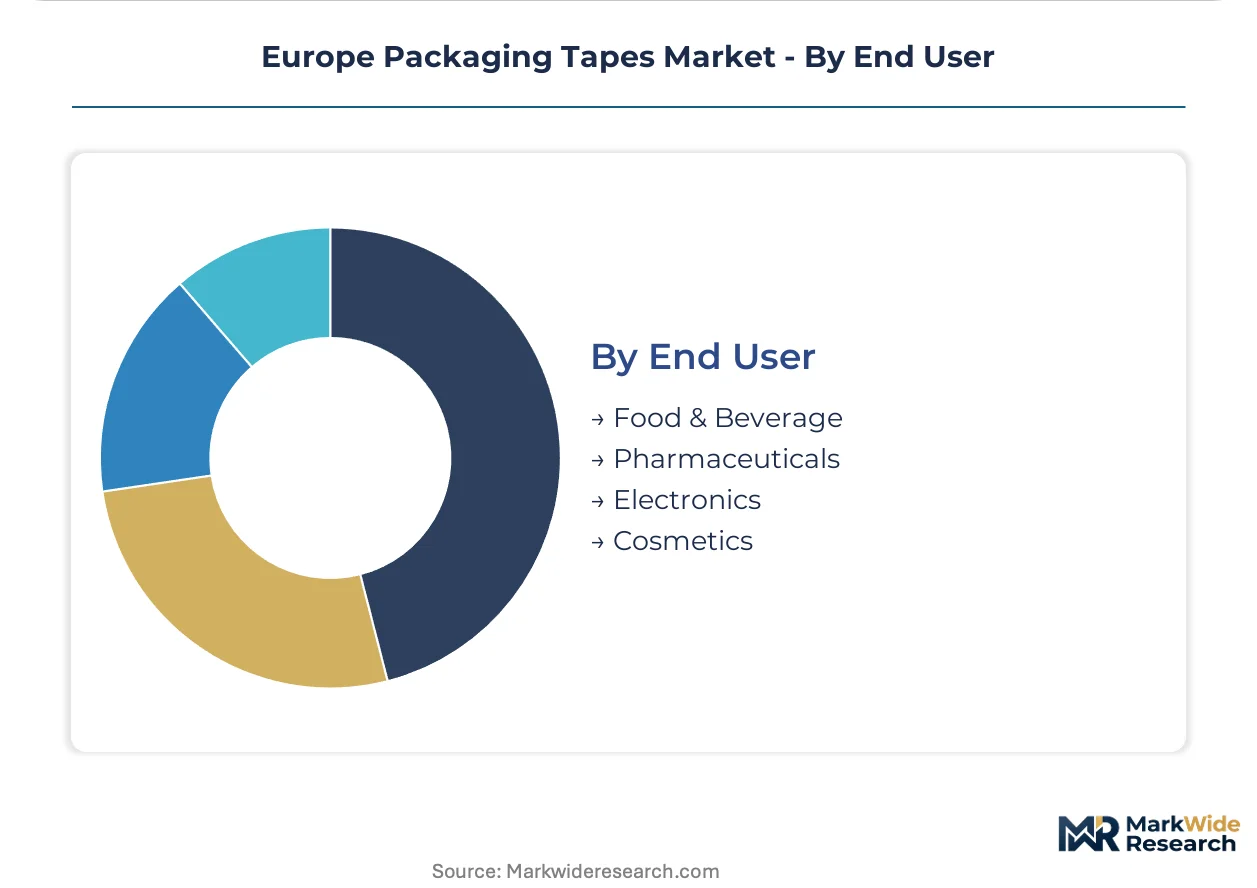
- Food & Beverage:Direct and indirect food-contact tapes require EFSA compliance on migration limits and sensory neutrality. Italian pasta exporters specify odor-free adhesives for aromatic product protection.
- Pharmaceuticals:Cold-chain distribution demands temperature-indicating tapes with irreversible color change below 8°C. EMA serialization mandates drive tamper-evident format adoption across secondary packaging.
- Electronics:Antistatic and low-outgassing tapes protect sensitive components during kitting and transport. Stuttgart R&D clusters prototype sub-25-micrometer calipers for sensor packaging.
- Cosmetics:Premium unboxing experiences favor printable paper tapes with matte finishes and clean edge tear. French luxury houses specify custom pantone matching and embossed logos.
Food and beverage generates the highest unit volumes; pharmaceuticals show the strongest value-per-meter premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naphtha and propylene monomer contract movements along the Rotterdam-Antwerp corridor anchor European tape manufacturing economics, with feedstock volatility transmitting directly into converter margins across the continent.
Germany
Automotive export packaging and pharmaceutical cold-chain distribution drive specialized tape demand. REACH compliance deadlines under ECHA substance evaluation protocols accelerate solvent-free coating line conversions. Stuttgart-area R&D clusters prototype thin-film acrylic systems for precision electronics bundling and sensor packaging applications.
Netherlands
Automated e-commerce fulfillment centers operating at 40+ cartons per minute consume hot-melt adhesive tapes at throughput velocities unmatched elsewhere. F-Gas Regulation emissions thresholds favor water-based acrylic systems in Dutch converting operations. Rotterdam port logistics corridors concentrate pallet unitization demand for polypropylene strapping grades.
France
Luxury cosmetics unboxing experiences and artisanal food packaging sustain premium paper tape segments. EFSA migration limits govern direct food-contact adhesive formulations for wine and cheese exporters. Auvergne-Rhône-Alpes industrial zones retrofit thermal drying systems to UV curing for volatile organic compound reduction.
Poland
Central European logistics corridors capture automotive and electronics export packaging demand with lower labor cost structures than Western European sites. EU Packaging and Packaging Waste Regulation recyclability mandates reshape substrate selection for converters near German border freight routes. Warsaw and Łódź distribution hubs specify cost-efficient polypropylene grades for cross-dock operations.
Italy
Pasta and aromatic food exporters specify odor-free adhesive systems for sensory product protection. EFSA compliance timelines compress development cycles for food-contact tape grades. Northern Italian packaging machinery manufacturers integrate tape application systems with automated case sealing lines for Mediterranean export channels.
Europe Packaging Tapes Market Competitive Landscape
Global majors compete with regional champions across adhesive chemistry expertise and circular-economy certification capabilities. The vendor base separates into integrated manufacturers with in-house extrusion and coating capabilities, specialized converters focused on pharmaceutical and food-contact compliance grades, and merchant adhesive buyers dependent on external supply. Three archetypes dominate: technology leaders patenting UV-curable formulations, sustainability-focused players qualifying mono-material constructions for EU recyclability streams, and scale operators serving pan-European e-commerce platforms. Competitive moves concentrate on M&A for coating capacity acquisition and strategic partnerships with resin suppliers to hedge petrochemical feedstock volatility.
Among Germany-based specialists, Tesa SE and Henkel AG & Co. KGaA exemplify divergent strategic positions. Tesa SE anchors technology leadership through its Stuttgart R&D concentration, while Henkel's Düsseldorf headquarters supports broad hot-melt adhesive portfolio breadth. Avery Dennison represents the North American-headquartered multinational archetype, occupying a compliance-specialist position in pharmaceutical cold-chain applications. These three companies illustrate how geographic clustering around regulatory hubs and industrial R&D corridors shapes competitive differentiation.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| Henkel AG & Co. KGaA |
| Nitto Denko Corporation |
| Tesa SE |
| Intertape Polymer Group |
| Berry Global |
| Scapa Group |
| Advance Tapes International |
| Others |
Supply & Pricing Matrix
Backward integration into polypropylene resin extrusion anchors converter pricing power across German and Dutch coating operations, with captive feedstock supply insulating integrated manufacturers from naphtha contract volatility that compresses margins at merchant adhesive buyers.
Pricing Analysis
After-sales technical support and recyclability certification documentation are bundled into premium tape grades while standard polypropylene carton-sealing tapes trade on unbundled per-meter pricing. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cold-chain grades with EMA compliance from logistics-specification polypropylene and unbranded economy imports. Cost compression in standard grades is intensifying because Polish freight corridors prioritize procurement efficiency over performance premiums. Pan-European e-commerce platforms exhibit the sharpest price sensitivity, while pharmaceutical contract packers accept substantial premiums for serialization-compatible formats.
Supply Chain Analysis
Polypropylene resin supply rests on petrochemical complexes in Germany, Belgium, and the Netherlands along the Rotterdam-Antwerp corridor. Biaxially oriented film production, synthetic rubber adhesive feedstocks, and release liner substrates constitute critical input dependencies. Single-source vulnerability concentrates in styrene-isoprene-styrene block copolymers for hot-melt systems. Distribution runs through converter-direct relationships with automotive OEMs and pan-European packaging distributors serving e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe packaging tapes market sits in a solvent-to-UV curing transition, with electron-beam and UV-curable acrylic systems displacing thermal drying lines to meet REACH and F-Gas Regulation emissions thresholds.
For Market Incumbents: Extend coating capacity in Central European logistics corridors to capture automotive export packaging demand migrating eastward from Stuttgart-area clusters. Deepen backward integration into recycled-content polypropylene feedstocks to qualify for EU Packaging and Packaging Waste Regulation mono-material recyclability tiers. Solvent-free formulation expertise represents the critical capability gap threatening technology leadership.
For New Entrants and Emerging Players: The price-point gap between pharmaceutical premium grades and unbranded economy imports creates entry space for mid-tier converters with documented carbon footprints. Target Polish and Czech Republic manufacturing locations serving German border freight routes with cost-efficient polypropylene grades. Lead with digital print integration for brand authentication to differentiate from commodity suppliers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated adhesive manufacturers seeking coating capacity and circular-economy certifications. Five-to-ten year viability favors converters with in-house extrusion capabilities and pharmaceutical compliance infrastructure. Watch for EU extended-producer-responsibility implementation timelines as the inflection signal for mono-material construction winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Coating Line Conversion | REACH and F-Gas Regulation compliance eliminates thermal drying emissions at German and French converters. |
| Mono-Material Construction Certification | All-polypropylene tape systems qualify for closed-loop recycling under revised EU Packaging and Packaging Waste Regulation criteria. |
| Central European Capacity Expansion | Greenfield coating operations in Poland capture automotive and electronics export packaging with lower labor cost structures. |
| Digital Print Integration | Variable-data printing enables brand authentication and supply-chain traceability for e-commerce platform specifications. |
| Recycled-Content Backing Development | Post-industrial polypropylene feedstocks meet circular-economy mandates from pan-European retail procurement desks. |
Research Methodology
Trade association filings, ECHA substance registration databases, and EU customs records formed the secondary backbone, supplemented by primary interviews with coating line engineers, adhesive procurement managers at automotive OEMs, pharmaceutical packaging specialists, and distribution channel partners across German, Dutch, and Polish logistics corridors. Bottom-up and top-down triangulation validated volume estimates against resin consumption data and converting capacity utilization.
Bottom-up modeling built from segment-level demand drivers across material type, adhesive chemistry, and end-use compliance requirements, while top-down cross-checks anchored against macroeconomic freight and e-commerce fulfillment indicators. CAGRs were derived from regression analysis of historical tape consumption against industrial production and retail sales indices. Modeled inputs included propylene monomer contract movements, REACH substance restriction timelines, and EU Packaging and Packaging Waste Regulation implementation phases.
Inputs from EMA regulatory filings and automotive OEM packaging specifications were available through the study window; gaps in real-time converter inventory data introduce uncertainty bands around short-term demand fluctuations. Forecasts reflect documented assumptions on regulatory enforcement intensity and feedstock price normalization. E-commerce automation penetration rates and extended-producer-responsibility sorting protocol finalization warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
ESD Tapes and Labels Market
Tapes
Building and Construction Tapes Market
Tapes
Holographic Tear Tape Market
Tapes
Heat Sealing Tape Market
Tapes
Removal Strips Market
Tapes
Acoustic Tape Market
Tapes
Carbon Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Foil Tapes Market
Tapes
Invisible Tapes Market
Tapes
Lacing Tape Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Wire Harness Tape Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Packaging Tapes Market