
 Polyester Strapping Machines Market | 2026-2036
Polyester Strapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Strapping Machines Market Analytics
Capital-intensity divergence between automated and semi-automatic production lines is bifurcating competitive positioning in the polyester strapping machines sector. Signode Industrial Group LLC leverages captive steel-to-plastic strapping expertise to anchor premium system sales across North American manufacturing corridors. Mosca GmbH sustains R&D intensity in ultrasonic sealing architectures, differentiating its automatic platform from commodity alternatives. FROMM Packaging Systems competes through geographic dominance in European aftermarket service networks, extending machine lifecycle value for logistics operators.
Polyester strapping machines apply thermoplastic polyethylene terephthalate (PET) banding at tensions typically ranging from 400 to 2,400 pounds to secure palletized loads for transport and warehousing operations. The equipment incorporates friction-weld or heat-seal heads that bond strap ends without metallic seals, reducing material contamination in recycling streams. Automatic machine types command the largest installed base in high-volume food and beverage facilities where line speeds exceed 60 pallets per hour. Electric drive architectures represent the fastest-growing machine category as warehouses phase out pneumatic infrastructure to cut energy intensity. The pharmaceutical industry vertical carries concentrated margin pools due to validation requirements and cleanroom-compatible stainless steel specifications that elevate equipment pricing.
OSHA machine guarding standards in the United States and CE marking requirements under the EU Machinery Directive shape product design, mandating two-hand operation protocols and emergency stop circuits that add engineering cost. The EU Green Deal's packaging waste targets are forcing strapping material suppliers to certify recycled PET content, which in turn requires machine builders to validate seal integrity with variable resin grades. Stakeholders must monitor how regulatory divergence between North American and European safety and sustainability frameworks influences platform standardization decisions.
Market Dynamics
Electric drive architectures are decomposing the installed base of pneumatic strapping systems across high-throughput logistics facilities, forcing capital reallocation toward warehouse energy efficiency mandates.
Growth Catalysts
- E-commerce fulfillment automation:Third-party logistics operators in Germany are retrofitting pallet consolidation lines with automatic polyester strapping equipment to match throughput targets.
- EU Packaging and Packaging Waste Regulation:Material recovery requirements are pushing converters toward recyclable PET strap formats that demand compatible sealing validation.
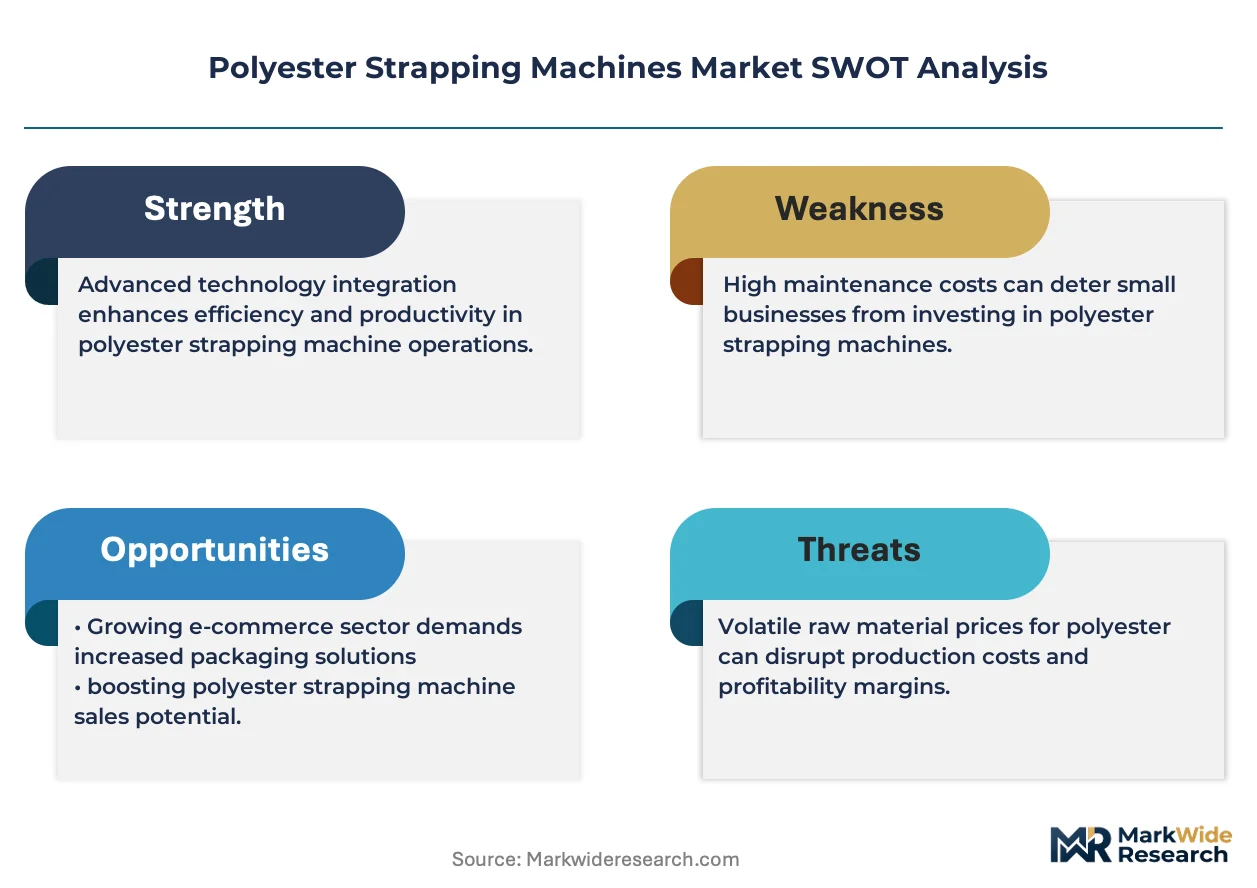
- Ultrasonic sealing advancement:Bond integrity improvements are expanding machine deployment into pharmaceutical cleanroom environments with stainless steel specifications.
Market Restraints
- Recycled PET resin variability:Inconsistent melt-flow indices from post-consumer feedstock complicate heat-seal head calibration and increase rejection rates.
- Pneumatic infrastructure lock-in:Existing compressed air investments in legacy warehousing create switching cost barriers for electric platform adoption.
- CE marking compliance burden:EU Machinery Directive two-hand operation protocols add engineering cost that compresses margin on semi-automatic units.
Strategic Opportunities
- Indian cold chain expansion:Temperature-controlled pharmaceutical distribution is creating demand for corrosion-resistant strapping systems in Mumbai and Hyderabad logistics hubs.
- Outcome-based service contracting:Equipment-as-a-service models are penetrating European aftermarket networks, capturing lifecycle value beyond initial hardware sale.
- Battery manufacturing logistics:Cell and module palletization for electric vehicle supply chains is opening dedicated strapping specifications for hazardous material transport.
Industry Challenges
- Ultrasonic transducer calibration expertise:Field service technician shortages are extending mean-time-to-repair for advanced sealing architectures.
- Legacy ERP integration:Automatic line data exchange with warehouse management systems requires custom middleware development that delays deployment timelines.
- Cleanroom validation documentation:Pharmaceutical equipment qualification protocols extend sales cycles by eight to fourteen months for new machine introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Strapping Machines Market |
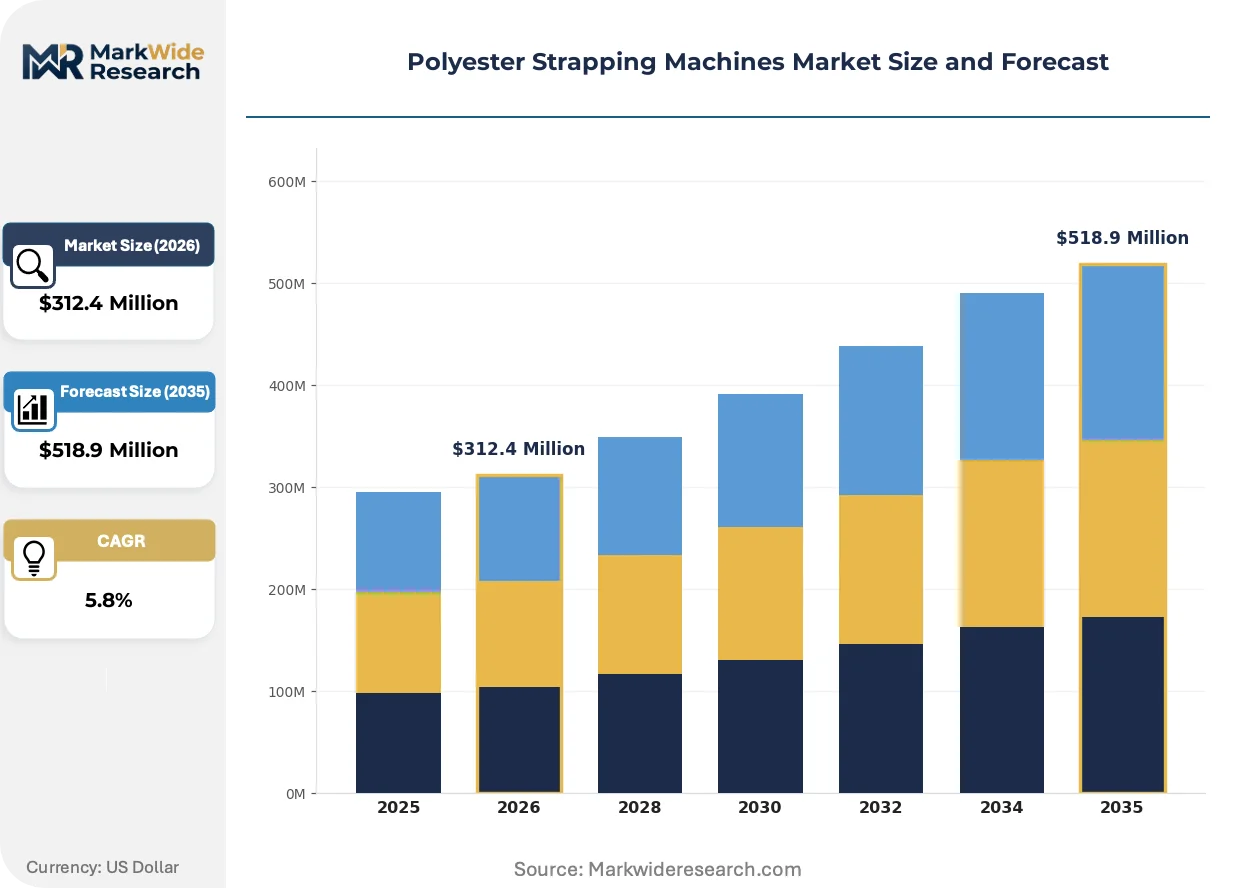
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Automatic, Semi-Automatic, Manual, Electric Strapping Material: Polyester, Polypropylene, Steel, Composite End User: Logistics, Manufacturing, Packaging, Warehousing Industry Vertical: Food & Beverage, Retail, Pharmaceuticals, Construction |
| Companies Covered | Signode Industrial Group LLC, Mosca GmbH, FROMM Packaging Systems, StraPack, Dynaric Inc., Polychem Corporation, MJ Maillis Group, Samuel Strapping Systems, Messersì Packaging S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Strapping Machines Market Evolving Landscape
Equipment intelligence and material circularity are converging to redefine competitive differentiation, with machine builders racing to validate seal performance across variable recycled content grades.
Ultrasonic welding heads are decomposing the dominance of friction-weld sealing in high-speed food and beverage lines. Coca-Cola and PepsiCo bottling facilities are retrofitting existing arches with piezoelectric transducer modules to eliminate metallic seal contamination. This transition is compressing the addressable market for conventional heat-seal consumables while expanding service revenue pools for calibration-intensive architectures.
REACH substance restrictions on legacy plasticizers are forcing reformulation of PET strap additives across European converter supply chains. ECHA compliance deadlines are accelerating R&D expenditure toward bio-based plasticizer alternatives that maintain tensile strength specifications. Food contact applications face the steepest certification burden, with migration testing protocols extending material qualification timelines.
Leasing structures are displacing outright purchase for mid-volume logistics operators in France and Benelux markets. FROMM Packaging Systems and regional distributors are unbundling hardware ownership from maintenance obligation, capturing recurring revenue through per-pallet pricing models. This shift is most pronounced in contract logistics where capex flexibility outweighs total cost of ownership optimization.
Polyester Strapping Machines Market Segmentation
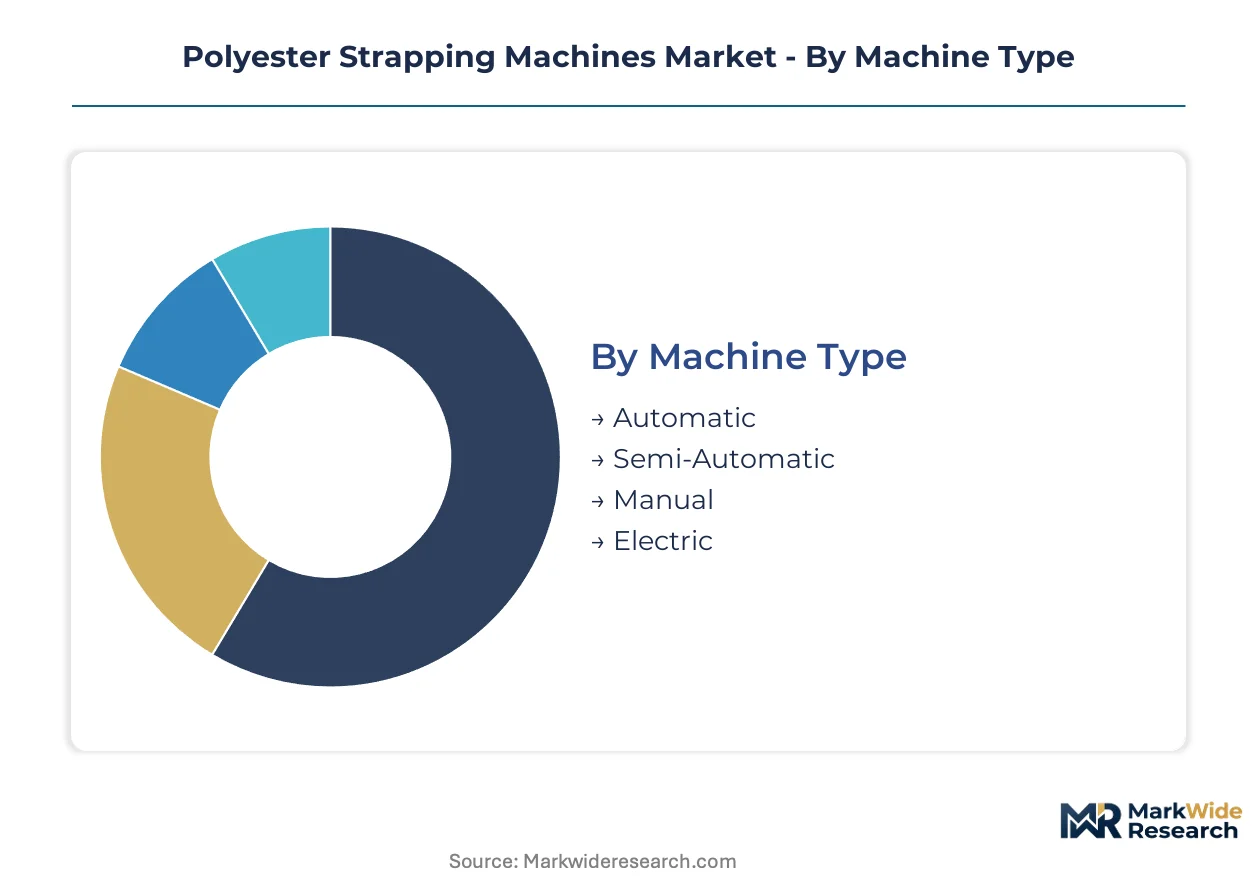
Segmentation in polyester strapping machines reveals how equipment specifications align with operational intensity and regulatory exposure across end-use environments. Machine builders configure sealing architectures and drive systems to match pallet throughput requirements and material recovery mandates.
Machine Type:
Substitution pressure from electric architectures is fragmenting the pneumatic installed base, with capital allocation tilting toward warehouse energy efficiency mandates.
- Automatic:These systems deploy arch-based strap dispensing with friction-weld or ultrasonic sealing heads operating at 60-plus pallets per hour. Food and beverage bottling facilities in Germany concentrate demand here, driven by line speed requirements and CE marking compliance for high-speed guarding protocols.
- Electric:Servo-driven tensioning and sealing modules eliminate compressed air dependency, cutting energy intensity by 30-40% versus pneumatic equivalents. Third-party logistics operators in France retrofit warehouses with these systems to meet corporate sustainability targets and reduce pneumatic infrastructure maintenance.
- Semi-Automatic:Operator-fed strap insertion with automated tensioning and sealing suits mid-volume pallet consolidation. These units face margin compression from CE marking two-hand operation requirements.
- Manual:Hand-held tensioners and sealers serve low-volume or field repair applications with minimal capital outlay. Construction sites and small warehousing operations in India deploy these for intermittent pallet securing.
Automatic retains volume leadership; electric holds the steepest expansion curve.
Strapping Material:
Cost tier differentiation separates commodity resin grades from validated recycled content formats demanded by EU circularity mandates.
- Polyester:PET strap delivers 400-2,400 pound tension range with elastic recovery for load stability during transport. Pharmaceutical distribution in Switzerland specifies medical-grade PET with full batch traceability, elevating qualification burdens and equipment pricing.
- Steel:High-tensile metal strapping retains dominance in heavy construction materials and metal coil shipping where PET elongation risks load shift. German steel service centers continue specifying steel for outbound flat-rolled products.
- Polypropylene:Lower-cost thermoplastic banding suits lightweight carton consolidation where tension requirements stay below 500 pounds. E-commerce fulfillment in the Netherlands deploys PP for parcel bundling before palletization.
- Composite:Fiber-reinforced plastic strapping combines tensile strength with corrosion resistance for chemical and salt-exposed logistics. Battery cell palletization for electric vehicle supply chains in South Korea tests composite specifications for hazardous material compliance.
Polyester dominates value contribution; composite climbs fastest on hazardous material transport requirements.
End User:
Application intensity varies sharply between continuous-flow manufacturing and intermittent warehousing operations.
- Logistics:Third-party operators run 24-hour pallet consolidation with automatic arch systems integrated to warehouse management software. Mumbai cold chain hubs demand corrosion-resistant specifications for temperature-controlled pharmaceutical distribution.
- Manufacturing:In-line strapping at production output points requires validation documentation for FDA-regulated environments. Cleanroom-compatible stainless steel architectures concentrate in pharmaceutical manufacturing corridors.
- Warehousing:Retrofit installations balance throughput against existing pneumatic infrastructure lock-in. Benelux contract logistics operators favor leasing structures to preserve capex flexibility.
- Packaging:Converter facilities apply strapping for downstream pallet preparation, with REACH-compliant strap additives driving material qualification timelines.
Logistics commands the largest equipment installed base; manufacturing carries the highest margin pools.
Industry Vertical:
Margin concentration tracks regulatory validation burden and cleanroom specification requirements across end-use environments.
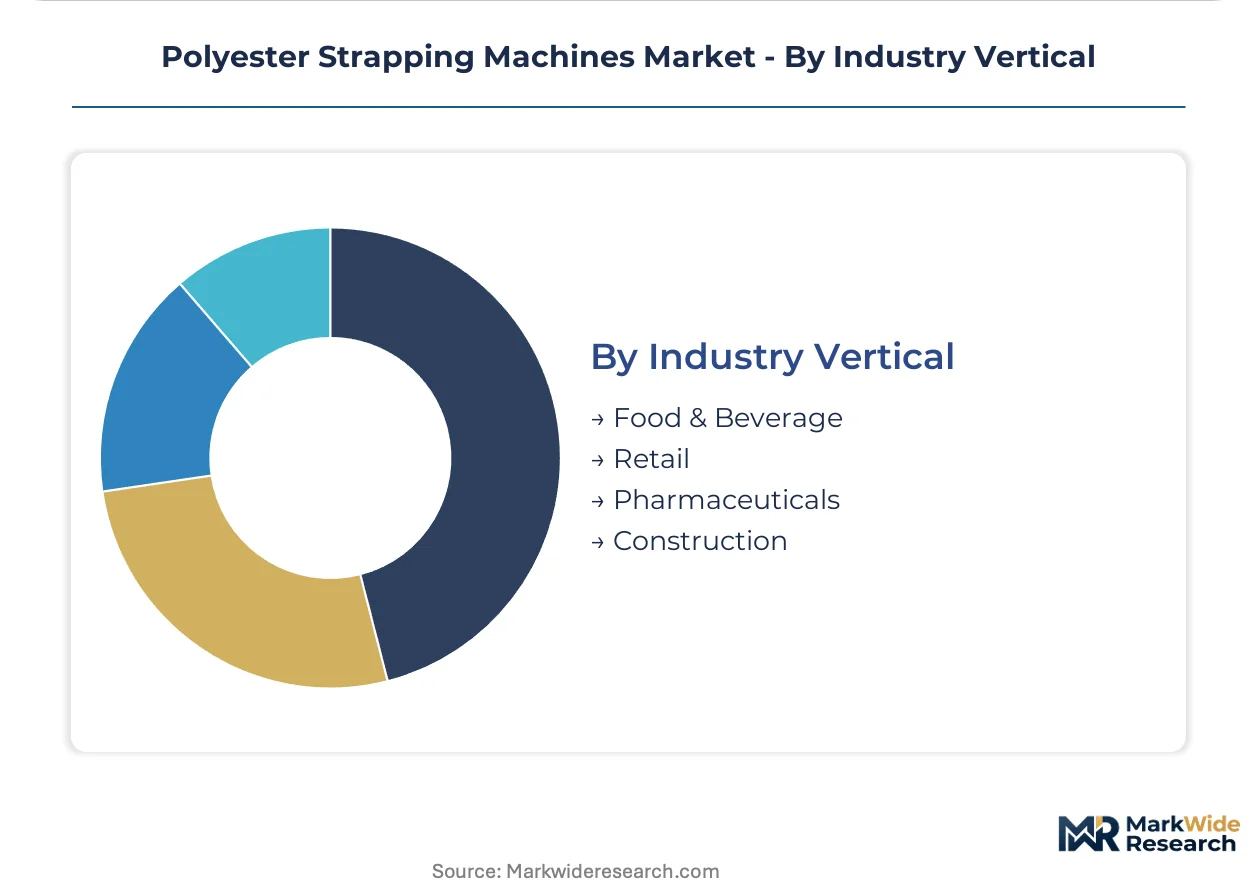
- Food & Beverage:High-speed bottling lines exceed 60 pallets per hour, mandating automatic arch configurations with ultrasonic sealing to eliminate metallic contamination. Coca-Cola and PepsiCo facilities drive retrofit demand for piezoelectric transducer modules.
- Pharmaceuticals:FDA and EMA validation requirements extend sales cycles eight to fourteen months for new machine introductions. Stainless steel specifications and cleanroom compatibility elevate equipment pricing substantially above industrial norms.
- Retail:Omnichannel distribution centers balance throughput against SKU proliferation, favoring flexible semi-automatic units for mixed pallet profiles.
- Construction:Heavy material shipping retains steel strapping dominance, though PET penetration grows in prefabricated component logistics for residential building supply chains.
Food & Beverage leads equipment volume; Pharmaceuticals captures the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in polyester strapping machines varies sharply by logistics infrastructure maturity, with emerging market buyers prioritizing capital efficiency while German and Swiss purchasers absorb premium pricing for validation-heavy pharmaceutical specifications.
Germany
Third-party logistics operators in the Ruhr Valley and Bavaria are retrofitting pallet consolidation lines with automatic arch systems to match e-commerce throughput targets. The EU Machinery Directive's CE marking requirements mandate two-hand operation protocols that add engineering cost to semi-automatic units. Mosca GmbH and FROMM Packaging Systems anchor a dense machinery cluster around Stuttgart and Karlsruhe, driving ultrasonic sealing R&D intensity.
United States
OSHA machine guarding standards shape product design across food and beverage bottling corridors in Georgia and California, mandating emergency stop circuits. FDA validation requirements for pharmaceutical distribution in New Jersey and North Carolina extend equipment sales cycles. Signode Industrial Group LLC leverages captive steel-to-plastic expertise across Midwestern manufacturing belts.
India
Temperature-controlled pharmaceutical distribution in Mumbai and Hyderabad logistics hubs is creating demand for corrosion-resistant strapping specifications. The country's national pharmaceutical regulator imposes cleanroom compatibility standards that elevate stainless steel equipment pricing. Cold chain expansion in Maharashtra and Telangana is accelerating capital deployment toward electric drive architectures.
Switzerland
Swissmedic validation protocols for medical-grade PET distribution concentrate margin pools in Basel and Zurich pharmaceutical corridors. Full batch traceability requirements for strap materials extend qualification timelines and equipment pricing substantially above industrial norms. Precision manufacturing clusters around Lake Geneva demand seal integrity validation across variable recycled resin grades.
South Korea
Battery cell and module palletization for electric vehicle supply chains in Ulsan and Gwangju is opening dedicated strapping specifications for hazardous material transport. The Ministry of Environment's dual carbon goals are pushing logistics operators toward electric drive systems. Composite fiber-reinforced strapping is undergoing compliance testing for chemical exposure resistance in Busan port logistics.
Polyester Strapping Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium positioning hinging on captive material expertise and aftermarket service density. The competitive landscape bifurcates between automated platform builders and semi-automatic equipment fabricators. Three archetypes dominate: integrated strapping-to-machinery conglomerates, ultrasonic sealing technology specialists, and regional aftermarket service networks. Dominant competitive moves include geographic expansion through distributor acquisition and technology licensing for electric drive architectures.
Among Germany-based fabricators, Mosca GmbH and FROMM Packaging Systems exemplify the premium-tier positioning anchored in European regulatory compliance expertise. Signode Industrial Group LLC represents the integrated conglomerate archetype with captive material capabilities. These three occupy positions that span the value chain from resin validation through field service calibration, with each exemplifying a distinct competitive vector: sealing technology depth, geographic service density, or backward integration into strapping materials.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| Mosca GmbH |
| FROMM Packaging Systems |
| StraPack |
| Dynaric Inc. |
| Polychem Corporation |
| MJ Maillis Group |
| Samuel Strapping Systems |
| Messersì Packaging S.r.l. |
| Others |
Value Network & Pricing Analysis
Electric drive substitution for pneumatic architectures is redrawing procurement geography toward German and French warehouse automation clusters while compressing aftermarket service pricing power. This equipment transition simultaneously elevates upfront capital requirements and fragments legacy maintenance revenue pools across European logistics networks.
Pricing Analysis
Aftermarket service contracts and per-pallet leasing structures now generate lifetime value exceeding original equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cleanroom specifications from food-grade industrial units and entry-level semi-automatic alternatives. Cost compression in mid-volume logistics tiers is intensifying because CE marking compliance adds fixed engineering burden to lower-priced equipment. Third-party logistics operators in France exhibit highest price sensitivity, while Swiss pharmaceutical distributors absorb substantial premiums for validation documentation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for piezoelectric transducer modules and servo drive components. Machine assembly concentrates in Germany, Italy, and South Korea, drawing from PET resin feedstock anchored in Belgium, the Netherlands, and China. Single-source vulnerability sits with ultrasonic transducer suppliers serving pharmaceutical sealing architectures. Distribution runs through regional distributor networks with factory-authorized service depots in major logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation mandates are accelerating a high-growth disruption as recycled PET validation requirements force machine builders to requalify seal integrity across variable resin grades.
For Market Incumbents: Fortify aftermarket service density in German logistics corridors to capture recurring revenue from ultrasonic sealing calibration requirements. Expand captive PET strap supply partnerships to ensure resin grade consistency for pharmaceutical customers facing ECHA compliance deadlines. This defends margin position against emerging electric-drive specialists from Asia. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Stuttgart or Karlsruhe opens immediate addressable market in mid-volume French warehousing. Target Indian cold chain expansion in Mumbai and Hyderabad with corrosion-resistant electric architectures. Leasing model penetration in Benelux contract logistics offers the most penetrable entry point. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed packaging machinery conglomerates seeking portfolio rationalization. Five-to-ten year viability hinges on electric platform R&D intensity and pharmaceutical validation expertise. Watch for ultrasonic transducer calibration technician shortages as inflection signal for service network scarcity value.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing Platform Migration | Coca-Cola and PepsiCo bottling facilities drive retrofit demand eliminating metallic seal contamination. |
| Electric Drive Architecture Rollout | French third-party logistics operators cut energy intensity by 30-40% versus pneumatic equivalents. |
| Pharmaceutical Validation Documentation Investment | FDA and EMA requirements extend sales cycles eight to fourteen months for new machine introductions. |
| Outcome-Based Service Contracting Expansion | FROMM Packaging Systems captures recurring revenue through per-pallet pricing in contract logistics. |
| Recycled PET Seal Integrity Qualification | EU Green Deal packaging waste targets force validation across variable post-consumer resin grades. |
Research Methodology
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and warehouse automation directors converged on the working assumptions for equipment deployment timelines. Primary field engagement combined with secondary validation from SEC filings, customs and trade data, machinery directive compliance databases, and industrial automation capex disclosures. Bottom-up unit economics triangulated against top-down market sizing across machine type, drive architecture, and end-use verticals.
Segmentation dimensions modeled include machine type, strapping material specification, end-user operational intensity, and industry vertical regulatory exposure across the analysis window. CAGRs derived from logistic curve penetration modeling for electric drive substitution and ultrasonic sealing adoption. Forecast inputs incorporated EU Machinery Directive compliance cost trajectories and REACH substance restriction timelines for PET strap additives.
Underlying assumptions cover recycled PET resin grade stabilization, technician availability for field calibration, and warehouse energy efficiency mandate continuity, with deviation risk concentrated in regulatory divergence between North American and European sustainability frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Global Wrapping Machine Market
Packaging Machinery
Metal Banding Machine Market