
 Global Pressure Sensitive Tapes Market | 2026-2036
Global Pressure Sensitive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pressure Sensitive Tapes Market Foresight
Aftermarket service revenue for tape application tooling and die-cut converting is tilting toward integrated suppliers with in-house slitting and precision cutting capabilities. 3M Company leverages its polymer science heritage to sustain premium positioning in electronics-grade acrylic platforms. Tesa SE anchors European automotive OEM relationships through direct specification programs. Nitto Denko Corporation dominates Asian display and semiconductor bonding applications with cleanroom-compatible tape systems.
Pressure sensitive tapes are flexible substrates coated with adhesive formulations that bond upon light pressure without solvent activation or heat curing, typically specified by peel adhesion strength, shear resistance, and temperature operating ranges for industrial joining, surface protection, and electrical insulation. Packaging tapes occupy the highest volume tier but face margin compression from commodity polypropylene films and hot melt adhesive competition. Water-based acrylic systems are gaining share in consumer and light industrial segments as environmental compliance tightens, while solvent-based platforms retain dominance in high-performance automotive and aerospace bonding where elevated temperature resistance is non-negotiable.
FDA regulations govern medical-grade tape biocompatibility and skin contact safety, while EPA and OSHA frameworks limit worker exposure to solvent emissions in tape manufacturing facilities across the United States. REACH and RoHS compliance in Europe restricts hazardous substance content and drives reformulation investments among adhesive producers serving cross-border supply chains. Stakeholders must monitor evolving battery safety standards from China's MIIT and the EU's Battery Regulation, as thermal runaway containment tapes become critical specification items in EV platform designs.
Market Dynamics
Automotive electrification is rewiring tape specifications across the value chain, as battery thermal management systems demand adhesives with precise dielectric strength and flame-retardant properties that legacy formulations cannot deliver.
Growth Catalysts
- Battery thermal management specifications:EV platform designs from Germany, China, and the United States are mandating pressure-sensitive tapes for cell-to-cell bonding and thermal runaway containment, creating specification pull from automotive OEMs.
- REACH compliance timelines:ECHA's tightening volatile organic compound limits on solvent-based formulations are accelerating reformulation investments toward water-based acrylic and hot-melt alternatives in European supply chains.
- Display and semiconductor cleanroom demand:Asian electronics manufacturing clusters in South Korea, Taiwan, and Japan are specifying ultra-low outgassing tape systems for OLED lamination and wafer dicing applications.
Market Restraints
- Petrochemical input volatility:Polypropylene film substrates and acrylic monomer feedstocks expose converters to margin compression when crude-derived raw material costs spike without corresponding pass-through mechanisms.
- Solvent-based formulation lock-in:Aerospace and heavy-duty automotive bonding segments remain technically dependent on solvent acrylics for elevated temperature resistance, limiting near-term substitution despite regulatory pressure.
- Converter concentration in East Asia:Slitting, die-cutting, and precision converting capacity clusters in China and Taiwan create geographic supply risk for North American and European tape buyers seeking regional sourcing alternatives.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for domestic EV manufacturing are creating demand for localized tape converting capacity to serve battery pack and motor assembly operations.
- Biodegradable backing materials:Convergence of cellulose fiber substrates with bio-based pressure-sensitive adhesives opens positioning for premium sustainable packaging applications in European consumer goods.
- Aftermarket tooling integration:Direct specification relationships with automotive OEMs are enabling integrated suppliers to capture recurring revenue from application equipment and die-cut kit programs.
Industry Challenges
- Polymer science talent scarcity:Formulation chemistry expertise for high-performance acrylic and silicone adhesive platforms concentrates among aging specialist workforces in Japan, Germany, and the United States.
- Multi-jurisdiction certification timelines:Simultaneous FDA biocompatibility, REACH substance registration, and China GB standard compliance for medical-grade tapes extends product launch cycles by 18-36 months.
- Legacy slitting equipment incompatibility:Thin-gauge film substrates for electronics applications require capital-intensive precision slitting lines that smaller regional converters cannot justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pressure Sensitive Tapes Market |
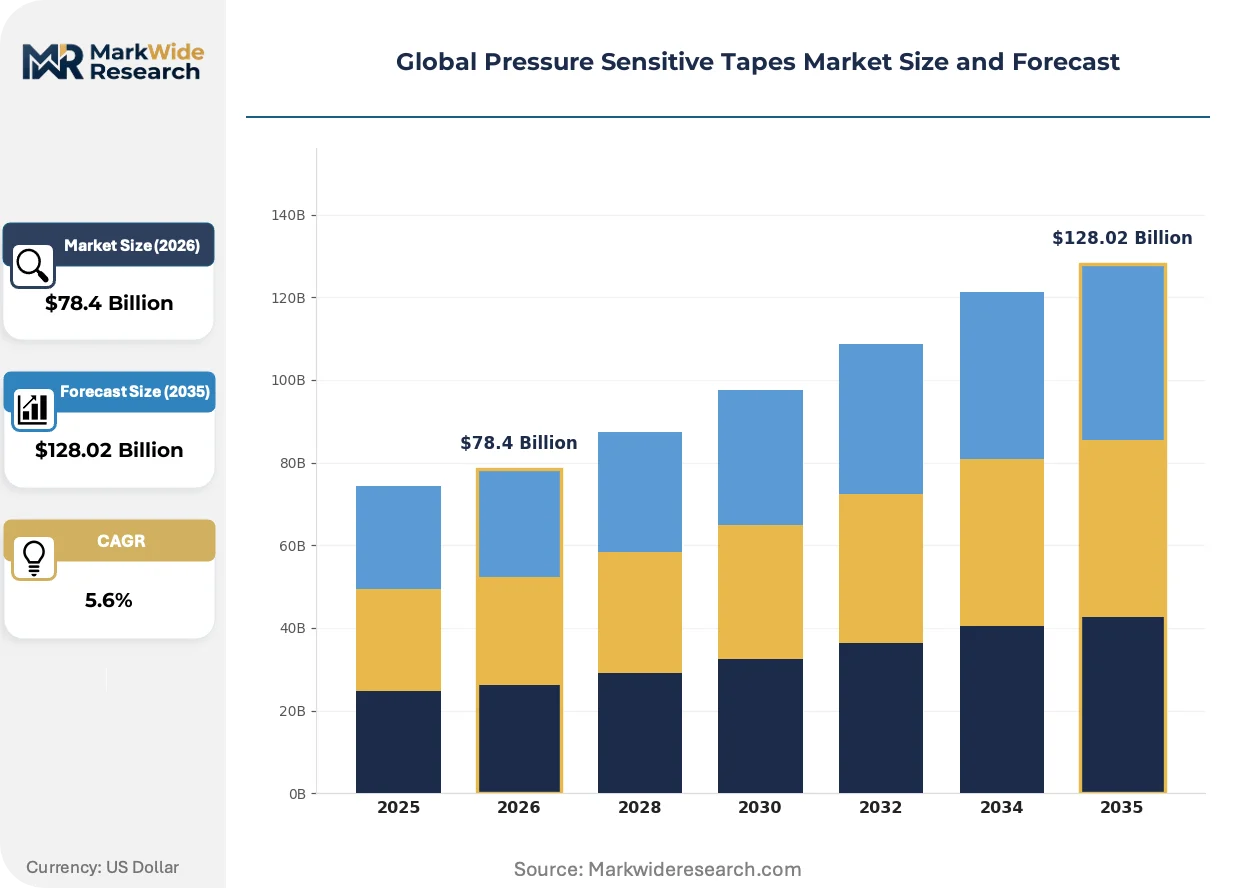
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tapes, Electrical Tapes, Masking Tapes, Packaging Tapes Adhesive Type: Water-Based, Solvent-Based, Hot Melt, Rubber-Based End User: Automotive, Electronics, Construction, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | 3M Company, Tesa SE, Nitto Denko Corporation, Avery Dennison Corporation, LINTEC Corporation, Intertape Polymer Group, Berry Global Group, Henkel AG & Co. KGaA, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pressure Sensitive Tapes Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry mandates are converging to reshape competitive positioning, as performance specifications tighten and environmental compliance becomes non-negotiable across end-use verticals.
UV-curable pressure-sensitive adhesives are rendering obsolete thermal curing processes in electronics assembly workflows. Display manufacturers in South Korea and Taiwan are adopting these systems for touch panel lamination to eliminate oven energy costs and substrate thermal damage. The shift is compressing cycle times from minutes to seconds while enabling thinner, more temperature-sensitive backing materials.
REACH authorization requirements for substances of very high concern are forcing systematic adhesive reformulation across European supply chains. ECHA's 2025-2027 sunset dates for specific phthalate plasticizers and isocyanate crosslinkers are driving R&D investment toward bio-based tackifiers and hybrid acrylic-urethane chemistries. Automotive OEMs with pan-European assembly networks are most exposed, accelerating supplier qualification programs to maintain production continuity.
Specification authority is migrating from distributor catalogs to direct OEM engineering relationships. Tier-1 automotive and electronics manufacturers in Germany, Japan, and China are consolidating approved vendor lists and demanding collaborative development programs rather than off-the-shelf product selection. This disintermediation is visible most acutely in battery and display supply chains, where tape performance directly impacts end-product safety certifications.
Global Pressure Sensitive Tapes Market Segmentation
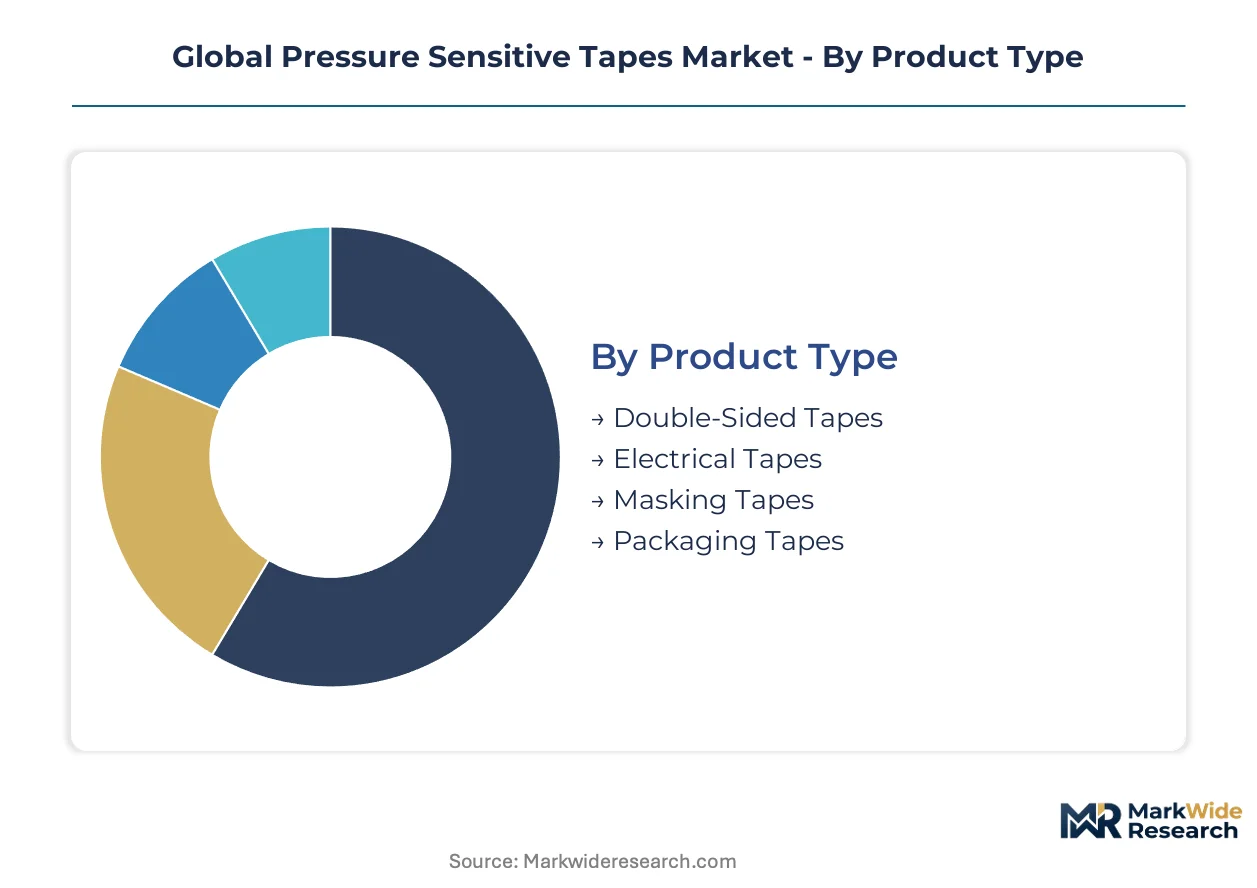
Segmentation in pressure sensitive tapes determines specification authority and margin capture. Product architecture dictates reformulation investments, while adhesive chemistry governs regulatory exposure across jurisdictions.
Product Type:
After-sales service intensity varies sharply by product type, with die-cut converting and application tooling generating recurring revenue streams in industrial grades.
- Packaging Tapes:Polypropylene film substrates coated with hot melt or water-based acrylic adhesives dominate volume. Demand concentrates in e-commerce fulfillment centers across China and the United States as automated case sealing lines specify consistent unwind force and shear resistance.
- Double-Sided Tapes:Carrier films or foams bonded with high-tack acrylic or rubber adhesives enable structural bonding without mechanical fasteners. Automotive battery pack assembly in Germany and China is specifying these systems for cell-to-cell bonding where thermal cycling resistance is mandatory.
- Electrical Tapes:PVC or polyimide backings with pressure-sensitive adhesive coatings provide dielectric insulation and flame retardancy.
- Masking Tapes:Crepe paper backings with rubber or silicone adhesives withstand paint bake cycles and clean removal.
Packaging tapes hold the largest share; momentum sits with double-sided tapes.
Adhesive Type:
Cost tier stratification separates premium solvent-based formulations from commodity water-based alternatives.
- Solvent-Based:Acrylic polymers dissolved in organic carriers deliver elevated temperature resistance and aggressive tack. Aerospace assembly in France and Germany retains technical dependence on these systems despite REACH-driven reformulation pressure.
- Water-Based:Acrylic emulsions dispersed in aqueous vehicles reduce volatile organic compound emissions and manufacturing hazard classification. Consumer goods and light industrial applications in the United States and India are shifting specification toward these platforms as EPA and state-level air quality rules tighten.
- Hot Melt:Synthetic rubber and tackifier blends applied molten eliminate solvent handling entirely.
- Rubber-Based:Natural or synthetic elastomers combined with tackifying resins provide immediate bond formation.
Solvent-based adhesives retain premium positioning; water-based systems are climbing the fastest.
End User:
Application criticality determines specification stringency and supplier qualification timelines.
- Automotive:Thermal management, NVH damping, and exterior bonding applications specify tapes with temperature cycling resistance and flame-retardant certification. Battery platform designs from BYD, Tesla, and Volkswagen are driving specification pull for cell-to-cell bonding and thermal runaway containment tapes.
- Electronics:Cleanroom-compatible systems with ultra-low outgassing enable OLED lamination and semiconductor wafer processing. Display manufacturing clusters in South Korea and Taiwan specify these grades for touch panel assembly where particle contamination risks yield loss.
- Construction:Weatherproofing, vapor barrier sealing, and temporary surface protection applications demand UV resistance and adhesion to rough substrates.
- Healthcare:Skin-contact medical-grade tapes require FDA or equivalent biocompatibility certification and hypoallergenic adhesive platforms.
Automotive commands the highest specification intensity; electronics represents the fastest-growing trajectory.
Distribution Channel:
Customer type and order scale dictate channel selection and margin structure.
- Distributors:Industrial and safety supply distributors maintain local inventory and technical support for maintenance-repair-operations procurement. German and Japanese automotive suppliers rely on these relationships for just-in-time delivery of approved-specification tapes.
- Online Retail:E-commerce platforms capture small-volume orders from contractors and small businesses seeking price transparency and rapid fulfillment.
- Specialty Stores:Professional paint and industrial supply retailers serve tradespeople requiring immediate availability of application-specific grades.
- Supermarkets:Mass retail channels move commodity packaging and consumer-grade masking tapes.
Distributors hold the largest share; momentum sits with online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, accepting premium formulations for automotive and electronics specifications, while Indian and Southeast Asian packaging converters drive hard bargains on commodity polypropylene grades.
China
Domestic EV production from BYD and CATL battery suppliers is consuming specialized thermal runaway containment tapes at unprecedented rates. MIIT battery safety standards mandate flame-retardant adhesive systems for all new energy vehicle platforms. Tape converting capacity clusters in Suzhou and Dongguan are expanding precision slitting lines to serve local automotive tier-1s.
Germany
Volkswagen and BMW battery platform designs specify European-sourced double-sided tapes for cell-to-cell bonding with REACH-compliant formulations. ECHA's 2025-2027 sunset dates for phthalate plasticizers are accelerating reformulation investments among adhesive suppliers serving Stuttgart and Munich automotive clusters. Bavarian chemical producers are piloting bio-based tackifier alternatives.
United States
Tesla's Nevada and Texas gigafactories are qualifying domestic tape converters for thermal management specifications previously sourced from Asia. EPA and OSHA emission limits on solvent-based manufacturing are pushing water-based acrylic adoption in consumer goods segments. Industrial distributors in Michigan and Ohio maintain just-in-time inventory for automotive OEM supply chains.
Japan
Display manufacturers in Osaka and Nagoya are specifying ultra-low outgassing tape systems for OLED lamination. METI cleanroom standards for semiconductor materials create technical barriers for non-domestic suppliers. Polymer science expertise concentrates in Kansai region adhesive formulators serving Sony and Panasonic production networks.
India
PLI scheme incentives for domestic EV manufacturing are creating demand for localized tape converting capacity to serve battery pack assembly operations. BIS certification requirements for automotive adhesives extend supplier qualification timelines. Tamil Nadu and Gujarat automotive corridors are attracting precision die-cutting investments from multinational tape suppliers.
Global Pressure Sensitive Tapes Market Competitive Landscape
Capability concentration sits with polymer science specialists commanding premium specifications; scale advantage sits with diversified materials conglomerates serving commodity packaging volumes. The market structures around three tiers: integrated multinationals with direct OEM relationships, regional converters with slitting and die-cutting expertise, and commodity film coaters competing on price. Strategic moves center on backward integration into adhesive resin production and collaborative development programs with automotive battery engineers.
Within the integrated multinational tier, 3M Company and Tesa SE exemplify specification authority through direct OEM engineering relationships. Nitto Denko Corporation anchors Asian electronics supply chains with cleanroom-compatible platforms. These three entities represent divergent geographic anchoring—American, German, and Japanese—that shapes their respective regulatory compliance postures and customer proximity advantages.
| Leading Market Players |
|---|
| 3M Company |
| Tesa SE |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| LINTEC Corporation |
| Intertape Polymer Group |
| Berry Global Group |
| Henkel AG & Co. KGaA |
| Lohmann GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Slitting line overcapacity in Dongguan and Suzhou is compressing converter margins while simultaneously strengthening the pricing leverage of adhesive resin suppliers with captive polymer production. This utilization asymmetry forces independent converters toward toll-coating arrangements or backward integration investments, reshaping competitive economics across the value chain.
Pricing Analysis
After-sales service revenue from die-cut kit programs and application tooling drives lifetime value capture for integrated suppliers with direct OEM relationships. Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade cleanroom tapes from automotive thermal management formulations and commodity packaging grades. Cost compression in polypropylene film substrates is intensifying because e-commerce fulfillment centers negotiate volume contracts with unwind-force specifications. Packaging converters in India and Southeast Asia demonstrate the highest price sensitivity, while German automotive tier-1s accept formulation premiums for REACH-compliant bonding systems.
Supply Chain Analysis
Acrylic monomer and polypropylene resin feedstock supply concentrates in China, South Korea, and the United States, tethering converter margins to petrochemical pricing cycles. Raw material dependencies center on crude-derived polymer substrates, tackifier resins, and silicone release coatings. Single-source vulnerability runs through Asian precision slitting equipment manufacturers, creating capital access barriers for regional converters seeking electronics-grade capability. Distribution runs through industrial supply distributors with just-in-time inventory commitments to automotive OEM supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tier-1 automotive and electronics OEM consolidation onto approved vendor lists has shifted procurement leverage toward buyers with collaborative development requirements. This buyer-power concentration rewards suppliers with direct engineering relationships and punishes catalog-dependent distributors.
For Market Incumbents: Insulate specification authority by deepening direct OEM engineering programs and captive adhesive resin production. Battery thermal management qualification timelines from BYD and Volkswagen create switching costs that defend position against Asian electronics-grade entrants. Backward integration into acrylic polymer production secures margin capture during petrochemical volatility cycles. For New Entrants and Emerging Players: Mid-market automotive component localization in Tamil Nadu and Gujarat represents the most penetrable entry point, given PLI scheme incentives and BIS certification gaps among established multinational suppliers. Biodegradable packaging tape formulations for European consumer goods brands offer a sustainability-differentiated wedge. Partner with domestic Indian slitting operators to bypass capital-intensive precision equipment requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated suppliers with die-cut converting and application tooling capabilities serving automotive battery platforms. Long-term viability across the analysis window favors adhesive formulators with polymer science expertise concentrated in Japan and Germany. Monitor MIIT battery safety standard revisions as inflection indicators for thermal runaway containment tape demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Resin Production | Captures margin compression from acrylic monomer volatility affecting Dongguan converters. |
| Direct OEM Engineering Relationship Programs | Bypasses distributor disintermediation visible in Volkswagen battery platform specifications. |
| Cleanroom-Compatible Tape System Certification | Unlocks OLED lamination demand from South Korean and Taiwanese display manufacturers. |
| Biodegradable Backing Material Development | Positions for European consumer goods sustainability mandates under REACH reformulation timelines. |
| Precision Slitting Capacity Expansion in India | Serves PLI-scheme EV manufacturing clusters in Tamil Nadu with localized die-cutting capability. |
Research Methodology
Cross-validation between primary interviews with adhesive formulators and secondary trade data anchors the qualitative findings in this study. Tape converter operations heads, automotive tier-1 procurement managers, electronics cleanroom materials engineers, and polymer science R&D directors provided operational perspective. Secondary sources included customs and trade flow databases, chemical industry association reports, SEC filings from listed materials companies, and regulatory submissions to ECHA and MIIT. Bottom-up demand modeling from end-use applications triangulates against top-down market sizing from adhesive resin production volumes.
Calibration against historical capacity utilization rates in Chinese slitting clusters and German automotive adhesive consumption patterns validates the projection framework. Segmentation dimensions include adhesive chemistry type, backing substrate material, end-use industry vertical, and regional production hub classification. CAGRs derive from elasticity-adjusted demand curves across the modeling period, incorporating EV platform rollout schedules and REACH sunset date impacts on formulation substitution. Battery thermal management content-per-vehicle assumptions and display manufacturing capacity expansion pipelines inform sector-specific trajectories.
Practitioners should monitor ECHA authorization timelines and MIIT battery safety standard revisions for early signals of reformulation-driven demand shifts. Forecasts reflect assumptions about petrochemical input stability and OEM vendor list consolidation trajectories that could accelerate or decelerate based on trade policy developments. Cross-checking against IHS Markit vehicle production databases and chemical industry capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tissue Tapes Market
Tapes
Invisible Tapes Market
Tapes
Pouch Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
India Masking Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Release Tape Market
Tapes
Spacer Tapes Market
Tapes
Painting Masking Tapes Market
Tapes
Heat Activated Tear Tape Market
Tapes
UV Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Tear Tape Dispenser Market