
 Wing Walk Tapes Market | 2026-2036
Wing Walk Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Wing Walk Tapes Market Analytics
Commercial aviation MRO operators are unwinding legacy procurement patterns as airline fleet renewal accelerates. 3M Company leverages its aerospace-certified adhesive portfolio to dominate OEM specification channels. Tesa SE anchors European supply through direct airline technical partnerships. Advance Tapes International specializes in regional MRO distributor networks across Asia-Pacific markets.
Wing walk tapes are pressure-sensitive adhesive strips engineered with polyurethane or PVC substrates and silicon carbide aggregate surfaces to achieve coefficient of friction thresholds exceeding 0.60 on wet aluminum aircraft skin. These tapes bond permanently to wing surfaces, engine nacelles, and horizontal stabilizers to prevent technician falls during pre-flight inspections and maintenance operations. Anti-slip formulations command the largest volume share due to mandatory fitment on all Part 25 transport category aircraft, while safety marking variants generate superior per-meter margins from custom color-coding requirements. Aerospace end users absorb the majority of value, though railway platform applications represent the fastest-expanding adjacent demand pool.
The FAA airworthiness directives on slip-resistant surfaces and EASA CS-25 certification standards collectively enforce minimum performance thresholds that filter out uncertified suppliers. OSHA workplace safety regulations for ground handling personnel indirectly expand retrofit demand across aging commercial fleets. Buyers must monitor evolving MEE environmental compliance in China and dual carbon goals that may restrict solvent-based adhesive formulations in future procurement cycles.
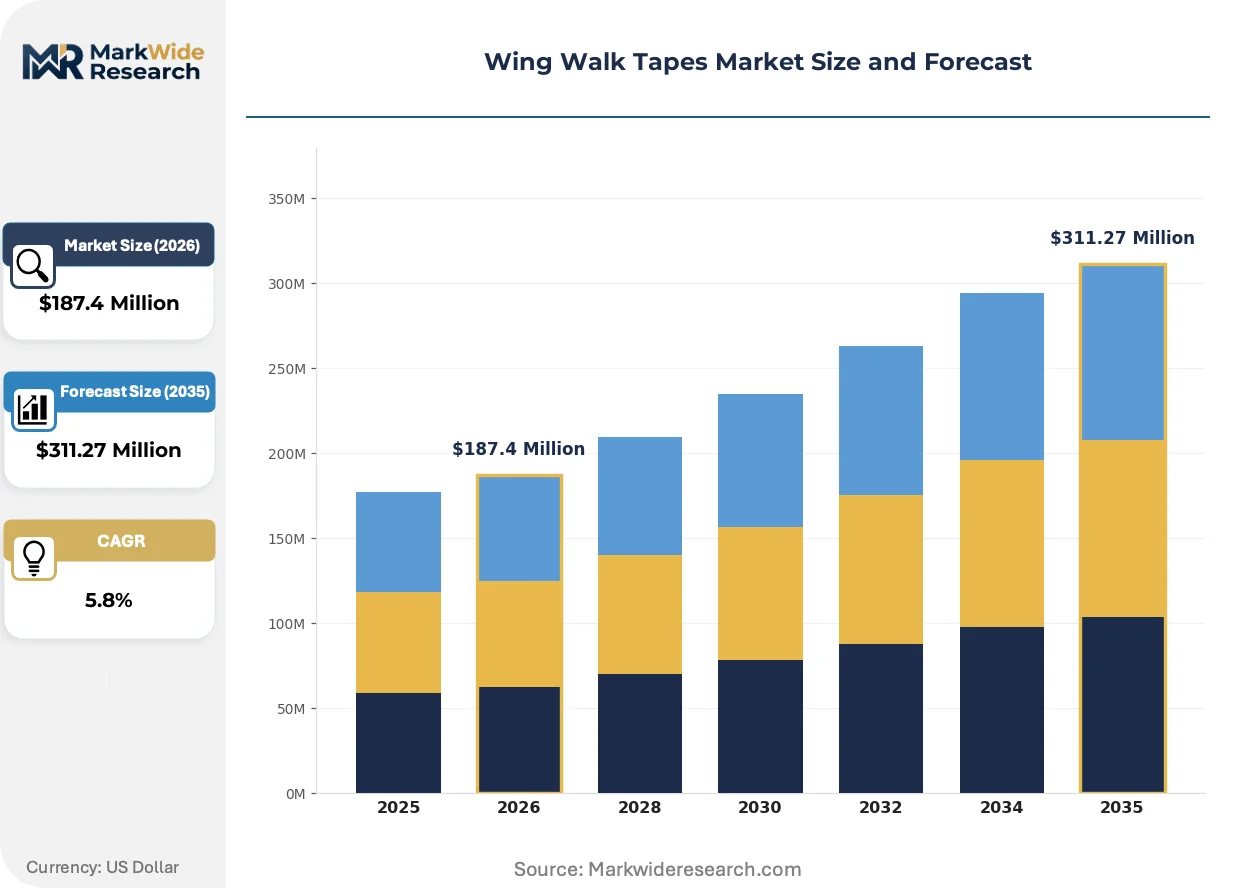
Market Dynamics
Fleet renewal cycles at US and European airlines are compressing procurement timelines for wing walk tape retrofit programs, forcing MRO operators to abandon legacy annual purchasing schedules in favor of continuous replenishment models.
Growth Catalysts
- FAA Airworthiness Directives:Mandated friction coefficient thresholds for Part 25 aircraft walking surfaces are compelling complete tape replacement across aging commercial fleets.
- Silicon Carbide Aggregate Formulations:Advanced abrasive surfaces achieving wet COF above 0.60 are expanding fitment to engine nacelles and horizontal stabilizers previously untreated.
- United States MRO Hub Concentration:Dallas-Fort Worth, Miami, and Los Angeles maintenance clusters generate concentrated demand pull from line maintenance operations.
Market Restraints
- Petrochemical Input Volatility:Polyurethane substrate costs fluctuate with propylene oxide and MDI feedstock pricing, compressing formulation margins.
- Adhesive Supply Concentration:Solvent-based aerospace-grade acrylic adhesives depend on a limited German and Japanese supplier base.
- Substitution Pressure from Spray Coatings:Two-part epoxy anti-slip systems threaten tape retrofit demand in heavy maintenance scenarios.
Strategic Opportunities
- India Fleet Expansion:IndiGo and Air India's narrowbody order books create greenfield specification opportunities at emerging MRO facilities.
- Railway Platform Adjacencies:Anti-slip surface requirements at UK and German commuter stations replicate aerospace friction specifications.
- EASA CS-25 Harmonization:Converging certification standards with FAA Part 25 reduce dual-qualification burdens for pan-Atlantic suppliers.
Industry Challenges
- Certification Timeline Compression:EASA and FAA concurrent validation processes demand 18-24 month qualification cycles that outpace airline fleet entry schedules.
- Aerospace Adhesive Formulation Expertise Scarcity:Pressure-sensitive adhesive chemists with AS9100 audit experience command premium compensation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wing Walk Tapes Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Slip, Safety Marking, Decorative, Insulation Material: Polyurethane, PVC, Acrylic, Rubber End User: Aerospace, Automotive, Railway, Marine Application: Surface Protection, Ground Marking, Safety Measures, Vehicle Maintenance |
| Companies Covered | 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, Tesa SE, Advance Tapes International, Intertape Polymer Group, Scapa Group, Heskins, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wing Walk Tapes Market Evolving Landscape
Material science advances and regulatory harmonization are converging to reshape wing walk tape specifications, with sustainability mandates and performance miniaturization driving parallel development tracks across supplier R&D programs.
Water-based acrylic adhesive systems are miniaturizing volatile organic compound footprints while maintaining peel adhesion above 25 N/cm on etched aluminum substrates. European MRO operators at Lufthansa Technik and Air France Industries KLM Engineering are piloting these formulations to preempt REACH solvent restrictions. The shift is compressing incumbent solvent-based product lifecycles and forcing reformulation investments.
EASA's 2024 update to CS-25 AMC 25.793 harmonizes wet friction testing protocols with FAA AC 25-17A, eliminating redundant qualification requirements for dual-certified suppliers. This convergence reduces certification costs by eliminating divergent test matrices. Asian-Pacific carriers operating mixed Boeing-Airbus fleets are the primary beneficiaries, accelerating supplier consolidation around pan-Atlantic qualified manufacturers.
Airline technical procurement teams are consolidating wing walk tape purchasing under airframe component contracts rather than separate consumable categories. This bundling displaces independent distributor relationships at regional MRO networks. The pattern is most pronounced at US ultra-low-cost carriers where maintenance material spend centralization under fleet management offices eliminates site-level purchasing autonomy.
Wing Walk Tapes Market Segmentation
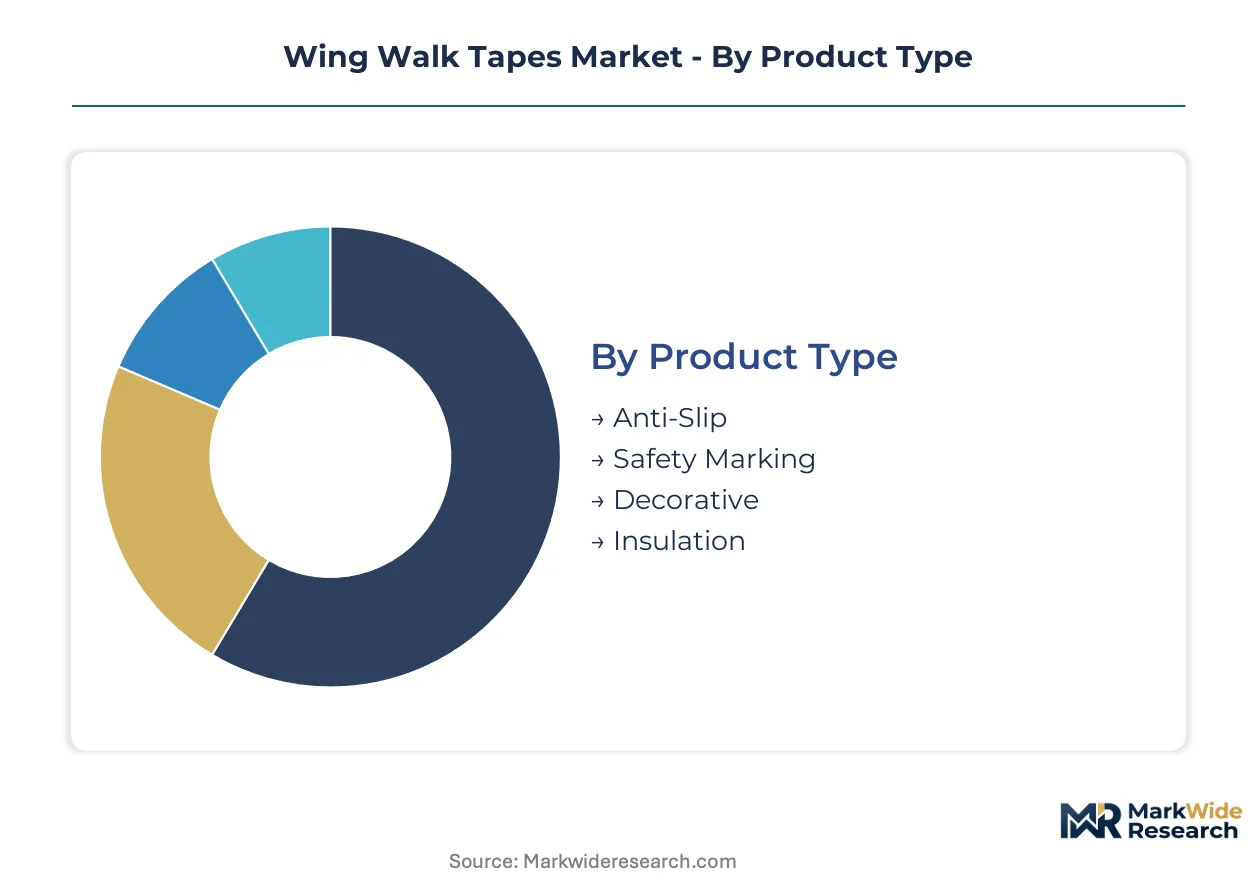
Wing walk tape procurement patterns diverge sharply across material grades and end-use certifications, with aerospace-qualified formulations commanding specification-controlled distribution while industrial variants flow through open distribution channels. Understanding these segment boundaries enables suppliers to align qualification investments with addressable revenue pools.
Product Type:
Anti-slip and safety marking variants dominate export flows to FAA-regulated fleets, while decorative and insulation grades serve predominantly domestic maintenance operations with lighter certification burdens.
- Anti-Slip:Polyurethane substrates bonded with silicon carbide aggregate achieve wet coefficient of friction exceeding 0.60 on etched aluminum. Demand concentrates at Dallas-Fort Worth and Miami MRO hubs serving Part 25 transport category aircraft under FAA airworthiness directives mandating complete surface replacement.
- Safety Marking:Custom color-coded PVC formulations enable technician pathway demarcation on engine nacelles and horizontal stabilizers. European carriers at Lufthansa Technik and Air France Industries KLM Engineering drive specification pull for harmonized EASA CS-25 compliance.
- Decorative:Low-abrasion aesthetic films for private aviation and heritage aircraft restoration. Regional U.S. MRO networks and specialty refinish shops absorb volume.
- Insulation:Thermal barrier tapes for engine proximity zones requiring combined anti-slip and heat-resistant properties. Niche fitment at heavy maintenance facilities.
Anti-slip holds the largest share; momentum sits with safety marking as custom color-coding requirements expand.
Material:
Cost tier stratification separates aerospace-grade formulations with 18-24 month qualification cycles from commercial industrial grades with immediate availability.
- Polyurethane:Dominant aerospace substrate achieving permanent bond strength above 25 N/cm peel adhesion. AS9100-certified production lines at German and Japanese adhesive suppliers constrain capacity expansion.
- PVC:Lower-cost alternative for safety marking and decorative applications with faster turnaround from regional extrusion facilities. Price volatility tracks propylene oxide feedstock movements.
- Acrylic:Water-based formulations piloting at Lufthansa Technik to preempt REACH solvent restrictions. European MRO operators represent the primary demand concentration.
- Rubber:Natural and synthetic elastomer blends for railway platform adjacencies replicating aerospace friction specifications. UK and German commuter station retrofits drive volume.
Polyurethane commands premium positioning; acrylic is climbing the fastest as environmental compliance tightens.
End User:
Application maturity varies from decades-old aerospace specifications to emerging railway platform standards still harmonizing test protocols.
- Aerospace:Original equipment specification channels at Boeing and Airbus facilities, plus MRO retrofit demand from fleet renewal cycles. FAA Part 25 and EASA CS-25 certification gates filter supplier participation.
- Railway:Anti-slip surface requirements at UK and German commuter stations represent the steepest expansion trajectory as infrastructure safety budgets increase. Friction specifications mirror aerospace thresholds.
- Automotive:Motorsport pit lane markings and commercial vehicle maintenance bays. Aftermarket distribution through industrial safety suppliers.
- Marine:Deck treatments for offshore platform maintenance vessels. Salt spray corrosion resistance requirements parallel aerospace environmental testing.
Aerospace absorbs majority value; railway is gaining share fastest as platform safety budgets expand.
Application:
Customer type bifurcation separates specification-driven OEM procurement from price-sensitive aftermarket replenishment.
- Surface Protection:Permanent wing skin and engine nacelle treatments preventing technician falls during pre-flight inspections. Mandatory fitment scope drives consistent replacement demand.
- Safety Measures:Pathway demarcation and hazard zone identification combining anti-slip performance with visual contrast. Custom color requirements generate superior per-meter margins.
- Ground Marking:Hangar floor and maintenance bay applications with lower certification barriers. Industrial safety distributors serve fragmented demand.
- Vehicle Maintenance:Mobile maintenance unit exterior treatments and temporary protective films. Cyclical demand tied to airline capital expenditure cycles.
Surface protection dominates volume; safety measures delivers strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth International Airport's central maintenance complex anchors North American wing walk tape demand through its concentration of Part 25 MRO operations serving narrowbody and widebody fleets.
United States
FAA airworthiness directives mandating wet friction coefficients above 0.60 drive complete tape replacement across aging commercial fleets. OSHA workplace safety regulations for ground handling personnel expand retrofit demand at legacy carriers. Miami and Los Angeles maintenance clusters generate concentrated pull from line maintenance operations at American Airlines and Delta facilities.
Germany
Lufthansa Technik's technical procurement centralization creates specification pull for EASA CS-25 compliant formulations. REACH solvent restrictions accelerate pilot programs for water-based acrylic adhesive systems. The Hamburg MRO campus and Munich assembly corridors concentrate demand from heavy maintenance and OEM integration activities.
United Kingdom
Railway platform safety budgets at UK commuter stations replicate aerospace friction specifications for anti-slip surface treatments. Health and Safety Executive regulations for station infrastructure expand adjacent demand pools beyond aviation. Manchester and Birmingham transport hubs drive volume for dual-certified suppliers bridging aerospace and rail applications.
China
IndiGo and Air India's narrowbody order books create greenfield specification opportunities at emerging MRO facilities through offset partnerships. MEE environmental compliance and dual carbon goals restrict solvent-based adhesive formulations in procurement cycles. The Tianjin Airbus final assembly line and Shanghai Pudong maintenance clusters concentrate technical specification activity.
India
Fleet expansion at IndiGo and Air India generates demand for AS9100-certified tape formulations at new MRO facilities in Delhi-NCR and Hyderabad. BIS standards adoption for aerospace materials tightens supplier qualification requirements. The GMR Aerospace cluster and Tata-Airbus joint venture corridors concentrate emerging specification activity for narrowbody programs.
Wing Walk Tapes Market Competitive Landscape
Concentration sits with diversified adhesive specialists and aerospace-certified manufacturers. The vendor base organizes around three strategic archetypes: diversified materials conglomerates with aerospace adhesive portfolios, European tape specialists with direct airline technical partnerships, and regional distributors serving fragmented MRO networks. Competitive moves center on qualification timeline compression and water-based formulation R&D to preempt REACH and MEE environmental restrictions.
Within the diversified materials tier, 3M Company and Avery Dennison Corporation exemplify specification channel dominance through OEM relationships and AS9100-certified production infrastructure. Tesa SE anchors European supply positioning through technical partnerships with Lufthansa Technik and Air France Industries KLM Engineering. Nitto Denko Corporation represents Japanese adhesive specialization with concentrated aerospace-grade acrylic supply.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Tesa SE |
| Advance Tapes International |
| Intertape Polymer Group |
| Scapa Group |
| Heskins |
| Saint-Gobain |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between major MRO operators and AS9100-certified adhesive suppliers lock in both polyurethane substrate access and price visibility across fleet renewal cycles. These contracts insulate buyers from propylene oxide feedstock volatility while constraining supplier flexibility to serve spot demand from emerging aviation markets.
Pricing Analysis
Three-tier pricing structure across aerospace-qualified, commercial-grade, and industrial-decorative levels separates anti-slip formulations with 18-24 month certification cycles from rapid-turnaround PVC alternatives. Price differentiation rests on AS9100 audit status and wet friction coefficient performance rather than brand premium alone. Cost compression in commercial-grade tiers is intensifying because regional MRO networks consolidate purchasing under airframe component contracts. Ultra-low-cost carriers exhibit highest price sensitivity, while OEM specification channels at Boeing and Airbus facilities absorb premium positioning with minimal volume negotiation.
Supply Chain Analysis
Strategic stockpiling of silicon carbide aggregate and solvent-based acrylic adhesives dominates procurement behavior among Dallas-Fort Worth and Miami maintenance clusters facing FAA-mandated replacement deadlines. Manufacturing concentration centers on Germany, Japan, and the United States for aerospace-grade pressure-sensitive adhesive production. Raw material dependencies draw from propylene oxide, MDI isocyanates, and specialty silicon carbide grit sourced from limited metallurgical suppliers. Single-source vulnerability in German and Japanese adhesive formulation capacity represents the primary structural risk. Distribution runs through OEM specification channels and authorized MRO distributor networks rather than open industrial trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wing walk tape adoption sits in early-cycle expansion as fleet renewal accelerates retrofit demand across aging commercial aircraft platforms. Railway platform safety budgets in the United Kingdom and Germany replicate aerospace friction specifications, opening adjacent penetration pathways beyond aviation.
For Market Incumbents: Shield specification channel positioning at Boeing and Airbus facilities by accelerating water-based acrylic R&D to preempt REACH and MEE solvent restrictions. Deepen backward integration into polyurethane substrate production to offset petrochemical input volatility and compress formulation margins threatening distributor-tier competitors. For New Entrants and Emerging Players: Differentiate on EASA-FAA dual-certification agility to capture IndiGo and Air India narrowbody programs at emerging Delhi-NCR and Hyderabad MRO facilities. Target railway platform retrofits in UK and German commuter stations as the most penetrable adjacent segment, leveraging harmonized friction test protocols with aerospace standards. For Investors and Strategic Acquirers: Regional distributors with AS9100 audit experience and established airline technical partnerships represent the most defensible acquisition archetype for long-term viability. Monitor EASA CS-25 harmonization implementation velocity as the critical inflection signal; accelerated convergence compresses qualification timelines and consolidates supplier margins around pan-Atlantic qualified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Transition | REACH compliance at Lufthansa Technik pilots eliminates solvent-based product lifecycles. |
| Dual-Certification Investment | EASA-FAA harmonization reduces 18-24 month qualification burdens for pan-Atlantic suppliers. |
| Railway Platform Adjacency Entry | UK Health and Safety Executive regulations expand friction-specification demand beyond aviation. |
| Long-Term Airline Contracts | Fleet management office centralization at US ultra-low-cost carriers displaces site-level purchasing. |
| Silicon Carbide Aggregate Sourcing | Permanent wet COF above 0.60 enables engine nacelle and horizontal stabilizer fitment expansion. |
Research Methodology
Cross-validation between primary interviews with MRO procurement directors, airline fleet management officers, and adhesive formulation chemists anchors the qualitative findings against secondary validation from FAA airworthiness directives, EASA CS-25 certification databases, and customs trade flow records. Bottom-up triangulation across polyurethane substrate consumption patterns and top-down reconciliation with OEM specification channel revenues ensures segmentation integrity.
Sensitivity analysis around propylene oxide price volatility and fleet renewal cycle timing informs the analytical framework across the projection horizon. Segmentation dimensions include product type tier, material grade, end-use certification level, and regional MRO hub concentration. CAGRs derive from fitted growth curves against historical replacement demand patterns and regulatory mandate implementation schedules. Silicon carbide aggregate supply constraints and REACH solvent restriction timelines serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained commercial aviation fleet expansion or delayed EASA-FAA harmonization would require recalibration. Forecasts reflect assumptions regarding certification timeline compression and petrochemical input stability. Revision becomes warranted when water-based adhesive performance thresholds cross commercial viability thresholds or railway platform safety budgets exceed infrastructure allocation baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Heat Sealing Tape Market
Tapes
Nylon Cable Ties Market
Tapes
Tape and Label Adhesives Market
Tapes
Hand Wrappers Market
Tapes
Double Coated Film Tapes Market
Tapes
Tapes Market
Tapes
Moisture Barrier Tapes Market
Tapes
Silicone Tape Market
Tapes
Tape Unwinder Market
Tapes
Paper Masking Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Tissue Tapes Market
Tapes
Foam Tape Market
Tapes
Galley Tapes Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Sterilization Tape Market