
 Spacer Tapes Market | 2026-2036
Spacer Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Spacer Tapes Market Analytics
South Korea is narrowing its specialty tape supply gap through dedicated polymer processing zones near Seoul and Busan. tesa SE leverages its European R&D footprint to sustain formulation leadership in high-temperature automotive grades. Saint-Gobain anchors North American demand through vertically integrated foam substrate production. 3M competes on patent density across acrylic adhesive platforms for electronics spacing.
Spacer tapes are dimensionally stable adhesive-backed strips, typically engineered from polyethylene foam or acrylic carriers with calibrated thickness tolerances between 0.1 mm and 3.0 mm, designed to maintain precise gaps between bonded surfaces while absorbing mechanical stress and thermal expansion. Foam tapes dominate volume consumption in construction and automotive sealing where compressibility and weather resistance outweigh unit cost, while double-sided tapes command premium positioning in electronics mounting where residue-free removability and dielectric performance determine specification. Specialty tapes represent the fastest-expanding margin pool as aerospace OEMs qualify custom formulations for outgassing control and flame retardancy under FAR 25.853.
REACH in Europe mandates full substance disclosure for adhesive chemistries above 0.1% w/w concentration, forcing reformulation of legacy solvent-based systems. EPA TSCA Section 6 restrictions on persistent organic pollutants in the United States are accelerating water-based acrylic migration across imported tape portfolios. China's GB standards for construction material flammability are raising barrier heights for uncertified polyethylene foam imports. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Electric vehicle battery pack assembly is compressing bonding tolerances below 0.2 mm, forcing spacer tape suppliers to recalibrate die-cutting precision and thermal cycling performance simultaneously across multiple qualification cycles.
Growth Catalysts
- EV Battery Bonding:Automotive OEMs in Germany are specifying multi-layer foam laminates for thermal interface management in pouch cell configurations, creating specification pull for high-compression set materials.
- REACH Disclosure Mandates:ECHA's 0.1% w/w substance disclosure threshold is accelerating water-based acrylic reformulation, opening substitution windows for compliant European suppliers against legacy solvent-based imports.
- Electronics Miniaturization:Display assembly lines in South Korea are adopting sub-millimeter thickness tapes for foldable smartphone hinge gaps, driving precision coating equipment investments near Seoul.
Market Restraints
- Petrochemical Feedstock Volatility:Polyethylene foam substrates face margin compression from ethylene price swings tied to naphtha cracking economics in Northeast Asia.
- Concentrated Acrylic Supply:Three chemical conglomerates control bulk acrylic acid ester production, creating single-source vulnerability for mid-tier tape coaters without backward integration into monomer supply.
- Silicone Substitution Pressure:Liquid silicone gap fillers are displacing foam tapes in high-heat automotive underhood applications above 150°C continuous service temperature.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme subsidies for mobile phone assembly are attracting tape converters to set up slitting operations in Tamil Nadu and Uttar Pradesh industrial corridors.
- FAR 25.853 Qualification:Aerospace OEMs are qualifying custom low-outgassing formulations for satellite payload bonding, creating 3-5 year sole-source contracts with certified suppliers.
- Direct-to-Factory Digital Platforms:Tape distributors are launching specification-matching portals that bypass traditional converter networks for standard thickness construction grades.
Industry Challenges
- Adhesive Formulation Talent Scarcity:Cross-functional expertise combining polymer chemistry and electronics assembly process engineering commands premium compensation and extended recruitment cycles.
- Multi-Jurisdiction Certification Overlap:Simultaneous UL 94 flammability, FAA outgassing, and automotive OEM material approvals extend qualification timelines by 18-24 months for new product introductions.
- Legacy Equipment Retrofit Costs:Converting lines built for solvent-based coating require capital-intensive ventilation and solvent recovery upgrades to handle water-based viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spacer Tapes Market |
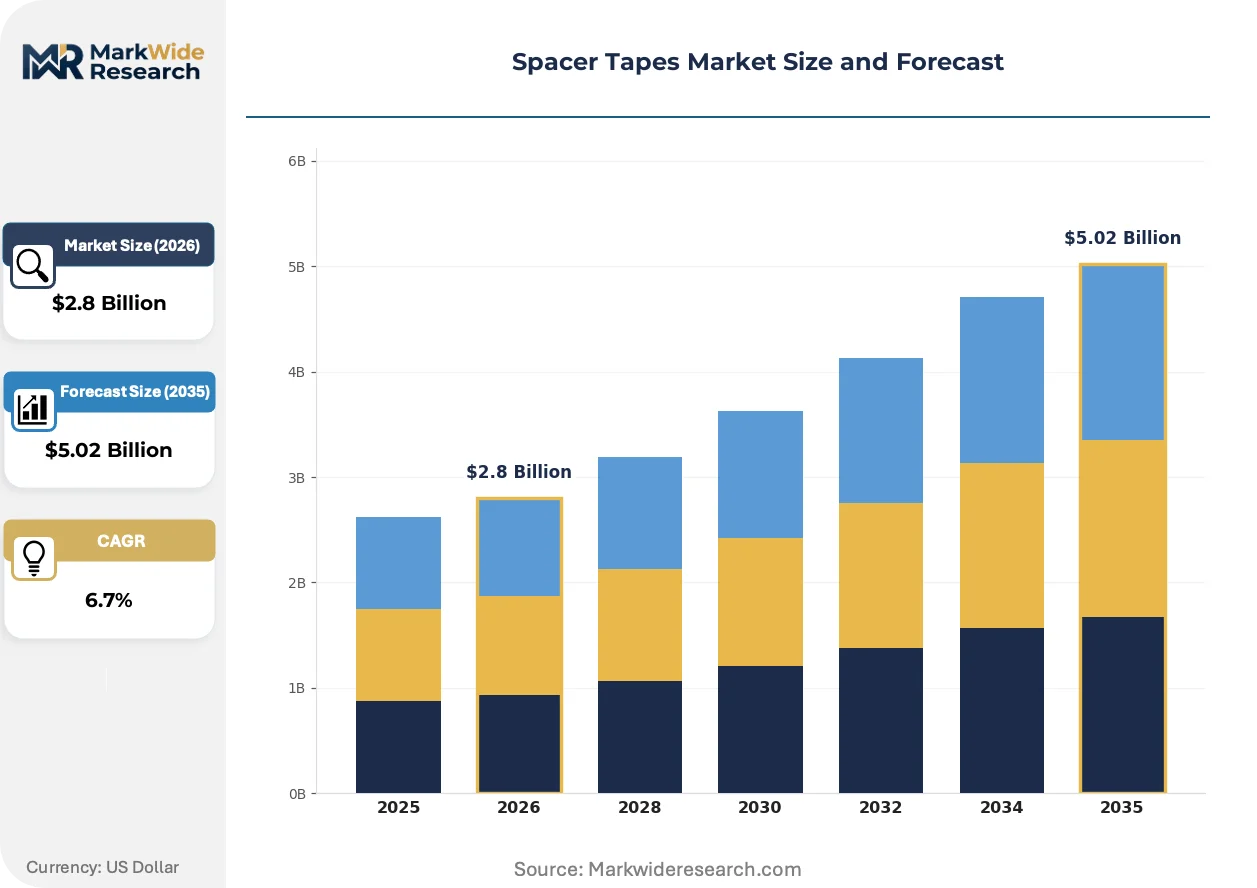
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Tapes, Double-Sided Tapes, Adhesive Tapes, Specialty Tapes Material: Polyethylene, Acrylic, PVC, Rubber Industry Vertical: Automotive, Electronics, Construction, Aerospace Application: Insulation, Mounting, Spacing, Sealing |
| Companies Covered | tesa SE, Saint-Gobain, Sika AG, 3M, Avery Dennison Corporation, Scapa, Capital Tape Company, Inc., Gaska Tape Inc., Adhesives Research, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spacer Tapes Market Evolving Landscape
Precision thickness control is migrating from mechanical die-cutting to laser-scored release liners, enabling single-digit micron tolerances for electronics spacing applications while compressing setup waste and qualification scrap rates.
Laser-scored spacer tape manufacturing is digitizing quality assurance through inline machine vision systems that map thickness variation across entire master rolls. Automotive battery pack assemblers in Germany are specifying 100% dimensional verification certificates, rejecting traditional statistical sampling protocols. This digitizing of quality documentation is compressing supplier qualification cycles from 18 months to 8 months for qualified laser-scoring equipment operators.
EPA TSCA Section 6 restrictions on persistent organic pollutants are accelerating water-based acrylic migration across imported tape portfolios entering US manufacturing supply chains. Tape coaters with legacy solvent-based lines face capital decisions on equipment replacement versus formulation retrofit. Construction-grade polyethylene foam imports are experiencing extended customs holds pending TSCA certification documentation, favoring domestic water-based production capacity.
Specification-driven procurement is consolidating purchase authority from plant-level maintenance managers to central engineering teams with direct OEM qualification relationships. Tier-1 automotive suppliers are mandating approved vendor lists with pre-qualified tape thickness grades, eliminating spot-buying flexibility at individual assembly facilities. This concentration is most visible in German automotive supply chains where battery pack bonding specifications are locked 24 months ahead of production ramp.
Spacer Tapes Market Segmentation
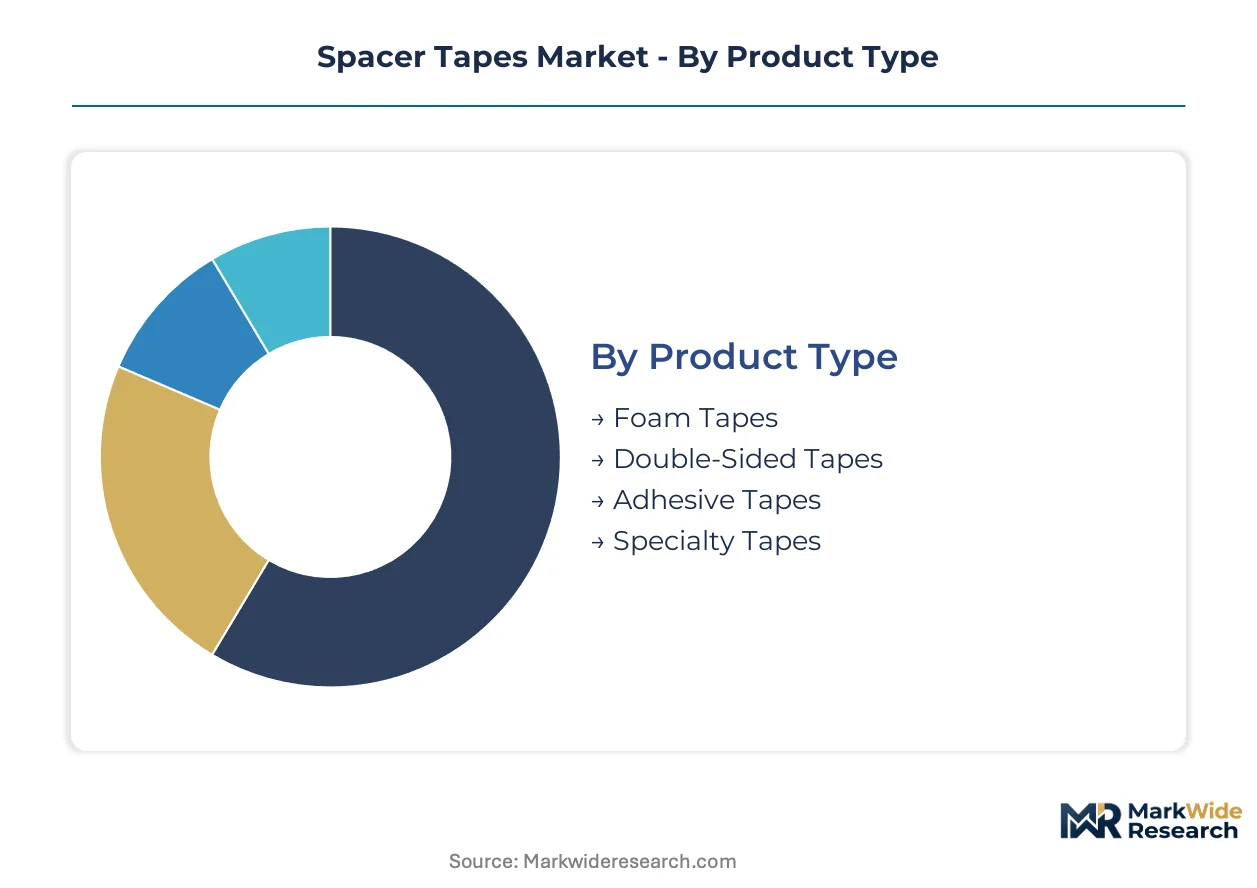
Spacer tape procurement cycles vary dramatically by end-use. Automotive battery pack qualifications lock specifications 24 months ahead of production ramp. Electronics assembly lines rotate tape grades quarterly based on device model refreshes. Aerospace OEMs maintain decade-long sole-source contracts with certified suppliers.
Product Type:
Double-sided tapes turn inventory fastest in South Korean display corridors where hinge gap specifications shift with each smartphone generation. Foam tapes rotate slowest through construction distribution channels stocked for weather sealing projects with 18-month procurement horizons.
- Foam Tapes:Compressible polyethylene or polyurethane substrates absorb mechanical stress and thermal expansion in building envelopes and automotive sealing. German EV manufacturers specify multi-layer foam laminates for thermal interface management in pouch cell configurations, pulling demand toward high-compression set materials with sub-0.2 mm tolerances.
- Double-Sided Tapes:Calibrated acrylic adhesive layers on both faces enable residue-free removability critical for electronics mounting. Seoul-area display assembly lines adopt sub-millimeter thickness grades for foldable smartphone hinge gaps, compressing supplier qualification cycles to 8 months for laser-scoring equipment operators.
- Adhesive Tapes:General-purpose bonding strips serve maintenance and repair applications across industrial facilities.
- Specialty Tapes:Custom formulations for outgassing control and FAR 25.853 flame retardancy in satellite payload bonding command 3-5 year sole-source contracts.
Foam tapes dominate installed base. Specialty tapes are where expansion concentrates.
Material:
Acrylic formulations command premium pricing in precision electronics spacing. Polyethylene serves volume construction markets where weather resistance outweighs unit cost sensitivity.
- Polyethylene:Closed-cell foam substrates deliver compressibility and moisture resistance for construction sealing and automotive gasketing. China's GB standards for construction material flammability are raising barrier heights for uncertified imports, favoring domestic water-based production capacity.
- Acrylic:Pressure-sensitive adhesive platforms enable precise thickness control with dielectric performance for electronics mounting. EPA TSCA Section 6 restrictions on persistent organic pollutants are accelerating water-based acrylic migration across imported tape portfolios entering US manufacturing supply chains.
- PVC:Rigid carrier films provide dimensional stability in industrial mounting applications with moderate temperature exposure.
- Rubber:Natural and synthetic elastomer bases deliver high-tack adhesion for heavy-duty industrial bonding.
Polyethylene anchors volume consumption. Acrylic is climbing the fastest.
Industry Vertical:
Electronics verticals rotate specifications quarterly. Aerospace qualifications extend across decade-long platform lifecycles with minimal formulation changes.
- Automotive:Battery pack bonding applications compress tolerances below 0.2 mm, forcing simultaneous recalibration of die-cutting precision and thermal cycling performance. German OEMs are locking specifications 24 months ahead of production ramp, consolidating purchase authority to central engineering teams.
- Electronics:Display and semiconductor assembly demand sub-millimeter thickness precision with residue-free removability. South Korea's PLI-scheme mobile phone assembly subsidies are attracting tape converters to set up slitting operations in Tamil Nadu and Uttar Pradesh industrial corridors.
- Construction:Weather sealing and glazing applications prioritize compressibility and UV resistance over micron-level tolerances.
- Aerospace:Satellite payload bonding requires FAR 25.853 qualification for low-outgassing and flame retardancy, creating multi-year sole-source relationships.
Construction dominates installed base. Automotive is gaining share fastest.
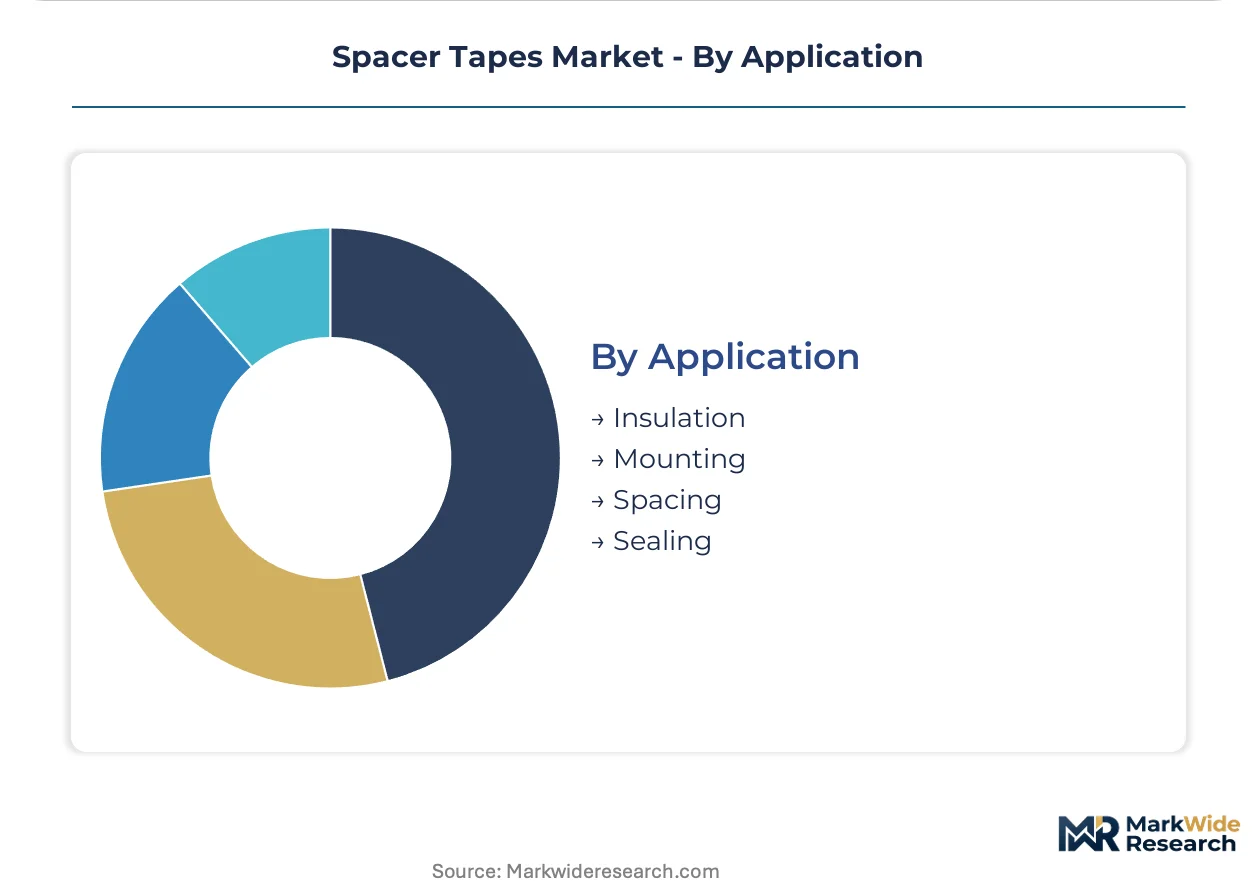
Application:
Mounting applications in electronics rotate specifications fastest with device model cycles. Insulation applications in building envelopes maintain stable procurement patterns across multi-year construction projects.
- Insulation:Thermal and acoustic barrier applications in building envelopes and industrial equipment. Construction-grade polyethylene foam imports face extended customs holds pending TSCA certification documentation.
- Mounting:Permanent and removable attachment of components in electronics and signage. Precision thickness control is migrating from mechanical die-cutting to laser-scored release liners, enabling single-digit micron tolerances while compressing setup waste.
- Spacing:Maintaining calibrated gaps between bonded surfaces under mechanical stress and thermal expansion.
- Sealing:Environmental barrier applications against moisture, dust, and air infiltration in automotive and construction.
Sealing dominates installed base. Mounting is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH disclosure mandates anchor European demand calibration, while battery assembly and electronics mounting pull procurement toward Germany and South Korea respectively.
Germany
Automotive OEMs specify multi-layer foam laminates for EV pouch cell thermal interface management. KBA oversees material compliance for vehicle safety applications. Stuttgart-area battery pack assemblers lock spacer tape specifications 24 months ahead of production ramp.
South Korea
Display manufacturers adopt sub-millimeter thickness tapes for foldable smartphone hinge gaps. MFDS maintains oversight of industrial chemical safety in manufacturing zones. Seoul and Busan polymer processing corridors attract precision coating equipment investments.
United States
EPA TSCA Section 6 restrictions accelerate water-based acrylic migration across imported tape portfolios. Construction-grade polyethylene foam faces extended customs holds pending certification. Michigan and Ohio automotive corridors drive qualification demand for battery bonding applications.
China
GB standards for construction material flammability raise barrier heights for uncertified polyethylene foam imports. MEE enforces environmental compliance across adhesive manufacturing. Yangtze River Delta tape coaters invest in water-based line retrofits to maintain US export access.
India
PLI scheme subsidies for mobile phone assembly attract tape converters to establish slitting operations. BIS certification requirements shape import substitution strategies. Tamil Nadu and Uttar Pradesh industrial corridors concentrate new converter capacity near electronics assembly demand.
Spacer Tapes Market Competitive Landscape
Specialty chemical conglomerates and diversified materials groups split the market along formulation depth versus substrate breadth lines. Three archetypes dominate: vertically integrated foam substrate producers, precision adhesive formulators with R&D footprints, and regional converters leveraging tariff-advantaged slitting capacity. Competitive moves concentrate on qualification-driven sole-source contract capture and laser-scoring equipment deployment for micron-tolerance segments.
Among European-headquartered formulators, tesa SE exemplifies the precision adhesive archetype through its sustained formulation leadership in high-temperature automotive grades. Saint-Gobain anchors the substrate-integrated tier through captive foam production serving North American demand concentration. 3M occupies a position defined by patent density across acrylic adhesive platforms for electronics spacing applications. These three represent distinct strategic vectors: formulation specialization, backward integration into substrate supply, and intellectual property accumulation.
| Leading Market Players |
|---|
| tesa SE |
| Saint-Gobain |
| Sika AG |
| 3M |
| Avery Dennison Corporation |
| Scapa |
| Capital Tape Company, Inc. |
| Gaska Tape Inc. |
| Adhesives Research, Inc. |
| Others |
Value Network & Pricing Analysis
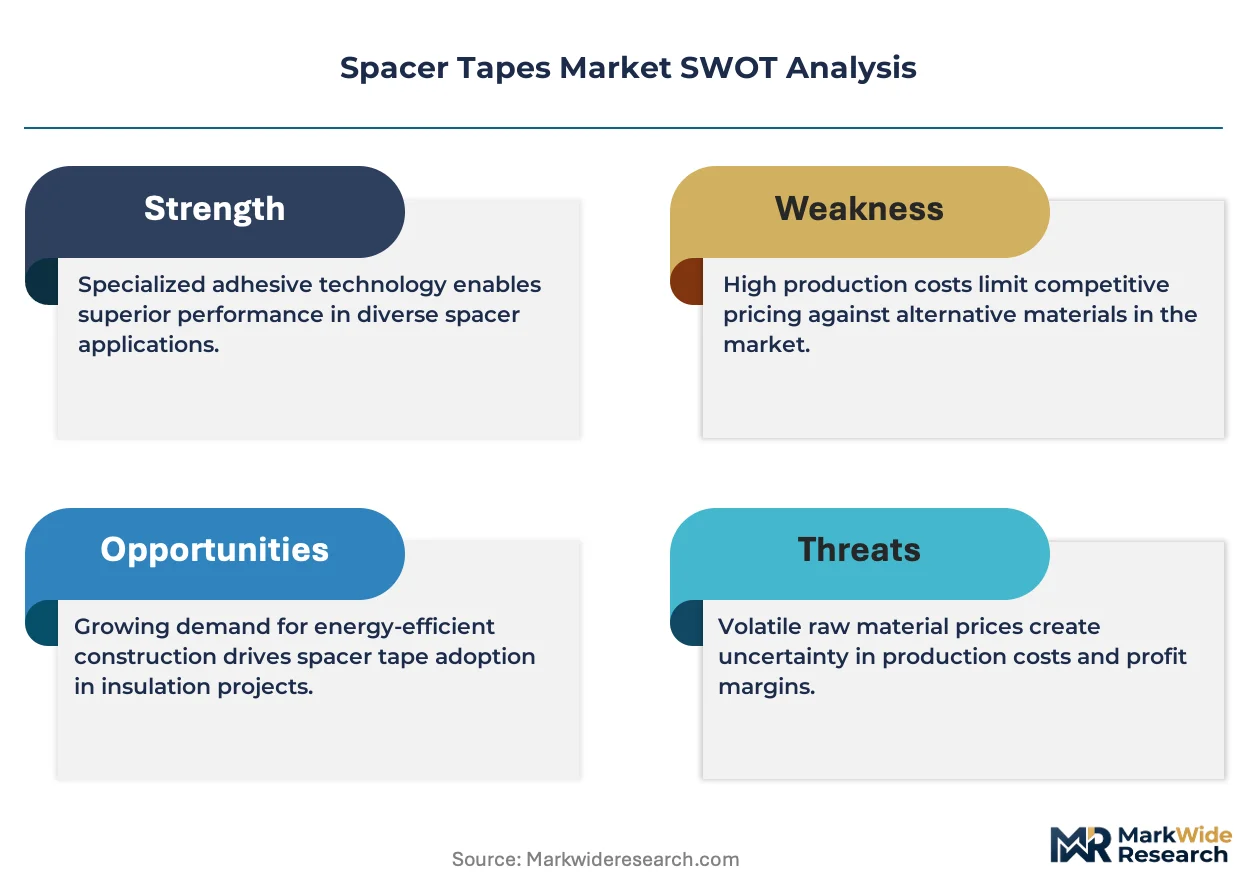
Three chemical conglomerates controlling bulk acrylic acid ester production in Northeast Asia concentrate margin capture at the formulation tier, forcing mid-tier tape coaters without backward integration into monomer supply to accept compressed spreads or exit precision electronics segments.
Pricing Analysis
Acrylic adhesive platforms command 40-60% premiums over polyethylene foam substrates across South Korean display corridors, where sub-millimeter thickness tolerances and dielectric performance separate specification tiers. Pricing stratifies across aerospace FAR 25.853 certification, automotive OEM qualification, and construction-grade commodity levels. Cost compression in standard foam tapes is intensifying because ethylene price volatility tied to naphtha cracking economics feeds directly into substrate costs. Construction distributors exhibit highest price sensitivity, while aerospace OEMs accept multi-year sole-source premiums for outgassing-controlled formulations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for water-based acrylic tape portfolios facing EPA TSCA Section 6 documentation requirements. Manufacturing gravity centers on Germany for automotive qualification, South Korea for electronics precision, and China for polyethylene foam substrate volume. Raw material dependencies span ethylene feedstocks for foam substrates, acrylic acid esters for adhesive platforms, and release liner films. Distribution runs through approved vendor lists at Tier-1 automotive suppliers, bypassing spot-buying flexibility at individual assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where 18-24 month multi-jurisdiction certification timelines create switching costs that entrench qualified suppliers against unqualified challengers.
For Market Incumbents: Insulate formulation leadership through captive R&D investment in laser-scoring equipment for micron-tolerance segments, while locking 24-month sole-source contracts with German automotive OEMs ahead of battery pack production ramps. Liquid silicone gap fillers above 150°C service temperatures threaten foam tape displacement in underhood applications.
For New Entrants and Emerging Players: Build out slitting operations in Tamil Nadu and Uttar Pradesh corridors to capture PLI-subsidized mobile phone assembly demand with tariff-advantaged regional supply. Indian electronics manufacturing presents the most penetrable white space, with qualification cycles compressing to 8 months for precision coating equipment operators versus 18-24 months in aerospace.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converters lacking backward integration into acrylic monomer supply or captive foam substrate production. Long-term viability hinges on qualification density across automotive and aerospace verticals. Watch for water-based line retrofit completion rates among solvent-dependent coaters as inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Reduces single-source vulnerability from three chemical conglomerates controlling bulk ester production. |
| Laser-Scoring Equipment Deployment | Enables single-digit micron tolerances for South Korean foldable smartphone hinge gap specifications. |
| FAR 25.853 Qualification Investment | Captures 3-5 year sole-source contracts with aerospace OEMs for satellite payload bonding applications. |
| Water-Based Line Retrofit Completion | Maintains US export access under EPA TSCA Section 6 persistent organic pollutant restrictions. |
| Direct-to-Factory Digital Platform Launch | Bypasses traditional converter networks for standard thickness construction grades with specification-matching portals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and ECHA REACH registration databases, combining structured interviews with adhesive formulators, automotive Tier-1 procurement leads, and electronics coating equipment operators. Bottom-up demand modeling from end-use qualification cycles triangulates against top-down supply-side capacity assessments across polymer processing zones.
Forecast inputs span product type segmentation across foam, double-sided, and specialty tapes; material platforms including acrylic, polyethylene, and PVC; and industry verticals from automotive battery bonding to aerospace satellite payload mounting. CAGR derivation incorporates adhesive formulation talent scarcity premiums, multi-jurisdiction certification timeline extensions, and legacy equipment retrofit capital requirements across the projection horizon.
Stress conditions across ethylene feedstock volatility, REACH disclosure threshold enforcement, and silicone substitution rates above 150°C were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on qualification cycle compression and water-based formulation migration timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Building and Construction Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Pucker Free Tapes Market
Tapes
Tear Tape Dispenser Market
Tapes
Tape Backing Materials Market
Tapes
Cable Wrapping Tapes Market
Tapes
Paper Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
ESD Tapes and Labels Market
Tapes
Gaffers Tape Market
Tapes
Tape Dispenser Market
Tapes
Labels, Tapes and Films Market
Tapes
Thermal Transfer Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Tabbing Tapes Market