
 Moisture Barrier Tapes Market | 2026-2036
Moisture Barrier Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture Barrier Tapes Market Analytics
EPA regulations on volatile organic compound emissions from construction adhesives and sealants is hardening demand for low-VOC moisture barrier formulations. 3M leverages its polymer science portfolio to sustain leadership in pressure-sensitive adhesive platforms for building envelope applications. DuPont anchors its position through fluoropolymer and advanced film technologies that compete on permeance ratings in commercial roofing systems.
Moisture barrier tapes are pressure-sensitive adhesive laminates engineered to block liquid water and water vapor transmission, typically constructed with polyethylene or PVC backings bonded to rubber or silicone adhesives with specified perm ratings below 1.0 perms for Class I vapor retarder performance. Single-sided tapes dominate volume in construction sheathing and flashing applications where peel-and-stick installation speed reduces labor cost, while specialty tapes command premium positioning in electronics cleanroom assembly where outgassing specifications determine qualification. Polyethylene-based formulations lead material share due to cost efficiency in residential wrapping, though silicone adhesive variants capture margin pools in automotive underbody corrosion protection where thermal cycling resistance is mandatory.
FDA oversight of adhesive components in food-contact packaging applications shapes material selection for barrier tapes used in cold-chain logistics, while OSHA workplace exposure limits for solvent-based adhesives push manufacturers toward hot-melt and UV-cured processing platforms. REACH chemical restrictions in Europe constrain phthalate plasticizer use in PVC backings, redirecting formulation investment toward bio-based alternatives. Stakeholders must monitor evolving building code harmonization between IECC and ASHRAE standards to anticipate specification shifts that will redefine competitive qualification requirements.
Market Dynamics
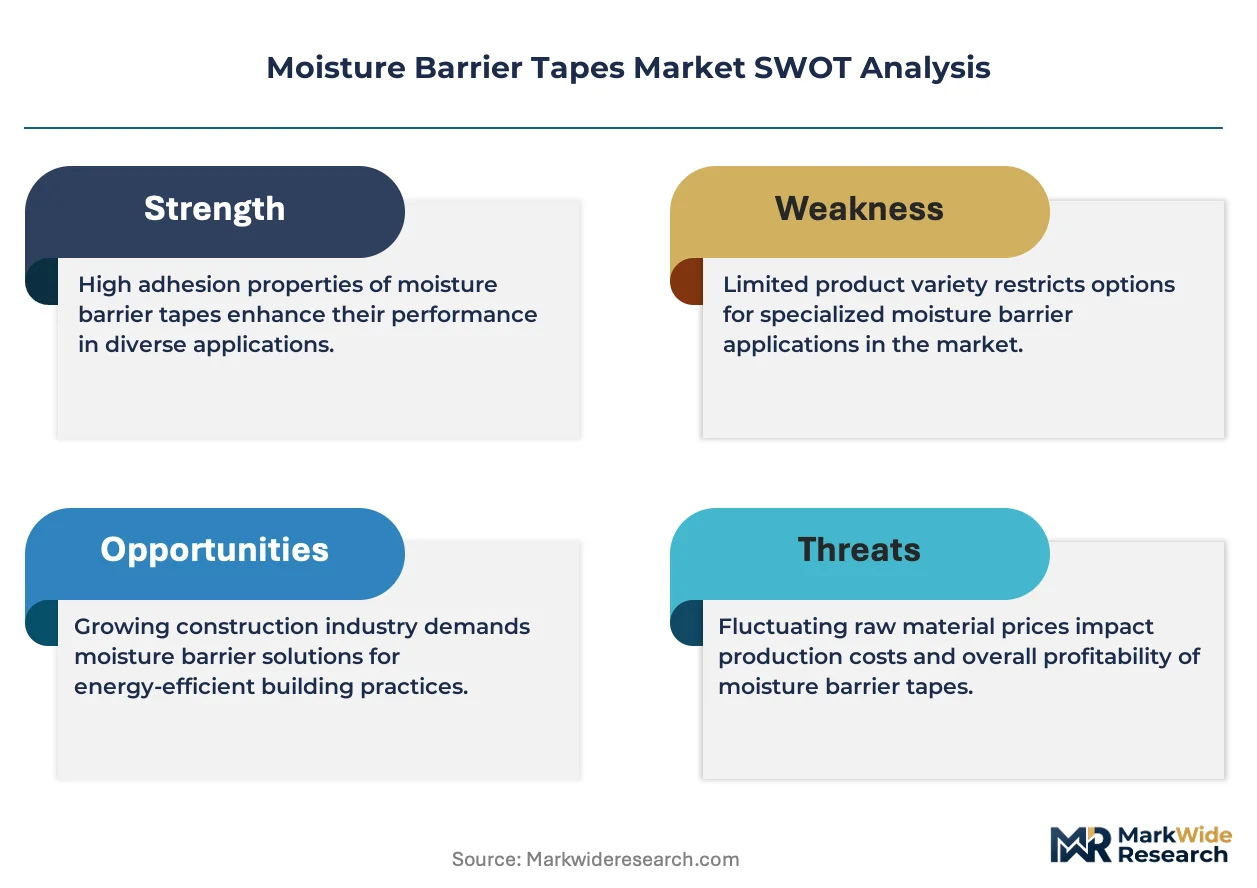
Building envelope energy codes are hardening across jurisdictions, forcing specification upgrades from commodity polyethylene tapes to engineered vapor retarders with certified permeance ratings and multi-climate durability testing.
Growth Catalysts
- EPA VOC Phase-Down:The U.S. EPA's tightening emission standards for construction adhesives is disqualifying solvent-based formulations and redirecting specification toward hot-melt and UV-cured moisture barrier platforms in commercial building applications.
- Passive House Construction Clustering:Germany's Darmstadt-Kranichstein and Vienna districts are concentrating demand for sub-0.1 perm Class I vapor retarders in multi-family residential envelopes, creating specification pull-through across Central European supply chains.
- Polymer Film Advances:Co-extruded multilayer polyethylene films with integrated desiccant layers are extending service life in below-grade waterproofing, displacing traditional bituminous sheet membranes in foundation applications.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene price swings directly compress margin on polyethylene and polypropylene backing substrates, forcing inventory risk onto converters without long-term supply agreements.
- Silicone Adhesive Concentration:Specialty silicone PSA production centers on a narrow base of German and Japanese chemical suppliers, creating single-source vulnerability for automotive and electronics-grade moisture barrier specifications.
- REACH Phthalate Restrictions:ECHA's expanding list of restricted plasticizers in PVC formulations is forcing reformulation cycles that delay product requalification with major construction distributors.
Strategic Opportunities
- India Green Building Code Expansion:The Bureau of Energy Efficiency's Eco-Niwas Samhita mandates are creating first-time demand for vapor control layers in residential construction across Mumbai, Delhi, and Bangalore metro corridors.
- Cold-Chain Packaging Convergence:FDA-regulated pharmaceutical distribution is absorbing moisture barrier tapes with integrated temperature indicators, merging passive barrier and active monitoring functions in single-use shipping systems.
- Automotive Battery Enclosure Sealing:Electric vehicle battery pack IP67 sealing requirements are opening specification windows for silicone-foam hybrid tapes that manage thermal runaway pressure events alongside moisture ingress prevention.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of IECC, ASHRAE 90.1, and PHIUS certifications for a single product platform extends qualification cycles and fragments R&D resource allocation.
- Adhesive Coater Capacity Bottlenecks:Narrow-web precision coating assets for electronics-grade cleanroom tapes require capital commitments exceeding mid-tier converter balance sheet capacity, consolidating supply among integrated film manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture Barrier Tapes Market |
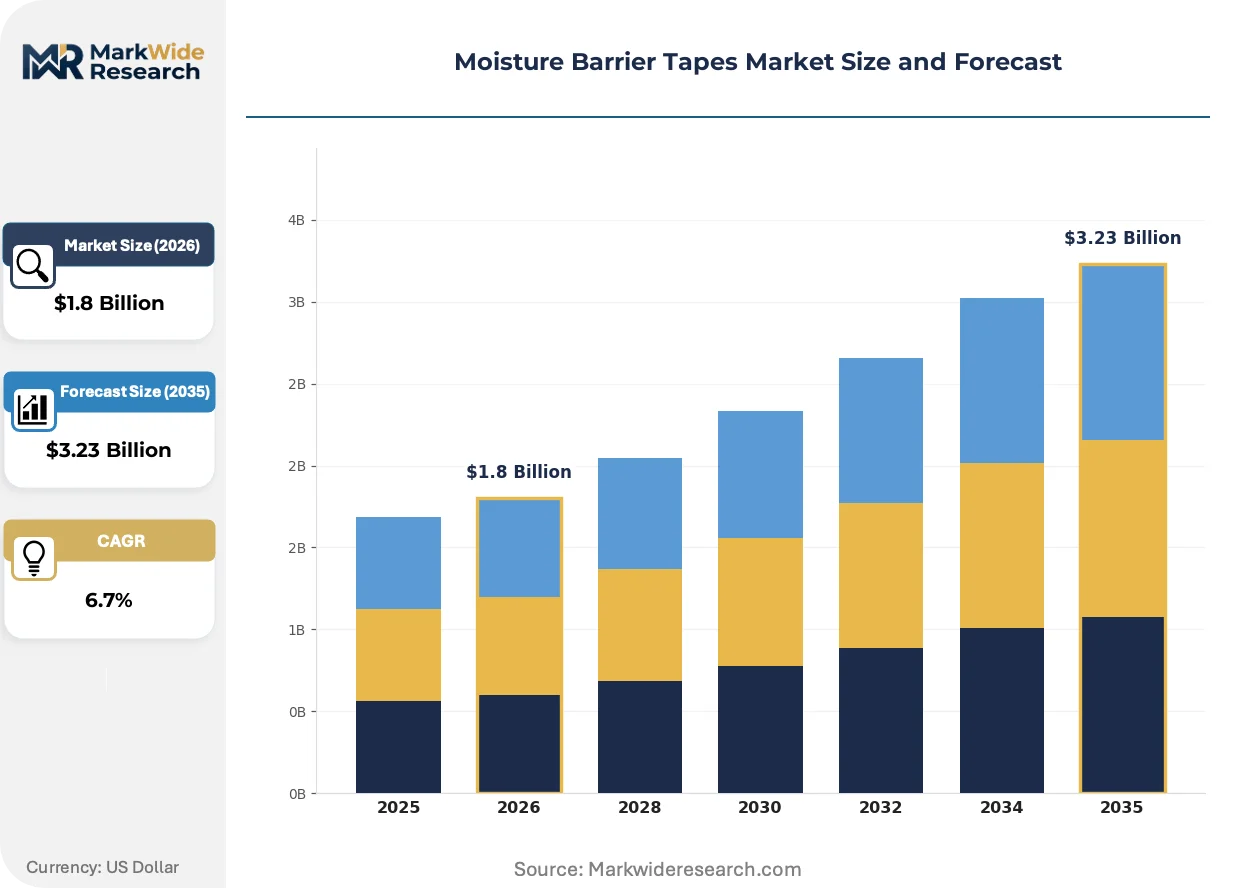
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tapes, Double-Sided Tapes, Custom Tapes, Specialty Tapes Material: PVC, Polyethylene, Rubber, Silicone Application: Construction, Electronics, Automotive, Packaging End User: Contractors, Manufacturers, Distributors, Retailers |
| Companies Covered | 3M, Scapa, DuPont, Stego Industries, ISI Building Products, Elliott Group International, WR Meadows, 3F Adhesive Tapes, tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture Barrier Tapes Market Evolving Landscape
Material science convergence is dissolving traditional boundaries between vapor retarders, air barriers, and thermal breaks, creating hybrid products that compete on installed system performance rather than component specifications.
Multilayer co-extrusion with nanoclay reinforcement is unifying vapor retardance and structural rigidity in a single polyethylene substrate. Passive house contractors in Austria and Switzerland are specifying these composites for window-to-wall transitions where dimensional stability under cyclic loading determines warranty coverage. The technology is compressing the distinction between sheathing membrane and flashing tape categories, enabling single-source envelope system procurement.
REACH's Substances of Very High Concern candidate list expansion is forcing substitution of chlorinated paraffin flame retardants in construction-grade PVC backings. German tape converters are accelerating bio-based plasticizer trials with epoxidized soybean oil formulations to maintain CE marking compliance. Commercial roofing contractors face specification uncertainty as legacy products phase out before replacements achieve equivalent UV resistance ratings.
Consolidated general contractors are unbundling tape specification from framing and sheathing packages, creating direct procurement relationships with specialized envelope material distributors. This disintermediation is visible in the U.S. Pacific Northwest where design-build firms source vapor retarders separately from structural packages to capture LEED v4.1 material ingredient reporting credits. Distributor technical sales teams now coordinate directly with project energy modelers to optimize permeance sequencing across wall assemblies.
Moisture Barrier Tapes Market Segmentation
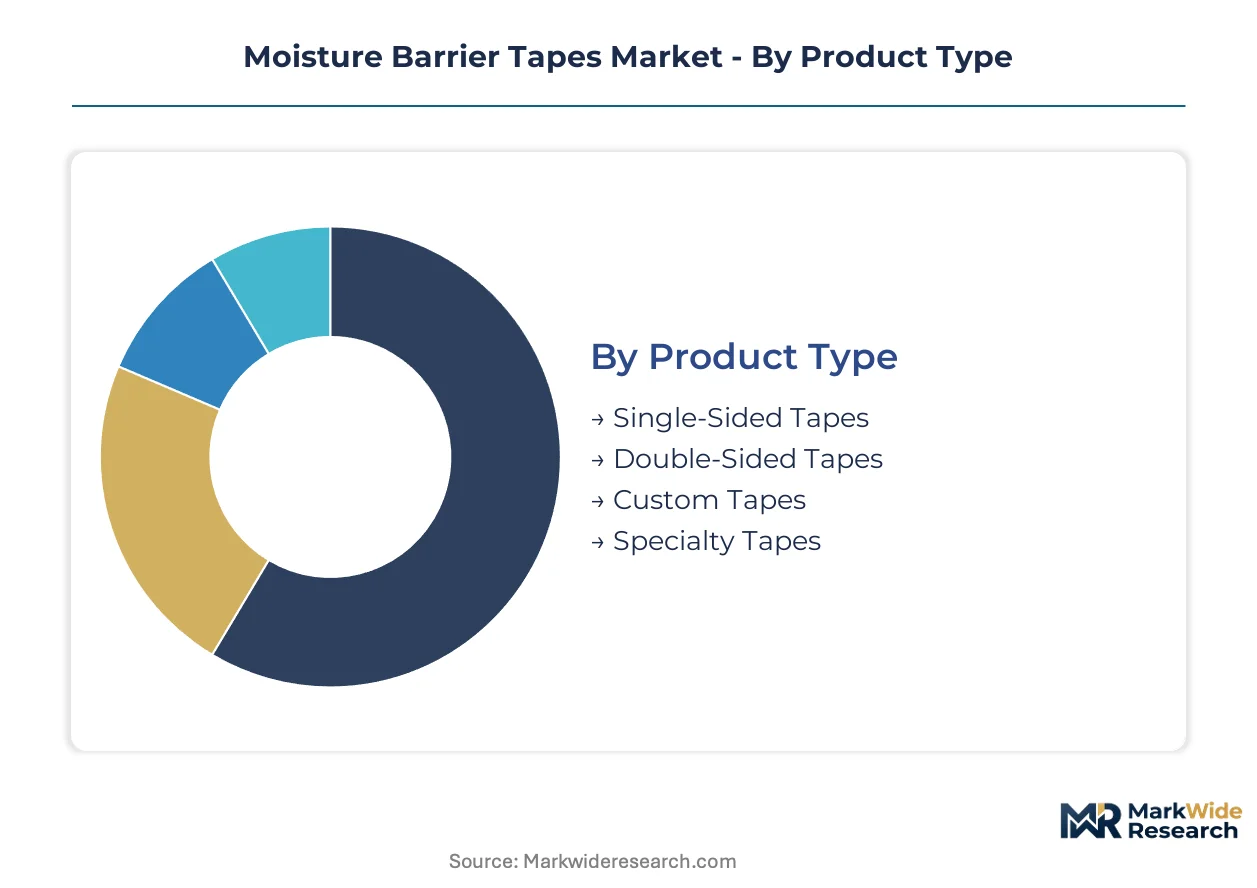
Moisture barrier tape specification fragments across adhesive chemistry, backing substrate, and installation geometry. Each segment carries distinct certification requirements and margin profiles that reshape procurement relationships across construction, electronics, and automotive value chains.
Product Type:
Supply concentration in precision coating assets favors converters with captive adhesive polymerization, locking out mid-tier competitors from electronics-grade qualification.
- Single-Sided Tapes:Pressure-sensitive adhesive laminates with one active bonding surface, typically polyethylene or PVC backings with rubber or acrylic adhesives. Residential construction contractors in the U.S. Pacific Northwest specify these for sheathing seam sealing where peel-and-stick speed reduces labor hours. ECHA's expanding SVHC list is forcing reformulation of legacy rubber adhesives, delaying CE marking renewals.
- Double-Sided Tapes:Adhesive-coated substrates on both faces with release liners, engineered for membrane-to-substrate bonding in commercial roofing and window flashing. Passive house clusters in Germany's Darmstadt-Kranichstein district specify sub-0.1 perm rated variants for multi-family envelopes. REACH phthalate restrictions in PVC backings are compressing available supplier pools.
- Custom Tapes:Width, thickness, and adhesive formulations tailored to OEM assembly specifications.
- Specialty Tapes:Cleanroom-qualified variants with outgassing controls for semiconductor and pharmaceutical packaging.
Today's leader: Single-Sided Tapes. Tomorrow's challenger: Specialty Tapes.
Material:
Petrochemical feedstock volatility spreads unevenly across polymer classes, with polyethylene converters absorbing margin compression more acutely than silicone specialists serving automotive thermal cycling applications.
- Polyethylene:Co-extruded multilayer films dominating residential construction volume due to cost efficiency in housewrap and foundation waterproofing. Below-grade applications in India's Mumbai and Delhi metro corridors are absorbing these formulations as the Bureau of Energy Efficiency's Eco-Niwas Samhita mandates expand. Integrated desiccant layers are extending service life against bituminous membrane displacement.
- Silicone:PSA platforms engineered for thermal stability across -40°C to 200°C operating windows, mandatory for electric vehicle battery enclosure IP67 sealing. Production concentrates among German and Japanese chemical suppliers, creating single-source vulnerability for automotive OEM qualification.
- PVC:Flexible backings with flame-retardant additives, facing REACH-driven substitution of chlorinated paraffin plasticizers.
- Rubber:Natural and synthetic elastomer adhesives, cost-competitive in construction but losing share to hot-melt alternatives under EPA VOC phase-down.
Polyethylene commands construction volume. Silicone captures automotive and electronics margin pools.
Application:
End-use diversification is accelerating as building envelope codes harden and electric vehicle production scales, fragmenting R&D allocation across incompatible performance certification regimes.
- Construction:Vapor retarder and air barrier applications spanning residential sheathing, commercial roofing, and below-grade waterproofing. U.S. contractors face specification bifurcation as IECC and ASHRAE 90.1 code harmonization stalls, forcing parallel certification investments.
- Automotive:Underbody corrosion protection and battery pack sealing where thermal cycling resistance determines warranty coverage. OEMs in Germany and Japan are qualifying silicone-foam hybrid tapes for thermal runaway pressure management alongside moisture ingress prevention.
- Electronics:Cleanroom assembly with outgassing specifications below 1000 ppm total mass loss.
- Packaging:FDA-regulated cold-chain logistics with integrated temperature indicators merging passive barrier and active monitoring functions.
Construction anchors current demand. Automotive battery applications are climbing the fastest.
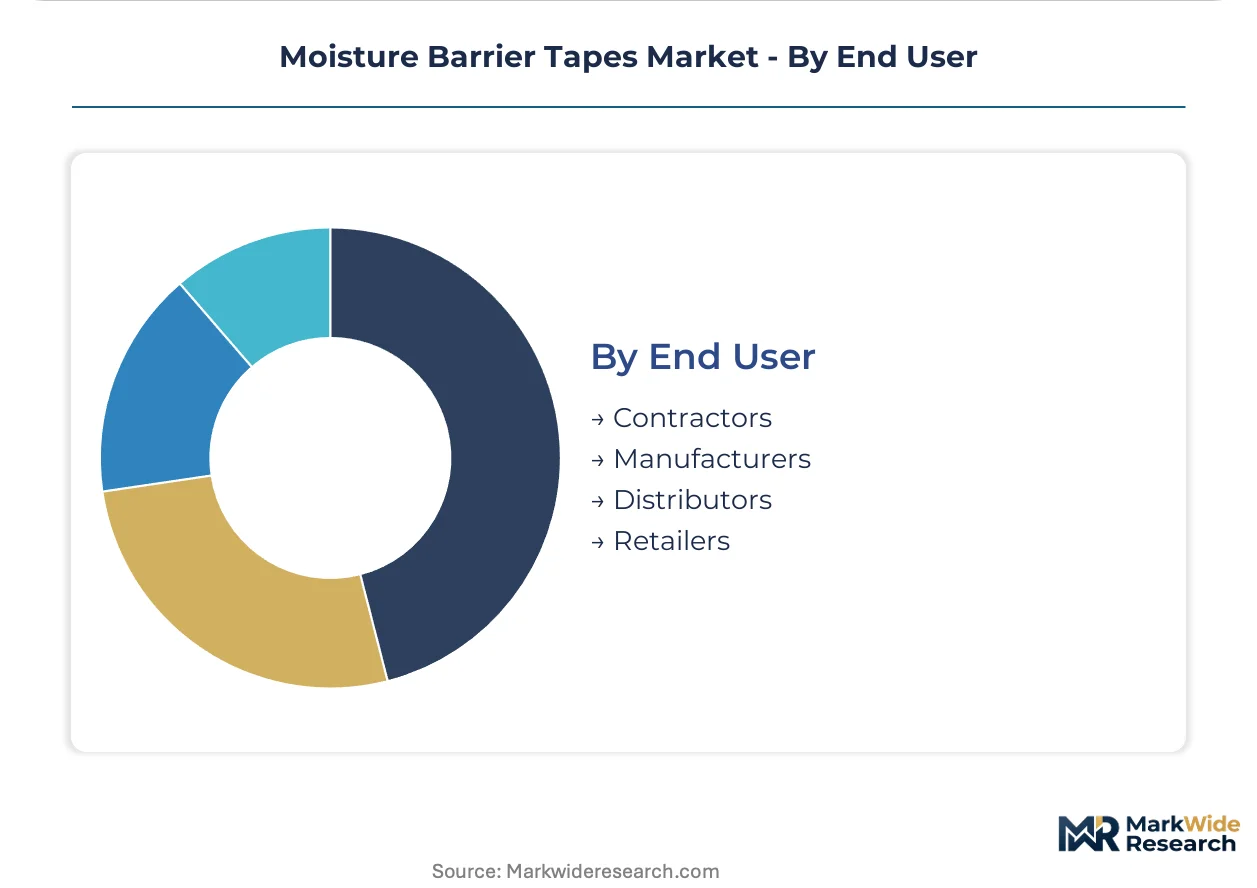
End User:
Procurement authority is shifting as consolidated general contractors unbundle envelope material specification from structural packages, creating direct relationships with specialized distributors.
- Contractors:Design-build firms and specialty envelope installers sourcing vapor retarders separately from framing to capture LEED v4.1 material ingredient reporting credits. Pacific Northwest distributors now coordinate directly with project energy modelers to optimize permeance sequencing.
- Manufacturers:OEMs in automotive and electronics with captive tape converting operations or long-term supply agreements insulating against petrochemical price swings.
- Distributors:Specialized envelope material distributors with technical sales capabilities bridging specification gaps between energy modelers and field installation.
- Retailers:Big-box and specialty building material channels serving residential repair and remodeling demand.
Contractors currently control specification. Distributors are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moisture barrier tape technology first achieved industrial scale in post-war Germany, where the Passivhaus Institute's founding in Darmstadt established the world's most demanding vapor control specifications. That regulatory lineage now shapes specification patterns across four continents.
United States
Construction contractors in the Pacific Northwest and Northeast corridors drive specification for low-VOC formulations. EPA's evolving emission standards for construction adhesives disqualify solvent-based products from federal procurement. Seattle design-build firms now source vapor retarders separately from structural packages to capture LEED v4.1 credits.
Germany
The Darmstadt-Kranichstein passive house cluster concentrates demand for sub-0.1 perm Class I vapor retarders in multi-family residential envelopes. ECHA's REACH restrictions on phthalate plasticizers force PVC backing reformulation cycles. Stuttgart-based converters accelerate bio-based plasticizer trials with epoxidized soybean oil to maintain CE marking compliance.
India
Mumbai and Delhi metro corridors absorb polyethylene-based formulations as the Bureau of Energy Efficiency's Eco-Niwas Samhita mandates expand. Below-grade waterproofing applications displace traditional bituminous sheet membranes in foundation construction. Bangalore's commercial real estate developers pioneer vapor control layer integration in speculative office builds.
Japan
Automotive OEMs in the Nagoya-Toyota industrial corridor qualify silicone-foam hybrid tapes for electric vehicle battery pack IP67 sealing. METI's industrial standards for thermal runaway pressure management create specification windows beyond moisture ingress prevention. Specialty silicone PSA production concentrates among domestic chemical suppliers, creating regional supply security.
China
Yangtze River Delta construction markets absorb cost-optimized polyethylene tapes for residential sheathing applications. GB standards for building envelope energy performance harden specification requirements in Shanghai and Suzhou metro areas. Local converters face margin compression from ethylene feedstock volatility without long-term supply agreements.
Moisture Barrier Tapes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across adhesive chemistry sophistication and certification depth. The vendor base stratifies into three tiers: integrated polymer science conglomerates with captive adhesive production, specialized tape converters with precision coating assets, and regional distributors with technical sales capabilities. Strategic moves concentrate on backward integration into polymer film extrusion and forward integration into envelope system specification support.
Within the integrated science tier, 3M and DuPont occupy positions that exemplify divergent competitive vectors—3M anchoring pressure-sensitive adhesive platform breadth, DuPont competing on fluoropolymer permeance ratings in commercial roofing. Scapa and tesa SE represent European precision coating specialists with narrow-web assets for cleanroom-qualified electronics applications. ISI Building Products and WR Meadows sit within the construction-focused converter tier where distributor relationships and code certification speed determine specification capture.
| Leading Market Players |
|---|
| 3M |
| Scapa |
| DuPont |
| Stego Industries |
| ISI Building Products |
| Elliott Group International |
| WR Meadows |
| 3F Adhesive Tapes |
| tesa SE |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between Class I vapor retarders and commodity polyethylene tapes manifests in parallel pricing architectures and supply chain configurations. Premium-tier converters with captive adhesive polymerization command pricing power through PHIUS and IECC multi-certification, while commodity producers absorb ethylene feedstock volatility without long-term offtake protection.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicone-foam hybrids for automotive battery sealing from hot-melt construction grades and basic polyethylene housewrap variants. Price differentiation hinges on permeance certification tier and captive resin supply. Cost compression in standard-grade polyethylene backings is intensifying because of ethylene spot market exposure. Residential contractors exhibit highest price sensitivity, while automotive OEMs prioritize thermal cycling warranty coverage over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese silicone PSA suppliers serving automotive and electronics qualification. Raw material supply concentrates in Germany, Japan, and the U.S. Gulf Coast for specialty adhesive monomers. Production draws from ethylene crackers, fluoropolymer resin plants, and precision narrow-web coating assets. Regulatory restriction from REACH SVHC expansions threatens PVC backing continuity. Distribution runs through specialized envelope material distributors with technical sales capabilities bridging energy modelers and field installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in silicone-foam hybrid platforms where electric vehicle battery sealing specifications outpace commodity construction tape pricing erosion. Bio-based plasticizer substitution in REACH-compliant PVC backings offers parallel cost-down pathways for European market access.
For Market Incumbents: Hedge against ethylene feedstock volatility through backward integration into multilayer co-extrusion assets or long-term resin offtake agreements with Gulf Coast crackers. Defend specification capture by accelerating PHIUS-IECC dual certification timelines before code harmonization stalls fragment R&D budgets further. Prioritize distributor technical sales team expansion in the U.S. Pacific Northwest where design-build firms unbundle envelope procurement from structural packages. For New Entrants and Emerging Players: Capture first-mover position in India's Eco-Niwas Samhita compliance market before incumbent converters establish local coating capacity in Mumbai and Delhi corridors. Target cold-chain packaging convergence where FDA-regulated pharmaceutical distribution absorbs moisture barrier tapes with integrated temperature indicators. Lead with direct technical sales engagement of project energy modelers rather than traditional distributor channel penetration. For Investors and Strategic Acquirers: Consolidation pressure builds where narrow-web precision coating assets for electronics-grade cleanroom tapes exceed mid-tier converter balance sheet capacity. Five-to-ten-year viability favors integrated polymer science conglomerates with captive adhesive production over pure-play converters exposed to petrochemical margin compression. Target acquisition archetype: European precision coating specialists with PHIUS certification and automotive silicone-foam hybrid qualification. Watch for inflection when ECHA expands SVHC restrictions to force chlorinated paraffin substitution completion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Extrusion | Captive multilayer co-extrusion capacity insulates margin from ethylene spot volatility and accelerates PHIUS certification cycles. |
| Dual Certification Investment (PHIUS-IECC) | Simultaneous passive house and energy code compliance captures specification pull-through across Central European and U.S. Northeast corridors. |
| Bio-Based Plasticizer Substitution | Epoxidized soybean oil formulations in PVC backings maintain CE marking compliance ahead of REACH chlorinated paraffin restrictions. |
| Distributor Technical Sales Expansion | Direct coordination with project energy modelers optimizes permeance sequencing and captures LEED v4.1 material ingredient reporting credits. |
| Silicone-Foam Hybrid Platform Development | IP67 battery enclosure sealing with thermal runaway pressure management opens automotive OEM qualification beyond moisture ingress prevention. |
Research Methodology
Direct dialogue with plant managers at adhesive coating facilities, procurement leads at construction OEMs, technical R&D directors at polymer science conglomerates, and distributor sales heads specializing in envelope materials grounded this analysis. Secondary validation drew from EPA VOC emission filings, ECHA REACH restriction updates, Bureau of Energy Efficiency Eco-Niwas Samhita mandates, and customs trade data on polyethylene and silicone resin flows. Bottom-up segment sizing triangulated against top-down construction spending and automotive production forecasts.
Bottom-up modeling aggregated adhesive chemistry, backing substrate, and application geometry segments across the analysis window. Top-down cross-checks referenced building envelope energy code adoption curves, electric vehicle battery pack production scaling, and cold-chain pharmaceutical distribution growth. CAGRs derived from segment-level volume and value buildups normalized against petrochemical feedstock price indices and certification timeline assumptions.
Feedstock price volatility, regulatory restriction acceleration, and code harmonization failure are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on ethylene cost trajectories and REACH SVHC expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Building and Construction Tapes Market
Tapes
Acoustic Tape Market
Tapes
Strapping Tapes Market
Tapes
High Bond Tape Market
Tapes
India Masking Tapes Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Packaging Tape Printing Market
Tapes
Thermoplastic Tape Market
Tapes
Differential Tapes Market
Tapes
Global Electrical Tapes Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Breathable Tape Market
Tapes
Coding Foils and Tapes Market
Tapes
Tear Tape Dispenser Market
Tapes
Replica Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market