
 Shipping Tapes Market | 2026-2036
Shipping Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Tapes Market Analytics
ISO 9001 quality management certification is unwinding the competitive landscape by filtering out suppliers lacking documented process controls. 3M leverages its materials science heritage to sustain premium positioning in specialty acrylic formulations. Intertape Polymer Group anchors North American capacity through integrated film extrusion and adhesive coating operations. Tesa SE competes on precision-engineered tapes for automated carton sealing systems in European distribution hubs.
Shipping tapes are pressure-sensitive adhesive strips, typically constructed from biaxially oriented polypropylene film coated with synthetic rubber or hot-melt resin, designed to create tamper-evident seals on corrugated fiberboard containers during transit and storage. Packaging tape dominates volume flows through e-commerce fulfillment networks, while double-sided tape captures higher margin pools in pallet stabilization and unitizing applications. Polypropylene substrates lead material demand due to tensile strength and cost efficiency, though paper-based alternatives are gaining share in recyclable packaging streams driven by retailer sustainability mandates.
FDA regulations govern indirect food contact adhesives in tape formulations used for packaged goods distribution, while EPA guidelines restrict solvent-based coating emissions from manufacturing facilities. The EU REACH framework governs substance restrictions in adhesive chemistries, forcing reformulation investments across imported and domestic supply chains. Stakeholders must monitor evolving extended producer responsibility schemes and decide between regional formulation adaptation or global standardization strategies.
Market Dynamics
E-commerce fulfillment automation is compressing tape specification cycles as warehouse operators demand higher-speed compatibility with robotic case sealers and vision-guided packaging lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclable packaging materials are accelerating paper-based tape adoption across German automotive parts distribution networks.
- Automated carton sealing systems:European distribution hubs are retrofitting packaging lines with precision-engineered tapes that reduce jam rates and maintenance downtime.
- Hot-melt adhesive formulations:Synthetic rubber chemistries optimized for high-temperature performance are capturing share in pallet stabilization applications.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin costs swing with crude oil benchmarks, compressing margins for film extrusion operations.
- Adhesive chemistry restrictions:EU REACH substance limitations force costly reformulation cycles for imported tape products.
- Water-activated paper tape:Lower tensile strength versus polypropylene alternatives limits substitution in heavy-load corrugated sealing.
Strategic Opportunities
- Recyclable packaging streams:Retailer sustainability mandates in France and the Netherlands are opening specification windows for fiber-based tape substrates.
- Extended producer responsibility schemes:German packaging compliance fees create incentive structures for tape suppliers offering closed-loop material recovery.
- Digital printing integration:Variable-data barcode printing on tape surfaces converges with track-and-trace requirements in pharmaceutical distribution.
Industry Challenges
- ISO 9001 certification timelines:Documentation gaps delay supplier qualification for automated packaging line integrations.
- Legacy solvent-based coating assets:EPA emission restrictions require capital-intensive conversion to hot-melt or waterborne adhesive systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Tapes Market |
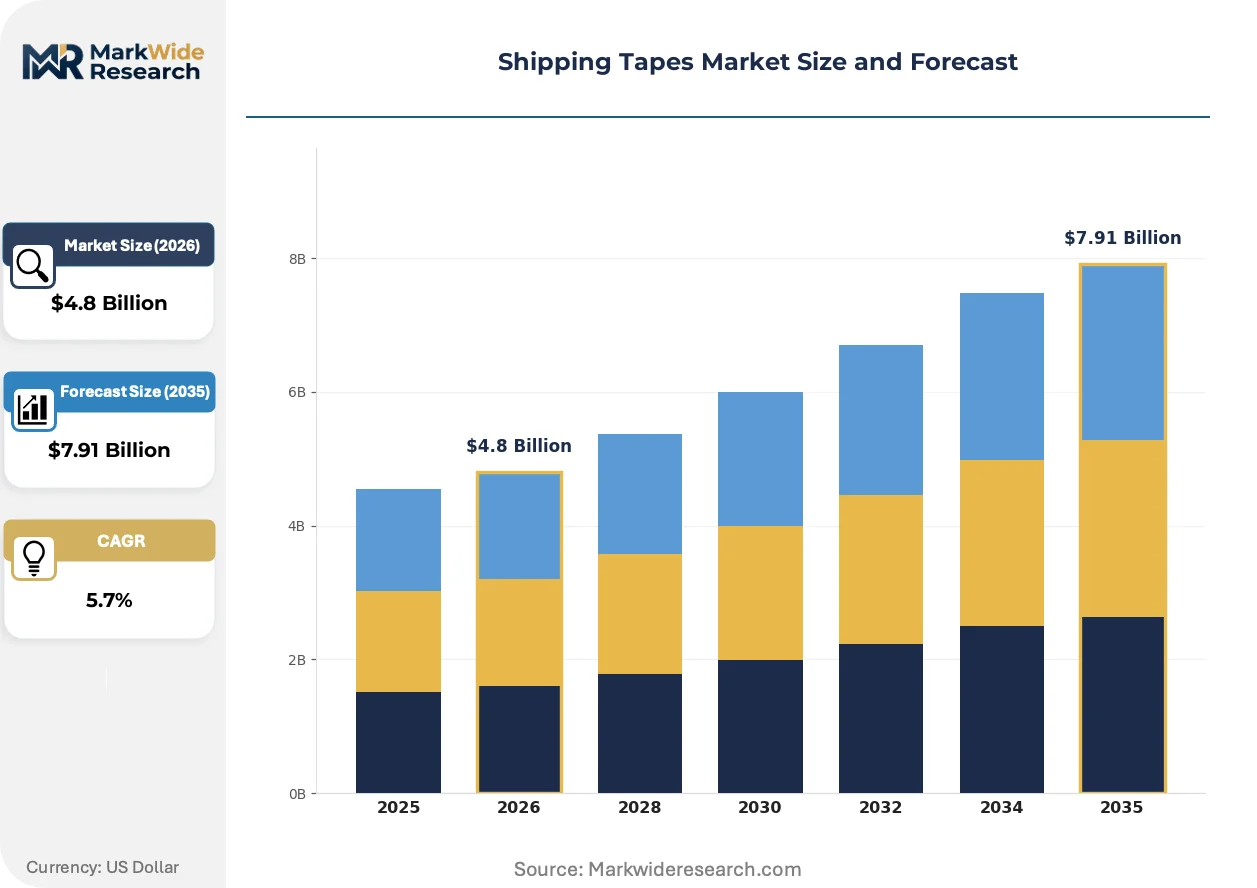
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaging Tape, Duct Tape, Masking Tape, Double-Sided Tape Material: Polypropylene, Paper, Vinyl, Cotton Application: Retail Packaging, Logistics, Moving, Manufacturing Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | 3M, Intertape Polymer Group, Tesa SE, Shurtape Technologies, Avery Dennison, Berry Global, Nitto Denko, Scapa Group, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Tapes Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are rewriting tape formulation roadmaps. Suppliers must balance performance specifications against compliance deadlines while serving divergent regional packaging standards.
Acrylic adhesive layers are miniaturizing while maintaining shear resistance through nanostructured polymer architectures. Pharmaceutical cold-chain distributors in Switzerland and Belgium are specifying these ultra-thin formulations for temperature-sensitive shipments. The technology is miniaturizing tape roll dimensions, enabling longer footage per spindle and reducing changeover frequency in high-throughput fulfillment centers.
REACH substance restrictions are forcing systematic elimination of certain phthalate plasticizers from synthetic rubber adhesives. German tape manufacturers face reformulation investments or supply chain exclusion from EU single-market distribution. Automotive parts suppliers in Stuttgart and Wolfsburg are accelerating supplier audits to verify compliance ahead of enforcement phase-ins.
Consolidated procurement contracts are displacing fragmented spot purchasing across European third-party logistics providers. Amazon-scale fulfillment operators in Poland and the Czech Republic are mandating multi-year supply agreements with volume-tiered pricing. The shift concentrates specification authority with packaging engineers rather than warehouse operations managers.
Shipping Tapes Market Segmentation
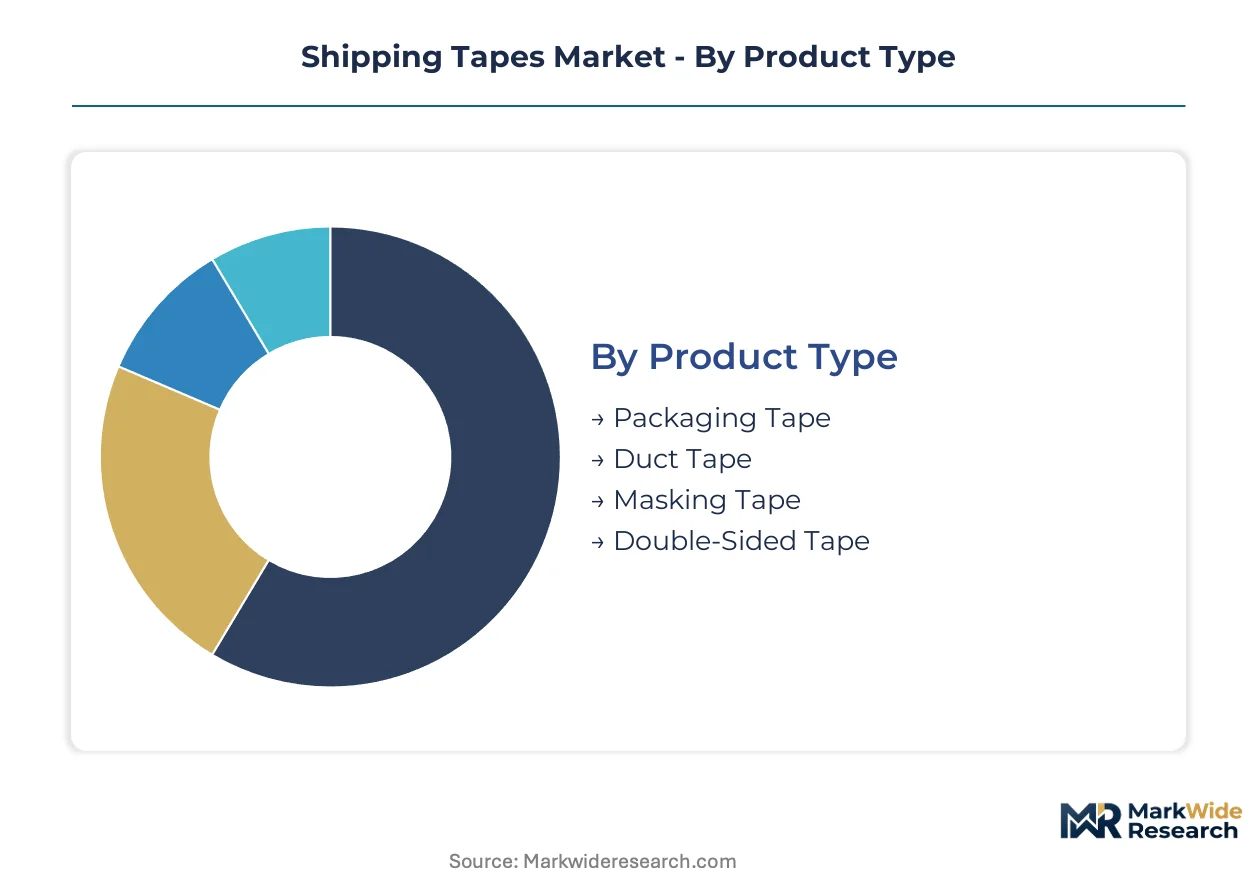
Shipping tape segmentation reveals divergent margin structures across substrate chemistries and fulfillment channel economics. Material choices determine compliance pathways under EU REACH and FDA indirect food contact rules, while distribution channel selection locks in customer lifetime value profiles.
Product Type:
Margin pools concentrate in specialty adhesive formulations serving automated packaging lines and temperature-controlled logistics.
- Packaging Tape:Biaxially oriented polypropylene film coated with synthetic rubber or hot-melt resin dominates volume flows through e-commerce fulfillment networks. Amazon-scale operators in Poland and the Czech Republic are mandating multi-year supply agreements with precision-engineered tapes that reduce jam rates in robotic case sealers.
- Double-Sided Tape:Acrylic adhesive layers miniaturized through nanostructured polymer architectures capture higher margin pools in pallet stabilization and unitizing applications. Pharmaceutical cold-chain distributors in Switzerland and Belgium specify these ultra-thin formulations for temperature-sensitive shipments.
- Duct Tape:Reinforced polyethylene backing with aggressive natural rubber adhesive serves heavy-duty sealing in industrial maintenance and field repair scenarios.
- Masking Tape:Crepe paper substrate with solvent-based or waterborne adhesive coatings protects surfaces during automotive painting and electronics finishing operations.
Packaging tape holds installed capacity. Double-sided tape is rotating up the share rankings.
Material:
Cost tier differentiation separates commodity resin formulations from certified substrates commanding sustainability premiums.
- Polypropylene:Tensile strength and cost efficiency sustain dominance in high-throughput corrugated sealing, though petrochemical feedstock volatility compresses margins for film extrusion operations tied to crude oil benchmarks.
- Paper:Water-activated kraft and gummed tape formats gain specification windows in recyclable packaging streams driven by retailer sustainability mandates in France and the Netherlands, despite lower tensile strength versus synthetic alternatives.
- Vinyl:PVC backing delivers conformability and moisture resistance for irregular surface sealing in outdoor and cold-chain applications.
- Cotton:Woven cloth substrate with natural rubber adhesive serves heritage bookbinding and archival preservation niches requiring reversible adhesion.
Polypropylene maintains volume leadership. Paper is expanding most quickly in premium retail channels.
Application:
Customer type determines specification authority and contract structure across fragmented versus consolidated procurement patterns.
- Logistics:Third-party logistics providers across Europe are consolidating procurement contracts, displacing spot purchasing with multi-year agreements that concentrate specification authority with packaging engineers rather than warehouse operations managers.
- Retail Packaging:Brand owners in German automotive parts distribution networks are accelerating supplier audits to verify REACH compliance ahead of enforcement phase-ins for phthalate-free adhesive formulations.
- Moving:Consumer-grade carton sealing drives seasonal demand spikes through home improvement and rental truck channels.
- Manufacturing:In-process unitizing and temporary holding applications require tape compatibility with automated material handling systems.
Logistics commands contract value concentration. Retail packaging is climbing the fastest in compliance-driven specification.
Distribution Channel:
Supply concentration varies sharply between asset-light digital platforms and relationship-dependent wholesale networks.
- Wholesale Distributors:Integrated film extrusion and adhesive coating operations anchor North American capacity through regional distribution hubs serving mid-market converters and packaging suppliers.
- Online Retail:Digital platforms capture small-lot and emergency replenishment demand from decentralized warehouse operations, though price transparency compresses margin realization.
- Direct Sales:Account-managed relationships with Amazon-scale fulfillment operators and automotive tier-one suppliers lock in volume commitments and technical collaboration.
- Specialty Stores:Localized inventory positions serve immediate-need segments in moving services and light industrial maintenance.
Wholesale distributors retain infrastructure density. Direct sales is gaining share fastest in automated packaging line integrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive parts distributors and e-commerce fulfillment operators concentrate tape procurement authority in Germany's industrial corridor, while regulatory chemistry restrictions in the EU single market reshape supplier qualification requirements across adjacent economies.
Germany
Automotive tier-one suppliers in Stuttgart and Wolfsburg drive specification for high-performance sealing solutions in parts distribution networks. The EU REACH framework mandates systematic elimination of phthalate plasticizers from synthetic rubber adhesives, forcing reformulation investments. Bavaria's packaging engineering clusters verify compliance ahead of enforcement phase-ins.
United States
Amazon-scale fulfillment operators and third-party logistics providers consolidate procurement contracts through multi-year supply agreements. FDA regulations govern indirect food contact adhesives in tape formulations for packaged goods distribution. Midwestern automated packaging corridors in Illinois and Ohio specify precision-engineered tapes for robotic case sealers.
Poland
E-commerce fulfillment centers retrofit packaging lines with higher-speed tape compatibility for vision-guided automation. EPA guidelines restrict solvent-based coating emissions from manufacturing facilities, requiring capital-intensive conversion to hot-melt systems. Warsaw and Krakow distribution hubs concentrate specification authority with packaging engineers rather than warehouse operations managers.
France
Retailer sustainability mandates in Paris and Lyon open specification windows for fiber-based tape substrates in recyclable packaging streams. The EU Packaging and Packaging Waste Regulation tightens material compliance requirements for adhesive products. Automotive distribution networks in the Île-de-France region accelerate supplier audits for REACH-compliant formulations.
Switzerland
Pharmaceutical cold-chain distributors in Basel and Geneva specify ultra-thin acrylic formulations for temperature-sensitive shipments. Swissmedic oversees quality standards for medical device packaging materials. Precision-engineered tape demand concentrates in pharmaceutical distribution corridors serving European export markets.
Shipping Tapes Market Competitive Landscape
Player mix skews toward integrated materials specialists with captive film extrusion and adhesive coating operations. The supplier base concentrates around three capability tiers: diversified industrial conglomerates with materials science heritage, mid-cap polymer specialists with regional manufacturing footprints, and niche precision-engineered tape providers serving automated packaging integrations. Consolidation pressures favor backward integration into resin supply and strategic partnerships with e-commerce fulfillment operators.
Among diversified industrial conglomerates, 3M leverages its materials science heritage to sustain premium positioning in specialty acrylic formulations. Intertape Polymer Group anchors North American capacity through integrated operations. Tesa SE occupies a position within the precision-engineered tier, competing on specifications for automated carton sealing systems in European distribution hubs. These three represent the dominant archetypes: science-driven premium positioning, integrated regional scale, and precision automation specialization.
| Leading Market Players |
|---|
| 3M |
| Intertape Polymer Group |
| Tesa SE |
| Shurtape Technologies |
| Avery Dennison |
| Berry Global |
| Nitto Denko |
| Scapa Group |
| Henkel |
| Others |
Value Network & Pricing Analysis
ISO 9001 certification gates supplier qualification and price differentiation simultaneously, filtering out undocumented process controls while creating tiered access to automated packaging line integrations in Germany and Poland.
Pricing Analysis
Cost-plus contracts with polypropylene resin indexation dominate procurement between film extrusion operations and e-commerce fulfillment operators. Three-tier pricing structure across precision-engineered, standard commodity, and economy grades reflects certification tier and volume scale. Pricing pressure stems from petrochemical feedstock volatility tied to crude oil benchmarks. Amazon-scale buyers exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while spot purchasers in decentralized warehouse operations drive hardest bargain.
Supply Chain Analysis
Just-in-time inventory strategies prevail among European automotive parts distributors, while strategic stockpiling characterizes North American integrated film extrusion operations buffering against resin price swings. Supply concentrates in Germany, the United States, and China for biaxially oriented polypropylene film and synthetic rubber adhesive chemistries. Raw material dependencies rest on propylene monomer, natural rubber derivatives, and acrylic polymer feedstocks. Single-source vulnerability runs through specialized hot-melt adhesive formulators serving pharmaceutical cold-chain specifications. Distribution runs through wholesale distributors anchoring regional capacity, with direct sales gaining share in automated packaging line integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated procurement contracts across European third-party logistics providers, displacing fragmented spot purchasing and shifting specification authority toward packaging engineers.
For Market Incumbents: Consolidate backward integration into captive film extrusion assets to defend margin position against petrochemical feedstock volatility. Lock in multi-year supply agreements with Amazon-scale fulfillment operators in Poland and the Czech Republic before REACH enforcement phase-ins tighten supplier qualification. Priority investment targets ISO 9001 certification acceleration for mid-tier competitors facing documentation gaps. For New Entrants and Emerging Players: Differentiate on REACH-compliant paper-based tape formulations targeting retailer sustainability mandates in France and the Netherlands. White-space opportunity concentrates in recyclable packaging streams where fiber-based substrates gain specification windows against polypropylene dominance. Go-to-market angle: closed-loop material recovery partnerships with German packaging compliance fee structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hot-melt adhesive coating conversions required by EPA emission restrictions. Long-term viability favors integrated operations with captive resin supply and automated packaging line technical collaboration capabilities. Acquisition target archetype: mid-cap polymer specialists with regional manufacturing footprints and pending ISO 9001 certification. Signal to watch: enforcement phase-in timelines for phthalate-free adhesive formulations under EU REACH.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polypropylene supply insulates margin from crude oil benchmark volatility in German automotive corridors. |
| REACH Compliance Reformulation | Phthalate-free adhesive chemistry investment gates continued EU single-market access for Stuttgart and Wolfsburg suppliers. |
| Automated Packaging Line Certification | ISO 9001 documentation accelerates supplier qualification for robotic case sealer integrations in Polish fulfillment hubs. |
| Closed-Loop Material Recovery Partnership | German extended producer responsibility fee structures create incentive alignment for fiber-based tape substrate adoption. |
| Precision-Engineered Tape R&D Collaboration | Technical partnerships with Amazon-scale operators reduce jam rates and maintenance downtime in vision-guided packaging lines. |
Research Methodology
A spread of perspectives from packaging engineers at automated fulfillment operators, procurement leads at third-party logistics providers, adhesive R&D directors, plant managers at film extrusion facilities, and regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC filings of integrated polymer specialists, EU REACH substance restriction databases, and EPA emission compliance records. Bottom-up volume modeling triangulated against top-down market sizing across substrate chemistries and fulfillment channel economics.
Segmentation dimensions modeled include product type, material substrate, application end-use, and distribution channel across the analysis window. Growth trajectories derived from installed capacity expansion in automated packaging corridors, e-commerce fulfillment network buildouts, and regulatory compliance investment cycles. Industry-specific forecast inputs incorporated REACH enforcement phase-in schedules and retailer sustainability mandate adoption curves in France and the Netherlands.
Forecasts assume regulatory continuity in EU REACH substance restrictions and EPA emission guidelines; material policy shifts would require re-modeling. Specific risk factors include accelerated phthalate elimination timelines, solvent-based coating asset stranded costs, and petrochemical price spike duration. Revision becomes warranted when automated packaging line retrofit penetration crosses thresholds that compress specification cycles beyond current modeling assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
Filmic Tapes Market
Tapes
Seam Tapes Market
Tapes
Spacer Tapes Market
Tapes
Adhesive Transfer Tape Market
Tapes
Carton Sealing Tape Market
Tapes
Carry Handle Tape Market
Tapes
Unsupported Single Coated Tape Market
Tapes
Pucker Free Tapes Market
Tapes
Paper Packaging Tapes Market
Tapes
Gaffers Tape Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Tape Banding Machine Market
Tapes
Cloth Self-Adhesive Tapes Market