
 Thermal Transfer Tapes Market | 2026-2036
Thermal Transfer Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Transfer Tapes Market Analytics
Distributor networks for specialty industrial adhesives is narrowing as direct procurement portals gain share among large electronics OEMs. 3M leverages its materials science portfolio to sustain premium positioning in polyimide thermal management solutions. Nitto Denko anchors Asian supply chains through localized compounding facilities in Japan and Taiwan. Avery Dennison competes on specification breadth, offering calibrated thermal impedance grades for aerospace qualification.
Thermal transfer tapes are pressure-sensitive adhesive constructions engineered to conduct heat away from electronic components while maintaining dielectric isolation, typically incorporating aluminum, ceramic, or carbon-filled layers with thermal conductivities ranging from 0.5 to 5 W/m·K. Single-sided configurations dominate volume shipments for semiconductor heat-spreader attachment, though double-sided variants capture disproportionate margin pools in electric vehicle battery module bonding where structural adhesion and thermal pathing converge. Acrylic formulations lead material selection for cost-sensitive consumer electronics, while silicone chemistry extends operating temperature ranges for automotive under-hood and power electronics applications.
REACH compliance in Europe restricts certain halogenated flame retardants used in legacy PVC backings, redirecting formulation investment toward halogen-free polyimide substrates. The EPA's New Chemicals Review Program under TSCA scrutinizes novel silicone crosslinkers entering US commerce, extending qualification timelines for next-generation thermal interface materials. FDA biocompatibility requirements for wearable medical devices constrain adhesive selection in diagnostic and patient-monitoring applications where skin contact occurs. Stakeholders must weigh regional regulatory divergence against the scale economies of unified product platforms.
Market Dynamics
The EU F-Gas Regulation is forcing solvent-free adhesive chemistry substitution across European electronics supply chains, compressing qualification timelines and favoring compounders with in-house formulation capabilities.
Growth Catalysts
- Electric vehicle battery module bonding:Automotive OEMs in Germany and South Korea are specifying double-sided thermal tapes for structural adhesion combined with thermal pathing in pack assembly.
- REACH halogen-free mandates:ECHA restrictions on halogenated flame retardants redirect investment toward polyimide substrates with alternative flame suppression chemistry.
- Semiconductor heat-spreader attachment:Taiwan and South Korea fabrication corridors are standardizing single-sided configurations for die-level thermal management.
Market Restraints
- Silicone crosslinker qualification delays:EPA's TSCA New Chemicals Review Program extends approval timelines for novel silicone thermal interface materials entering US commerce.
- Polyimide film supply concentration:Specialty polyimide substrate production concentrates in Japanese and Korean chemical conglomerates, creating input bottleneck risk.
- Acrylic thermal conductivity ceiling:Acrylic formulations face inherent thermal conductivity limitations below 1.5 W/m·K, constraining deployment in high-power density applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and component assembly create demand for localized thermal tape qualification and distribution.
- Wearable medical diagnostics:FDA biocompatibility requirements for skin-contact devices open specification windows for silicone-based thermal management with biocompatibility certification.
- Solvent-free adhesive convergence:UV-curable and hot-melt thermal adhesive technologies are converging with automated tape lamination equipment for clean-room electronics assembly.
Industry Challenges
- Multi-regulatory qualification burden:Manufacturers must simultaneously satisfy EPA TSCA, REACH, and FDA requirements for unified product platforms, fragmenting R&D resources.
- Thermal impedance calibration complexity:Aerospace qualification protocols at Avery Dennison's specification breadth require extensive test matrix validation, extending customer onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Transfer Tapes Market |
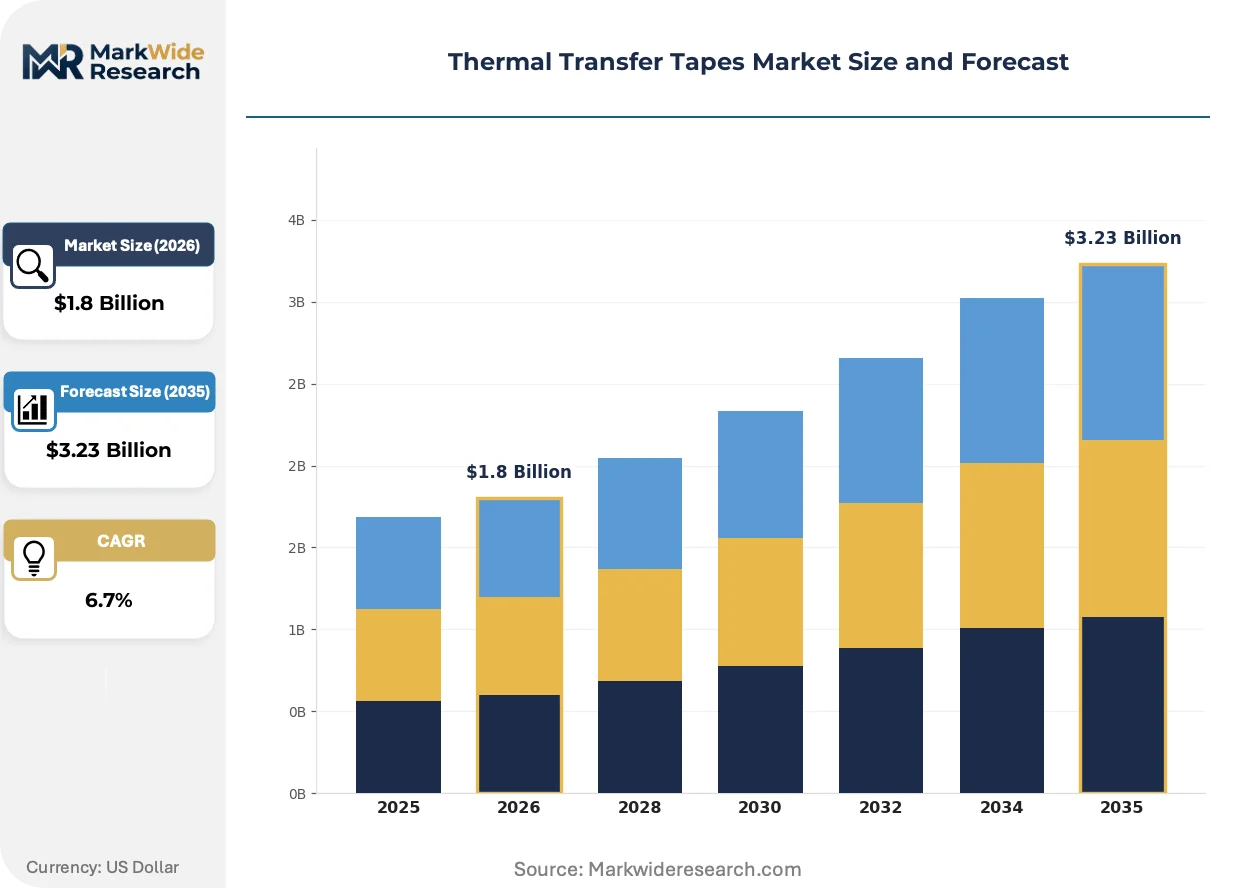
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Conductive, Non-Conductive Material: Polyimide, Acrylic, Silicone, PVC Application: Electronics, Automotive, Aerospace, Medical End User: Manufacturers, Contractors, OEMs, Distributors |
| Companies Covered | 3M, Nitto Denko, Avery Dennison, tesa SE, Henkel, Scapa, LINTEC Corporation, Intertape Polymer Group, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Transfer Tapes Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are jointly reshaping thermal tape construction, with formulation priorities shifting from performance maximization toward compliance-integrated design.
Ceramic-filled silicone thermal interface materials are migrating from legacy boron nitride loadings toward aluminum oxide and aluminum nitride hybrid fillers. Automotive power electronics manufacturers in Japan and Germany are accelerating this transition to meet combined thermal conductivity and dielectric strength targets. The shift is compressing margins for compounders without captive ceramic powder processing capabilities.
REACH authorization procedures for persistent organic pollutants now encompass legacy chlorinated flame retardants used in PVC-backed thermal tapes. European electronics OEMs are responding by disqualifying PVC constructions from new product introductions. This regulatory pressure most acutely affects consumer electronics supply chains serving EU markets, where halogen-free polyimide specifications are becoming default requirements.
Direct procurement portals are displacing traditional specialty adhesive distributor networks among large electronics OEMs. Samsung and TSMC procurement organizations now specify thermal interface materials through vendor-managed inventory platforms, extracting price transparency and compressing distributor margins. This channel transformation is most advanced in South Korea's semiconductor fabrication corridor, where localized compounding facilities enable just-in-time delivery models.
Thermal Transfer Tapes Market Segmentation
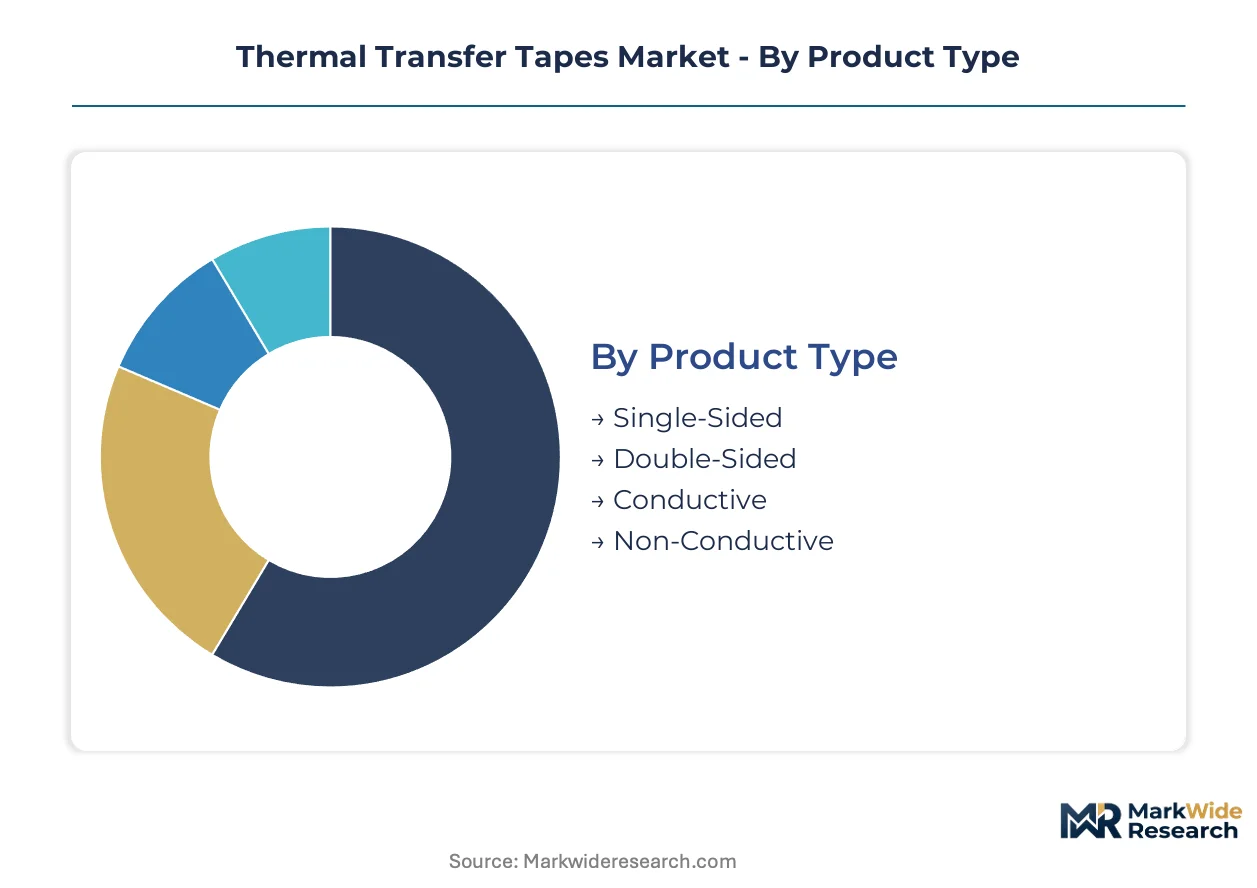
Thermal transfer tape specifications diverge sharply across end-use contexts, with semiconductor fabs demanding dielectric isolation ratings incompatible with automotive bonding requirements. Procurement patterns in this market tie directly to technical qualification cycles that span 18-36 months, making segment-specific application engineering a decisive commercial capability.
Product Type:
After-sales service intensity varies dramatically across product configurations, with double-sided constructions requiring field-level thermal impedance validation that single-sided variants rarely need.
- Single-Sided:Aluminum or ceramic-filled constructions conduct heat from semiconductor dies to spreader plates while maintaining electrical isolation. Taiwan and South Korea fabrication corridors standardize these configurations for die-level thermal management in advanced node production. By volume, single-sided leads. By growth pace, double-sided is ahead.
- Double-Sided:Structural adhesion converges with thermal pathing in electric vehicle battery module bonding, where German and South Korean OEMs specify combined load-bearing and heat-dissipation performance. These variants command premium positioning due to qualification complexity and failure-mode criticality in pack assembly.
- Conductive:Carbon-filled or metal-laden adhesives provide electrical continuity alongside thermal transfer for EMI shielding applications in telecommunications infrastructure.
- Non-Conductive:Ceramic-loaded dielectric constructions isolate high-voltage power electronics in railway traction and renewable energy inverters.
Double-sided configurations carry the heaviest technical support burden, with automotive OEMs demanding on-site lamination process optimization.
Material:
Cost tier stratification separates commodity acrylic formulations from specialty silicone and polyimide substrates that serve temperature-extreme environments.
- Polyimide:Halogen-free substrates with alternative flame suppression chemistry satisfy REACH mandates while sustaining 200°C+ continuous operating temperatures. East Asian electronics manufacturers expand procurement for battery pack assembly applications requiring thin-film dielectric strength.
- Silicone:Crosslinked elastomer backbones extend thermal cycling resilience for automotive under-hood and power electronics applications, though EPA TSCA review timelines delay novel formulation introductions. Silicone chemistry gains share fastest in wearable medical diagnostics where FDA biocompatibility certification opens specification windows.
- Acrylic:Cost-optimized pressure-sensitive adhesives dominate consumer electronics volume, constrained by inherent thermal conductivity ceilings below 1.5 W/m·K that exclude high-power density deployment.
- PVC:Legacy backing constructions face disqualification from EU market introductions as ECHA authorization procedures restrict chlorinated flame retardants.
Acrylic formulations dominate unit shipments. Polyimide substrates command the steepest expansion trajectory.
Application:
Customer type segmentation reveals divergent procurement behaviors, with aerospace qualification protocols demanding extensive test matrix validation that consumer electronics volume buyers bypass.
- Electronics:Semiconductor heat-spreader attachment and PCB-level thermal management drive specification diversity across single-sided dielectric and conductive grounding variants. Direct procurement portals displace distributor networks among large OEMs in this segment.
- Automotive:Electric vehicle battery module bonding combines structural adhesion with thermal pathing, with German OEMs and South Korean manufacturers advancing double-sided specification adoption.
- Aerospace:Calibrated thermal impedance grades with extensive qualification documentation serve satellite and avionics applications where outgassing and vibration resistance are mandatory.
- Medical:Wearable diagnostic devices with skin-contact requirements constrain adhesive selection to silicone-based constructions with biocompatibility certification.
Electronics applications generate the highest shipment volumes. Automotive applications climb the fastest.
End User:
Supply concentration patterns favor compounders with localized production facilities serving just-in-time delivery models for high-volume purchasers.
- Manufacturers:Electronics component fabricators and battery pack assemblers specify thermal interface materials through vendor-managed inventory platforms, extracting price transparency.
- Contractors:Installation and integration specialists in telecommunications and industrial automation procure calibrated grades for field-level thermal management retrofits.
- OEMs:Original equipment manufacturers in automotive and aerospace verticals drive qualification-heavy specification development with 24-36 month design-in cycles.
- Distributors:Traditional specialty adhesive distributor networks face margin compression as direct procurement channels gain share among large electronics purchasers.
OEMs anchor premium segment value capture. Manufacturers represent the fastest-expanding procurement channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for semiconductor manufacturing is redirecting procurement patterns across South and East Asia, while EU F-Gas Regulation compliance deadlines compress European qualification timelines for solvent-free adhesive platforms.
South Korea
Semiconductor fabrication corridors in Gyeonggi Province and the Seoul Capital Area are standardizing single-sided thermal tape specifications for advanced node production. The MFDS maintains biocompatibility oversight for wearable medical device applications. Samsung Electronics and SK Hynix procurement organizations operate vendor-managed inventory platforms that extract price transparency from compounders.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify double-sided thermal tapes for electric vehicle battery module bonding requiring combined structural adhesion and thermal pathing. The KBA enforces vehicle safety standards that cascade into component-level qualification protocols. Stuttgart's automotive engineering cluster anchors specification development with 24-36 month design-in cycles.
United States
EPA's TSCA New Chemicals Review Program extends approval timelines for novel silicone crosslinkers entering domestic commerce. The FDA constrains adhesive selection in wearable diagnostic applications through biocompatibility requirements for skin-contact devices. Texas and Arizona semiconductor fabrication investments are creating localized demand for thermal interface material qualification.
Japan
METI industrial policy supports captive ceramic powder processing capabilities among specialty chemical conglomerates. Polyimide film production concentrates in the Chubu and Kanto regions, creating input supply leverage for downstream tape compounders. Nagoya-area automotive power electronics manufacturers are accelerating transitions from boron nitride toward aluminum oxide and aluminum nitride hybrid fillers.
Taiwan
TSMC procurement specifications drive thermal impedance calibration standards for die-level heat-spreader attachment across the Hsinchu Science Park ecosystem. The island's concentrated semiconductor supply chain enables just-in-time delivery models for polyimide-based thermal management materials. Localized compounding facilities serve direct procurement portals displacing traditional distributor networks.
Thermal Transfer Tapes Market Competitive Landscape
On the supply side, the industry is consolidating around materials science specialists with captive formulation capabilities and regional compounding infrastructure. Japanese and Korean chemical conglomerates anchor upstream polyimide substrate supply, while European and North American players compete on specification breadth and qualification documentation. Three archetypes dominate: diversified materials science portfolios, Asian supply chain integrators with localized production, and specification-heavy aerospace qualification specialists. Competitive moves center on backward integration into ceramic filler processing and geographic expansion through vendor-managed inventory platforms.
Among diversified materials science portfolios, 3M exemplifies premium positioning through integrated adhesive and substrate capabilities. Nitto Denko occupies a position as an Asian supply chain anchor with localized compounding facilities. Avery Dennison represents the specification-breadth archetype, serving qualification-intensive aerospace and medical applications where calibrated thermal impedance grades and extensive test matrix documentation command positioning.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko |
| Avery Dennison |
| tesa SE |
| Henkel |
| Scapa |
| LINTEC Corporation |
| Intertape Polymer Group |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Kaohsiung semiconductor freight corridor carries polyimide substrate rolls at rates that compound downstream pricing power for Japanese chemical conglomerates. This logistics artery connects concentrated polyimide film production in Chubu and Kanto to Taiwan's fabrication ecosystem, amplifying cost pass-through to battery pack assemblers in South Korea and Germany while compressing margin pools for distributors without direct mill relationships.
Pricing Analysis
Certification level creates the primary spread between aerospace-grade thermal impedance calibration and commodity consumer electronics specifications. Three-tier pricing structure across premium, standard, and economy levels reflects FDA biocompatibility, REACH halogen-free compliance, and basic acrylic formulations respectively. Cost compression in standard-tier acrylic tapes intensifies because direct procurement portals extract price transparency from compounders. Consumer electronics volume buyers exhibit highest price sensitivity; aerospace OEMs tolerate premium positioning for extensive qualification documentation.
Supply Chain Analysis
Contract manufacturing concentration at Foxconn, Pegatron, and Jabil facilities across Shenzhen and Chennai anchors downstream tape lamination capacity. Upstream polyimide substrate production rests on Japanese and Korean chemical conglomerates in Chubu and Ulsan, with ceramic filler processing concentrating in Nagoya-area specialty compounders. Single-source vulnerability in halogen-free polyimide film creates qualification bottleneck risk for European automotive OEMs. Distribution runs through vendor-managed inventory platforms serving Samsung and TSMC procurement organizations, displacing traditional specialty adhesive distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as semiconductor capital expenditure rebounds from trough levels and electric vehicle battery pack assembly scales accelerate procurement. The cyclical driver is foundry utilization rates in Taiwan and South Korea, which correlate directly with die-level thermal tape consumption.
For Market Incumbents: Harden supply security through backward integration into ceramic powder processing capabilities, particularly aluminum oxide and aluminum nitride hybrid fillers. Secure polyimide substrate offtake agreements with Japanese chemical conglomerates before REACH authorization procedures tighten further. Defend margin position by embedding field-level thermal impedance validation services with automotive OEMs, creating switching costs that commodity compounders cannot replicate. For New Entrants and Emerging Players: Pursue qualification gaps in India's PLI scheme electronics manufacturing corridor, where localized thermal tape testing infrastructure remains underdeveloped. Target wearable medical diagnostics specifications requiring FDA biocompatibility certification, a segment where silicone chemistry expertise opens windows against acrylic-dominated incumbents. Establish joint development programs with contract manufacturers in Chennai and Noida to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Regional compounders with captive formulation capabilities and existing automotive OEM qualifications represent the most defensible acquisition profile. Long-term viability hinges on exposure to electric vehicle battery module bonding rather than consumer electronics volume, which faces persistent price erosion. Watch foundry utilization reports from TSMC and Samsung as the inflection signal for thermal interface material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Filler Processing | Captive supply of aluminum nitride hybrid fillers insulates compounders from Japanese powder processor pricing power. |
| REACH Halogen-Free Certification Investment | Alternative flame suppression chemistry qualification opens specification windows with European automotive OEMs facing ECHA restrictions. |
| Vendor-Managed Inventory Platform Deployment | Direct procurement portals serving Samsung and TSMC extract price transparency while locking out traditional distributor competition. |
| India PLI Scheme Localization Partnership | Joint qualification programs with Chennai contract manufacturers capture semiconductor assembly incentives before infrastructure matures. |
| FDA Biocompatibility Pathway Development | Silicone-based thermal tape certification for wearable diagnostics creates premium positioning against acrylic-dominated consumer electronics supply. |
Research Methodology
A standing panel of thermal interface material R&D directors, automotive OEM procurement leads, semiconductor fabrication facility engineers, and specialty adhesive distribution channel managers provided ongoing calibration throughout the study. Primary interview findings combined with secondary validation from EPA TSCA submission databases, ECHA REACH authorization registers, SEC 10-K filings from listed materials science companies, and customs trade data tracking polyimide film shipments. Bottom-up segment sizing triangulated against top-down market aggregation across product type, material chemistry, and end-use application dimensions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with baseline, upside, and downside trajectories reflecting semiconductor capital expenditure cycles and electric vehicle production ramp schedules. Segmentation modeling incorporated product configuration, substrate material, thermal conductivity grade, application vertical, and regional regulatory cluster. CAGRs derived from slope-intercept analysis of historical shipment data mapped against announced foundry and battery gigafactory capacity additions. Industry-specific forecast inputs included TSMC and Samsung vendor-managed inventory platform procurement disclosures and KBA vehicle safety standard cascade timelines.
Sensitivities concentrate around EPA TSCA review timeline extensions for novel silicone crosslinkers, polyimide film supply disruptions from Japanese chemical conglomerate capacity allocation decisions, and automotive OEM platform standardization shifts affecting double-sided thermal tape specifications. Forecasts reflect assumptions regarding REACH authorization procedure scope expansion and PLI scheme incentive continuity. Quarterly review of foundry utilization rates, battery pack assembly production schedules, and ECHA substance restriction proposal dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Water Activated Tape Dispensers Market
Tapes
India Masking Tapes Market
Tapes
Acetate Cloth Tape Market
Tapes
Heat Activated Tear Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Custom Printed Tape Market
Tapes
Paper Masking Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
Carbon Tapes Market
Tapes
Dicing Tapes Market
Tapes
Paper Packaging Tapes Market
Tapes
Unidirectional Tapes Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Paper Tapes Market
Tapes
Non-UV Dicing Tapes Market