
 Thermoplastic Tape Market | 2026-2036
Thermoplastic Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Tape Market Outlook
Automated fiber placement with in-situ consolidation is fragmenting traditional thermoset-dominated aerospace manufacturing. Toray Industries leverages its carbon fiber prepreg heritage to anchor premium thermoplastic unidirectional tape supply for next-generation aircraft programs. Teijin Limited competes through high-performance polyaryletherketone tapes that sustain elevated temperature performance in engine-adjacent structures. Solvay differentiates via integrated resin-to-tape vertical capability, controlling specialty polymer grades that few rivals can replicate.
Thermoplastic tape consists of continuous fiber reinforcement—typically carbon, glass, or aramid—fully impregnated with a thermoplastic matrix such as polyetheretherketone or polyphenylene sulfide, supplied in slit widths from 6.35 mm to 300 mm for automated laydown and welding processes. Its primary purpose replaces thermoset prepregs and metallic assemblies in applications demanding damage tolerance, recyclability, and rapid processing cycles. Polyethylene tapes occupy the volume tier in packaging and consumer goods where cost thresholds dominate procurement decisions. Aerospace-grade polyetherimide and PEEK tapes represent the fastest-expanding margin pool, though polyester maintains entrenched position in electrical insulation where UL certification creates switching friction. Thermal bonding technology leads capital deployment as equipment makers scale laser- and ultrasonic-assisted welding platforms for automotive structural modules.
REACH compliance in Europe mandates disclosure of Substances of Very High Concern in adhesive formulations, reshaping tape chemistry roadmaps for exporters. FAA certification pathways for thermoplastic primary structures in commercial aviation are compressing qualification timelines, while EPA guidelines on volatile organic compounds from solvent-based coating processes push manufacturers toward melt-impregnation alternatives. Stakeholders must monitor evolving OEM qualification standards that will determine which resin-fiber combinations achieve platform design approval.
Market Dynamics
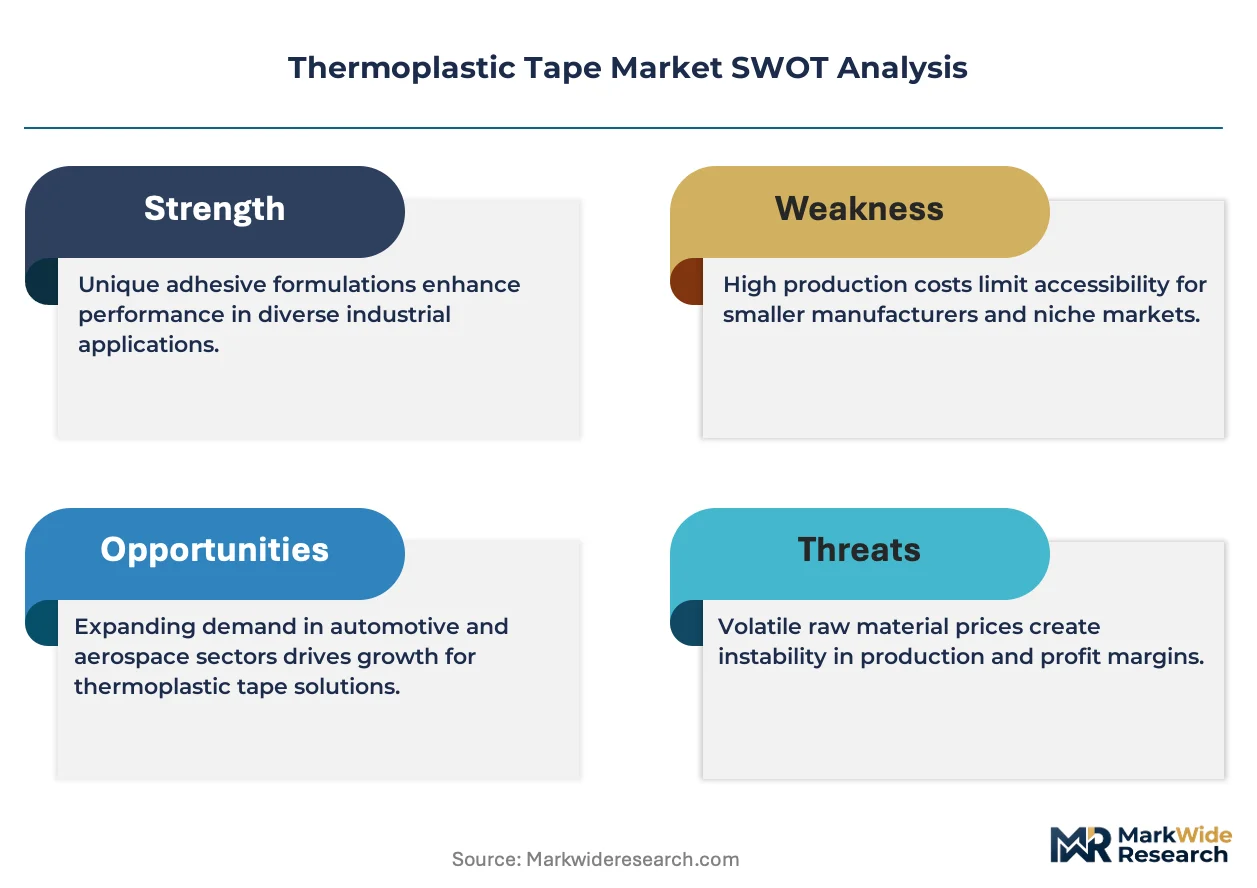
Automated fiber placement with in-situ consolidation is fragmenting aerospace manufacturing's thermoset dominance, while EU Green Deal circularity mandates accelerate bio-based resin development across automotive supply chains.
Growth Catalysts
- REACH SVHC disclosure mandates:European chemical transparency rules force adhesive reformulation, opening demand for melt-impregnated thermoplastic tapes that eliminate solvent-based coating processes.
- Automotive structural bonding:Lightweighting imperatives in electric vehicle platforms displace metallic assemblies with carbon fiber-reinforced PEEK tapes for crash-critical modules.
- FAA certification pathway compression:Accelerated qualification timelines for thermoplastic primary structures enable faster platform design approval for commercial aviation programs.
Market Restraints
- Specialty polymer supply concentration:Polyaryletherketone resin production clusters among three chemical conglomerates, creating feedstock vulnerability for high-performance tape grades.
- Ultrasonic welding equipment capex:Thermal bonding platforms require seven-figure capital deployment, gating entry for mid-tier automotive suppliers.
- UL certification friction:Polyester tape's entrenched electrical insulation position creates switching costs for polyetherimide alternatives despite superior thermal performance.
Strategic Opportunities
- India automotive corridor expansion:PLI scheme incentives for advanced materials manufacturing attract tape laminators to Chennai and Pune industrial zones.
- Laser-assisted welding convergence:Integration of real-time temperature monitoring with robotic laydown equipment enables closed-loop quality assurance for structural modules.
- Bio-based polyamide development:EU Green Deal material circularity targets create procurement preference for tapes derived from renewable feedstocks in German automotive clusters.
Industry Challenges
- Automated fiber placement technician scarcity:In-situ consolidation programming requires specialized robotics expertise that outpaces vocational training output in aerospace manufacturing regions.
- OEM qualification timeline compression:Accelerated platform development cycles strain resin-fiber combination testing protocols, risking premature tape specification lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Tape Market |
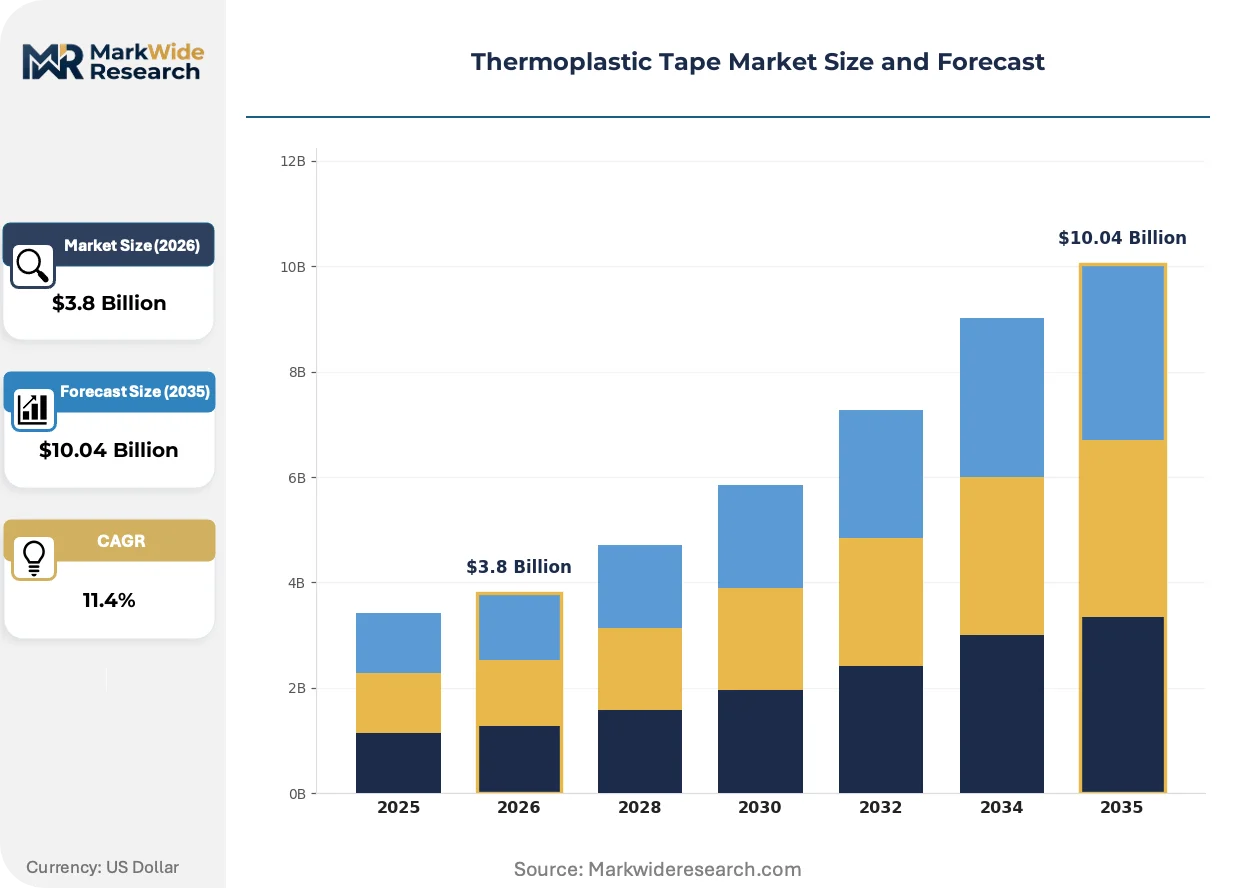
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Vinyl, Polyester Application: Electrical Insulation, Packaging, Automotive, Construction Technology: Adhesive Bonding, Coating Process, Thermal Bonding, Surface Modification End User: Aerospace, Electrical, Consumer Goods, Healthcare |
| Companies Covered | Toray Industries, Inc., Teijin Limited, Solvay, Hexcel Corporation, SGL Carbon, Evonik Industries AG, BASF SE, SABIC, Mitsui Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Tape Market Strategic Shifts
Digital thread integration across design-to-manufacturing workflows is compressing development cycles, while regulatory chemistry roadmaps and procurement model evolution reshape competitive positioning in structural composites.
Laser-assisted thermal bonding equipment is digitizing quality assurance in automotive structural module production. Tier-1 suppliers in Stuttgart's manufacturing corridor deploy real-time thermography feedback loops during automated tape laydown. The technology is digitizing defect detection, collapsing rework cycles from hours to minutes for crash-critical battery enclosures.
EPA volatile organic compound guidelines are eliminating solvent-based coating processes in tape manufacturing. Melt-impregnation alternatives achieve equivalent fiber wet-out without hazardous emissions. Electrical insulation applications in US industrial motor markets respond fastest, with polyester and polyetherimide tape converters retrofitting production lines ahead of enforcement deadlines.
Specification-driven procurement consolidation concentrates buying power among airframe OEMs and automotive platform architects. Long-term resin-fiber supply agreements displace spot purchasing for aerospace-qualified grades. German automotive clusters around Wolfsburg exhibit the most pronounced consolidation, with single-source tape qualifications spanning entire vehicle program lifecycles.
Thermoplastic Tape Market Segmentation
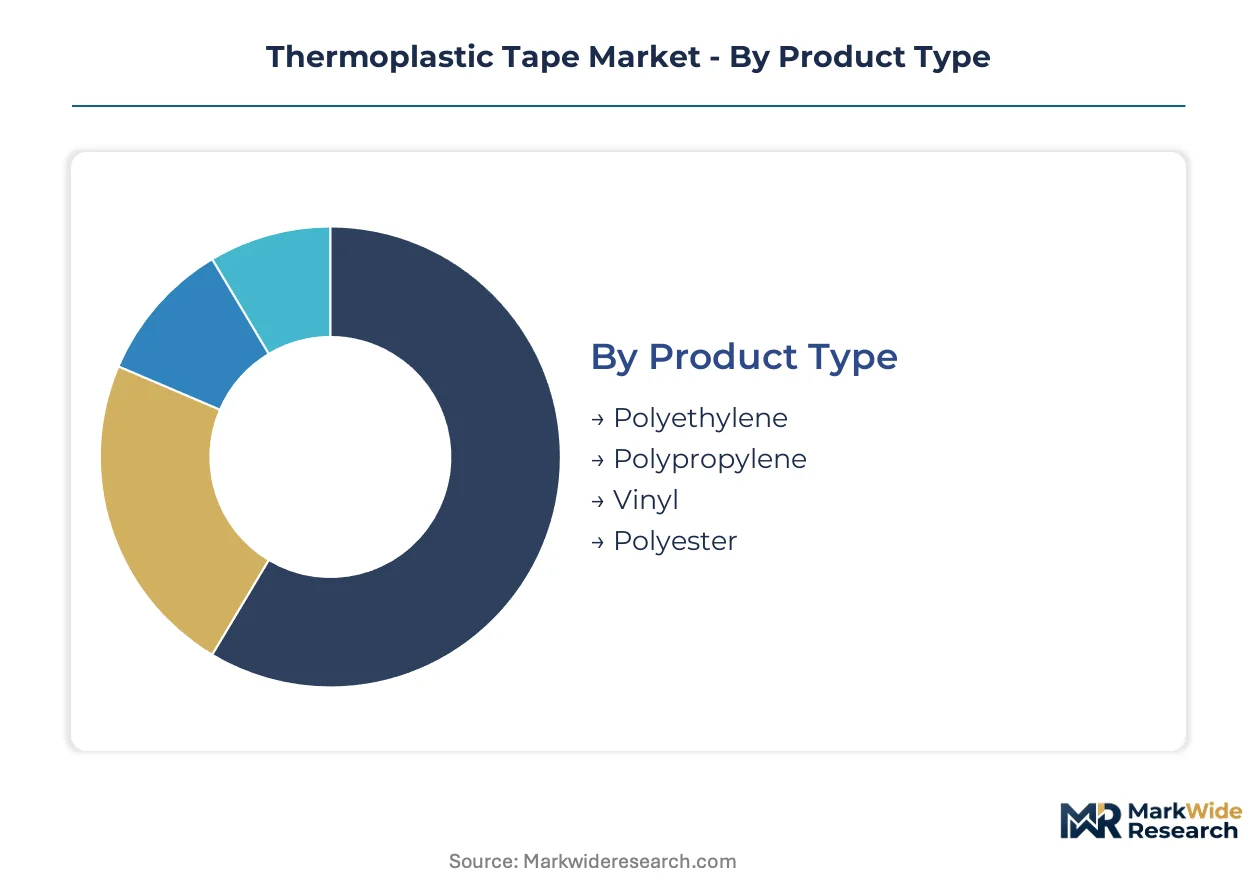
Thermoplastic tape segmentation reveals distinct velocity profiles across chemistry grades and bonding technologies. Procurement cycles compress from commodity polyethylene orders measured in days to aerospace-qualified PEEK specifications spanning quarters.
Product Type:
Polyethylene turns inventory fastest through packaging converters, while polyester and vinyl grades lock into longer electrical certification cycles.
- Polyethylene:Low-density formulations dominate stretch-wrap and bundling applications with 24-48 hour order cycles. Walmart's North American distribution network alone consumes pallet-scale volumes weekly, though margin compression from resin price volatility constrains converter profitability.
- Polyester:Biaxially oriented films with acrylic or silicone adhesives carry UL 510 and CSA C22.2 certifications for motor winding insulation. Siemens and ABB specify 0.025 mm to 0.125 mm thickness grades in transformer manufacturing, where dielectric strength requirements create multi-year specification lock-in.
- Polypropylene:Oriented film tapes with hot-melt or solvent rubber adhesives serve carton sealing and label protection in e-commerce fulfillment.
- Vinyl:Plasticized PVC formulations provide conformable wire harness wrapping with flame-retardant additive packages.
Polyethylene anchors the volume base while polyester gains share at the steepest rate through electrification infrastructure buildouts.
Application:
Cost tiers separate commodity packaging from engineered automotive and electrical grades where certification overhead dominates landed cost.
- Electrical Insulation:Class F and Class H thermal ratings (155°C to 180°C) dictate tape selection in traction motor manufacturing. Tesla's Nevada gigafactory sources polyimide and polyester composite tapes for battery module isolation barriers, with qualification protocols extending 18-24 months.
- Automotive:Carbon fiber-reinforced PEEK and PPS tapes displace aluminum stampings in electric vehicle battery enclosures. BMW's Leipzig assembly plant deploys automated fiber placement for floor pan modules, achieving 40% weight reduction versus steel baseline.
- Packaging:Pressure-sensitive carton sealing tapes compete on metered cost per thousand packages shipped.
- Construction:Vapor barrier seam tapes and flashing membranes integrate with building wrap systems.
Packaging commands absolute volume while automotive applications expand most quickly through platform electrification.
Technology:
Capital intensity stratifies the supply base, with thermal bonding equipment requiring seven-figure outlays that filter supplier participation.
- Thermal Bonding:Laser-assisted and ultrasonic welding platforms enable in-situ consolidation of thermoplastic composites without adhesive layers. GKN Aerospace's Bristol facility processes PEEK/carbon tape through automated fiber placement with real-time temperature feedback, collapsing aerospace part cycle times from hours to minutes.
- Adhesive Bonding:Pressure-sensitive and structural acrylic, epoxy, and rubber-based adhesives dominate electrical and packaging applications. 3M's Scotch brand and tesa SE control formulation IP for high-temperature automotive harness tapes.
- Coating Process:Solvent-based and hot-melt coating lines apply adhesive layers to film substrates.
- Surface Modification:Corona, plasma, and flame treatments improve adhesion on low-surface-energy polyolefin films.
Adhesive bonding retains volume dominance while thermal bonding climbs the fastest through aerospace and automotive structural adoption.
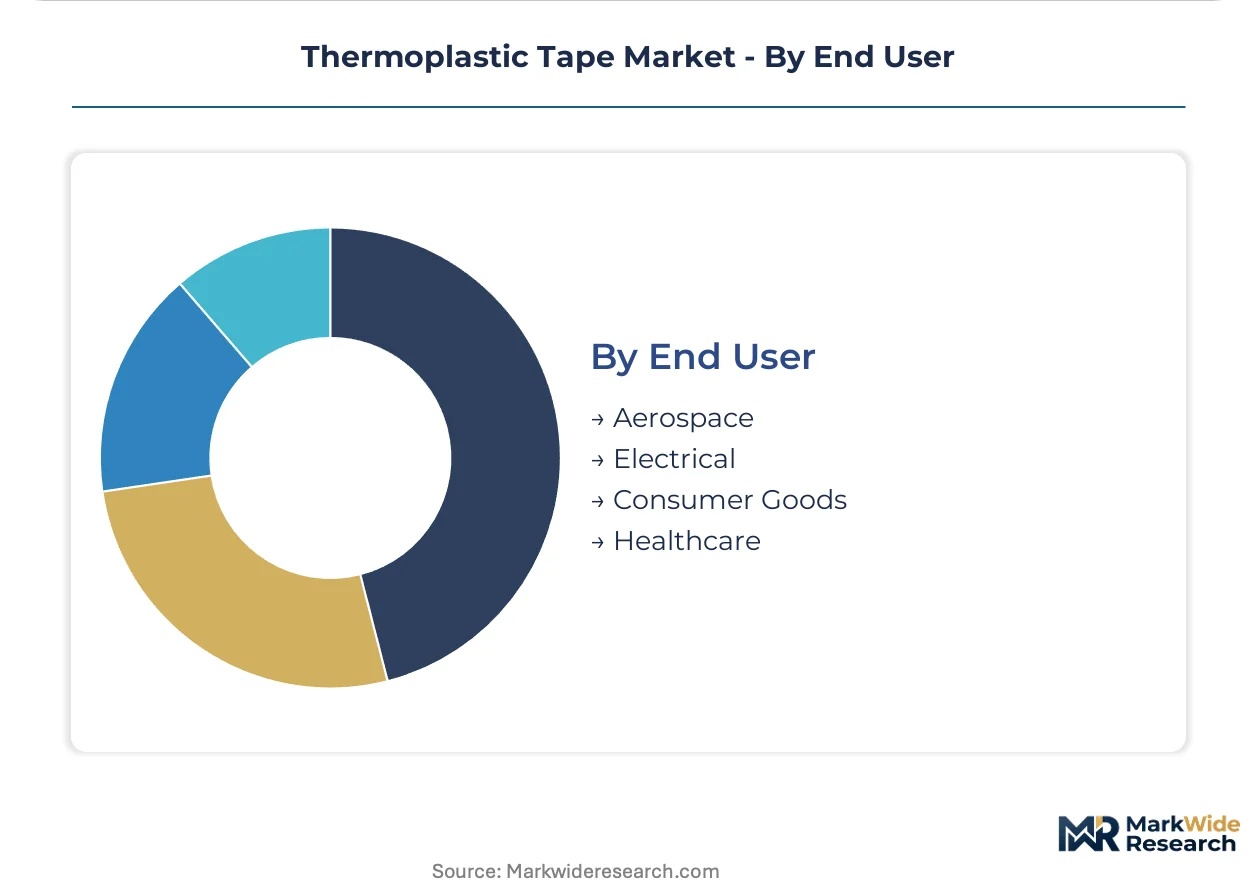
End User:
Customer type determines specification stringency, from healthcare's biocompatibility mandates to consumer goods' cost-per-meter procurement.
- Aerospace:FAA certification under 14 CFR Part 25 governs primary structure qualification. Boeing's 787 and Airbus A350 programs specify Toray Cetex thermoplastic tapes for clips, brackets, and access panels, with resin-fiber combinations locked through multi-decade production agreements.
- Electrical:OEM motor manufacturers and tier-one winding shops specify insulation systems by thermal class and agency certification. Nidec Corporation's appliance motor division sources polyester and polyimide tapes through annual volume contracts with converter partners.
- Consumer Goods:Retail private-label and branded office supply channels procure transparent and colored stationery tapes.
- Healthcare:USP Class VI and ISO 10993 biocompatibility testing governs surgical drape and device packaging tapes.
Electrical end users anchor current volume while aerospace applications demonstrate the steepest expansion trajectory through primary structure qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs concentrate premium thermoplastic tape procurement through long-term supply agreements, while US aerospace primes compress qualification timelines and Chinese EV manufacturers scale automated fiber placement for battery enclosures.
Germany
BMW and Volkswagen specify carbon fiber-reinforced PEEK tapes for electric vehicle floor pans and battery housings. The EU Green Deal's material circularity mandates accelerate bio-based polyamide development across supplier networks. Stuttgart's manufacturing corridor hosts automated fiber placement facilities serving Wolfsburg-based platform programs.
United States
Boeing and Lockheed Martin drive aerospace-grade tape demand for primary structure qualification under compressed FAA certification pathways. EPA volatile organic compound guidelines push converters toward melt-impregnation processes. Washington State's aerospace cluster processes Toray-supplied thermoplastic unidirectional tape for next-generation aircraft programs.
China
BYD and CATL expand carbon fiber tape usage in battery enclosure manufacturing for export-market EV platforms. MIIT dual carbon goals incentivize lightweight structural materials adoption across automotive supply chains. Shanghai's Yangtze River Delta concentration hosts tape laminators serving Ningbo and Hangzhou EV assembly plants.
Japan
Toray Industries and Teijin Limited anchor domestic supply of polyaryletherketone and polyimide tapes for aerospace and electrical insulation applications. METI industrial competitiveness programs fund next-generation composite manufacturing equipment. Nagoya's Chubu region concentrates automated fiber placement expertise for regional jet programs.
India
Tata Motors and Mahindra & Mahindra pilot thermoplastic composite modules for domestic SUV platforms under cost-constrained procurement models. PLI scheme incentives attract tape converter investments to Tamil Nadu and Maharashtra. Chennai's automotive corridor hosts laminator facilities serving Pune-based OEM assembly operations.
Thermoplastic Tape Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. Japanese and European chemical conglomerates dominate high-performance resin supply, while specialized tape converters occupy mid-tier fabrication roles. Three archetypes define competitive structure: integrated resin-to-tape producers, carbon fiber heritage players leveraging prepreg expertise, and automated equipment-integrated laminators. Consolidation through backward integration into specialty polymer production and strategic partnerships for thermal bonding equipment access represent dominant competitive moves.
Among integrated chemical producers, Toray Industries, Teijin Limited, and Solvay occupy positions spanning resin synthesis through qualified tape supply. Toray exemplifies the carbon fiber heritage archetype, anchoring premium unidirectional tape production through captive fiber supply. Teijin represents high-performance polymer specialization, while Solvay sits within the integrated resin-to-tape tier controlling specialty polyaryletherketone grades.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Teijin Limited |
| Solvay |
| Hexcel Corporation |
| SGL Carbon |
| Evonik Industries AG |
| BASF SE |
| SABIC |
| Mitsui Chemicals, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo-Hangzhou freight corridor's container cost dynamics compress margins for polyaryletherketone resin imports while amplifying price differentiation between aerospace-qualified PEEK tapes and commodity polyethylene grades. Supply concentration among Japanese and European chemical conglomerates reinforces their pricing power over high-performance grades, forcing automotive OEMs into long-term offtake contracts.
Pricing Analysis
Cost-plus contracts with polyetheretherketone resin indexation dominate aerospace-grade tape procurement, insulating suppliers from feedstock volatility while locking OEMs into multi-year commitments. Price differentiation separates FAA-certified primary structure grades from industrial insulation tiers through qualification overhead and fiber volume fractions. Pricing pressure stems from resin supply concentration among three chemical conglomerates. Packaging converters exhibit highest price sensitivity, while airframe OEMs accept premium positioning for certified structural grades.
Supply Chain Analysis
Export controls on carbon fiber production equipment under US-Japan-EU restricted-technology frameworks limit capacity expansion in emerging manufacturing regions. Geographic supply concentrates in Japan, Germany, and the United States for aerospace-qualified resin-fiber combinations. Raw material dependencies span polyaryletherketone polymer synthesis, continuous carbon fiber supply, and specialized sizing chemistries. Single-source vulnerability pervades qualified aerospace grades where resin-fiber combinations lock through platform certification. Distribution runs through direct mill relationships for high-performance tiers and converter networks for electrical insulation grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specification-driven procurement consolidation among German automotive platform architects and US aerospace primes, compressing supplier margins while extending qualification timelines.
For Market Incumbents: Entrench position through captive polyaryletherketone resin production and automated fiber placement equipment partnerships. Bio-based polyamide development addresses EU Green Deal circularity mandates threatening petrochemical-derived grades. Thermal bonding platform integration defends against adhesive-bonding substitutes in automotive structural applications.
For New Entrants and Emerging Players: India's PLI scheme-supported automotive corridor around Chennai and Pune represents the most penetrable entry point for tape laminators lacking aerospace certification heritage. Mid-tier electrical insulation converters in North America face EPA-driven equipment replacement cycles creating equipment supply gaps. Laser-assisted welding system partnerships with European equipment makers accelerate automotive qualification pathways.
For Investors and Strategic Acquirers: Automated equipment-integrated laminators with established OEM qualifications command premium positioning through the projection horizon. Long-term viability hinges on thermal bonding technology access and resin supply security. FAA primary structure approval timelines serve as the critical inflection signal for aerospace-grade capacity expansion decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Production | Toray Industries controls PEEK resin supply chains that rivals cannot replicate. |
| Long-term Supply Agreement with Automotive OEM | BMW's Leipzig plant locks carbon fiber tape volumes across entire EV platform lifecycles. |
| Joint Venture for Thermal Bonding Equipment Access | GKN Aerospace's Bristol facility deploys laser-assisted welding for in-situ consolidation. |
| Green Manufacturing Transition to Bio-based Feedstocks | EU Green Deal procurement preferences favor renewable polyamide development in Stuttgart. |
| Capacity Expansion in PLI-Eligible Manufacturing Zone | Chennai's automotive corridor attracts tape converter investments under Indian incentive schemes. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with composite manufacturing engineers, Tier 1 automotive procurement leads, aerospace platform qualification specialists, and tape converter operations managers; and secondary validation through FAA certification databases, EPA enforcement records, EU ECHA SVHC registries, and customs trade flows. SEC 10-K filings from chemical conglomerates, aerospace OEM supply chain disclosures, and automotive production databases provided bottom-up volume triangulation against top-down market sizing.
Forecast inputs considered resin-fiber combination adoption curves, thermal bonding equipment deployment rates, and regulatory chemistry roadmaps across the projection horizon. Segmentation dimensions spanned product chemistry grade, bonding technology, application certification tier, and regional manufacturing cluster. CAGRs derived from installed base growth in automated fiber placement equipment and OEM platform electrification timelines. Industry-specific inputs incorporated REACH SVHC disclosure implementation pace and FAA primary structure qualification compression.
Macroeconomic conditions sit as an overlay; deviation in carbon fiber feedstock pricing, automotive production volumes, or aerospace platform development cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and equipment adoption curves. Cross-checking against IHS Markit automotive production data and FAA certification pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
North America Packaging Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
Paper Gummed Tape Market
Tapes
Umbilical Tapes Market
Tapes
Acetate Cloth Tape Market
Tapes
Tape and Label Adhesives Market
Tapes
Acoustic Tape Market
Tapes
Industrial Tapes Market
Tapes
Strapping Supplies Market
Tapes
Mastic Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
High Bond Tape Market
Tapes
Pouch Tapes Market
Tapes
Heat Sealing Tape Market
Tapes
Nano Tapes Market