
 PVC Tapes Market | 2026-2036
PVC Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Tapes Market Analytics
Asian specialty chemical producers is consolidating captive resin supply for tape-grade PVC formulations. 3M Company leverages its polymer science infrastructure to sustain premium electrical tape positioning across North American utility channels. Saint-Gobain Performance Plastics anchors European demand through fluoropolymer-adjacent tape technologies for high-temperature industrial environments.
PVC tape comprises a flexible substrate of polyvinyl chloride film coated with pressure-sensitive adhesive, typically formulated with acrylic or rubber-based bonding layers and plasticizer additives to achieve elongation rates exceeding 150% for conformable insulation wrapping. The product serves primarily as electrical insulation, surface protection, and moisture sealing across industrial and commercial installations. Electrical tapes dominate value capture due to UL certification requirements and replacement-cycle demand from utility maintenance programs, while masking tapes within automotive refinishing represent the fastest-expanding application segment as OEM paint-shop specifications tighten. Duct tapes compete on contractor brand loyalty and wholesale channel density, with margin pools concentrating in specialized HVAC-grade formulations.
EPA oversees VOC emissions from adhesive manufacturing facilities, compelling solvent-based tape producers toward waterborne or hot-melt coating technologies. OSHA electrical safety standards mandate flame-retardant tape specifications for commercial building installations, directly shaping product certification pathways. ECHA REACH restrictions on phthalate plasticizers are forcing reformulation investments across European supply chains. Stakeholders must monitor evolving chemical substance regulations and adhesive platform transitions to preserve market access and avoid stranded inventory positions.
Market Dynamics
Phthalate-free plasticizer mandates across European regulatory frameworks are forcing rapid adhesive reformulation, compressing margins for solvent-dependent producers while creating technical differentiation for compliant manufacturers.
Growth Catalysts
- Electrical infrastructure investment:Utility-scale renewable energy deployments in the United States and China are accelerating replacement-cycle demand for UL-certified insulation tapes. Grid modernization programs require conformable wrapping materials rated for 600V applications.
- REACH compliance deadlines:ECHA restrictions on diisononyl phthalate (DINP) and diisodecyl phthalate (DIDP) are redirecting R&D expenditure toward bio-based plasticizer alternatives. Reformulation investments concentrate among German and French tape converters.
- Automotive refinishing specifications:OEM paint-shop standards for edge-sealing and masking precision are tightening across Japanese and South Korean assembly plants. Temperature-resistant PVC formulations are displacing lower-grade paper tapes in premium vehicle segments.
Market Restraints
- Crude oil derivative volatility:PVC resin prices track ethylene and chlorine feedstock costs, exposing tape manufacturers to margin compression when naphtha crack spreads widen. Asian petrochemical complexes dominate upstream supply.
- Fluoropolymer substitution in high-heat environments:Polyimide and PTFE tapes capture value in aerospace and industrial furnace applications above 105°C continuous operating temperature. PVC substrates face technical ceiling constraints.
- Waterborne coating capex barriers:EPA VOC emission limits require solvent-based producers to install hot-melt or aqueous adhesive lines. Equipment retrofit costs exceed $4 million for mid-scale coating facilities.
Strategic Opportunities
- India electrical distribution expansion:Rural electrification under the Saubhagya scheme and smart meter rollouts are creating demand for low-voltage insulation tapes. Domestic manufacturing scales to reduce import dependence from China.
- EV battery pack assembly:Cell-to-pack architectures require flame-retardant barrier tapes for thermal runaway containment. Automotive tier-one suppliers are qualifying halogen-free PVC formulations for 800V systems.
- E-commerce contractor channels:Professional HVAC and electrical wholesale buyers are migrating to digital procurement platforms. Private-label tape assortments on Amazon Business and Alibaba 1688 are capturing specification-driven volume.
Industry Challenges
- Adhesive polymer chemist scarcity:Formulation expertise for pressure-sensitive acrylics and synthetic rubber tackifiers is concentrating among aging technical workforces in Germany and Japan. Knowledge transfer gaps threaten innovation pipelines.
- UL certification timeline compression:Accelerated product development cycles for custom electrical tape widths are colliding with 16-week laboratory testing queues. Manufacturers face launch delays or speculative inventory builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Tapes Market |
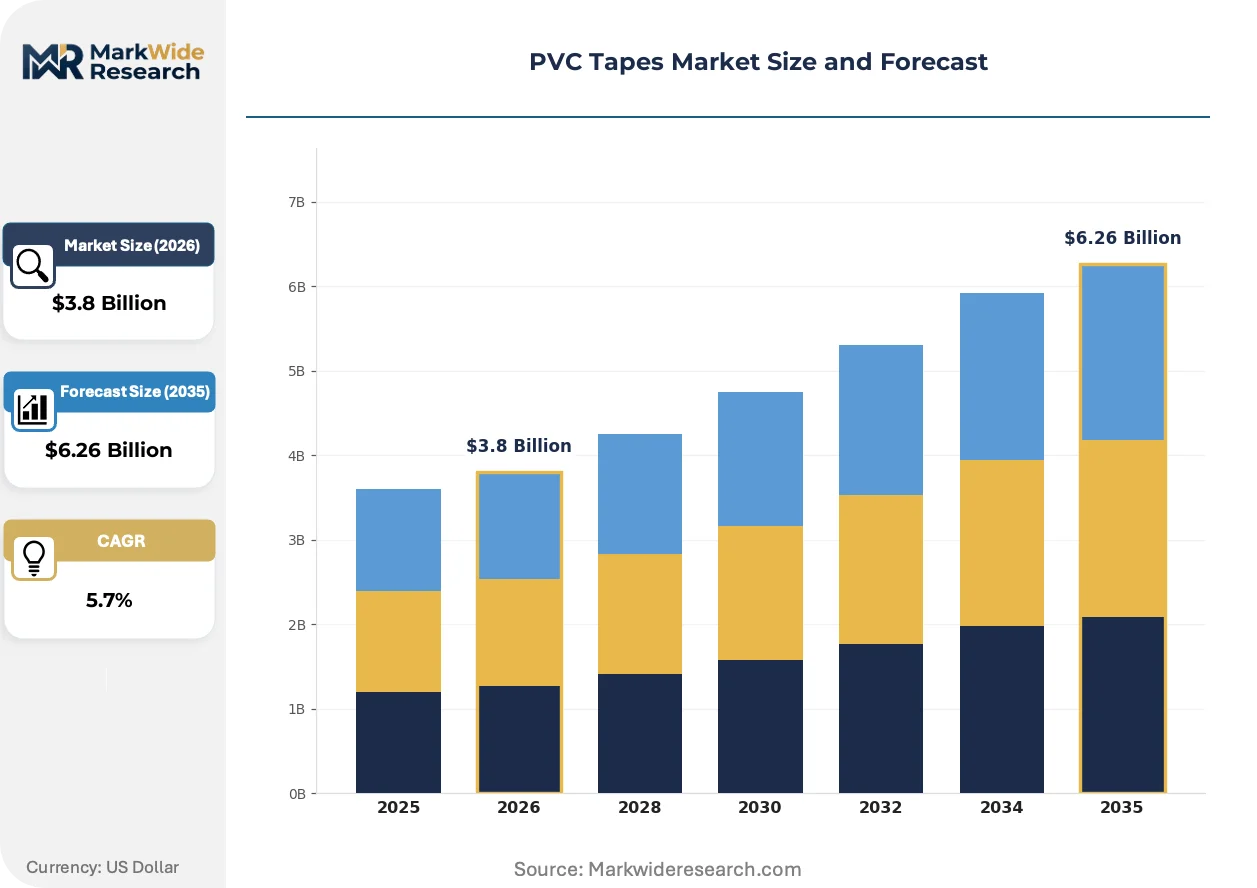
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical, Duct, Masking, Insulation Application: Construction, Automotive, Packaging, Electronics End User: Contractors, Manufacturers, Retailers, Distributors Distribution Channel: Online, Direct Sales, Wholesalers, Retail Stores |
| Companies Covered | Saint-Gobain Performance Plastics, Intertape Polymer Group, 3M Company, Shurtape Technologies LLC, Scapa Group Ltd., Nitto Denko Corporation, Avery Dennison Corporation, Nichiban Co., Ltd., Tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Tapes Market Evolving Landscape
Adhesive platform transitions and specification-driven procurement are reconfiguring competitive advantage around compliance velocity rather than scale economics alone.
Waterborne acrylic adhesive technology is expanding into electrical tape formulations previously dominated by solvent-based natural rubber systems. Tier-one utilities in California and Texas are specifying low-VOC products for indoor commercial installations. The shift is compressing demand for legacy toluene-based coating lines and favoring capital-rich producers with integrated resin compounding.
ECHA REACH Annex XVII restrictions on phthalate plasticizers are compelling European tape manufacturers to validate citrate and trimellitate alternatives. Reformulation cycles now span 18-24 months for full property equivalence in elongation and low-temperature flexibility. German automotive OEMs are demanding third-party certification from suppliers ahead of 2025 enforcement milestones.
Specification-driven procurement through digital distributor platforms is fragmenting buyer-seller relationships in North American contractor channels. Electrical wholesalers in Texas and Florida are unbundling tape SKUs from full-line vendor agreements. Amazon Business and WESCO e-commerce portals are capturing maintenance-repair-operations volume through same-day fulfillment and digital spec sheets.
PVC Tapes Market Segmentation
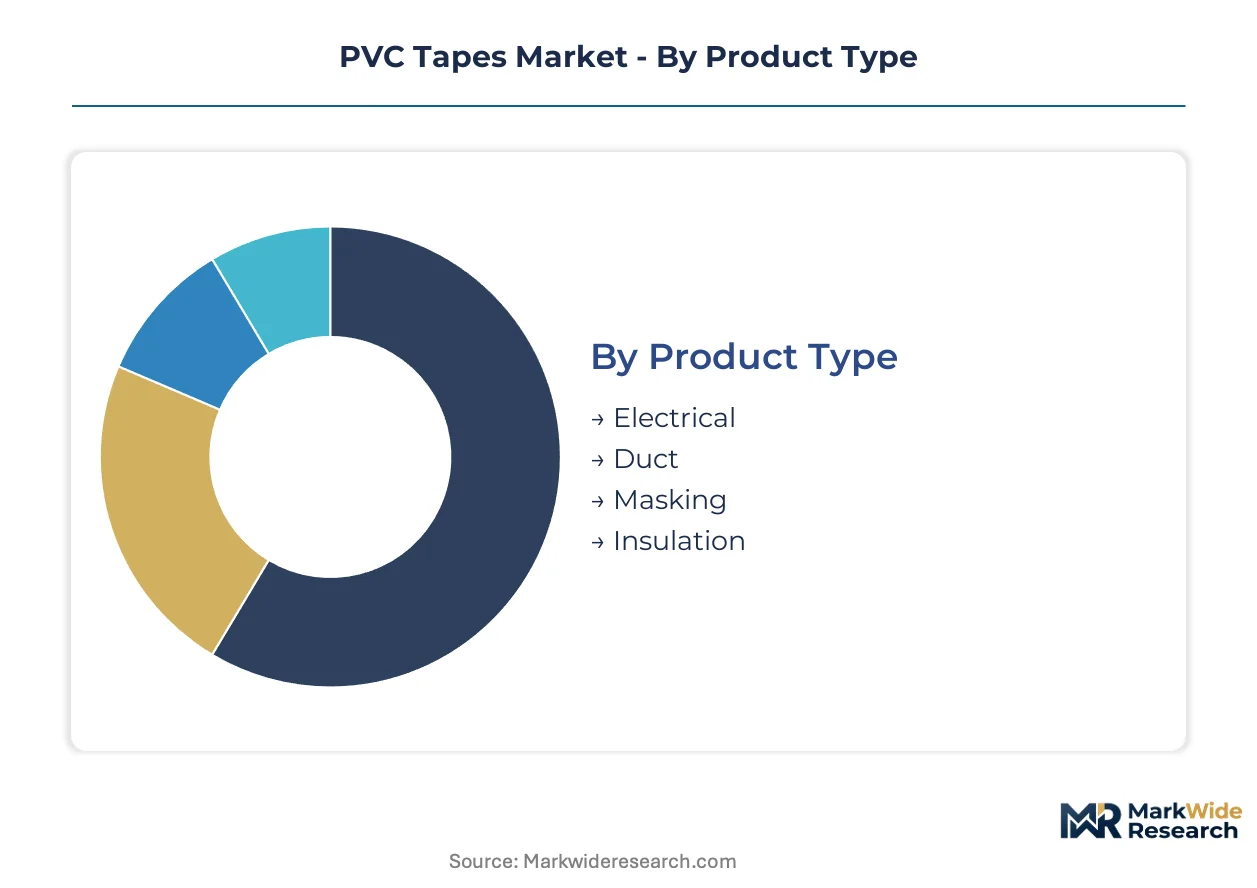
PVC tape manufacturers configure production lines around performance tiers and adhesive chemistries that align with end-use certification requirements. Segment boundaries reflect divergent margin structures between commodity construction supply and specification-driven electrical insulation products.
Product Type:
Supply concentration in electrical-grade formulations creates margin asymmetry across product categories, with UL-certified lines absorbing disproportionate technical labor and resin quality screening.
- Electrical:UL-listed formulations with flame-retardant additives and 600V dielectric strength ratings dominate utility procurement specifications. Demand concentrates in Texas and California grid modernization programs where conformable wrapping for renewable interconnection drives replacement-cycle volume.
- Masking:Temperature-resistant PVC substrates with clean-release adhesives serve automotive refinishing precision requirements. Japanese and South Korean OEM paint-shop standards are displacing lower-grade paper tapes in premium vehicle assembly.
- Duct:Polyethylene-coated cloth backing with aggressive synthetic rubber tackifiers targets HVAC contractor loyalty and wholesale channel density.
- Insulation:General-purpose moisture-sealing formulations compete on elongation rates and low-temperature flexibility for commercial building envelopes.
Electrical tapes absorb the bulk of installed capacity; masking tapes are expanding most quickly.
Application:
Cost tier stratification separates specification-driven automotive and electronics segments from price-sensitive construction bulk purchasing.
- Automotive:EV battery pack assembly requires halogen-free flame-retardant barrier tapes for 800V thermal runaway containment. Automotive tier-one suppliers in Germany and Michigan are qualifying reformulated PVC for cell-to-pack architectures.
- Electronics:Thin-gauge precision winding tapes with controlled unwind tension serve coil and transformer manufacturing. Japanese component producers specify low-outgassing adhesives for clean-room environments.
- Construction:General electrical rough-in and temporary surface protection drive high-volume, low-margin contractor channel movement.
- Packaging:Reinforced carton sealing and pallet stabilization applications compete with polypropylene strapping and hot-melt adhesives on cost per linear foot.
Automotive applications command premium pricing tiers; construction maintains volume leadership through wholesale distributor relationships.
End User:
Customer type determines technical service intensity and inventory holding patterns across the value chain.
- Contractors:Professional electrical and HVAC installers purchase through integrated supply houses with same-day fulfillment requirements and brand specification adherence.
- Manufacturers:OEM tape consumers in automotive and electronics sectors enforce incoming quality testing and lot traceability for adhesive batch consistency.
- Distributors:Industrial supply intermediaries aggregate SKU breadth across multiple adhesive platforms and substrate technologies.
- Retailers:Big-box home improvement chains move commodity-grade electrical and duct tapes through seasonal promotional cycles.
Manufacturers impose the most stringent qualification protocols; contractors generate the highest transaction frequency.
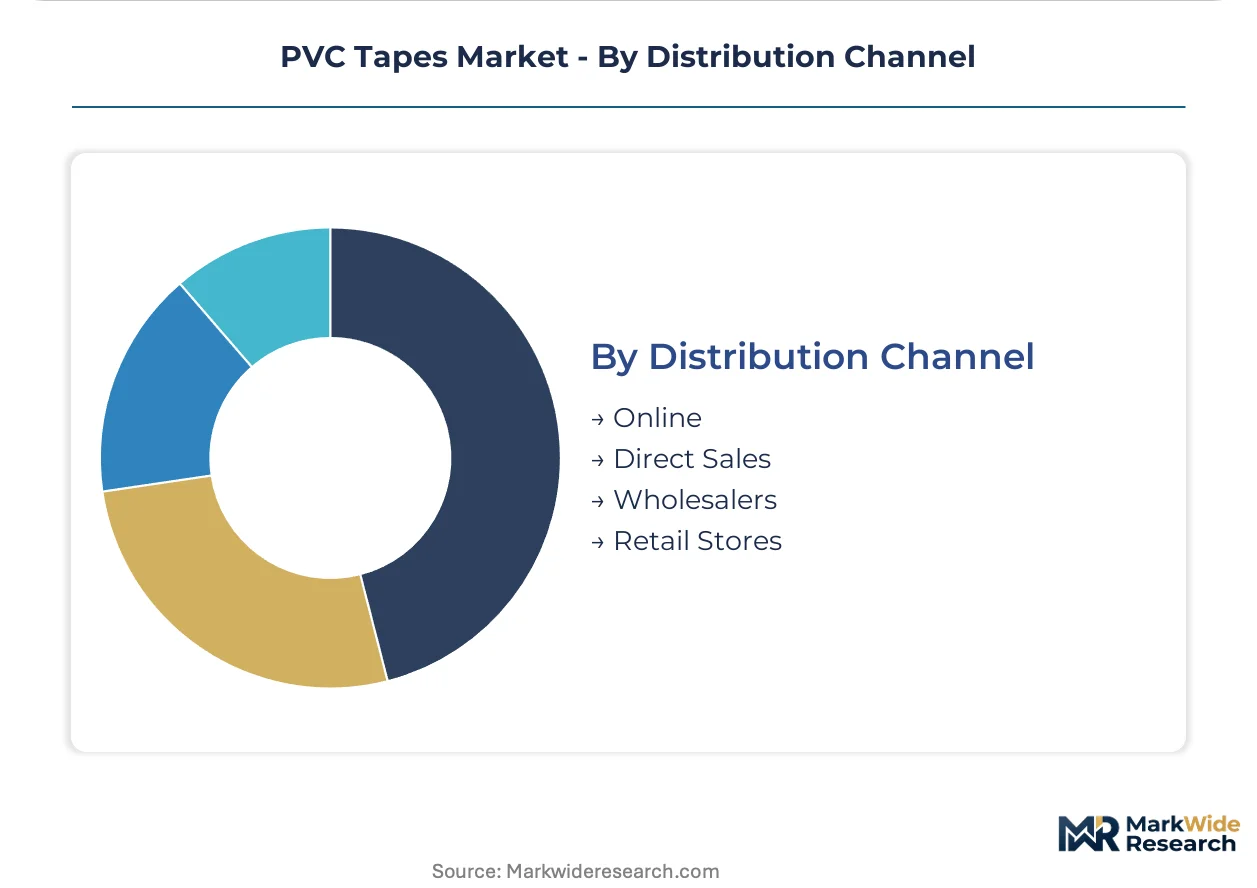
Distribution Channel:
Digital procurement migration is fragmenting traditional wholesale relationships in North American contractor segments.
- Online:Amazon Business and Alibaba 1688 platforms capture specification-driven MRO volume through digital spec sheets and subscription replenishment. California and Texas electrical contractors are unbundling tape SKUs from full-line vendor agreements.
- Direct Sales:National account relationships with utility cooperatives and automotive OEMs bypass distributor markups for volume commitments.
- Wholesalers:WESCO and Graybar maintain electrical tape inventory depth with local branch stocking for emergency repair demand.
- Retail Stores:Home Depot and Lowe's serve residential DIY demand through seasonal promotional placement and private-label alternatives.
Online channels are gaining share fastest; wholesalers retain critical inventory proximity for emergency procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene and chlorine feedstock availability from the US Gulf Coast petrochemical corridor anchors North American tape manufacturing capacity. Asian naphtha crackers in Zhejiang and Ulsan supply resin to integrated converters across East Asia. European chlor-alkali complexes in the Rhine-Ruhr basin face reformulation pressures from REACH plasticizer restrictions.
United States
Utility-scale solar and wind interconnection projects in Texas and California drive UL-certified electrical tape procurement through WESCO and Graybar distribution channels. EPA VOC emission limits under the Clean Air Act push solvent-based coaters toward hot-melt technology retrofits. The Houston Ship Channel petrochemical cluster supplies tape-grade PVC resin to domestic converters serving Gulf Coast industrial markets.
China
Domestic manufacturing scales in Zhejiang and Jiangsu provinces reduce import dependence for electrical insulation products. MIIT industrial standards and GB certification requirements shape product specifications for grid infrastructure investments. The Yangtze River Delta concentration of adhesive coaters exports volume to Southeast Asian construction markets while serving domestic renewable energy deployment.
Germany
ECHA REACH Annex XVII phthalate deadlines force 18-24 month reformulation cycles among tape converters in North Rhine-Westphalia. Automotive OEMs in Bavaria demand third-party certified halogen-free formulations for EV battery assembly. The Rhine-Ruhr industrial corridor hosts specialized adhesive polymer laboratories facing workforce succession challenges.
India
Rural electrification under the Saubhagya scheme and smart meter rollouts create demand for low-voltage insulation tapes across Maharashtra and Gujarat. BIS certification requirements and DGFT import tariffs protect domestic manufacturing scaling in Haryana and Tamil Nadu. Mumbai-Pune industrial belt converters target replacement of Chinese electrical tape imports in price-sensitive distribution segments.
Japan
Precision winding tape specifications from Tokyo and Osaka electronics manufacturers require low-outgassing adhesive formulations for clean-room coil production. METI energy efficiency standards shape industrial tape procurement for factory automation investments. The Chubu region around Nagoya anchors automotive masking tape qualification for premium vehicle paint-shop standards.
PVC Tapes Market Competitive Landscape
Global majors compete with regional champions across adhesive technology platforms and certification depth. The vendor base separates into three tiers: integrated polymer science conglomerates with captive resin supply, specialized tape converters with formulation expertise, and regional fabricators competing on price and local fulfillment. Strategic moves concentrate on waterborne coating capacity investments and REACH-compliant plasticizer partnerships.
Within the integrated polymer science tier, 3M Company and Saint-Gobain Performance Plastics exemplify premium positioning through technical certification depth and utility channel relationships. Among specialized Asian converters, Nitto Denko Corporation and Nichiban Co., Ltd. occupy positions defined by precision coating capabilities and electronics industry specifications. Tesa SE represents European formulation expertise navigating ECHA compliance transitions.
| Leading Market Players |
|---|
| Saint-Gobain Performance Plastics |
| Intertape Polymer Group |
| 3M Company |
| Shurtape Technologies LLC |
| Scapa Group Ltd. |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Nichiban Co., Ltd. |
| Tesa SE |
| Others |
Value Network & Pricing Analysis
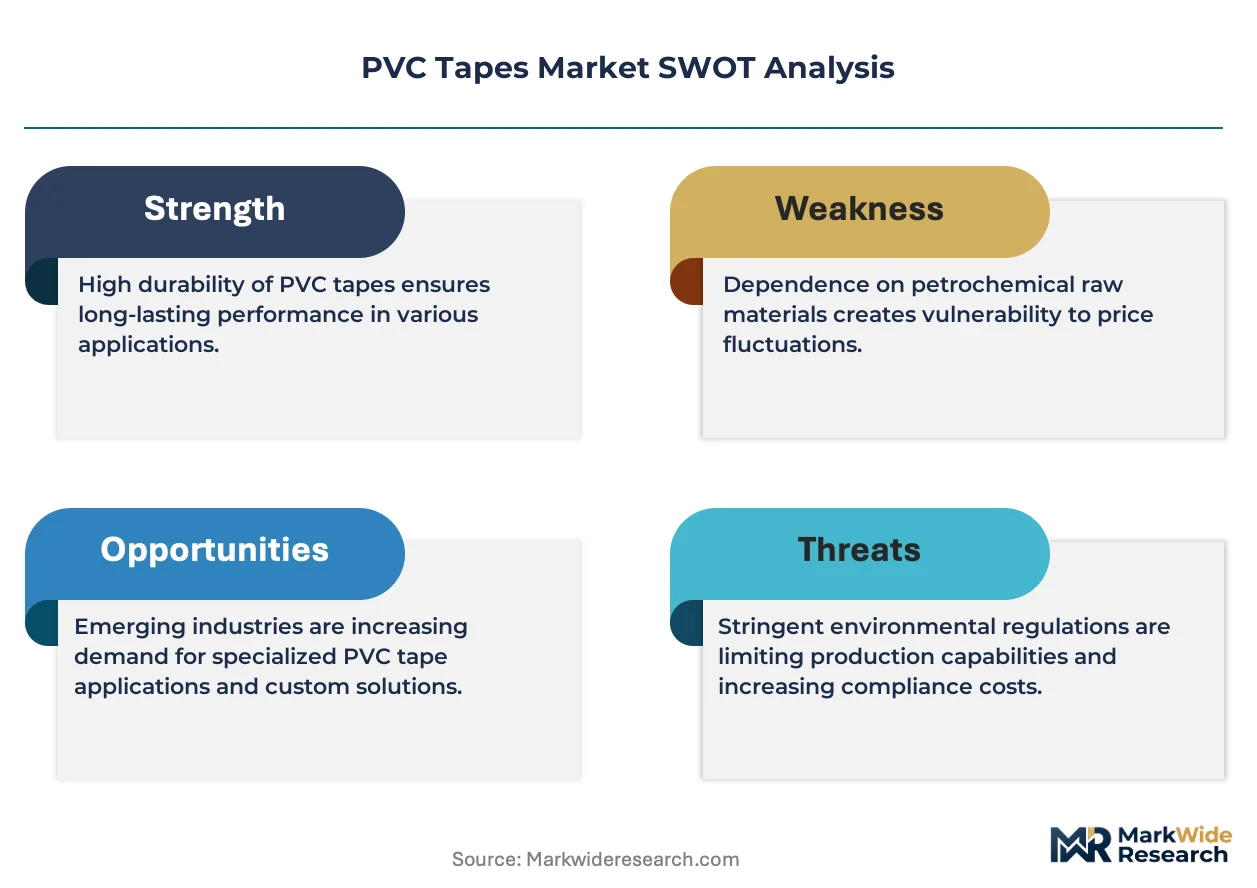
Adhesive polymer chemist scarcity in the Rhine-Ruhr industrial corridor widens labor-cost differentials between premium UL-certified tape manufacturers and commodity-grade converters, compressing margin spreads at the economy tier while compliant producers capture pricing power from REACH-mandated reformulation cycles.
Pricing Analysis
Warranty-backed certification bundles separate premium electrical tape positioning from unbundled commodity SKUs sold through digital procurement portals. Three-tier pricing structure across premium, standard, and economy levels reflects UL certification depth, plasticizer compliance grade, and channel service intensity. Pricing pressure stems from waterborne coating capex barriers forcing mid-scale solvent-based producers toward margin compression or exit. Contractor segments through WESCO and Graybar demonstrate lowest price sensitivity due to emergency procurement requirements, while retail DIY channels compete aggressively on private-label substitution.
Supply Chain Analysis
Reverse-logistics flows for defective tape rolls and adhesive batch returns concentrate among German and Japanese precision coaters with established refurbishment protocols for clean-room electronics specifications. Raw material supply draws from Zhejiang and Ulsan naphtha crackers for PVC resin, Texas Gulf Coast ethylene corridors for specialty monomers, and Rhineland chlor-alkali complexes for plasticizer feedstocks. Single-source vulnerability persists in tape-grade PVC resin compounding where Asian petrochemical complexes control upstream supply. Distribution runs through integrated electrical wholesalers with local branch stocking for emergency repair demand alongside Amazon Business and Alibaba 1688 platforms capturing specification-driven MRO volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH Annex XVII phthalate restrictions function as a cost-of-compliance moat, elevating capital requirements for adhesive reformulation and consolidating advantage among pre-compliant European manufacturers with validated citrate and trimellitate alternatives.
For Market Incumbents: Lock in captive resin supply through backward integration into tape-grade PVC compounding or long-term offtake agreements with Zhejiang and Ulsan petrochemical complexes. Secure UL certification pipeline capacity to preempt 16-week laboratory testing queues that delay custom width launches for utility procurement cycles. Defend channel position by embedding field technical service teams with Texas and California grid modernization contractors. For New Entrants and Emerging Players: Enter via India's rural electrification procurement under the Saubhagya scheme, where BIS certification requirements and DGFT tariffs protect domestic manufacturing scaling in Haryana and Tamil Nadu from Chinese import competition. Target EV battery pack assembly qualifications for halogen-free flame-retardant barrier tapes in 800V cell-to-pack architectures, where automotive tier-one suppliers in Germany and Michigan are actively qualifying new adhesive platforms. Pursue direct e-commerce fulfillment through Amazon Business and Alibaba 1688 to bypass entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with specialized tape converters possessing REACH-compliant plasticizer partnerships and waterborne coating capacity, given ECHA enforcement milestones accelerating customer switching costs toward pre-qualified suppliers. Long-term viability centers on formulation expertise concentration among aging technical workforces in Germany and Japan, where knowledge transfer gaps threaten innovation pipelines and create scarcity value. Monitor UL certification timeline compression and adhesive polymer chemist retirement rates as inflection indicators for consolidation opportunity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Coating Capacity Expansion | EPA VOC emission limits under the Clean Air Act compel solvent-based producers toward hot-melt or aqueous adhesive technology retrofits exceeding $4 million per facility. |
| Backward Integration into PVC Resin Compounding | Captive supply of tape-grade formulations insulates margin compression from naphtha crack spread volatility at Asian petrochemical complexes. |
| REACH-Compliant Plasticizer Partnership | ECHA Annex XVII deadlines force 18-24 month reformulation cycles, concentrating advantage among German and French converters with validated citrate alternatives. |
| Digital Procurement Platform Integration | Amazon Business and WESCO e-commerce portals capture specification-driven MRO volume through same-day fulfillment and digital spec sheet accessibility. |
| EV Battery Tape Qualification Program | Automotive tier-one suppliers in Bavaria and Michigan demand third-party certified halogen-free formulations for 800V thermal runaway containment applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with adhesive R&D directors, electrical utility procurement managers, automotive tier-one supplier quality engineers, and industrial distribution channel partners. Bottom-up demand modeling triangulated against top-down macroeconomic indicators incorporated ACC and Cefic chemical industry reports, SEC 10-K disclosures from listed adhesive manufacturers, ECHA substance restriction notifications, and USITF import trade databases.
Granularity-level modeling disaggregated volume and value outputs across product type, application, end user, and distribution channel dimensions, with additional segmentation by regional regulatory cluster and certification tier. CAGRs were derived from regression-based demand elasticity analysis incorporating electrical infrastructure investment cycles, automotive production forecasts, and construction activity indices. Industry-specific inputs included UL certification queue data, plasticizer price series from ICIS chemical pricing assessments, and utility-scale renewable energy deployment pipelines from FERC interconnection filings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH enforcement acceleration or naphtha feedstock supply disruptions. Projections reflect assumptions regarding adhesive platform transition timelines, workforce succession in specialized polymer chemistry, and digital procurement adoption rates among contractor segments. Practitioners should monitor ECHA substance restriction amendment proposals, EPA VOC emission threshold revisions, and adhesive polymer chemist demographic data for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Foil Tapes Market
Tapes
Sterilization Tape Market
Tapes
Flocking Tape Market
Tapes
Hydrocolloid Tapes Market
Tapes
Paper Tapes Market
Tapes
UV Tapes Market
Tapes
Lacing Tape Market
Tapes
India Masking Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Pouch Tapes Market
Tapes
Global Non Woven Tape Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Sterilization Indicator Tape Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Paper Packaging Tapes Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market