
 Global Printed Tape Market | 2026-2036
Global Printed Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printed Tape Market Foresight
Food-grade and pharmaceutical-grade specification tiers are unwinding new margin pools as buyers reject commodity-grade alternatives in regulated supply chains. 3M Company leverages its adhesive chemistry portfolio to command premium positioning in medical and electronics packaging segments. Avery Dennison Corporation anchors its position through integrated film-coating and print technologies that shorten lead times for custom branding runs. Shurtape Technologies LLC specializes in high-tack acrylic formulations that sustain adhesion across temperature-variable logistics corridors.
Printed tape denotes pressure-sensitive adhesive substrates bearing pre-applied graphics, text, or barcodes, typically manufactured through flexographic or rotogravure processes on polypropylene, PVC, or polyester backings with release coatings measured in grams per square meter. Its primary commercial purpose spans brand authentication, handling instruction communication, and automated sortation compatibility in warehouse environments. Packaging tape and labeling tape categories dominate current volume flows, with adhesive tape and double-sided tape segments capturing faster growth as e-commerce fulfillment centers prioritize damage-reduction and return-prevention protocols. Decorative tape occupies a narrower but higher-margin niche serving event organizers and retail display specialists.
REACH registration requirements in Europe govern phthalate content and heavy-metal thresholds in PVC-based printed tapes, while FDA oversight of medical device packaging imposes biocompatibility and sterility-maintenance standards on adhesive formulations. China's GB standards and SAMR labeling rules for export-bound goods add compliance layers that favor suppliers with in-house testing laboratories and certification documentation. Stakeholders must monitor evolving ESG disclosure frameworks and raw-material pass-through mechanisms as sustainability specifications harden across buyer procurement mandates.
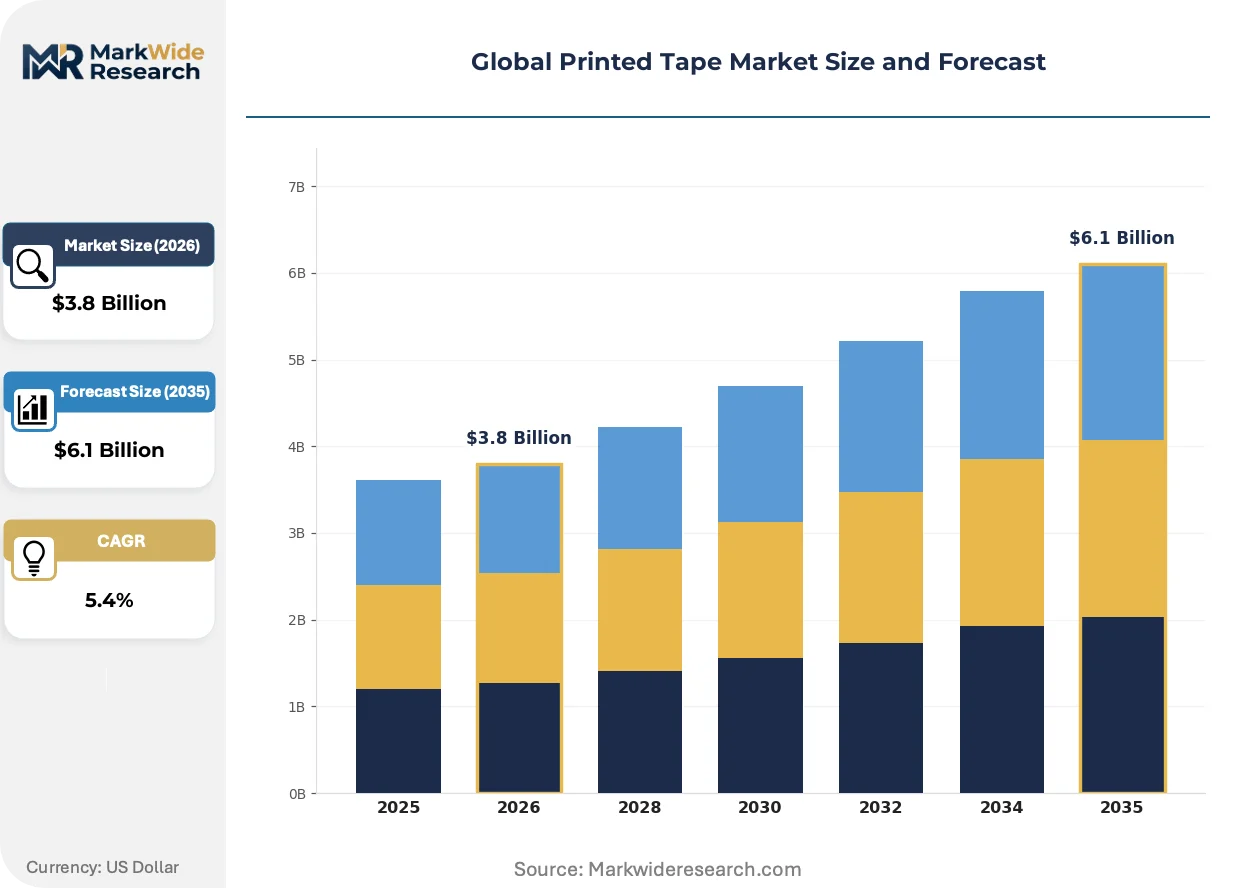
Market Dynamics
E-commerce fulfillment networks are reconfiguring printed tape specifications toward tamper-evidence and automated sortation compatibility, compressing supplier response windows while expanding SKU fragmentation.
Growth Catalysts
- REACH compliance mandates:European ECHA enforcement of phthalate thresholds in PVC backings is filtering out non-compliant suppliers and consolidating procurement toward certified film coaters with in-house testing laboratories.
- Medical device export protocols:FDA biocompatibility requirements for sterile packaging adhesives are creating specification tiers that reject commodity-grade alternatives in pharmaceutical supply chains.
- China's export manufacturing clusters:Guangdong and Zhejiang packaging houses are driving volume procurement of polypropylene-based printed tapes through SAMR labeling rules for cross-border e-commerce shipments.
Market Restraints
- Petrochemical input volatility:Propylene monomer and acrylic adhesive feedstock prices fluctuate with crude oil benchmarks, compressing margin predictability for mid-scale converters without captive resin supply.
- Film-coating concentration:Specialized release liner production concentrates among a handful of East Asian chemical conglomerates, creating single-source vulnerability for European and North American tape finishers.
- Digital watermark substitution:Blockchain-enabled package tracking and direct-to-box inkjet printing are eroding barcode-printed tape volumes in high-value electronics logistics.
Strategic Opportunities
- India's pharmaceutical cold chain:CDSCO serialization mandates for temperature-sensitive biologics are opening specification windows for adhesive tapes with embedded time-temperature indicators.
- EU Green Deal procurement incentives:Public-sector packaging tenders with CSRD-aligned ESG scoring are favoring bio-based acrylate formulations and solvent-free flexographic processes.
- RFID-inlay convergence:Near-field communication chips embedded during tape slitting operations are enabling item-level traceability for luxury goods authentication in Dubai and Singapore free-trade zones.
Industry Challenges
- Flexographic color-matching expertise:Short-run custom branding contracts require prepress technicians capable of Pantone-accurate proofing across substrate variations, a skill pool concentrated among aging specialists in industrialized economies.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and GB standard compliance documentation extends product qualification cycles by 8-14 months for medical-grade tape launches.
- Legacy warehouse management integration:Automated tape applicators in third-party logistics facilities require retrofitted communication protocols to synchronize with existing sortation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printed Tape Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Tape, Packaging Tape, Decorative Tape, Labeling Tape, Double-Sided Tape, Masking Tape Material: Polypropylene, PVC, Cloth, Paper, Acrylic, Polyester Application: Brand Promotion, Product Identification, Safety Markings, Decorative Uses, Inventory Management, Event Branding End User: Manufacturers, Retailers, Advertising Agencies, Shipping Companies, Educational Institutions, Event Organizers |
| Companies Covered | 3M Company, Avery Dennison Corporation, Intertape Polymer Group Inc., Nitto Denko Corporation, Tesa SE, Shurtape Technologies LLC, Lintec Corporation, UPM Raflatac, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printed Tape Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are converging to redefine performance benchmarks and procurement evaluation criteria across printed tape categories.
Water-based acrylic adhesive formulations are supplanting solvent-borne systems in European and North American packaging operations. Food-grade and pharmaceutical-grade buyers in Germany and the Netherlands are mandating volatile organic compound reductions in supplier audits. This chemistry transition is compressing capacity among converters without aqueous coating lines while opening margin pools for certified clean-process specialists.
REACH authorization procedures for di(2-ethylhexyl) phthalate (DEHP) in PVC plasticizers are tightening material specifications for medical device packaging tapes sold into European Economic Area markets. ECHA's sunset date enforcement is forcing reformulation investments among tape manufacturers serving surgical instrument sterilization pouches. German and French distributors are now requiring full substance-of-very-high-concern (SVHC) disclosure documentation upstream to polymer resin suppliers.
Direct-to-factory procurement platforms are fragmenting traditional distribution channels for standard-grade printed tapes. E-commerce fulfillment operators in the United States and United Kingdom are sourcing custom-printed polypropylene tapes through vertical procurement portals that bypass converter-distributor relationships. This disintermediation concentrates price transparency pressure on commodity-grade segments while preserving premium positioning for specification-grade suppliers with embedded technical service capabilities.
Global Printed Tape Market Segmentation
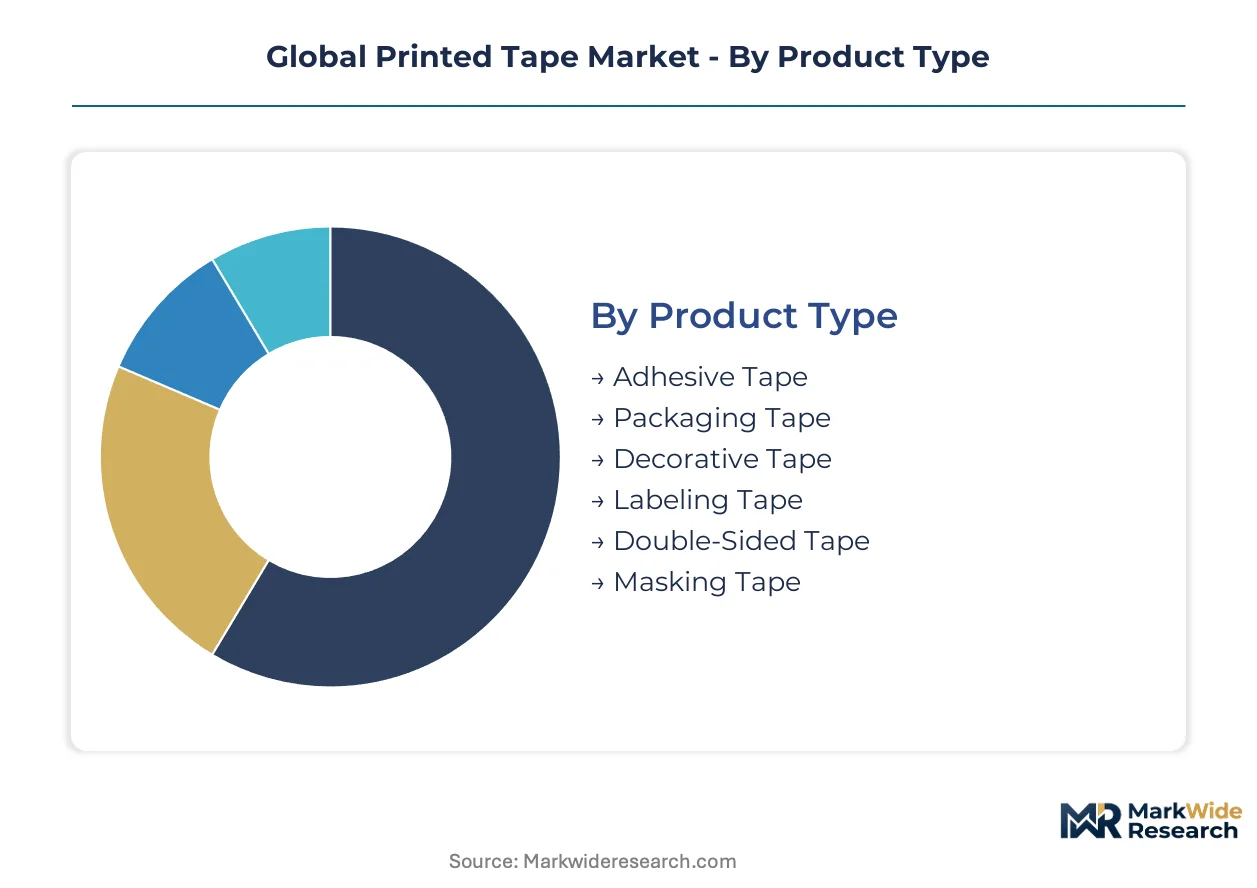
Printed tape segmentation reflects divergent supply chain logics across commodity and specification-grade tiers. Material chemistry and end-use certification requirements fragment procurement patterns, while application-specific durability standards reshape converter capacity allocation.
Product Type:
Domestic consumption concentrates in packaging and masking grades for regional manufacturing, while export-led demand flows through adhesive and double-sided tapes serving cross-border e-commerce fulfillment.
- Adhesive Tape:Pressure-sensitive acrylic or rubber-based formulations bond to corrugated, plastic, and metal surfaces without heat activation. China's Guangdong packaging clusters drive volume procurement for SAMR-compliant export shipments to North American and European markets. REACH phthalate thresholds filter supplier qualification toward certified film coaters with ECHA documentation.
- Packaging Tape:Polypropylene backings with hot-melt or water-based acrylic adhesives dominate carton sealing applications. German and Dutch food-grade buyers mandate volatile organic compound reductions in supplier audits, compressing capacity among converters without aqueous coating lines.
- Decorative Tape:PVC and washi paper substrates with pigment-based inks serve retail display and event organizers in Dubai and Singapore free-trade zones.
- Labeling Tape:Thermal-transfer compatible polypropylene and polyester grades integrate with warehouse management systems for barcode and RFID encoding.
- Double-Sided Tape:Tissue or foam carriers with permanent and removable adhesive zones support mounting and splicing operations in electronics assembly.
- Masking Tape:Crepe paper backings with rubber-based adhesives withstand paint bake cycles in automotive refinishing and industrial coating operations.
Packaging tape commands the established base. The steepest expansion runs through double-sided tape.
Material:
Cost tiers stratify around petrochemical feedstock exposure and specialty polymer premiums, with mid-scale converters vulnerable to propylene monomer volatility.
- Polypropylene:Biaxially oriented film with release coatings measured in grams per square meter serves high-volume carton sealing. India's pharmaceutical cold chain opens specification windows for temperature-stable formulations meeting CDSCO serialization mandates.
- PVC:Plasticized vinyl backings offer conformability to irregular surfaces and print receptivity for decorative applications. ECHA's DEHP sunset date enforcement forces reformulation investments among manufacturers serving European medical device sterilization pouches.
- Cloth:Woven cotton or synthetic fiber substrates with natural rubber adhesives provide hand-tearability and high-tack performance in construction and heavy-duty bundling.
- Paper:Kraft and flatback papers with solvent or hot-melt adhesives serve masking and temporary holding applications in painting and assembly operations.
- Acrylic:Cast or extruded acrylic films deliver optical clarity and UV resistance for outdoor signage and architectural bonding.
- Polyester:Dimensionally stable films with silicone release liners enable precision die-cutting for electronics and medical device labeling.
Polypropylene dominates volume flows. Polyester gains share fastest in specification-grade medical and electronics segments.
Application:
Customer type splits between procurement-led volume buyers and marketing-led custom branding contracts with divergent lead time and color-matching requirements.
- Brand Promotion:Flexographic or rotogravure printed graphics on colored substrates transform packaging into mobile advertising. United Kingdom and United States e-commerce fulfillment operators source through vertical procurement portals that bypass traditional converter-distributor relationships.
- Product Identification:Barcode, QR code, and human-readable text enable automated sortation and supply chain traceability. FDA biocompatibility requirements for sterile packaging adhesives create specification tiers that reject commodity-grade alternatives in pharmaceutical supply chains.
- Safety Markings:High-visibility colors and hazard symbols communicate handling protocols for hazardous materials and fragile contents.
- Decorative Uses:Metallic finishes, holographic effects, and custom patterns serve retail display and consumer craft segments.
- Inventory Management:Color-coded and sequentially numbered tapes support visual stock rotation and lot tracking in warehouse environments.
- Event Branding:Short-run custom Pantone matching for corporate activations and trade show installations demands prepress expertise concentrated among aging specialists in industrialized economies.
Product identification anchors industrial procurement. Brand promotion climbs fastest as unboxing experience investments expand.
End User:
Maturity gradients separate legacy manufacturing adopters from digitally native e-commerce operators with divergent technical service expectations.
- Manufacturers:Automotive, electronics, and consumer goods producers specify tape performance across temperature-variable logistics corridors. Shurtape Technologies LLC anchors positioning through high-tack acrylic formulations sustaining adhesion from assembly through final delivery.
- Retailers:Omnichannel operators balance stock-keeping unit proliferation against packaging standardization, compressing supplier response windows. Direct-to-factory procurement platforms fragment traditional distribution channels for standard-grade printed tapes.
- Advertising Agencies:Creative services firms source short-run custom branding with Pantone-accurate proofing requirements.
- Shipping Companies:Third-party logistics providers retrofit automated tape applicators with communication protocols synchronizing to existing sortation infrastructure.
- Educational Institutions:Administrative and facilities procurement favors economy-grade masking and labeling tapes for general purpose applications.
- Event Organizers:Corporate and entertainment producers demand rapid-turnaround custom printing for temporary installations and promotional activations.
Manufacturers retain the volume foundation. Retailers drive the steepest specification evolution toward tamper-evidence and automated compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Film-coating capacity clusters among East Asian chemical conglomerates, creating single-source vulnerability for European and North American tape finishers. Demand fragmentation accelerates as e-commerce fulfillment networks in multiple jurisdictions reconfigure specifications toward tamper-evidence and automated sortation compatibility.
United States
FDA biocompatibility requirements for sterile packaging adhesives create specification tiers that reject commodity-grade alternatives in pharmaceutical supply chains. E-commerce fulfillment operators source custom-printed polypropylene tapes through vertical procurement portals that bypass traditional converter-distributor relationships. California and Texas logistics hubs drive retrofit demand for automated tape applicators synchronizing with existing warehouse management infrastructure.
Germany
REACH authorization procedures for di(2-ethylhexyl) phthalate in PVC plasticizers tighten material specifications for medical device packaging tapes sold into European Economic Area markets. ECHA's sunset date enforcement forces reformulation investments among manufacturers serving surgical instrument sterilization pouches. Bavarian and North Rhine-Westphalian distributors now require full substance-of-very-high-concern disclosure documentation upstream to polymer resin suppliers.
China
Guangdong and Zhejiang packaging houses drive volume procurement of polypropylene-based printed tapes through SAMR labeling rules for cross-border e-commerce shipments. GB standards and evolving export compliance layers favor suppliers with in-house testing laboratories and certification documentation. Shanghai and Shenzhen manufacturing clusters concentrate film-coating capacity among state-affiliated chemical conglomerates with captive resin supply.
India
CDSCO serialization mandates for temperature-sensitive biologics open specification windows for adhesive tapes with embedded time-temperature indicators. Maharashtra and Gujarat pharmaceutical cold chain infrastructure expands procurement of polypropylene formulations meeting biocompatibility thresholds. Mumbai and Ahmedabad packaging converters invest in aqueous coating lines to capture food-grade and pharmaceutical-grade margin pools.
United Kingdom
Water-based acrylic adhesive formulations supplant solvent-borne systems in packaging operations serving German and Dutch food-grade buyers. Volatile organic compound reductions in supplier audits compress capacity among converters without aqueous coating lines. London and Midlands logistics corridors prioritize tamper-evidence specifications for e-commerce fulfillment networks competing with continental European hubs.
Global Printed Tape Market Competitive Landscape
Concentration sits with diversified adhesive chemistry specialists and integrated film-coating operations. Mid-scale converters without captive resin supply face margin compression from petrochemical input volatility. Three archetypes dominate: specification-grade suppliers with embedded technical service capabilities, scale-driven commodity producers with aqueous coating investments, and regional specialists in high-tack acrylic formulations. Competitive moves center on backward integration into release liner production and geographic expansion through certification documentation in multiple jurisdictions.
Within the specification-grade tier, 3M Company and Avery Dennison Corporation exemplify integrated adhesive chemistry and film-coating operations that shorten lead times for custom branding runs. Shurtape Technologies LLC anchors positioning through specialized formulations serving temperature-variable logistics corridors. These three entities represent the dominant competitive archetypes: diversified multinational with adhesive portfolio depth, integrated film-coating and print technology platform, and regional specialist with high-performance formulation expertise.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Intertape Polymer Group Inc. |
| Nitto Denko Corporation |
| Tesa SE |
| Shurtape Technologies LLC |
| Lintec Corporation |
| UPM Raflatac |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
Water-based acrylic adhesive formulations displacing solvent-borne systems in European packaging operations simultaneously relocate coating capacity toward Germany and the Netherlands while compressing margins among converters lacking aqueous line investments. This chemistry transition concentrates supply geography among certified clean-process specialists and fragments pricing power across legacy solvent-dependent mid-scale producers.
Pricing Analysis
REACH authorization procedures dictate the pricing tier structure across European medical device packaging segments, separating SVHC-compliant premium grades from reformulation-lagged standard tiers and commodity spot alternatives. Price differentiation rests on ECHA documentation depth and FDA biocompatibility certification status, with German and French distributors commanding premiums for upstream substance disclosure. Cost compression in standard-grade polypropylene backings is intensifying because direct-to-factory procurement portals bypass traditional converter-distributor markups. E-commerce fulfillment operators exhibit highest price sensitivity through volume aggregation, while pharmaceutical cold chain buyers prioritize specification compliance over unit economics.
Supply Chain Analysis
East Asian chemical conglomerate concentration in specialized release liner production underwrites single-source vulnerability for European and North American tape finishers. Manufacturing gravity centers on China, South Korea, and Japan, with propylene monomer and acrylic adhesive feedstocks drawing from regional petrochemical complexes. Tariff exposure on biaxially oriented polypropylene film imports threatens margin stability for mid-scale converters without captive resin supply. Distribution runs through converter-distributor networks fragmenting under vertical procurement portal pressure, with specification-grade suppliers preserving embedded technical service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and certification documentation subscriptions represent a recurring-revenue layer expanding faster than base tape hardware sales, as buyers prioritize compliance-ready supply partnerships over commodity spot purchasing.
For Market Incumbents: Secure backward integration into release liner production to neutralize East Asian single-source vulnerability, while locking ECHA pre-registered substance portfolios ahead of DEHP sunset enforcement. Digital watermark substitution in electronics logistics threatens barcode-printed tape volumes; defend through RFID-inlay convergence investments for luxury authentication segments. For New Entrants and Emerging Players: Anchor in India's pharmaceutical cold chain infrastructure where CDSCO serialization mandates create specification windows for time-temperature indicator embedded tapes. Maharashtra and Gujarat biologics distribution offers the most penetrable geography; pursue aqueous coating line partnerships with Mumbai converters lacking pharmaceutical-grade certification capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale converters possessing ECHA documentation libraries but lacking aqueous coating capacity for food-grade margin capture. Five-to-ten year viability favors specification-grade specialists with embedded testing laboratories over commodity spot players. Monitor EU Green Deal procurement incentive penetration in public-sector packaging tenders as inflection signal for bio-based acrylate formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Release Liner Production | Neutralizes single-source dependency on East Asian chemical conglomerates for European finishers. |
| Aqueous Coating Line Capacity Expansion | Captures food-grade and pharmaceutical-grade margin pools as German buyers mandate VOC reductions. |
| ECHA SVHC Documentation Investment | Secures premium positioning in REACH-compliant medical device sterilization pouch supply chains. |
| RFID-Inlay Convergence for Tape Slitting | Enables item-level traceability for luxury goods authentication in Dubai and Singapore free-trade zones. |
| Direct-to-Factory Procurement Portal Launch | Bypasses distributor markups for e-commerce fulfillment operators while concentrating price transparency pressure on commodity segments. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with adhesive chemists, flexographic prepress technicians, pharmaceutical packaging procurement managers, and third-party logistics operations directors; and secondary validation through ECHA substance registration databases, FDA 510(k) filings for medical device packaging, customs trade data on biaxially oriented polypropylene film flows, and SEC 10-K disclosures from diversified adhesive manufacturers. Bottom-up capacity modeling across coating line installations triangulated against top-down demand aggregation from e-commerce fulfillment network expansion metrics.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation dimensions spanning material chemistry tier, end-use certification grade, adhesive formulation type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating propylene monomer price volatility and REACH compliance cost pass-through assumptions. Industry-specific forecast inputs included SAMR labeling rule implementation timelines for cross-border e-commerce shipments and CDSCO serialization mandate phase-in schedules for temperature-sensitive biologics.
Underlying assumptions cover sustained e-commerce fulfillment network expansion and REACH sunset date enforcement without regulatory delay, with deviation risk concentrated in petrochemical feedstock price spikes and accelerated digital watermark substitution in high-value electronics logistics. Practitioners should keep alternative scenarios live as EU Green Deal procurement incentive penetration and bio-based acrylate formulation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Utility Grade Duct Tapes Market
Tapes
Heat Release Tape Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Tissue Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Protective Films Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Thermal Release Tapes Market
Tapes
Seam Tapes Market
Tapes
Nylon Cable Ties Market
Tapes
Filmic Tapes Market