
 UV Tapes Market | 2026-2036
UV Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
UV Tapes Market Intelligence
Semiconductor back-end processing is shifting toward finer-pitch die handling and temporary bonding workflows. Nitto Denko Corporation leverages its polymer synthesis capabilities to dominate UV-release formulations for wafer dicing. Lintec Corporation anchors East Asian supply through precision coating infrastructure. Furukawa Electric Co., Ltd. competes on thermal stability specifications for high-temperature cure environments.
UV tapes are pressure-sensitive adhesive films engineered with photoreactive chemistries that lose tack upon ultraviolet exposure, enabling residue-free removal of delicate substrates during semiconductor dicing, grinding, and pick-and-place operations. These products typically incorporate acrylic or olefin-based adhesive layers on polyolefin or PVC backings with controlled elongation properties calibrated to specific wafer thicknesses. Single-sided tapes lead volume consumption in dicing applications where temporary fixation must withstand coolant exposure and spindle stress. Double-sided configurations represent the fastest-growing category as 3D stacking and fan-out panel-level packaging expand. Polyimide substrates command premium positioning due to thermal endurance during laser grooving and plasma etch steps.
EPA chemical safety evaluations under TSCA constrain adhesive monomer selections for US-bound electronics supply chains. REACH substance restrictions in Europe mandate disclosure of photoinitiator compositions, pushing reformulation toward Type II cleavage initiators with lower migration profiles. Semiconductor manufacturers must monitor evolving dual-use export control classifications affecting tape-equipped die bonders and precision dicing equipment. Stakeholders should track how China's GB standards for electronic materials and South Korea's K-Battery and K-Semiconductor strategies reshape qualification requirements for adhesive suppliers serving advanced packaging ecosystems.
Market Dynamics
Semiconductor packaging roadmaps are compressing die thicknesses below 50 microns while expanding wafer diameters to 300mm, forcing adhesive suppliers to engineer UV tapes with simultaneous high-tack fixation and clean UV-triggered release without substrate damage.
Growth Catalysts
- Fan-out panel-level packaging:Panel formats exceeding 600mm square require double-sided UV tapes capable of handling warpage during mold compound curing, pulling volume from legacy wafer-level formats.
- REACH Article 33 disclosure mandates:European ECHA enforcement of photoinitiator substance declarations is accelerating supplier qualification cycles for compliant Type II cleavage chemistries.
- High-bandwidth memory stacking:HBM3 and HBM4 architectures demand temporary bonding tapes that survive multiple thermal excursions above 200°C during TSV formation and chip stacking.
Market Restraints
- Polyimide substrate cost volatility:Raw polyimide film prices fluctuate with aerospace and flexible electronics demand, compressing margins for thermal-grade UV tape formulations.
- Photoinitiator supply concentration:German and Japanese specialty chemical houses control 80% of high-purity cleavage-type photoinitiator production, creating single-source vulnerability.
- Acrylic adhesive temperature ceiling:Standard acrylic chemistries soften above 150°C, excluding them from laser grooving and plasma etch steps where polyimide alternatives dominate.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme disbursements for display and semiconductor fabrication are creating qualification demand for UV tapes in Gujarat and Tamil Nadu greenfield fabs.
- Glass substrate interposers:Intel and Samsung roadmaps for glass core substrates require UV tapes with matched CTE and non-contaminating release for panel processing.
- UV-LED curing equipment retrofit:Mercury lamp phase-outs under Minamata Convention implementation are creating upgrade cycles compatible with narrow-wavelength UV tape formulations.
Industry Challenges
- Cleanroom contamination control:Silicone outgassing from pressure-sensitive adhesive carriers requires nanogram-level detection protocols that extend tape qualification timelines by 6-12 months.
- Cross-functional substrate engineering:Tape formulators must coordinate elongation properties with grinding wheel vendors and dicing saw manufacturers, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Tapes Market |
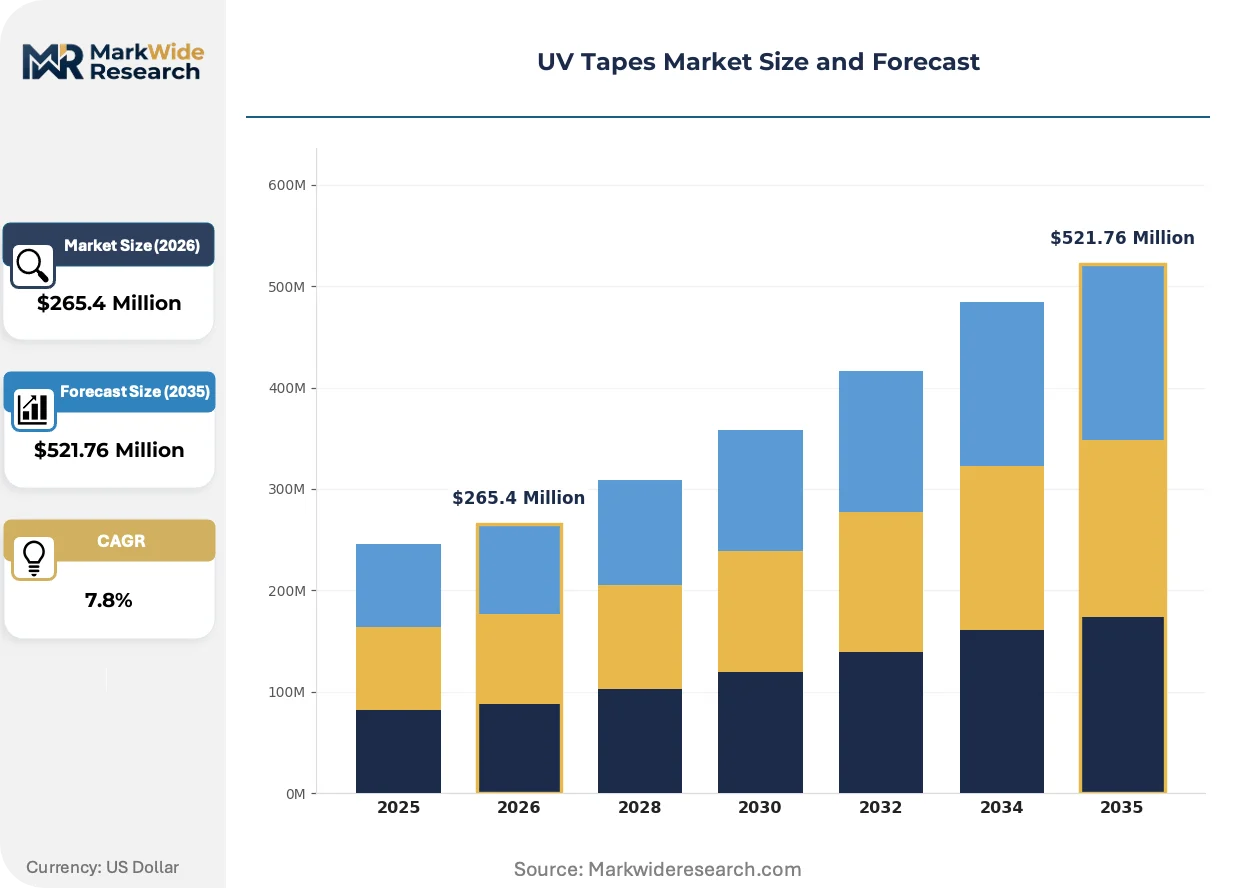
| Market Size in 2026 | $265.4 Million |
| Market Size in 2035 | $521.76 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tapes, Single-Sided Tapes, Transfer Tapes, Adhesive Films Application: Electronics, Automotive, Medical Devices, Packaging Material: Polyimide, Polyester, PVC, Paper End User: Manufacturers, Distributors, Research Institutions, Contractors |
| Companies Covered | Nitto Denko Corporation, Lintec Corporation, Furukawa Electric Co., Ltd., Sumitomo Bakelite Co., Ltd., 3M Company, Denka Company Limited, Mitsui Chemicals, Inc., tesa SE, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Tapes Market Strategic Shifts & Innovations
Photoreactive adhesive systems are undergoing functional specialization as semiconductor processing bifurcates between high-temperature cure environments and room-temperature debond workflows. Three developments are restructuring supplier technical roadmaps and buyer specification priorities.
Photocleavable silicone hybrid adhesives are converging with temporary bonding applications for ultra-thin wafer handling below 25 microns. Memory foundries in South Korea are qualifying these formulations for HBM manufacturing where traditional acrylic tapes fail under thermal stress. The technology is compressing the addressable market for standard acrylic UV tapes in advanced packaging nodes.
EPA TSCA Section 6 risk evaluations for bisphenol A derivatives are restricting certain acrylic monomer selections for US-bound electronics supply chains. Adhesive manufacturers are reformulating with aliphatic epoxy acrylates and urethane oligomers to maintain market access. Semiconductor packaging houses serving US defense and aerospace end-uses are prioritizing suppliers with verified TSCA-compliant substance inventories.
Consolidated procurement through semiconductor equipment OEMs is displacing direct tape purchasing by back-end assembly houses. Disco Corporation and Applied Materials now specify qualified UV tape vendors for die bonders and dicing systems, funneling volume through pre-approved supplier lists. Taiwan and South Korea display the most pronounced channel concentration, with equipment-integrated consumables capturing 60% of regional volume.
UV Tapes Market Segmentation
UV tape procurement decisions pivot on thermal endurance requirements, release kinetics, and substrate compatibility with specific semiconductor process flows. Buyers evaluate formulations against equipment OEM specifications, regulatory substance inventories, and cleanroom contamination protocols.
Product Type:
Cost tier determines specification depth, with premium double-sided formulations commanding qualification cycles that extend 18-24 months for advanced packaging nodes.
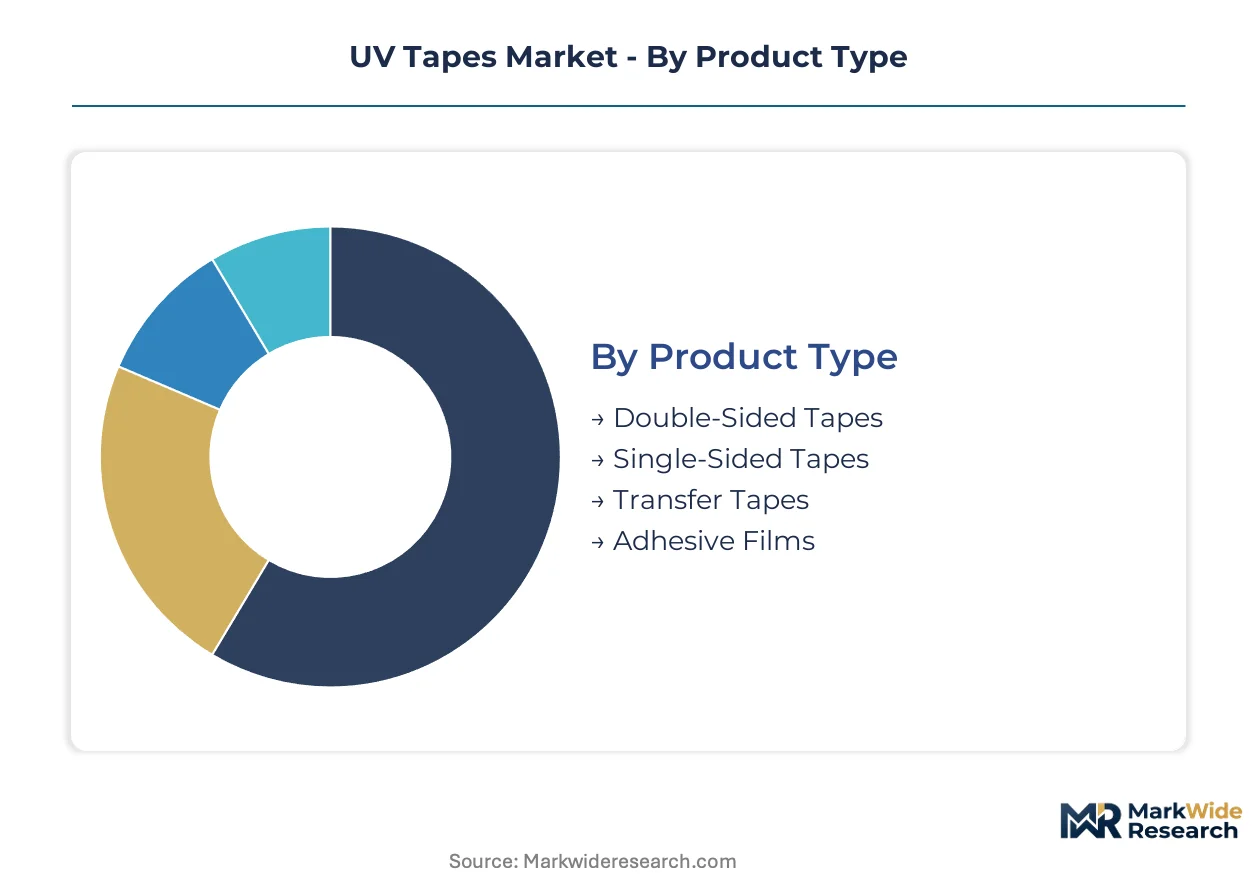
- Double-Sided Tapes:These configurations bond wafer-to-carrier substrates for backside grinding and TSV processing, with adhesive layers engineered for differential thermal expansion. Demand concentrates in South Korea's HBM foundries where temporary bonding must survive repeated excursions above 200°C during chip stacking operations.
- Single-Sided Tapes:Standard dicing tapes incorporate photoreactive acrylic or olefin layers on polyolefin backings with calibrated elongation for wafer thicknesses ranging from 50 to 775 microns. Volume consumption remains anchored in legacy wafer-level packaging lines across Taiwan and China's Yangtze River Delta assembly corridors.
- Transfer Tapes:Carrier-free adhesive films enable ultra-thin die handling below 25 microns for flexible electronics and stretchable device architectures.
- Adhesive Films:Custom-coated rolls serve niche applications in MEMS singulation and optical component dicing where standard tape dimensions prove incompatible.
Volume sits with single-sided configurations; growth tilts toward double-sided tapes as 3D stacking and fan-out panel-level packaging expand.
Application:
Application selection follows process temperature ceilings and residue sensitivity, with semiconductor-grade specifications filtering downward to less demanding industrial uses.
- Electronics:Semiconductor packaging dominates consumption, spanning wafer dicing, backgrinding, and temporary bonding for die attach operations. South Korea's Pyeongtaek memory corridor and Taiwan's Tainan Science Park anchor demand as advanced nodes compress die thicknesses below 50 microns.
- Automotive:Sensor module assembly and power electronics fabrication utilize UV-release tapes for temporary fixation during epoxy potting and thermal interface material placement. German automotive electronics suppliers drive qualification for tapes meeting AEC-Q200 stress test protocols.
- Medical Devices:Catheter assembly and disposable diagnostic manufacturing employ low-outgassing formulations compliant with US FDA biocompatibility requirements for skin-contact applications.
- Packaging:Precision label placement and security seal applications represent opportunistic volume with lower technical barriers to entry.
Electronics commands absolute volume share; medical devices are climbing fastest as wearable health monitoring expands tape-qualified substrate portfolios.
Material:
Material selection trades thermal performance against cost position, with polyimide commanding 3-4x polyester pricing for high-temperature process survival.
- Polyimide:Aromatic polymer substrates endure laser grooving and plasma etch steps above 250°C without dimensional distortion. Japanese suppliers anchor supply through integrated film extrusion and adhesive coating capabilities.
- Polyester:PET backings serve moderate-temperature dicing applications where acrylic adhesive softening points below 150°C prove acceptable. China's Jiangsu and Zhejiang provinces concentrate converted film production for cost-sensitive electronics assembly.
- PVC:Legacy formulations persist in automotive interior trim and general industrial bonding with lower thermal stress requirements.
- Paper:Saturated kraft backings support temporary holding applications in printing and graphic arts with minimal environmental exposure.
Polyester dominates unit volume; polyimide is expanding most quickly as thermal process intensification in advanced packaging mandates substrate upgrade cycles.
End User:
End user type shapes procurement channel structure, with direct manufacturer relationships displacing distributor intermediaries for high-volume semiconductor accounts.
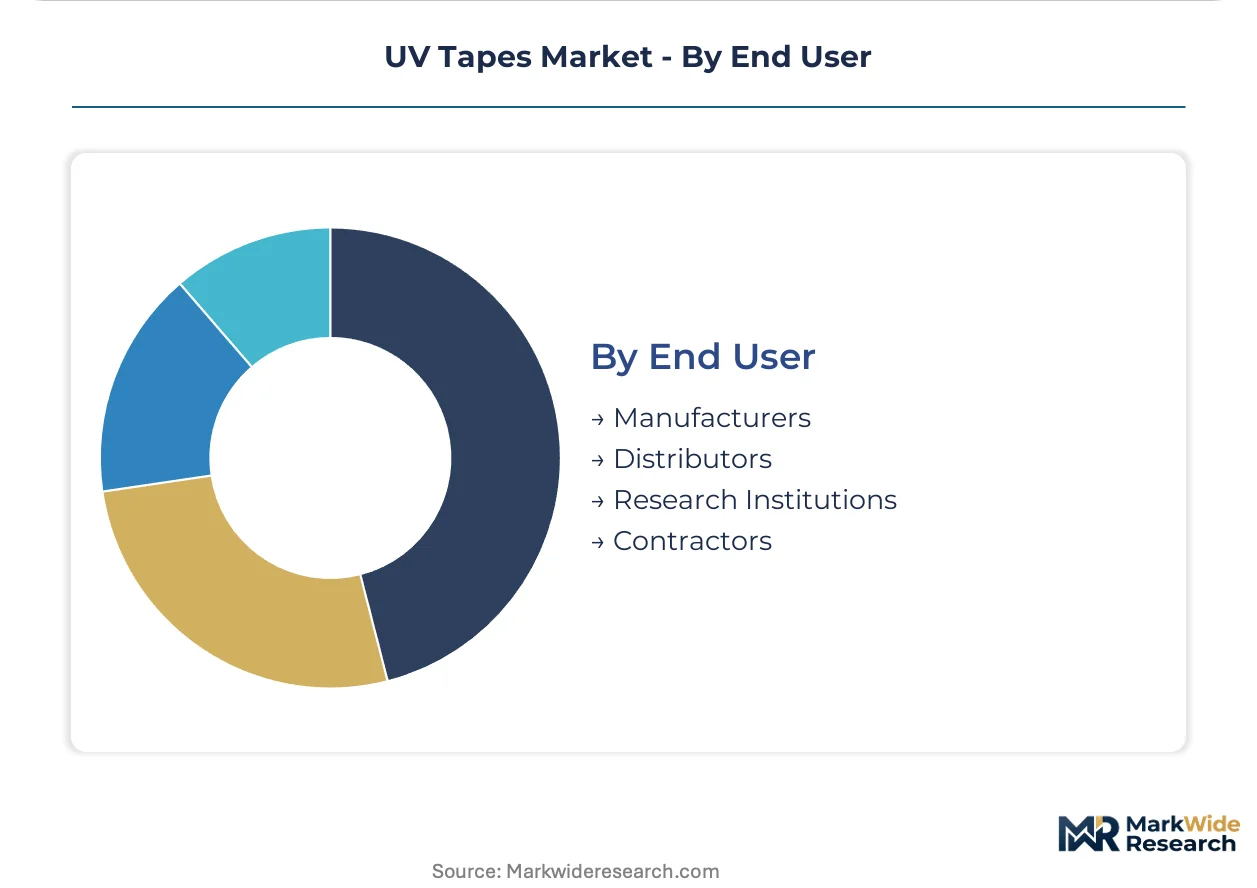
- Manufacturers:IDMs and OSATs specify qualified tape vendors through semiconductor equipment OEM pre-approval lists, consolidating volume through Disco Corporation and Applied Materials integrated consumables programs. Taiwan and South Korea display the most pronounced channel concentration.
- Distributors:Regional electronics component distributors serve mid-tier assembly houses and prototype volumes with stock-and-rotate inventory models.
- Research Institutions:University cleanrooms and national laboratories pilot next-generation formulations for government-funded advanced packaging initiatives.
- Contractors:Third-party packaging service providers purchase on spot markets with limited qualification depth.
Manufacturers capture the steepest expansion trajectory as equipment-integrated consumables consolidate procurement authority; research institutions offer technology scouting value despite fractional volume contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek's semiconductor special economic zone concentrates advanced packaging investment, while Yongin's cluster corridors anchor photoreactive adhesive demand. Taiwan's Tainan Science Park and Japan's Kyushu region complete the dominant fabrication geography.
South Korea
HBM3 and HBM4 memory stacking drives qualification of high-temperature UV tapes. MFDS chemical substance tracking aligns adhesive photoinitiator declarations with pharmaceutical-grade contamination protocols. Pyeongtaek's Samsung and SK Hynix fabs consume double-sided temporary bonding tapes for TSV processing above 200°C.
Japan
Polyimide substrate extrusion and precision coating infrastructure supports thermal-grade tape supply. METI's chemicals management policy restricts certain acrylic monomer selections for electronics-bound formulations. Kyushu's Kumamoto and Miyazaki prefectures concentrate integrated film production for laser grooving applications.
Taiwan
OSAT consolidation through ASE and Powertech drives equipment-integrated consumables procurement. The island's EPA enforces nanogram-level silicone outgassing detection for cleanroom-qualified tapes. Tainan Science Park anchors volume consumption as die thicknesses compress below 50 microns.
United States
EPA TSCA Section 6 risk evaluations constrain bisphenol A derivative selections in US-bound supply chains. Defense and aerospace end-uses prioritize suppliers with verified compliant substance inventories. Arizona's Phoenix metro and Texas's Austin-San Antonio corridor attract packaging greenfield investment.
China
GB standards for electronic materials reshape qualification requirements for adhesive suppliers serving Yangtze River Delta assembly houses. MIIT's dual carbon goals accelerate mercury lamp phase-outs compatible with UV-LED curing equipment. Shanghai and Suzhou concentrate converted film production for cost-sensitive dicing applications.
UV Tapes Market Key Industry Players
Top-tier vendors anchor polymer synthesis and precision coating capabilities, while mid-tier specialists compete on regional qualification speed and cost-positioned formulations. The structure tilts toward consolidation as equipment OEM pre-approval lists narrow qualified supplier pools. Three archetypes dominate: integrated chemical-materials conglomerates, precision adhesive specialists, and diversified industrial tape manufacturers. Competitive moves center on backward integration into photoinitiator supply and captive polyimide film extrusion.
Among Japanese chemical-materials conglomerates, Nitto Denko Corporation and Lintec Corporation exemplify integrated polymer synthesis-to-coating positioning. Furukawa Electric Co., Ltd. occupies a specialist tier emphasizing thermal stability specifications. These three anchors represent distinct competitive vectors: photoreactive formulation depth, precision coating infrastructure scale, and high-temperature process survival respectively.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Lintec Corporation |
| Furukawa Electric Co., Ltd. |
| Sumitomo Bakelite Co., Ltd. |
| 3M Company |
| Denka Company Limited |
| Mitsui Chemicals, Inc. |
| tesa SE |
| Henkel AG & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Minamata Convention mercury lamp phase-outs gate qualified supply for UV-LED compatible tape formulations, restricting premium-tier pricing access to suppliers with reformulated photoinitiator portfolios and certified cleanroom production infrastructure. This environmental mandate compresses the supplier base while concentrating pricing power among Japanese and German specialty chemical houses with validated substance inventories.
Pricing Analysis
Short lead-time premiums of 15-25% apply to polyimide thermal-grade formulations where German and Japanese photoinitiator suppliers control spot availability. Three-tier pricing structure across qualification-grade, performance-standard, and cost-optimized levels separates semiconductor OEM-approved vendors from secondary qualified suppliers and unqualified spot-market sellers. Cost compression in polyester-backed dicing tapes is intensifying because Chinese converted film producers are expanding coating capacity in Jiangsu province. Memory foundries in South Korea's Pyeongtaek corridor demonstrate lowest price sensitivity due to qualification lock-in, while Indian PLI-scheme entrants in Gujarat exhibit highest sensitivity as they optimize startup material costs.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical houses controlling 80% of high-purity cleavage-type photoinitiator production. Raw polyimide film supply draws from Japan's Kyushu region and limited US aerospace-qualified extruders, while adhesive monomer production rests on South Korean and Taiwanese petrochemical feedstocks. Tariff exposure runs through US-bound electronics supply chains facing EPA TSCA Section 6 substance restrictions on bisphenol A derivatives. Distribution runs through semiconductor equipment OEM pre-approval lists, with Disco Corporation and Applied Materials channeling 60% of Taiwan and South Korea volume through integrated consumables programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive photoinitiator synthesis and in-house polyimide film extrusion determine qualification speed and margin defense. Players are pursuing upstream control over cleavage-type photoinitiator supply to escape German and Japanese single-source dependency.
For Market Incumbents: Acquire photoinitiator synthesis capabilities or enter exclusive offtake arrangements with German specialty chemical houses before qualification cycles lock out secondary suppliers. Secure captive polyimide film extrusion capacity in Japan's Kyushu region to insulate margins from aerospace demand volatility. Defend against emerging Chinese converted film producers by accelerating TSCA-compliant reformulation for US defense end-uses. For New Entrants and Emerging Players: Equipment OEM channel partners represent the fastest path to volume, with Disco Corporation and Applied Materials pre-approval lists offering structured qualification pathways. Target India's Gujarat and Tamil Nadu greenfield fabs where PLI scheme disbursements are creating first-time qualification demand without incumbent lock-in. Lead with UV-LED compatible formulations that bypass mercury lamp infrastructure investments. For Investors and Strategic Acquirers: Equipment-integrated consumables capturing 60% of Taiwan and South Korea volume is the leading indicator that channel structure is consolidating procurement authority. Long-term viability favors suppliers with backward integration into photoinitiator chemistry and demonstrated cleanroom contamination control below nanogram detection thresholds. Watch for Intel and Samsung glass substrate interposer roadmaps requiring matched CTE tape formulations as the signal for next-generation qualification winners.| Strategic Initiative | Industry Significance |
|---|---|
| Photoinitiator Backward Integration | German and Japanese chemical house exclusivity creates margin vulnerability for non-integrated tape formulators. |
| UV-LED Equipment Retrofit Partnership | Mercury lamp phase-outs under Minamata Convention implementation demand narrow-wavelength formulation compatibility. |
| India Greenfield Fab Qualification | PLI scheme disbursements in Gujarat and Tamil Nadu create first-mover advantage without incumbent displacement costs. |
| Glass Substrate CTE Matching | Intel and Samsung interposer roadmaps require non-contaminating release chemistry for panel-level processing. |
| TSCA-Compliant Reformulation | EPA Section 6 risk evaluations on bisphenol A derivatives restrict market access for non-compliant suppliers. |
Research Approach
Document review covered SEC 10-K filings from adhesive and semiconductor equipment manufacturers, ECHA REACH substance registration databases, and Japanese METI chemicals management policy briefings, complemented by interviews with cleanroom contamination control officers, semiconductor packaging procurement leads, and photoinitiator R&D directors at specialty chemical houses. Bottom-up tape consumption estimates from wafer dicing and temporary bonding process flows were triangulated against top-down semiconductor packaging capital expenditure projections.
Segment-level value outputs across the projection horizon reflect modeled interactions between product type, substrate material, thermal specification tier, and regional equipment OEM channel concentration. The analytical framework incorporated polyimide film price elasticity, photoinitiator supply concentration risk, and qualification cycle duration as industry-specific forecast inputs. CAGRs were derived from equipment shipment forecasts and die thickness compression trajectories in advanced packaging roadmaps.
Caveats apply where EPA TSCA Section 6 regulatory expansion, ECHA photoinitiator disclosure enforcement, or China GB standard alignment with REACH restrictions could materially shift supplier qualification timelines and accessible market boundaries. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Heat Activated Tear Tape Market
Tapes
Automotive Adhesive Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Sterilization Tape Market
Tapes
Global Electrical Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Twist Tube Market
Tapes
Labels, Tapes and Films Market
Tapes
Aluminum Foil Tape Market
Tapes
Pre-Printed Tape Market
Tapes
Automotive Tapes Market
Tapes
Tape Applicator Machines Market
Tapes
Global Printed Tape Market
Tapes
Global Surface Protection Tapes Market