
 ESD Tapes and Labels Market | 2026-2036
ESD Tapes and Labels Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Tapes and Labels Market Foresight
Aftermarket ESD audit and compliance certification revenue is rewriting how suppliers capture lifetime value from electronics manufacturers. 3M Company leverages its materials science portfolio to dominate high-performance polyimide tape formulations for wafer-level packaging. Henkel anchors European demand through specialized adhesive platforms that bond reliably under cleanroom conditions. Tesa SE competes aggressively on automotive assembly line specifications where static control intersects with process automation.
ESD tapes and labels are engineered static-dissipative or conductive adhesive products, typically surface resistivity-rated between 10^6 and 10^9 ohms per square, designed to prevent electrostatic discharge damage to sensitive electronic components during handling, transport, and assembly operations. Polyester-based ESD labels currently occupy the largest product volume share due to cost-efficiency and broad compatibility with thermal transfer printing systems. Semiconductor packaging applications represent the fastest-growing demand segment as advanced node chips require stricter charge control throughout die attach, wire bonding, and final test workflows. Aerospace end users sustain premium pricing for polyimide material grades that withstand extreme temperature cycling during satellite component preparation.
IEC 61340 and ANSI/ESD S20.20 frameworks mandate documented static control programs, directly shaping procurement specifications for ESD consumables across certified electronics manufacturing facilities. China's GB standards for electrostatic protection, administered by SAMR, create localized compliance barriers that favor domestic label converters with in-country testing capabilities. FDA and ISO 13485 requirements for medical device manufacturing further segment the market, as sterile packaging applications demand ESD materials with validated biocompatibility profiles. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's chemical restriction roadmaps simultaneously pressure adhesive formulations and open substitution opportunities for bio-based static-dissipative polymers.
Market Dynamics
IEC 61340 surface resistivity requirements are tightening faster than material science cycles can adapt, forcing converters to reformulate adhesive platforms while semiconductor packaging nodes advance below 5nm. This regulatory-technology squeeze is compressing supplier certification timelines and fragmenting procurement specifications across East Asian manufacturing clusters.
Growth Catalysts
- Semiconductor packaging node shrinkage:Advanced die attach and wire bonding workflows below 7nm require stricter charge control, pulling ESD tape consumption upward in Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek semiconductor corridor.
- EU Green Deal chemical restriction roadmaps:REACH substance evaluations are accelerating substitution demand for bio-based static-dissipative polymers, opening formulation windows for adhesive suppliers with validated sustainable chemistry pipelines.
- GB standards enforcement in China:SAMR-administered electrostatic protection mandates are expanding certified facility coverage across the Yangtze River Delta, creating compliance-driven replacement cycles for legacy label inventories.
Market Restraints
- Polyimide resin supply concentration:High-performance film substrates depend on captive production in Japan and limited merchant supply, exposing converters to input cost volatility when electronics demand cycles spike.
- Cleanroom-grade adhesive technical limitation:Outgassing specifications below 100ppm total mass loss remain difficult to achieve without silicone platforms that compromise static-dissipative performance in high-humidity environments.
- China domestic testing capability requirements:GB standard compliance verification must occur in-country, creating regulatory friction for foreign label converters without established Chinese laboratory partnerships or SAMR-recognized certification pathways.
Strategic Opportunities
- India electronics manufacturing expansion:PLI scheme incentives for semiconductor assembly and mobile device production are building cleanroom infrastructure in Gujarat and Tamil Nadu where ESD program penetration remains below East Asian benchmarks.
- Automotive battery module assembly:Lithium-ion cell handling and pack integration workflows are adopting semiconductor-grade static control protocols, extending ESD tape specifications into EV manufacturing lines previously served by general industrial adhesives.
- Medical device sterile packaging convergence:FDA and ISO 13485 requirements are merging with ANSI/ESD S20.20 frameworks, creating dual-certified material demand for cardiovascular implant and diagnostic instrument manufacturers in Minnesota and Massachusetts clusters.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in polymer rheology, surface resistivity engineering, and cleanroom contamination control command premium compensation and extended recruitment timelines in Taiwan and Germany.
- Multi-standard certification complexity:Simultaneous IEC 61340, ANSI/ESD S20.20, and customer-specific OEM qualification protocols extend product launch cycles to 18-24 months, compressing revenue realization windows for new adhesive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Tapes and Labels Market |
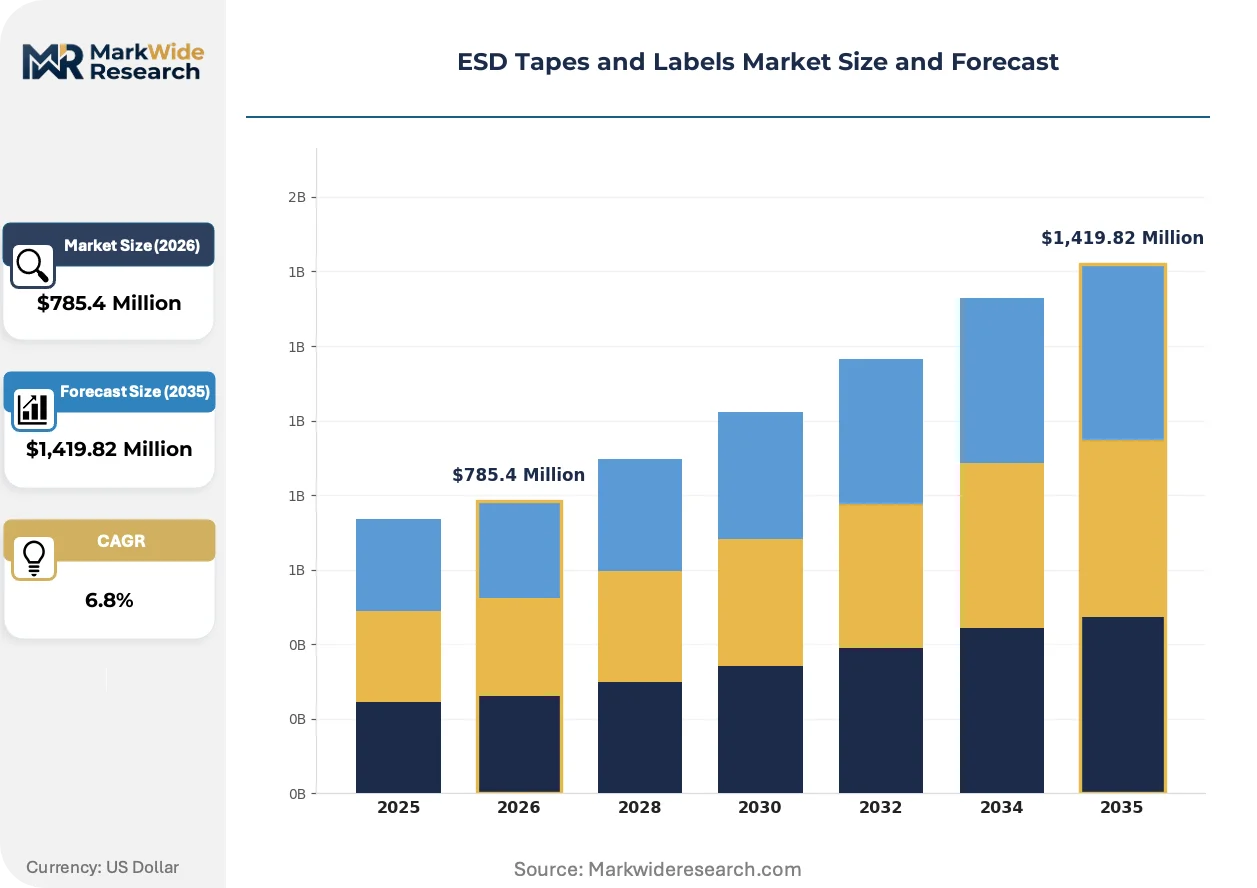
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,419.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ESD Labels, ESD Tapes, ESD Markers, ESD Wrist Straps Application: Electronics Manufacturing, Semiconductor Packaging, PCB Protection, Automotive Assembly Material: Polyester, Polyimide, Vinyl, Paper End User: Electronics, Aerospace, Defense, Medical Devices |
| Companies Covered | Henkel, Intertape Polymer Group, 3M Company, Teraoka Seisakusho, Tesa SE, Avery Dennison Corporation, Sealed Air Corporation, Edco Supply Corporation, Desco Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Tapes and Labels Market Shifts & Advancements
Digital traceability systems are penetrating ESD consumable supply chains, converting static control materials from passive commodities into data-generating infrastructure. This transformation is reshaping how electronics manufacturers audit compliance and how suppliers capture recurring revenue.
Embedded RFID and printed sensor technologies are digitizing ESD tape and label functionality beyond simple surface resistivity marking. Semiconductor foundries in Taiwan and memory manufacturers in South Korea are piloting intelligent packaging that logs environmental exposure and handling events throughout die transport. This capability is digitizing quality assurance workflows and compressing root-cause analysis timelines when electrostatic damage incidents occur.
REACH authorization procedures and EU Green Deal chemical restriction roadmaps are forcing adhesive reformulation investments across European converter operations. Substances of very high concern in traditional static-dissipative chemistries face sunset dates that overlap with semiconductor customer qualification windows, creating simultaneous compliance and supply continuity pressures. German automotive electronics suppliers are responding fastest, pushing their tape vendors toward bio-based polymer platforms with equivalent surface resistivity performance.
Consolidated procurement through electronics manufacturing services providers is concentrating ESD consumable purchasing decisions into fewer hands across the supply chain. Foxconn, Pegatron, and similar contract manufacturers are unbundling component-level sourcing from facility-level static control programs, creating direct supplier relationships that bypass traditional distributor networks. This pattern is most visible in Mexico and Vietnam, where EMS capacity expansion is outpacing local distributor infrastructure development.
ESD Tapes and Labels Market Segmentation
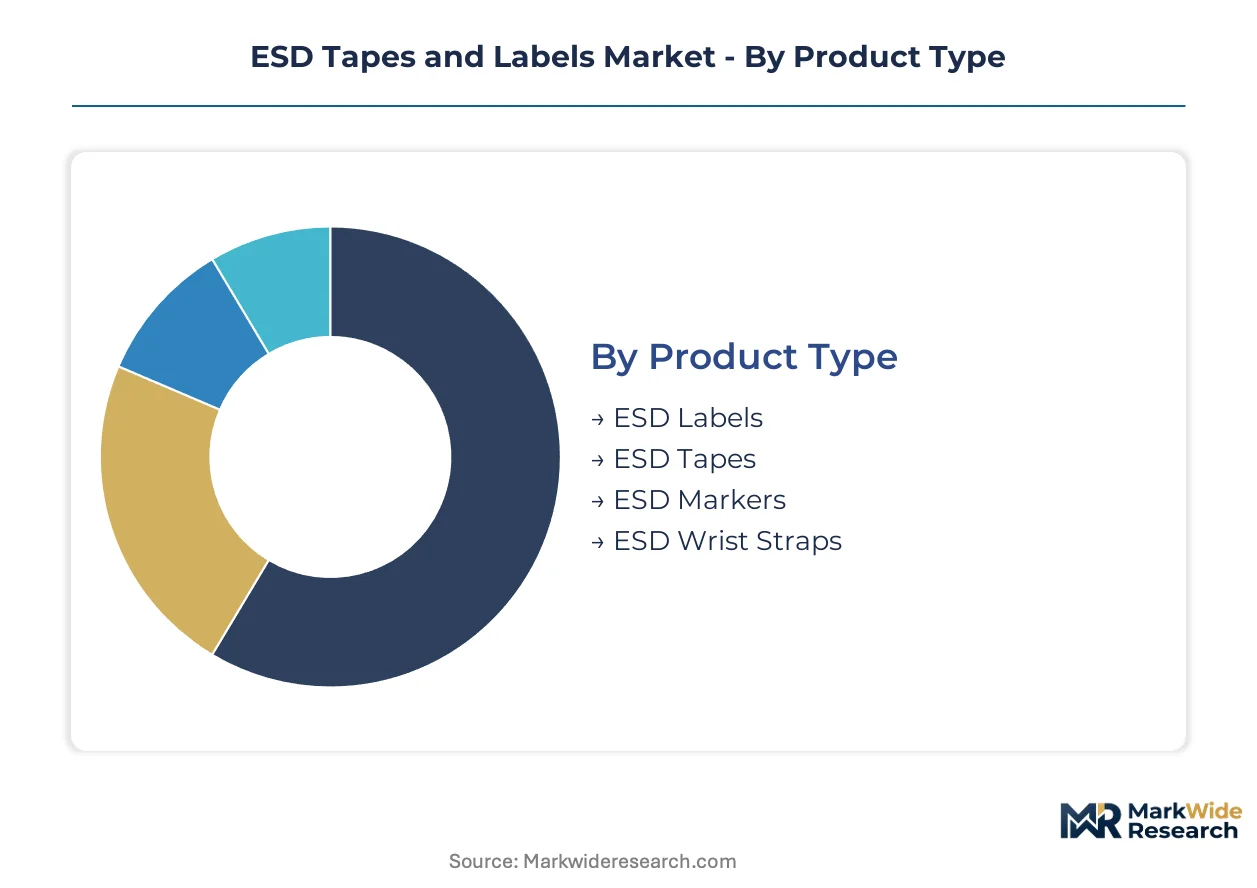
ESD consumables fragment across performance tiers that trade off surface resistivity precision against unit economics. Procurement patterns diverge sharply between semiconductor cleanrooms requiring IEC 61340-certified materials and general electronics assembly tolerating broader specification ranges.
Product Type:
Mature formats dominate procurement volumes while emerging categories digitize functionality beyond passive static control.
- ESD Labels:Polyester substrates with thermal-transfer printable topcoats deliver surface resistivity between 10^6 and 10^9 ohms per square. China's Yangtze River Delta electronics corridor consumes the majority of volume as GB standard enforcement accelerates certified facility replacement cycles.
- ESD Tapes:Pressure-sensitive adhesive platforms bond under cleanroom conditions with documented outgassing below 100ppm total mass loss. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek semiconductor corridor pull consumption upward as die attach workflows advance below 7nm nodes.
- ESD Markers:Static-dissipative ink formulations enable direct component marking without secondary label application.
- ESD Wrist Straps:Personnel grounding devices with coiled cord assemblies complete workstation-level static control programs.
ESD Labels handle the majority of throughput; ESD Tapes are expanding most quickly on share as semiconductor packaging node shrinkage intensifies.
Application:
Cost tiers separate commodity-grade assembly protection from premium cleanroom specifications that command 3-4x unit pricing.
- Electronics Manufacturing:General assembly workflows utilize polyester-based labels for component tracking and static protection. Foxconn and Pegatron consolidate procurement decisions across Mexico and Vietnam capacity expansion, bypassing traditional distributor networks.
- Semiconductor Packaging:Wafer-level and die-level handling demands polyimide substrates with extreme temperature cycling resistance. Advanced node chips below 5nm require stricter charge control throughout wire bonding and final test workflows in Taiwan and South Korea.
- PCB Protection:Board-level shielding during transport and storage prevents latent defect accumulation from electrostatic discharge events.
- Automotive Assembly:Lithium-ion battery module integration adopts semiconductor-grade static control protocols previously reserved for chip manufacturing.
Electronics Manufacturing anchors volume procurement; Semiconductor Packaging shows the steepest expansion trajectory as node advancement accelerates material specification tightening.
Material:
Supply concentration in Japanese polyimide resin production creates input cost volatility that propagates through converter pricing.
- Polyester:Cost-efficient films compatible with broad thermal transfer printing systems dominate label volume. Broad compatibility with existing print infrastructure sustains procurement preference across East Asian manufacturing clusters.
- Polyimide:High-temperature stability enables satellite component preparation and aerospace applications with extreme thermal cycling requirements. Captive production in Japan and limited merchant supply expose converters to demand spike volatility.
- Vinyl:Flexible substrates conform to irregular surfaces in general industrial static control applications.
- Paper:Disposable labels serve short-duration handling operations where durability requirements remain minimal.
Polyester commands the largest production throughput; Polyimide climbs the fastest as aerospace and advanced semiconductor applications multiply.
End User:
Customer type determines certification burden, with medical and aerospace segments demanding dual-standard compliance that extends qualification timelines.
- Electronics:Contract manufacturers and OEMs drive baseline demand across consumer device and industrial control production. EMS consolidation in Mexico and Vietnam concentrates purchasing decisions into fewer supplier relationships.
- Aerospace:Satellite component preparation sustains premium pricing for temperature-resistant material grades. Extreme thermal cycling during launch vehicle integration mandates polyimide performance specifications.
- Defense:Military electronics procurement emphasizes supply chain security and domestic converter qualification.
- Medical Devices:FDA and ISO 13485 requirements merge with ANSI/ESD S20.20 frameworks for cardiovascular implant and diagnostic instrument manufacturing in Minnesota and Massachusetts clusters.
Electronics generates the dominant demand volume; Medical Devices is gaining share fastest as sterile packaging convergence creates dual-certified material requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb volume at compressed margins while aerospace and medical segments in Western markets tolerate substantial premiums for certified materials. Price elasticity diverges sharply between commodity electronics assembly and cleanroom-grade specifications.
China
GB standards administered by SAMR are expanding certified facility coverage across the Yangtze River Delta electronics corridor. Dual carbon goals and MEE enforcement are pressuring adhesive reformulation timelines for domestic converters. Shanghai and Suzhou manufacturing clusters are replacing legacy label inventories at accelerated rates.
United States
Medical device manufacturers in Minnesota and Massachusetts clusters are driving dual-certified material demand under FDA and ISO 13485 frameworks. OSHA workplace safety guidelines intersect with ANSI/ESD S20.20 protocols in electronics assembly facilities. The Pacific Northwest semiconductor expansion and Texas instrument manufacturing sustain premium polyimide consumption.
Germany
REACH authorization procedures and EU Green Deal chemical restrictions are accelerating bio-based polymer substitution among automotive electronics suppliers. ECHA substance evaluations are compressing qualification windows for traditional static-dissipative chemistries. Bavarian and Baden-Württemberg automotive component plants are pushing tape vendors toward sustainable formulation platforms.
South Korea
Pyeongtaek semiconductor corridor facilities are pulling ESD tape consumption upward as die attach workflows advance below 7nm nodes. MFDS medical device regulations are beginning to overlap with electrostatic protection mandates in diagnostic instrument manufacturing. Seoul Capital Area cleanroom infrastructure is expanding faster than qualified converter capacity.
Japan
Captive polyimide resin production in Japanese chemical complexes creates supply concentration that propagates cost volatility through converter pricing. METI industrial standards for electrostatic protection are tightening in parallel with IEC 61340 revisions. Kyushu and Chubu semiconductor material clusters are absorbing the majority of high-performance film substrate output.
ESD Tapes and Labels Market Competitive Landscape
Diversified materials conglomerates and specialized adhesive converters split the market into distinct capability tiers. Consolidation pressure concentrates around formulation expertise and cleanroom certification velocity rather than manufacturing scale alone. Three archetypes dominate: integrated materials science platforms with captive polymer supply, precision adhesive specialists with OEM qualification depth, and regional converters with localized testing capabilities. Competitive moves center on backward integration into resin production and strategic partnerships with semiconductor foundries for co-development programs.
Within the integrated materials tier, 3M Company and Henkel occupy positions that exemplify divergent geographic anchoring—American and German respectively—while converging on high-performance formulation dominance. Tesa SE represents the specialized adhesive archetype with deep automotive electronics penetration. These three companies illustrate how strategic positioning around either materials breadth or application depth shapes competitive viability as semiconductor packaging requirements tighten.
| Leading Market Players |
|---|
| Henkel |
| Intertape Polymer Group |
| 3M Company |
| Teraoka Seisakusho |
| Tesa SE |
| Avery Dennison Corporation |
| Sealed Air Corporation |
| Edco Supply Corporation |
| Desco Industries |
| Others |
Supply & Pricing Matrix
Japanese polyimide resin production concentrates in captive chemical complexes, anchoring margin pools in high-performance film substrates while polyester label converters compete on throughput at thinner spreads. Electronics manufacturing services providers exploit this bifurcation to extract pricing concessions from commodity-grade suppliers while paying premiums for semiconductor-certified materials.
Pricing Analysis
Aftermarket ESD audit and compliance certification revenue drives lifetime value capture beyond unit tape and label sales. Three-tier pricing structure across IEC 61340-certified premium, ANSI/ESD S20.20-standard, and general industrial economy levels separates semiconductor cleanroom specifications from automotive assembly grades. Cost compression in polyester label tiers intensifies as China's SAMR enforcement accelerates certified facility replacement cycles, with contract manufacturers in Mexico and Vietnam exhibiting highest price sensitivity while aerospace end users in Japan and Germany tolerate substantial premiums for polyimide temperature cycling performance.
Supply Chain Analysis
Polyimide resin feedstock draws from captive production in Japan and limited merchant supply in South Korea and the United States, creating input cost volatility that propagates through converter pricing during electronics demand spikes. Static-dissipative adhesive formulations rest on specialty polymer additives, silicone platforms, and bio-based polymer substitutes facing REACH sunset timelines. Single-source vulnerability in Japanese high-performance film substrates exposes downstream converters to allocation risk when Taiwan and South Korea semiconductor foundries surge orders. Distribution runs through direct supplier relationships with Foxconn, Pegatron, and similar EMS providers that bypass traditional distributor networks in Mexico and Vietnam expansion corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through electronics manufacturing services consolidation, with Foxconn and Pegatron unbundling facility-level static control procurement from component sourcing to capture direct supplier pricing leverage.
For Market Incumbents: Pre-empt margin erosion in polyester label tiers by accelerating backward integration into specialty polymer additive production and securing SAMR-recognized laboratory partnerships in China before GB standard enforcement tightens further. Defend high-performance polyimide positioning through co-development programs with Taiwan foundries advancing below 5nm packaging nodes, as semiconductor-grade certification velocity becomes the primary competitive moat against emerging adhesive specialists. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Tamil Nadu cleanroom infrastructure buildout under PLI scheme incentives, where ESD program penetration remains below East Asian benchmarks and qualified converter capacity lags demand growth. Target automotive battery module assembly workflows adopting semiconductor-grade static control protocols, leveraging bio-based polymer formulation pipelines to meet EU Green Deal chemical restriction timelines ahead of incumbent reformulation cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision adhesive specialists possessing deep OEM qualification depth but limited geographic diversification beyond European automotive electronics clusters. Long-term viability over the next decade hinges on certification velocity and cleanroom-grade outgassing specification mastery rather than manufacturing scale alone. Watch for inflection when semiconductor foundries begin mandating embedded RFID traceability in ESD consumable specifications, digitizing quality assurance workflows and compressing root-cause analysis timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Resin Production | Captive supply of high-performance film substrates insulates converters from Japanese chemical complex allocation volatility. |
| SAMR-Recognized Laboratory Partnership | In-country GB standard compliance verification unlocks Yangtze River Delta replacement cycle participation for foreign label converters. |
| Bio-Based Polymer Formulation Pipeline | Validated sustainable chemistry platforms capture REACH substitution demand from Bavarian automotive electronics suppliers. |
| Embedded RFID Traceability Integration | Intelligent packaging capabilities digitize Taiwan foundry quality assurance workflows beyond passive surface resistivity marking. |
| Co-Development Program with Semiconductor Foundries | Direct collaboration on below 5nm packaging node requirements accelerates adhesive platform qualification velocity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ESD program managers at semiconductor foundries, cleanroom procurement leads at electronics manufacturing services providers, adhesive formulation chemists at converter operations, and static control auditors at certification bodies. Secondary validation drew from IEC 61340 standard revision documentation, SAMR GB standard enforcement notices, ECHA REACH substance evaluation timelines, SEC 10-K filings from diversified materials conglomerates, and customs trade data for polyimide film substrate flows. Bottom-up segmentation modeling triangulated against top-down market sizing from electronics manufacturing value chain analysis.
Calibration against historical semiconductor packaging node advancement patterns and ESD consumable intensity metrics anchored projections across the analysis window. Segmentation dimensions modeled include product type, application workflow, material substrate, end-user industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating semiconductor capital expenditure cycles and cleanroom infrastructure buildout timelines. Industry-specific forecast inputs included die attach workflow automation rates and automotive battery module assembly static control protocol adoption curves.
Stress conditions across polyimide resin supply disruption, REACH authorization acceleration, and EMS procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IEC 61340 revision implementation timing and SAMR enforcement intensity. Semiconductor node shrinkage acceleration or bio-based polymer performance shortfalls could revise trajectory. Cross-checking against SEMI equipment spending forecasts and foundry capacity utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Umbilical Tapes Market
Tapes
Nylon Cable Ties Market
Tapes
Thread Seal Tape Market
Tapes
Hydrocolloid Tapes Market
Tapes
Pre-Printed Tape Market
Tapes
Cable Wrapping Tapes Market
Tapes
Release Tape Market
Tapes
Tabbing Tapes Market
Tapes
Filmic Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Twist Tube Market
Tapes
High Bond Tape Market
Tapes
Global Printed Tape Market
Tapes
Holographic Tear Tape Market