
 High Bond Tape Market | 2026-2036
High Bond Tape Market Size, Share, and Industry Trends Forecast 2026-2036
High Bond Tape Market Insights
Aftermarket bonding solutions revenue is tilting toward permanent structural assembly applications as OEMs reduce welded joints. 3M Company leverages its acrylic adhesive platform to dominate aerospace and automotive OEM specifications. tesa SE anchors its position through captive film manufacturing and precision coating lines in Europe. Nitto Denko Corporation specializes in ultra-thin transfer tapes for electronics miniaturization in East Asian consumer device supply chains.
High bond tape denotes pressure-sensitive adhesive constructions engineered for structural load-bearing applications, typically achieving shear strengths above 20 N/cm² through viscoelastic acrylic or rubber-based chemistries cured via UV or thermal crosslinking processes. These products permanently bond dissimilar substrates in applications where welding, riveting, or mechanical fastening introduces weight, corrosion risk, or stress concentration. Double-sided foam tapes command the widest application footprint across automotive trim and glazing assemblies, while adhesive transfer tapes represent the fastest-expanding category driven by electronics lamination and display bonding. Acrylic formulations sustain premium pricing against rubber and PVC alternatives due to superior thermal stability and environmental aging resistance.
FDA indirect food contact standards, EPA VOC emission limits under NESHAP, and REACH substance restrictions collectively shape adhesive formulation roadmaps and raw material qualification protocols. OSHA workplace exposure thresholds for solvent-based tape manufacturing further constrain process chemistry choices and capital allocation decisions. Stakeholders must monitor evolving automotive crashworthiness certification requirements and electronics recyclability mandates as these will determine which adhesive platforms retain qualification status across downstream value chains.
Market Dynamics
Automotive lightweighting mandates are structurally displacing mechanical fasteners with adhesive bonding systems, compressing qualification timelines and concentrating specification power among tape suppliers with crash-test validation capabilities.
Growth Catalysts
- REACH solvent-free mandates:European ECHA substance restrictions are accelerating acrylic formulation transitions across German automotive supply chains.
- Electronics miniaturization:Ultra-thin transfer tape demand is surging in East Asian display lamination and semiconductor packaging applications.
- Stuttgart supplier corridor concentration:Germany's automotive engineering density is creating specification pull-through effects for high bond tape assemblies.
Market Restraints
- Petrochemical input volatility:Acrylic monomer and synthetic rubber feedstock costs fluctuate with crude oil derivatives, compressing formulation margins unpredictably.
- Regional supply concentration:Precision coating capacity clusters in Germany and Japan, creating geographic vulnerability to logistics disruptions or trade friction.
- Welding substitution limits:Structural steel applications in heavy commercial vehicles retain mechanical fastening for crash-load scenarios, capping adhesive penetration.
Strategic Opportunities
- India automotive assembly:Domestic OEM capacity expansion and PLI scheme incentives are opening specification opportunities for localized tape production.
- Recyclability-driven redesign:EU battery passport and end-of-life vehicle directives are creating demand for debondable adhesive platforms in electric vehicle battery packs.
- UV-LED curing convergence:Energy-efficient crosslinking technology is enabling inline tape bonding integration with automated assembly lines.
Industry Challenges
- Crashworthiness certification timelines:OEM validation protocols for structural adhesive joints require 18-36 month test cycles, delaying revenue recognition.
- Adhesive chemist talent scarcity:Formulation expertise in viscoelastic polymer science concentrates among retiring specialists in European and Japanese supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Bond Tape Market |
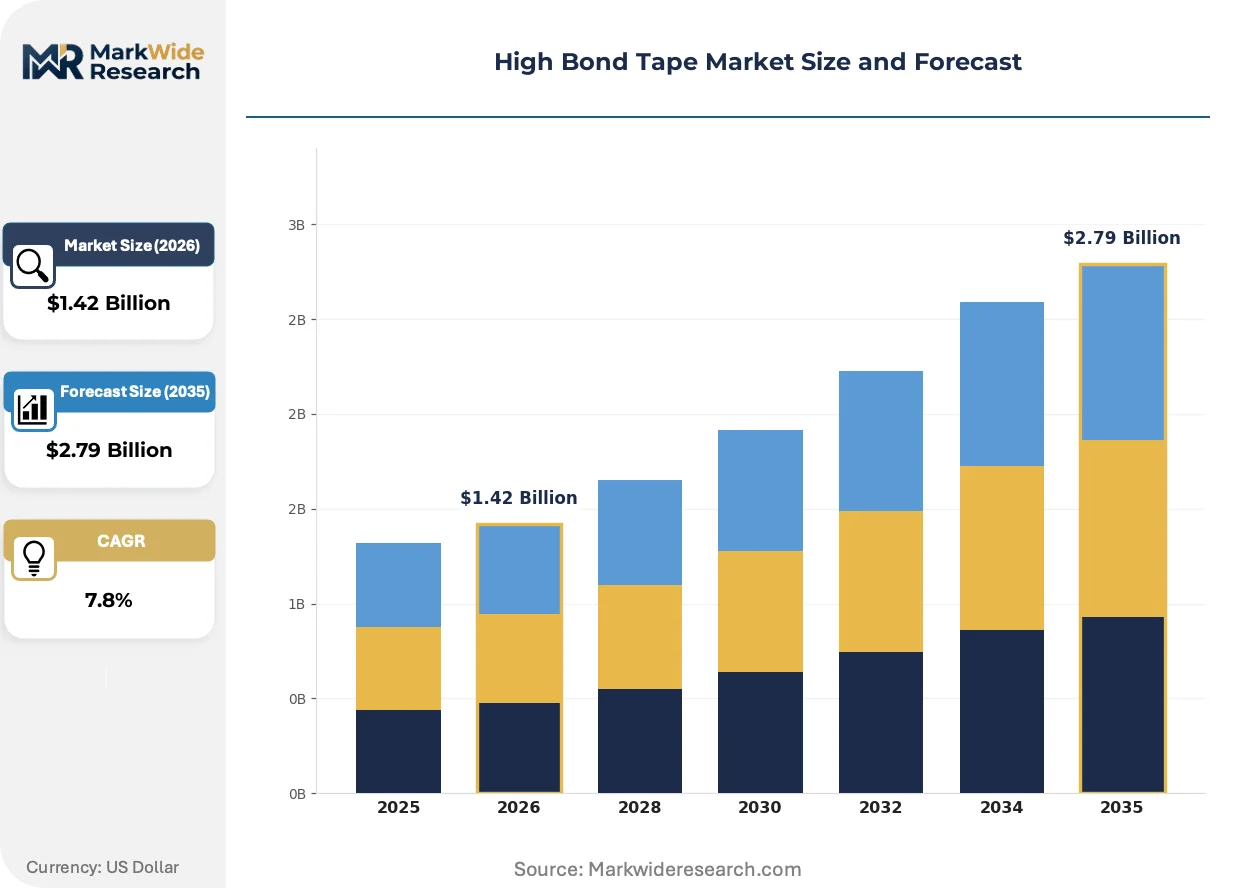
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tape, Foam Tape, Adhesive Transfer Tape, Mounting Tape Application: Automotive, Electronics, Packaging, Construction Material: Polyethylene, Acrylic, PVC, Rubber End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | 3M Company, Avery Dennison Corporation, tesa SE, Nitto Denko Corporation, Lintec Corporation, Intertape Polymer Group, Scapa Group plc, Lohmann GmbH & Co. KG, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Bond Tape Market Trends and Innovations
Active chemistry platforms and curing equipment are converging to enable thinner, stronger bond lines in automated production environments. Three developments are compressing traditional specification barriers.
UV-activated acrylic systems with tunable modulus profiles are rendering obsolete thermal curing ovens in automotive trim assembly operations. Tier-1 suppliers in Germany and the US are retrofitting production lines with LED curing stations to eliminate energy-intensive batch processes. The technology is compressing capital requirements for new tape specification entry.
EPA NESHAP VOC emission limits are forcing solvent-based formulation phase-outs across US manufacturing facilities. Adhesive producers are reallocating R&D spend toward hot-melt and UV-curable platforms to maintain compliance. The regulatory pressure is most acute in aerospace interior applications where FAA flammability standards intersect with environmental mandates.
Direct OEM procurement of bonding specifications is consolidating previously fragmented distributor relationships. Automotive engineering teams in Stuttgart, Wolfsburg, and Detroit are establishing preferred supplier programs that bypass traditional adhesive distributors. The shift is most visible in electric vehicle platform launches where bonding performance guarantees carry warranty liability.
High Bond Tape Market Segmentation
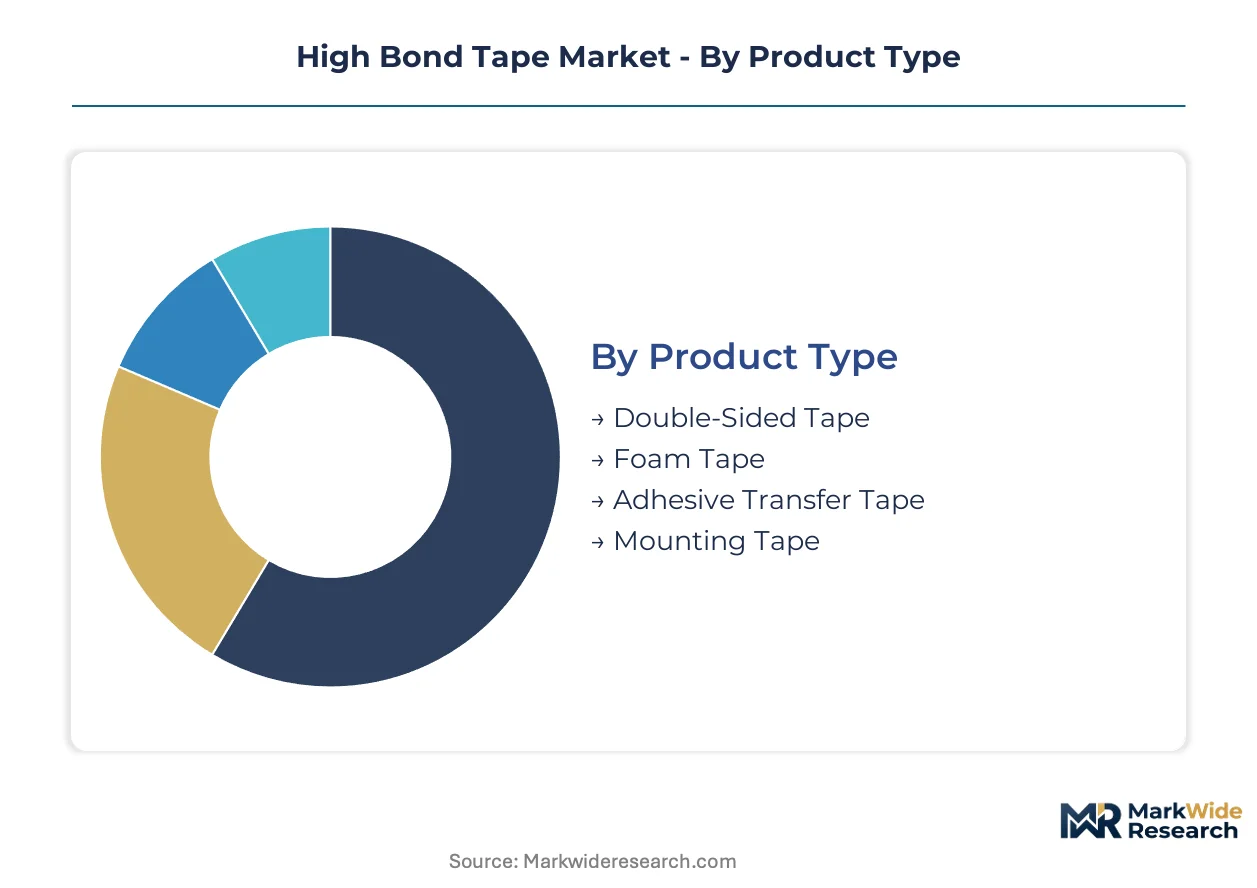
Segmentation in high bond tape markets reveals divergent specification cycles across product architectures and end-use verticals. Cycle times compress from 18-36 months in automotive structural bonding to 6-12 months in electronics lamination, creating distinct competitive dynamics within each category.
Product Type:
Replacement cycles stretch from weeks in electronics transfer tapes to years in automotive foam assemblies, dictating inventory and qualification investment intensity.
- Double-Sided Tape:Viscoelastic acrylic or rubber-based constructions bond dissimilar substrates through pressure activation without thermal curing. Automotive trim and glazing specifications in Germany's supplier corridor concentrate demand here, though crash-test validation timelines extend revenue recognition cycles.
- Foam Tape:Compressible polyethylene or polyurethane cores with adhesive skins absorb thermal expansion mismatches and vibration loads. Construction and heavy industrial applications favor this architecture for its conformability to irregular surfaces, with project-based procurement patterns creating lumpier demand profiles.
- Adhesive Transfer Tape:Ultra-thin unsupported adhesive films enable sub-millimeter bond lines in display lamination.
- Mounting Tape:Rigid carrier constructions support permanent fixture attachment in commercial signage and architectural applications.
Double-sided tape dominates installed base. Adhesive transfer tape is where expansion concentrates.
Application:
Margin structures vary sharply across verticals, with aerospace and medical specifications commanding formulation premiums against commodity construction grades.
- Automotive:Structural bonding of body-in-white components, battery pack assembly, and interior trim mounting. OEM lightweighting mandates in Stuttgart and Wolfsburg corridors are displacing welded joints, though NHTSA crashworthiness protocols constrain specification turnover.
- Electronics:Display lamination, semiconductor packaging, and miniaturized device assembly. East Asian consumer device supply chains are compressing bond line thickness requirements below 50 microns, favoring precision coating capabilities concentrated in Japan.
- Packaging:High-strength carton sealing and pallet unitization for logistics applications.
- Construction:Curtain wall glazing, HVAC duct sealing, and facade panel attachment subject to regional building code variations.
Automotive commands specification power. Electronics is climbing the fastest.
Material:
Raw material qualification protocols differ substantially, with REACH and RoHS compliance filtering supplier pools in European applications.
- Polyethylene:Closed-cell foam cores provide moisture resistance and compressibility in construction and automotive gap-filling applications. Cost positioning favors volume construction segments over precision industrial specifications.
- Acrylic:UV- or thermally-crosslinked polymer systems deliver thermal stability and environmental aging resistance. ECHA solvent-free mandates are accelerating transitions from rubber-based alternatives in German automotive supply chains.
- PVC:Rigid carrier films with economical adhesive coatings serve price-sensitive packaging and general industrial markets.
- Rubber:Natural and synthetic elastomer formulations offer tack and initial adhesion in lower-temperature applications, though thermal ceiling limitations constrain structural load-bearing use.
Acrylic sustains premium positioning. Polyethylene anchors volume throughput.
End User:
Procurement sophistication separates direct OEM engineering relationships from distributor-mediated contractor purchases.
- Manufacturers:Tier-1 automotive suppliers and electronics OEMs specify adhesive platforms directly, bypassing traditional distribution. Warranty liability for bonding performance concentrates qualification power among suppliers with crash-test validation capabilities.
- Contractors:Construction and installation trades purchase through building material distributors with project-based demand patterns.
- Retailers:Consumer and light commercial channels move standardized SKUs through hardware and home improvement chains.
- Distributors:Industrial supply intermediaries aggregate fragmented demand from maintenance and repair operations.
Manufacturers dictate specification roadmaps. Contractors represent the most price-elastic demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes high bond tape predominantly for automotive structural bonding, while Japan and South Korea concentrate demand in electronics miniaturization, and the United States splits consumption across aerospace interiors and construction applications.
Germany
Automotive lightweighting mandates from Stuttgart and Wolfsburg OEMs drive specification intensity for crash-test validated tape assemblies. ECHA REACH solvent-free substance restrictions accelerate transitions from rubber-based to acrylic formulations across supplier networks. The Baden-Württemberg automotive engineering corridor concentrates precision coating capacity and adhesive qualification expertise.
United States
Aerospace interior bonding and commercial construction applications split demand across distinct specification tiers. EPA NESHAP VOC emission limits under federal air quality standards force solvent-based formulation phase-outs in domestic manufacturing. The Detroit automotive engineering cluster and Pacific Northwest aerospace supply chain anchor regional consumption concentration.
Japan
Electronics miniaturization in display lamination and semiconductor packaging compresses bond line thickness requirements below 50 microns. METI industrial standards and JIS certification protocols filter supplier qualification for precision coating applications. The Chubu region around Nagoya hosts concentrated adhesive transfer tape manufacturing for East Asian consumer device supply chains.
China
Domestic EV platform launches and battery pack assembly create specification pull-through for structural bonding applications. MIIT new energy vehicle mandates and GB standards for automotive materials shape adhesive qualification roadmaps. The Yangtze River Delta manufacturing belt concentrates electronics lamination demand and precision coating investment.
India
Automotive assembly capacity expansion under PLI scheme incentives opens specification opportunities for localized tape production. BIS automotive component standards and DGFT import substitution policies encourage domestic manufacturing qualification. The Maharashtra-Gujarat automotive supplier corridor anchors emerging demand concentration for structural adhesive applications.
High Bond Tape Market Competitive Landscape
Capability concentration sits with European and Japanese specialists possessing crash-test validation credentials and precision coating expertise; scale advantage sits with diversified materials conglomerates commanding global distribution infrastructure and cross-industry specification power. The market structure tiers into three archetypes: vertically integrated film manufacturers with captive coating lines, precision specialists focused on ultra-thin transfer constructions, and diversified adhesive platforms serving multiple industrial verticals. Dominant competitive moves include backward integration into polymer resin production and strategic partnerships with Tier-1 automotive suppliers for platform-specific qualification.
Among the diversified multinational tier, 3M Company and Avery Dennison Corporation exemplify scale-driven positioning through broad adhesive platform coverage across automotive, aerospace, and electronics specifications. Within the European specialist cluster, tesa SE and Lohmann GmbH & Co. KG occupy positions anchored by captive film manufacturing and precision coating capabilities concentrated in German automotive supply corridors. Nitto Denko Corporation represents the East Asian precision archetype, with company structure indicating specialized focus on ultra-thin adhesive constructions for electronics miniaturization applications.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| tesa SE |
| Nitto Denko Corporation |
| Lintec Corporation |
| Intertape Polymer Group |
| Scapa Group plc |
| Lohmann GmbH & Co. KG |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Petrochemical input volatility determines both pricing tier spreads and supply chain shape in high bond tape markets. Acrylic monomer and synthetic rubber feedstock costs fluctuate with crude oil derivatives, compressing formulation margins unpredictably and forcing suppliers to segment offerings across crash-test validated premium grades and commodity construction tiers.
Pricing Analysis
Long-term offtake contracts dominate automotive structural bonding specifications, while spot purchasing prevails in construction and maintenance applications. Three-tier pricing structure across premium, standard, and economy levels separates crash-test validated automotive grades from general industrial formulations and price-sensitive packaging tapes. Cost compression in commodity rubber-based tiers is intensifying because of ECHA solvent-free mandates accelerating acrylic transitions. Contractors and retailers represent the most price-elastic demand pool, whereas Tier-1 automotive suppliers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from German automotive OEMs strain working capital for precision coating specialists concentrated in Baden-Württemberg. Supply concentrates in Germany, Japan, and China, with captive film manufacturing and adhesive qualification expertise anchoring European capacity. Raw material sourcing draws from acrylic monomer producers, synthetic rubber feedstock suppliers, and UV-curable resin specialists. Single-source vulnerability around precision coating equipment creates geographic concentration risk. Distribution runs through direct OEM procurement channels for automotive specifications and industrial distributors for fragmented construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high bond tape market sits in a cyclical recovery phase driven by automotive lightweighting program restarts and EV platform launches. OEM qualification timelines are compressing as crash-test validation capabilities become scarcer.
For Market Incumbents: Entrench specification power through captive polymer resin production and preferred supplier program lock-in with Stuttgart and Wolfsburg OEMs. Accelerate UV-LED curing platform deployment to eliminate energy-intensive batch processes and defend margin position against emerging Asian coating specialists. Certification investment in ECHA REACH solvent-free formulations represents the critical defensive lever as regulatory timelines tighten.
For New Entrants and Emerging Players: India's Maharashtra-Gujarat automotive supplier corridor offers the most penetrable white-space target, with PLI scheme incentives reducing qualification barriers for localized production. Electronics miniaturization applications in display lamination present secondary entry opportunity given thinner bond line requirements favoring new coating technology. Partner with domestic Indian OEMs for platform-specific qualification rather than competing head-to-head with established German-Japanese incumbents.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision specialists with crash-test validation credentials over diversified commodity players. Acquisition targets should demonstrate captive film manufacturing, established automotive OEM relationships, and UV-curable formulation pipelines. Monitor EU battery passport implementation timelines as the signal to watch for debondable adhesive platform inflection. Macroeconomic, regulatory, or technological deviation would prompt revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captive acrylic monomer supply secures margin control against petrochemical volatility in German supply chains. |
| UV-LED Curing Platform Deployment | Energy-efficient crosslinking enables inline bonding integration with Stuttgart OEM automated assembly lines. |
| Preferred Supplier Program Establishment | Direct OEM procurement relationships bypass distributors and concentrate warranty liability with validated suppliers. |
| Debondable Adhesive Platform Development | EU battery passport compliance creates specification pull-through for end-of-life vehicle directive alignment. |
| Localized Production in India | PLI scheme incentives and BIS qualification open specification opportunities in Maharashtra-Gujarat corridor expansion. |
Research Methodology
The analysis maps double-sided foam tapes, adhesive transfer tapes, mounting tapes, and UV-curable acrylic platforms, each validated through procurement directors at Tier-1 automotive suppliers, coating line engineers at precision manufacturers, regulatory affairs specialists tracking ECHA substance restrictions, and distribution channel managers across European industrial supply networks. Primary interview data triangulates against customs trade statistics for acrylic monomer flows, SEC filings from diversified adhesive platforms, IHS Markit vehicle production databases, and ECHA REACH registration dossiers. Bottom-up segment sizing and top-down market reconciliation ensure cross-validation across the analysis window.
Assumptions held fixed include ECHA solvent-free mandate implementation timelines, NHTSA crashworthiness protocol stability, and continued automotive lightweighting program commitment from Stuttgart and Wolfsburg OEMs. Variables tested include petrochemical input price trajectories, UV-LED curing adoption rates, and India PLI scheme incentive duration. Modeled segmentation spans product architecture, application vertical, material chemistry, and end-user procurement sophistication. CAGRs derive from segment-level volume trajectories calibrated to OEM platform launch schedules and electronics miniaturization bond line thickness compression rates.
Practitioners should monitor regulatory acceleration in EU battery passport requirements, tariff exposure in precision coating equipment trade flows, and adhesive chemist talent scarcity indicators for early signals of forecast deviation. Forecasts reflect documented assumptions about automotive production recovery trajectories and electronics lamination demand persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Electrical Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Thread Seal Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Adhesive Transfer Tape Market
Tapes
Flocking Tape Market
Tapes
Correction Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Masking Tape Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
ESD Tapes and Labels Market
Tapes
Hand Wrappers Market
Tapes
Pouch Tapes Market
Tapes
Gummed Tapes Market