
 PET Release Liner Market | 2026-2036
PET Release Liner Market Size, Share, and Industry Trends Forecast 2026-2036
PET Release Liner Market Analytics
Buyer concentration among medical device and automotive OEMs is restructuring procurement patterns across the PET release liner supply base. Loparex leverages its silicone coating expertise to serve diagnostic and wound-care adhesive producers. Polyplex Corporation anchors South Asian supply through integrated PET film and coating capacity. DuPont differentiates via fluorosilicone-modified release chemistry for extreme-temperature automotive bonding tapes.
PET release liner denotes a biaxially oriented polyethylene terephthalate film, typically 23–75 micron gauge, bearing a cured polydimethylsiloxane or olefinic release layer with 5–50 g/25cm peel force, engineered to protect pressure-sensitive adhesive surfaces until point of application. Silicone-coated variants dominate value pools given their thermal stability above 150°C and universal compatibility with acrylic, rubber, and silicone adhesives. Water-based adhesive formulations are gaining share as converters retrofit coating lines to eliminate solvent recovery infrastructure. Medical end-use generates premium pricing due to biocompatibility certification burdens and lot-traceability requirements.
FDA 21 CFR Part 175.300 and ISO 10993 frameworks govern medical-grade liner substrates in the United States, while REACH Annex XVII restrictions on siloxane emissions shape European coating chemistry choices. The EU Green Deal's packaging waste directives are pressuring label producers to specify thinner, recyclable PET carrier constructions. Stakeholders must monitor evolving state-level extended producer responsibility laws and adhesive migration test protocols to anticipate specification shifts before contract renewals.
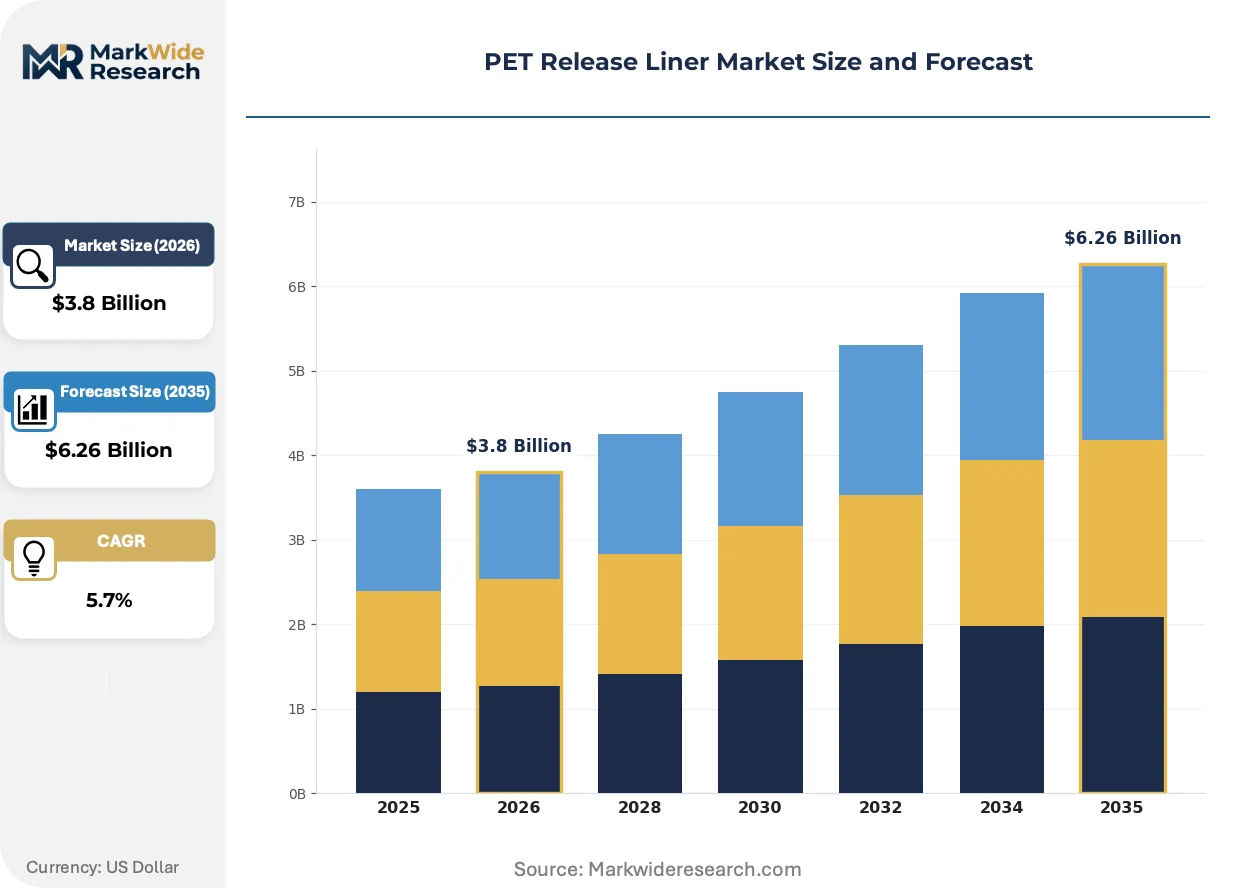
Market Dynamics
Buyer consolidation among German automotive OEMs and US medical device manufacturers is compressing supplier margins while accelerating specification harmonization across coating chemistries and film gauges.
Growth Catalysts
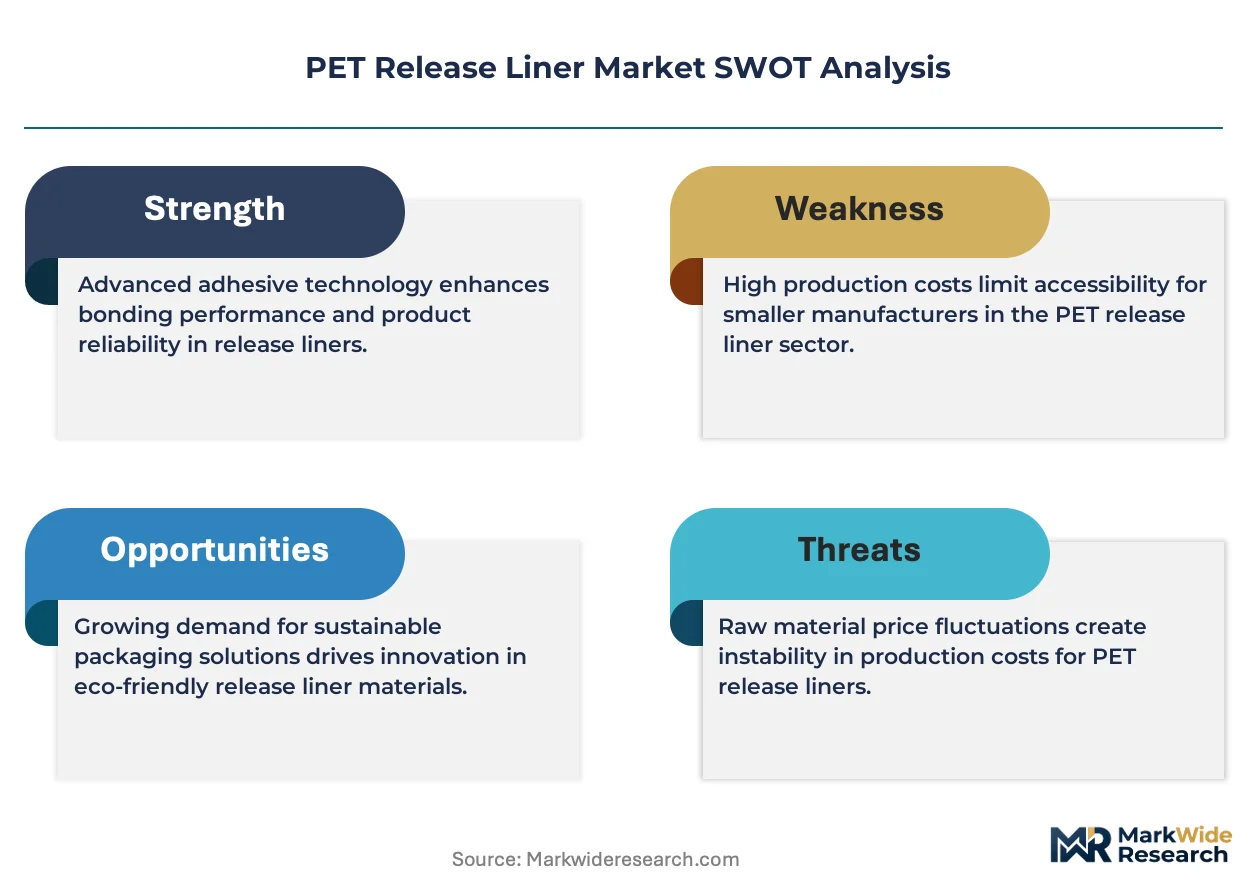
- ISO 10993 biocompatibility certification:Medical-grade PET liners command premium positioning as wound-care and diagnostic adhesive producers face mandatory substrate validation for FDA 510(k) submissions.
- Water-based silicone emulsion coating:European converters retrofit solvent-based lines to eliminate thermal oxidizer infrastructure and satisfy REACH Annex XVII emission thresholds.
- Germany's precision converting cluster:Stuttgart and Munich anchor regional demand for 12–23 micron ultra-thin liners serving electric vehicle battery bonding tapes.
Market Restraints
- Dimethicone raw material concentration:Siloxane precursor supply concentrates among three German and Chinese chemical conglomerates, exposing coaters to feedstock allocation risk.
- Fluorosilicone technical ceiling:Extreme-temperature automotive applications above 200°C exceed standard polydimethylsiloxane release stability, forcing costly hybrid chemistry development.
- EU Green Deal packaging directives:Recyclability mandates for multi-layer constructions threaten silicone-coated PET structures lacking established mechanical recycling pathways.
Strategic Opportunities
- India's medical device PLI scheme:Domestic adhesive converter expansion creates captive liner demand as CDSCO tightens import substitution incentives for sterile packaging substrates.
- RFID-integrated smart liners:Convergence of printable electronics with release substrates enables lot-traceability and cold-chain monitoring for pharmaceutical cold-form blister packs.
- Direct converter e-procurement platforms:Digital tendering bypasses traditional distribution layers, allowing mid-tier coaters to access automotive OEM specification committees previously gatekept by national distributors.
Industry Challenges
- Silicone coating technician scarcity:Thin-film web handling expertise concentrates among aging workforces in Germany and Japan, constraining line expansion timelines for new market entrants.
- ISO 15378 certification timeline:Pharmaceutical primary packaging qualification demands 18–24 month validation cycles, freezing specification changes and locking incumbents into multi-year supply agreements.
- Legacy solvent recovery asset stranding:Converters face accelerated depreciation on thermal oxidizer infrastructure as water-based coating transitions render capital-intensive abatement systems economically obsolete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Release Liner Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Coated, Polyethylene Coated, Polypropylene Coated, Others Adhesive Type: Water-Based, Solvent-Based, Hot Melt, Others End User: Packaging, Labeling, Medical, Automotive Thickness: 50 Micron, 100 Micron, 150 Micron, 200 Micron |
| Companies Covered | Loparex, Polyplex Corporation, DuPont, Fox River Associates, Tekra, Mondi Group, Lintec Corporation, Newmax Tec, Ahlstrom-Munksjö, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Release Liner Market Evolving Landscape
Active coating line digitization and substrate-thinning initiatives are compressing conversion economics while opening specification windows for novel release chemistries previously excluded on cost grounds.
Plasma-enhanced chemical vapor deposition of fluorocarbon release layers is modularizing coating operations by eliminating wet-chemistry baths and reducing changeover downtime from eight hours to forty-five minutes. Automotive tape producers in Stuttgart and Detroit adopt this dry-process technology for just-in-sequence supply contracts requiring rapid formulation switches. The capital efficiency gain is modularizing entry barriers, allowing regional coaters to challenge integrated film producers on technical service responsiveness.
REACH Annex XVII restrictions on cyclic siloxane emissions are forcing reformulation of condensation-cure silicone coatings toward addition-cure platinum-catalyzed systems with lower volatile organic compound profiles. German coaters face six-month requalification timelines with automotive OEMs as release force stability specifications tighten. Medical device manufacturers accelerate specification shifts ahead of 2027 sunset dates for legacy condensation-cure chemistries, prioritizing suppliers with validated addition-cure capacity.
Automotive OEMs consolidate adhesive tape procurement from regional converter networks toward direct master service agreements with tier-one coaters, unbundling specification-setting from logistics execution. This concentration eliminates distributor margin layers but demands coaters maintain finished-goods inventory within four-hour drive-time of assembly plants. The restructuring is most visible in Germany's Baden-Württemberg automotive corridor, where Mercedes-Benz and Porsche specify vendor-managed inventory programs with release liner suppliers holding sixteen weeks of finished-goods liability.
PET Release Liner Market Segmentation
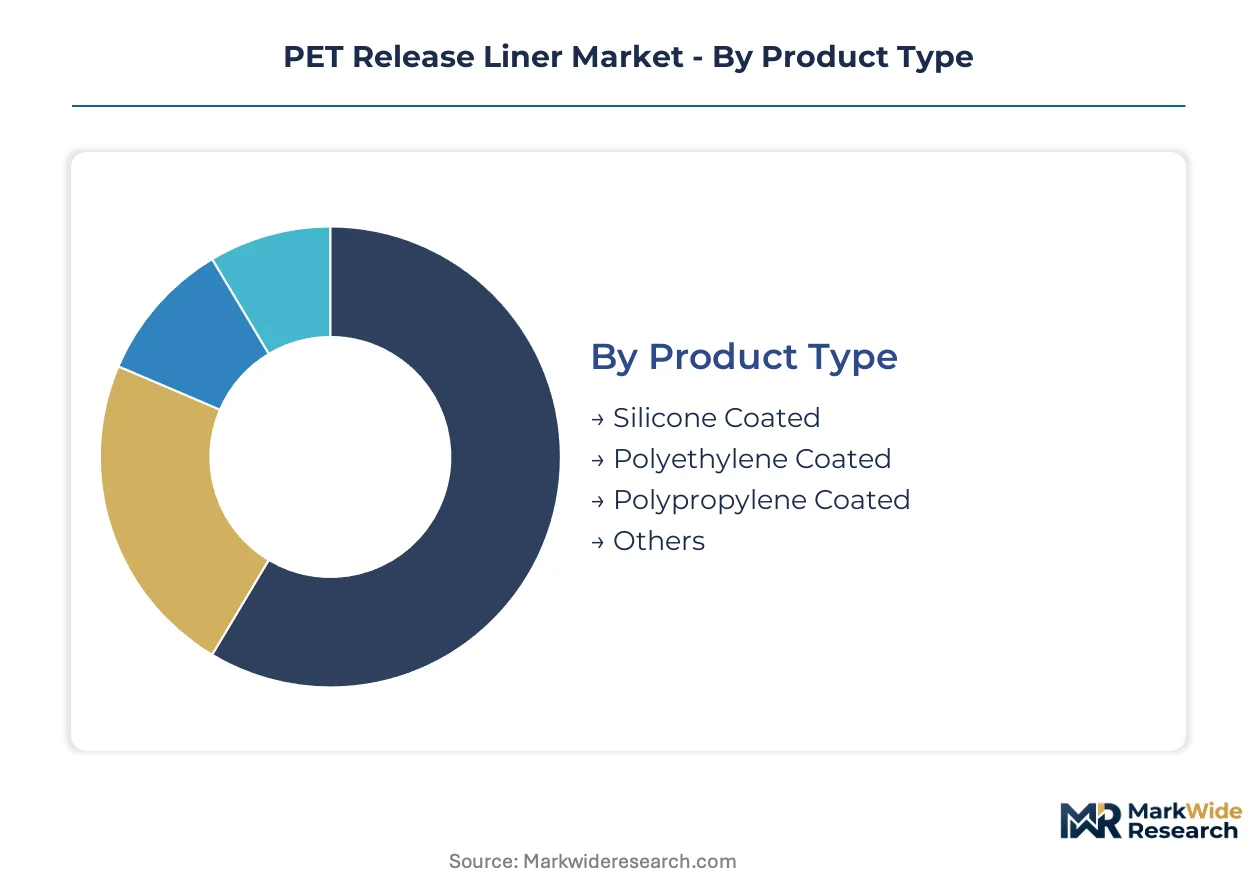
PET release liner segmentation reveals how coating chemistry, adhesive compatibility, and end-use certification requirements fragment supply chains. Specification divergence across medical, automotive, and packaging verticals forces coaters to maintain parallel production lines with distinct validation protocols.
Product Type:
Supply concentration in silicone coating expertise concentrates value capture among specialized chemical coaters with validated cleanroom infrastructure.
- Silicone Coated:Cured polydimethylsiloxane layers deliver thermal stability above 150°C and universal adhesive compatibility. Demand clusters in Germany's automotive corridor and US diagnostic adhesive manufacturing, where ISO 10993 biocompatibility certification commands premium positioning.
- Polyethylene Coated:Low-density olefinic release surfaces target cost-sensitive labeling applications with moderate peel force requirements. European converters specify these constructions for EU Green Deal compliance, as mono-material structures simplify mechanical recycling versus silicone-barrier laminates.
- Polypropylene Coated:Polypropylene release layers offer intermediate chemical resistance for industrial tape backing.
- Others:Fluorosilicone and fluorocarbon variants serve niche extreme-temperature applications exceeding 200°C.
Today's leader: Silicone Coated. Tomorrow's challenger: Polyethylene Coated.
Adhesive Type:
Cost tier stratification separates capital-intensive solvent infrastructure from emerging water-based retrofit investments.
- Water-Based:Silicone emulsion coatings eliminate thermal oxidizer requirements and satisfy REACH Annex XVII emission thresholds. German coaters accelerate line conversions as automotive OEMs mandate volatile organic compound reductions in supplier scorecards.
- Solvent-Based:Condensation-cure solvent systems retain share in medical-grade applications where eighteen-month requalification timelines freeze specification changes.
- Hot Melt:Reactive hot-melt adhesive compatibility demands specialized release force tuning for high-speed converting lines.
- Others:UV-curable and moisture-cure adhesive categories require custom release surface energy profiles.
Water-based formulations gain share fastest as regulatory pressure compounds total cost of ownership advantages.
End User:
Application-driven margin stratification separates commodity label backing from certified medical substrates with lot-traceability requirements.
- Medical:Sterile adhesive applications for wound care and diagnostics demand ISO 10993-validated substrates with full batch documentation. FDA 510(k) submission requirements lock converters into multi-year supply agreements with certified coaters.
- Automotive:Electric vehicle battery bonding tapes specify ultra-thin 12–23 micron liners with plasma-enhanced fluorocarbon coatings for just-in-sequence supply contracts in Stuttgart and Detroit.
- Packaging:Flexible food and pharmaceutical blister packs prioritize optical clarity and migration test compliance.
- Labeling:Pressure-sensitive label stock represents volume anchor but compresses margins through distributor-consolidated procurement.
Medical commands premium pricing. Automotive represents steepest expansion trajectory.
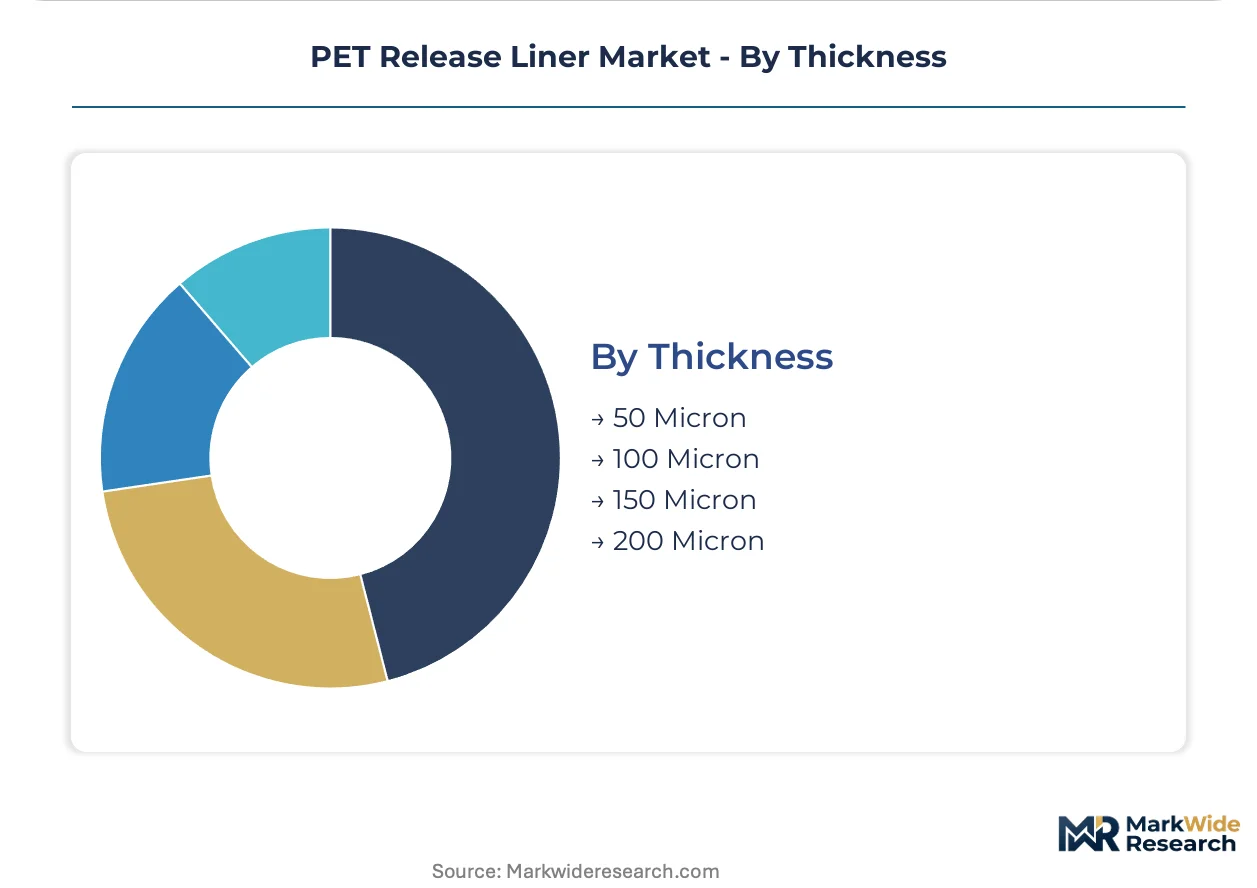
Thickness:
Volume concentration in mid-gauge constructions conflicts with end-use thinning initiatives across battery and wearable adhesive segments.
- 50 Micron:Ultra-thin gauge dominates electric vehicle battery bonding tapes and medical wearable adhesives where conformability and weight reduction override material cost.
- 100 Micron:Standard industrial gauge balances web handling stability with material efficiency for high-speed label converting.
- 150 Micron:Heavy-duty construction serves automotive exterior trim bonding and industrial assembly tapes requiring dimensional stability.
- 200 Micron:Maximum gauge targets specialty applications with extreme mechanical stress or multi-layer lamination requirements.
100 Micron holds volume leadership. 50 Micron posts fastest specification shift as substrate thinning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands automotive-grade liner specifications while India builds medical substrate capacity through import substitution incentives. The United States anchors diagnostic adhesive demand with FDA-validated supply chains.
Germany
Mercedes-Benz and Porsche consolidate procurement through vendor-managed inventory programs requiring sixteen weeks of finished-goods liability from coaters. REACH Annex XVII cyclic siloxane restrictions force six-month requalification timelines with automotive OEMs. Stuttgart and Munich anchor demand for 12–23 micron ultra-thin liners serving electric vehicle battery bonding tapes.
United States
Diagnostic adhesive producers drive ISO 10993 biocompatibility certification for FDA 510(k) submissions. FDA 21 CFR Part 175.300 governs medical-grade substrate specifications. Detroit automotive corridors adopt plasma-enhanced fluorocarbon coatings for just-in-sequence supply contracts requiring rapid formulation switches.
India
Domestic adhesive converter expansion creates captive liner demand as CDSCO tightens import substitution incentives for sterile packaging substrates. The medical device PLI scheme accelerates local coating capacity investments. Maharashtra and Gujarat host precision converting clusters serving pharmaceutical blister pack manufacturers.
China
Siloxane precursor supply concentrates among chemical conglomerates exposing coaters to feedstock allocation risk. GB standards and MIIT directives shape coating chemistry approvals for domestic medical device integration. Yangtze River Delta converters retrofit solvent-based lines to satisfy emission reduction mandates.
Japan
Thin-film web handling expertise concentrates among aging workforces constraining line expansion timelines for new market entrants. METI guidelines influence pharmaceutical primary packaging qualification protocols. Kanto and Kansai regions maintain specialized cleanroom infrastructure for wound-care adhesive applications.
PET Release Liner Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coating chemistry and film gauge segments. The vendor base separates into three tiers: integrated film producers with captive resin supply, specialized chemical coaters with validated cleanroom infrastructure, and regional converters serving distributor networks. Two dominant competitive moves define current positioning: automotive OEMs consolidate procurement through direct master service agreements eliminating distributor margins, and European coaters accelerate water-based line conversions to satisfy REACH emission thresholds.
Within the specialized coater tier, Loparex exemplifies silicone coating expertise serving diagnostic and wound-care adhesive producers. Polyplex Corporation anchors South Asian supply through integrated PET film and coating capacity. DuPont occupies a position in extreme-temperature automotive bonding tapes through fluorosilicone-modified release chemistry development.
| Leading Market Players |
|---|
| Loparex |
| Polyplex Corporation |
| DuPont |
| Fox River Associates |
| Tekra |
| Mondi Group |
| Lintec Corporation |
| Newmax Tec |
| Ahlstrom-Munksjö |
| Others |
Value Network & Pricing Analysis
Dimethicone spot price volatility cascades through PET release liner manufacturing into three distinct pricing tiers, with automotive OEMs absorbing premium escalation for validated silicone coating capacity while label converters face margin compression from commodity-grade polyethylene alternatives.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-gauge liners as domestic coating lines undercut European import pricing by 15–20 percent on freight-adjusted terms. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical substrates from automotive-grade silicone coatings and cost-sensitive label backings. Cost compression in the standard tier is intensifying because German coaters face six-month requalification timelines with automotive OEMs. Label converters exhibit highest price sensitivity due to distributor-consolidated procurement, while medical device manufacturers demonstrate lowest sensitivity given FDA 510(k) submission lock-in.
Supply Chain Analysis
Dual-sourcing requirements from Mercedes-Benz and Porsche mandate multi-supplier qualification for 12–23 micron ultra-thin liners, fragmenting procurement across German, Chinese, and South Korean coating capacity. Siloxane precursor supply concentrates among chemical conglomerates in Germany and China, exposing coaters to feedstock allocation risk. Single-source vulnerability intensifies for plasma-enhanced fluorocarbon coating equipment, with German and Japanese OEMs controlling modular deposition system supply. Distribution runs through vendor-managed inventory programs requiring sixteen weeks of finished-goods liability held within four-hour drive-time of Stuttgart and Detroit assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PET release liner demand is maturing into a late-cycle quality story as electric vehicle battery bonding tapes and diagnostic adhesive applications displace commodity label volume with specification-intensive premium substrates.
For Market Incumbents: Deepen silicone coating technician apprenticeship pipelines in Germany and Japan to offset aging workforce attrition threatening line expansion timelines. Fortify backward integration into dimethicone precursor supply through long-term offtake agreements with German and Chinese chemical conglomerates, neutralizing feedstock allocation risk that emerging coaters cannot match.
For New Entrants and Emerging Players: The mid-market price-point gap between DuPont fluorosilicone extreme-temperature solutions and commodity polyethylene label backings offers white-space entry for regional coaters with addition-cure platinum-catalyzed capacity. Target India's Maharashtra and Gujarat precision converting clusters where CDSCO import substitution incentives create captive demand for sterile packaging substrates. Pursue direct e-procurement platform access to automotive OEM specification committees, bypassing distributor gatekeepers.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized chemical coaters possessing validated cleanroom infrastructure and ISO 15378 pharmaceutical primary packaging certification, given eighteen-to-twenty-four month qualification timelines freeze specification changes and lock incumbents into multi-year supply agreements. Watch water-based silicone emulsion coating retrofit rates among European converters as the inflection indicator for REACH Annex XVII compliance-driven market share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Conversion | Eliminates thermal oxidizer infrastructure and satisfies REACH Annex XVII cyclic siloxane emission thresholds. |
| Plasma-Enhanced Fluorocarbon Deposition | Modularizes coating operations for Stuttgart and Detroit just-in-sequence supply contracts. |
| ISO 10993 Biocompatibility Certification | Locks medical-grade substrate suppliers into FDA 510(k) submission-dependent multi-year agreements. |
| Vendor-Managed Inventory Program | Mercedes-Benz and Porsche mandate sixteen weeks finished-goods liability within four-hour drive-time. |
| Dimethicone Precursor Backward Integration | Neutralizes feedstock allocation risk from German and Chinese chemical conglomerate concentration. |
Research Methodology
Bottom-up medical and automotive adhesive demand modeling reconciled against top-down PET film and coating capacity tracking forms the analytical core of this study. Primary interviews with silicone coating technicians, automotive OEM procurement leads, medical device regulatory affairs directors, and precision converting plant managers combined with secondary validation from FDA 510(k) submission databases, ECHA REACH Annex XVII regulatory filings, and German automotive OEM supplier scorecard disclosures. Top-down customs data from Germany, China, and India triangulates against bottom-up converter consumption surveys.
Historical trendline analysis of silicone coating capacity utilization and adhesive formulation shifts anchors the projection framework across the analysis window. Segmentation dimensions include coating chemistry type, adhesive compatibility class, end-use certification tier, film gauge specification, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand curves incorporating electric vehicle battery tape content-per-vehicle trajectories and diagnostic adhesive substrate intensity trends.
The model assumes a particular technology adoption path; alternative pathways for water-based silicone emulsion coating penetration would alter the outlook if European automotive OEMs accelerate volatile organic compound reduction mandates ahead of baseline expectations. Forecasts reflect assumptions about REACH Annex XVII enforcement consistency, CDSCO import substitution incentive durability, and dimethicone precursor supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Nano Sealers Market