
 Spine Surgery Robots Market | 2026-2036
Spine Surgery Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Spine Surgery Robots Market Intelligence
Subscription-based leasing and pay-per-procedure financing is reconfiguring capital deployment across the spine surgery robots landscape. Stryker leverages its installed base of navigation platforms to cross-sell robotic systems into integrated delivery networks. Medtronic sustains R&D intensity through its dedicated robotics division, while Globus Medical differentiates via specialized spine-focused engineering rather than general surgical diversification.
Spine surgery robots comprise electromechanical arms, optical tracking arrays, and instrument guidance software designed to execute pedicle screw placement and vertebral alignment with sub-millimeter accuracy. The primary commercial purpose is reduction of revision rates and radiation exposure during thoracolumbar fixation procedures. Robotic Assistance Systems command the dominant share of product-type revenue as hospitals prioritize turnkey platforms over standalone navigation modules. AI Integration represents the fastest-expanding technology segment, with machine learning algorithms now enabling predictive trajectory planning that reduces intraoperative fluoroscopy time.
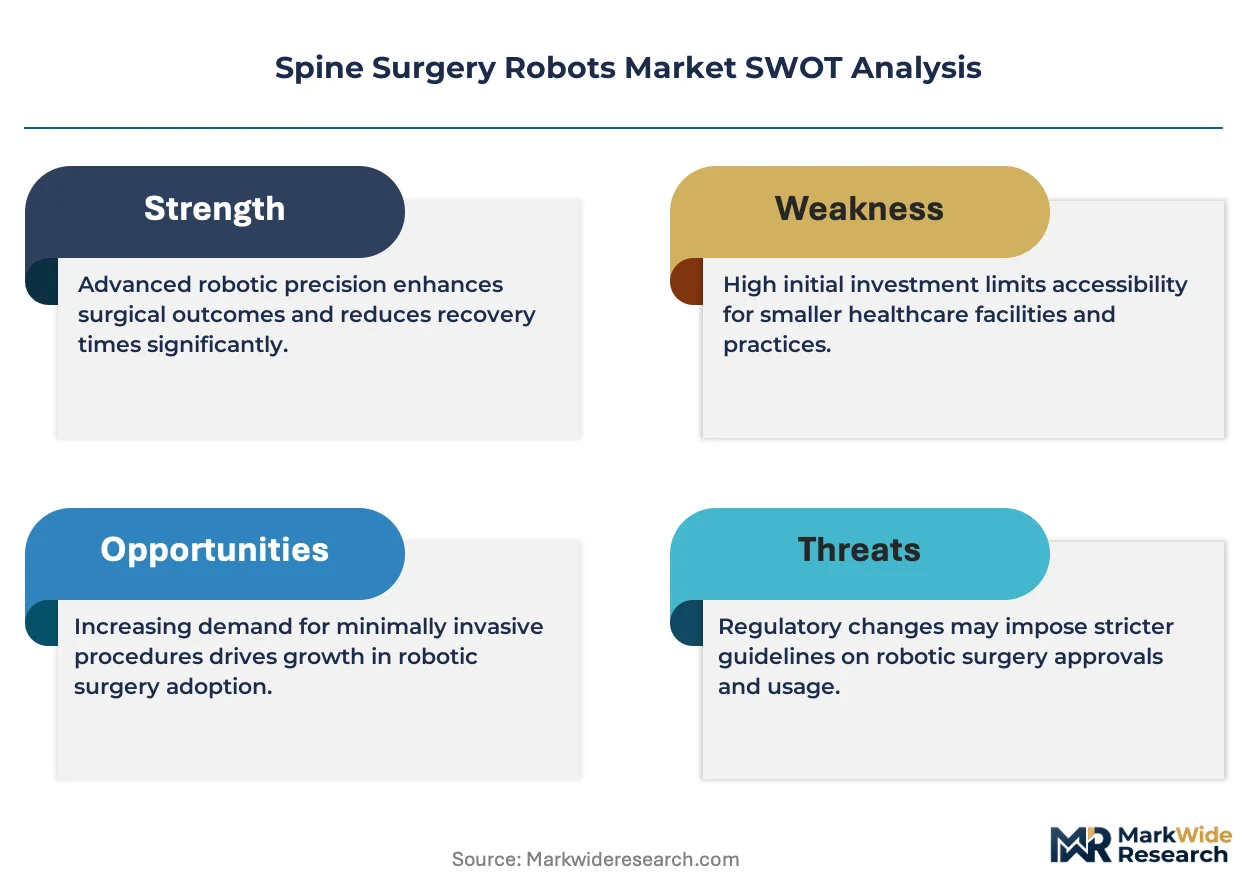
FDA 510(k) clearances and CE marking under the EU Medical Device Regulation govern commercial access across North America and Europe, with both frameworks tightening software validation requirements for autonomous surgical planning. The EPA and OSHA indirectly shape demand through workplace radiation exposure limits that robotic guidance helps hospitals satisfy. Stakeholders must monitor how reimbursement parity between robotic and conventional spine procedures evolves under CMS and private payer frameworks, as this determines hospital capital allocation cycles.
Market Dynamics
Subscription-based leasing models are compressing capital deployment cycles for spine surgery robots, forcing manufacturers to restructure revenue recognition around procedure volume rather than upfront hardware sales. This financial engineering shift is altering how integrated delivery networks evaluate robotic platform acquisitions.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's premarket notification pathway for robotic surgical devices reduces commercial entry timelines for manufacturers, accelerating platform availability in hospital systems.
- Ambulatory Surgical Center Expansion:ASCs are integrating robot-assisted spine procedures as cost-competitive alternatives to inpatient hospital surgery, broadening addressable procedure volumes.
- OSHA Radiation Limits:Workplace exposure regulations are driving fluoroscopy reduction mandates that robotic guidance systems satisfy through sub-millimeter trajectory planning.
Market Restraints
- Capital Intensity:Robotic platform acquisition requires substantial upfront expenditure that strains ambulatory surgical center balance sheets, limiting penetration outside hospital networks.
- Surgeon Training Bottlenecks:Proctoring requirements and learning curve variability constrain deployment velocity, particularly for complex thoracolumbar fixation procedures.
- Reimbursement Parity Gaps:CMS and private payer frameworks maintain payment equivalence between robotic and conventional spine procedures, removing margin incentives for hospital capital allocation.
Strategic Opportunities
- AI Trajectory Planning:Machine learning algorithms enabling predictive screw placement are reducing intraoperative fluoroscopy time, creating differentiation for platforms with integrated intelligence.
- Pay-per-Procedure Financing:Usage-based revenue models align manufacturer incentives with hospital utilization rates, lowering adoption barriers for capital-constrained facilities.
- EU MDR Software Validation:Tighter CE marking requirements for autonomous surgical planning favor established platforms with regulatory infrastructure, consolidating competitive position.
Industry Challenges
- Interoperability Fragmentation:Navigation platform incompatibility with existing hospital imaging systems creates integration friction and extends implementation timelines.
- Procedural Volume Concentration:High-complexity spine cases cluster in academic medical centers, limiting addressable market for community hospital and ASC deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spine Surgery Robots Market |
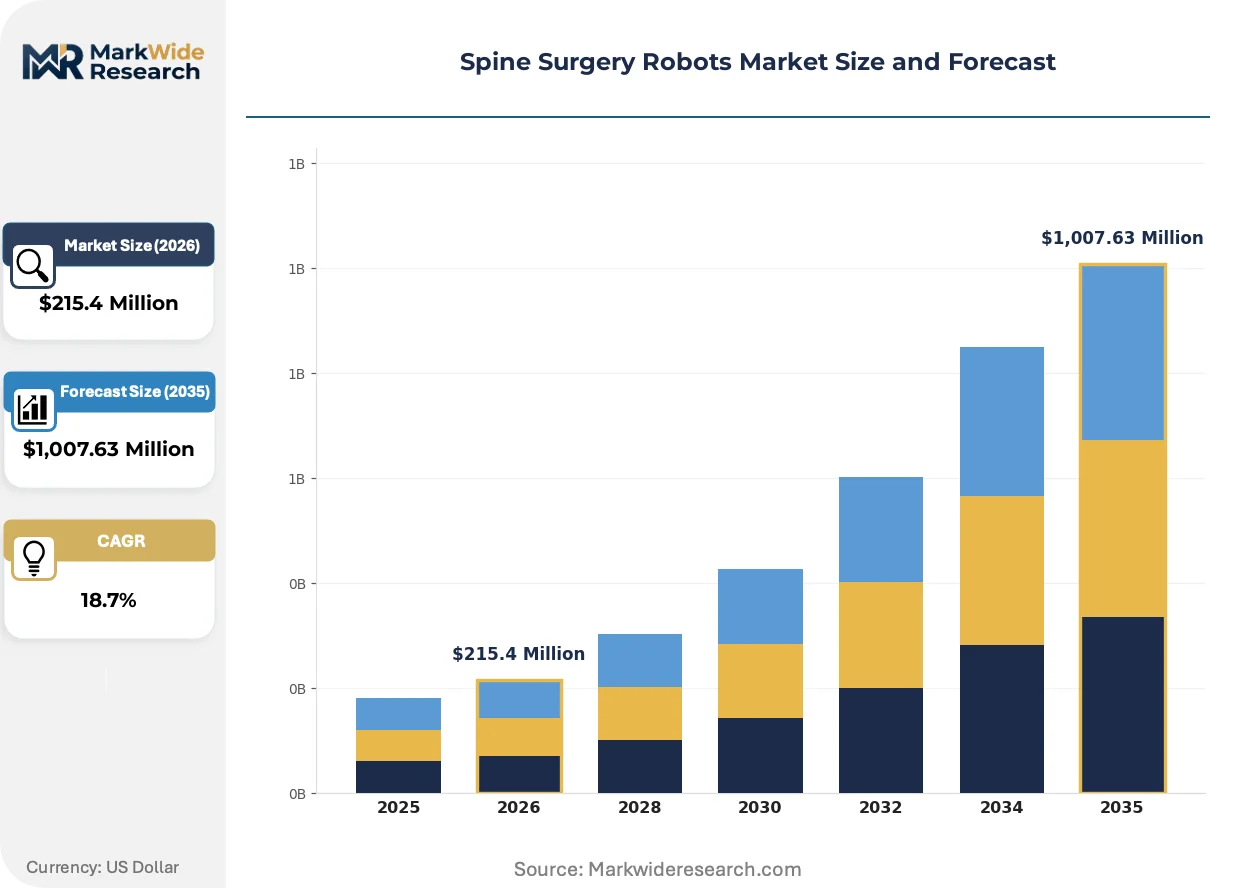
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $1,007.63 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Assistance Systems, Imaging Systems, Navigation Systems, Surgical Tools End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile Technology: Minimally Invasive Surgery, AI Integration, Haptic Feedback, 3D Imaging |
| Companies Covered | Stryker, NuVasive, Medtronic, TINAVI Medical Technologies, Brainlab, Zimmer Biomet, Mazor Robotics, CUREXO, Globus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spine Surgery Robots Market Strategic Shifts & Innovations
Artificial intelligence integration is digitizing surgical planning workflows, compressing the gap between preoperative imaging and intraoperative execution. Three developments are reshaping competitive positioning in spine robotics.
Optical tracking arrays combined with real-time instrument guidance software are digitizing pedicle screw placement accuracy. Academic medical centers in the United States are deploying these systems for complex deformity corrections. The technology is digitizing surgical workflow standardization across previously variable manual techniques.
The EU Medical Device Regulation's software validation requirements are tightening commercial access for autonomous planning modules. Manufacturers must demonstrate algorithmic traceability and clinical performance equivalence. Spine-focused engineering divisions are responding by segregating AI development from general surgical robotics portfolios.
Integrated delivery networks are consolidating vendor relationships around turnkey platforms that bundle navigation, robotics, and after-sales support. Hospital procurement committees now evaluate total cost-of-ownership across five-year utilization horizons. This concentration is most visible in United States metropolitan markets where IDNs control multiple surgical facilities.
Spine Surgery Robots Market Segmentation
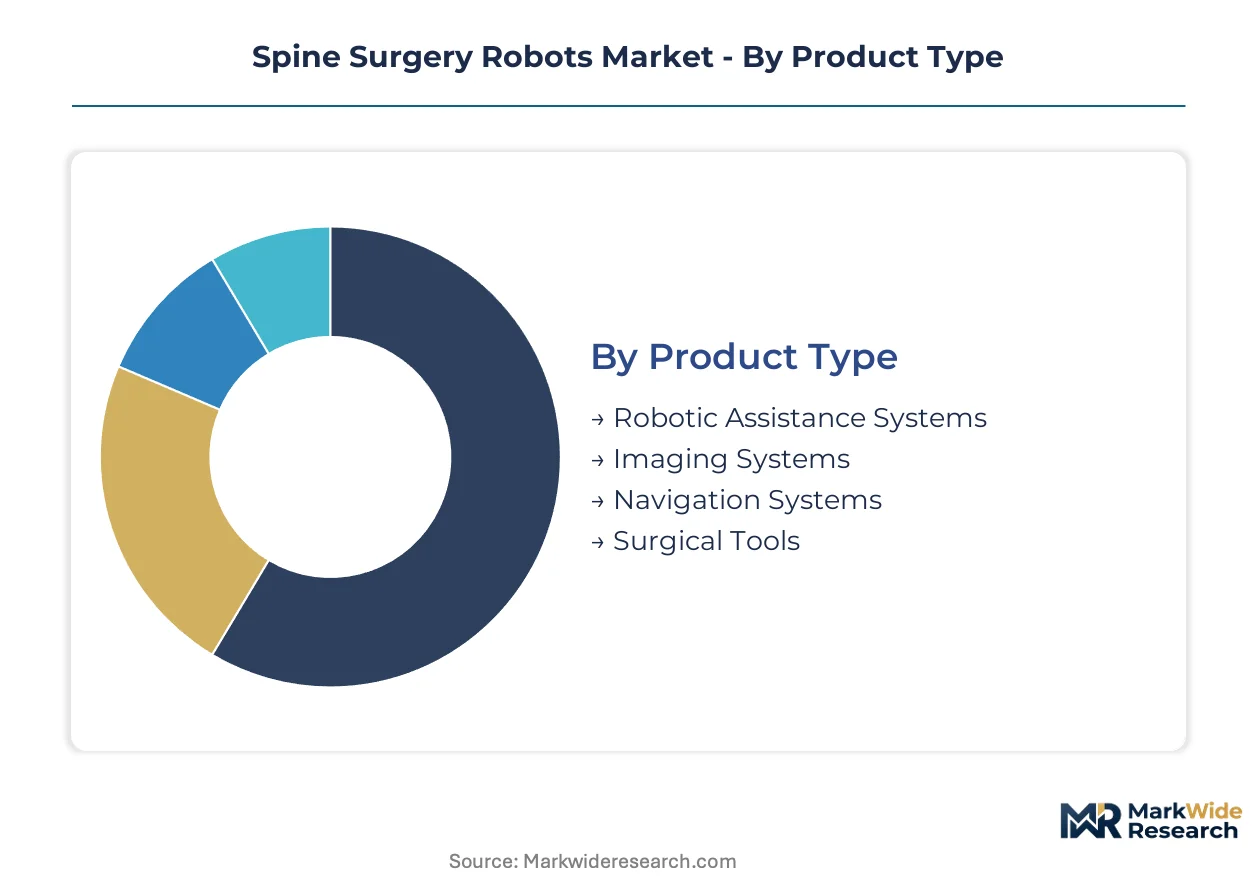
Spine surgery robots segment across hardware platforms, customer settings, delivery architectures, and enabling technologies. Each dimension shapes procurement criteria, regulatory pathways, and capital deployment cycles differently across hospital systems and ambulatory networks.
Product Type:
Cost tier differentiation separates turnkey platforms from modular components, with capital allocation decisions pivoting on total cost-of-ownership calculations versus incremental upgrade paths.
- Robotic Assistance Systems:Electromechanical arms with optical tracking arrays execute pedicle screw placement through sub-millimeter trajectory planning. Demand concentrates in United States integrated delivery networks prioritizing turnkey platforms that bundle navigation, robotics, and after-sales support to reduce revision rates and radiation exposure during thoracolumbar fixation.
- Imaging Systems:Intraoperative fluoroscopy and cone-beam CT modules provide real-time anatomical visualization during robotic-assisted procedures. Academic medical centers in metropolitan United States markets deploy these systems for complex deformity corrections where imaging integration determines surgical workflow standardization.
- Navigation Systems:Optical tracking and instrument guidance software digitize surgical planning workflows.
- Surgical Tools:Robotic-compatible pedicle screws, drill guides, and retractor systems complete instrument ecosystems.
Robotic Assistance Systems holds installed capacity. Navigation Systems is rotating up the share rankings as hospitals prioritize modular upgrade paths over full platform replacements.
End User:
Customer type determines purchasing authority, with capital deployment cycles varying between consolidated hospital networks and independent ambulatory facilities.
- Hospitals:Academic medical centers and community hospital systems command procurement committees evaluating five-year utilization horizons for robotic platforms. United States metropolitan markets exhibit concentration where integrated delivery networks control multiple surgical facilities and negotiate enterprise-wide vendor contracts.
- Ambulatory Surgical Centers:Outpatient spine facilities are integrating robot-assisted procedures as cost-competitive alternatives to inpatient surgery. Capital intensity strains ASC balance sheets, though pay-per-procedure financing models are lowering adoption barriers for these settings.
- Clinics:Specialist spine practices access robotic capabilities through partnership arrangements with hospital systems.
- Research Institutions:Academic research centers drive algorithmic development for autonomous surgical planning.
Hospitals maintains procurement volume concentration. Ambulatory Surgical Centers is expanding addressable procedure volumes fastest as regulatory frameworks adapt to outpatient spine surgery.
Deployment Model:
Architecture choice reflects data governance requirements, with cloud connectivity enabling predictive analytics while on-premise installations satisfy institutional cybersecurity policies.
- On-Premise:Local server installations keep surgical planning data within hospital firewall boundaries. United States health systems with stringent HIPAA compliance requirements favor this architecture despite higher capital expenditure and dedicated IT infrastructure demands.
- Cloud-Based:Remote server architectures enable centralized software updates and cross-facility analytics. European hospitals navigating EU AI Act algorithmic transparency requirements are evaluating cloud deployments for audit trail centralization.
- Hybrid:Mixed architectures separate patient data storage from processing workloads.
- Mobile:Transportable robotic units serve multi-site hospital networks.
On-Premise dominates current installed base. Cloud-Based is climbing the fastest as software validation requirements favor centralized update management.
Technology:
Maturity gradients separate established minimally invasive techniques from emerging AI capabilities, with reimbursement parity and regulatory clearance timelines determining commercial velocity.
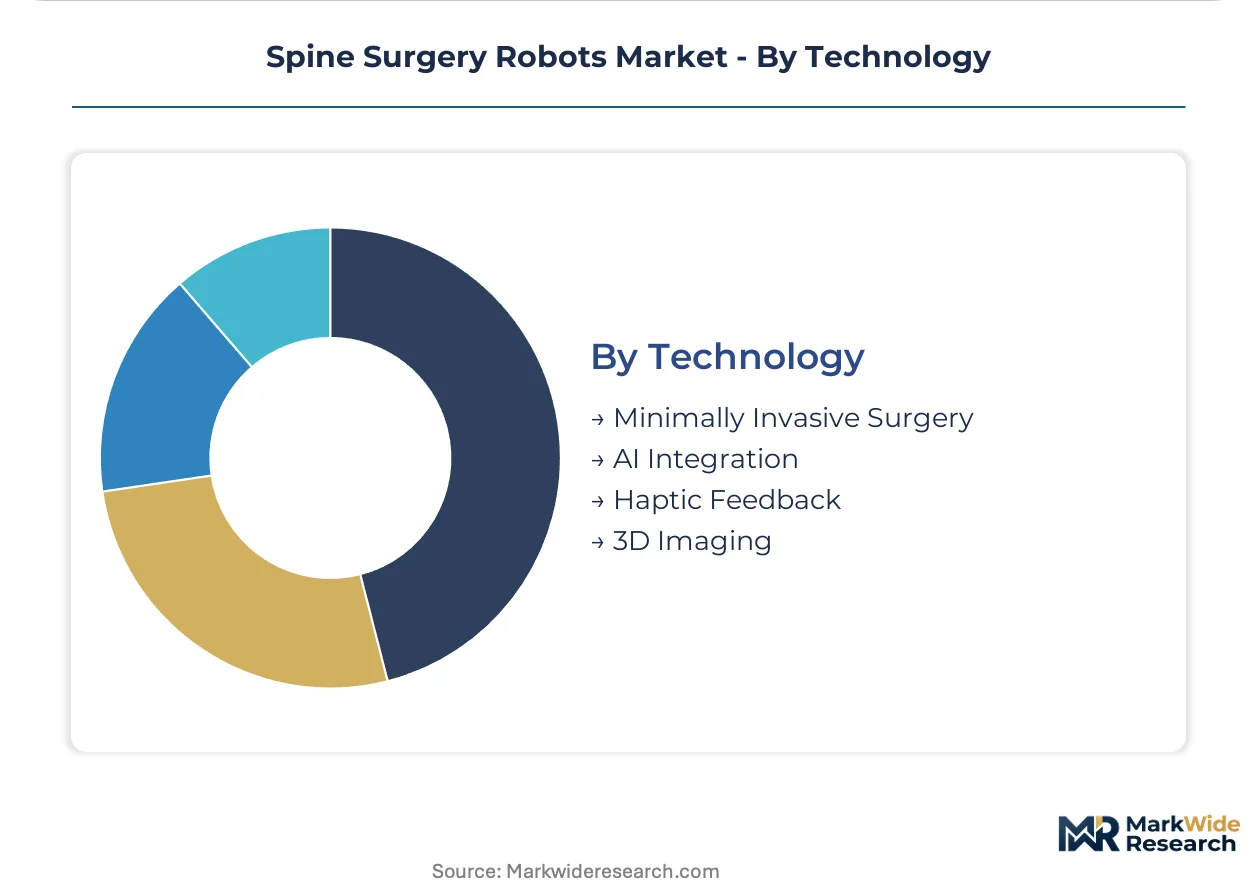
- AI Integration:Machine learning algorithms enable predictive trajectory planning that reduces intraoperative fluoroscopy time. FDA 510(k) clearances for autonomous surgical planning modules are streamlining commercial entry, though EU MDR software validation requirements demand algorithmic traceability demonstrations.
- Minimally Invasive Surgery:Percutaneous and tubular approaches through small incisions reduce tissue disruption and recovery times. Established reimbursement codes and surgeon training pathways sustain demand concentration in high-volume spine centers across United States hospital networks.
- Haptic Feedback:Force-sensing instruments provide tactile response during robotic manipulation.
- 3D Imaging:Preoperative and intraoperative three-dimensional visualization supports complex deformity planning.
Minimally Invasive Surgery holds procedural volume concentration. AI Integration is gaining share fastest as fluoroscopy reduction mandates intensify under OSHA radiation exposure regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways and integrated delivery network procurement consolidation are concentrating spine surgery robot deployments in health systems with capital-efficient financing structures. Reimbursement parity debates under CMS frameworks determine hospital capital allocation cycles across major markets.
United States
Integrated delivery networks in metropolitan markets prioritize turnkey robotic platforms that bundle navigation and after-sales support. OSHA radiation exposure limits drive fluoroscopy reduction mandates that robotic guidance satisfies. Academic medical centers in Boston and New York deploy these systems for complex thoracolumbar deformity corrections.
Germany
University hospitals in Baden-Württemberg and Bavaria evaluate robotic platforms against EU MDR software validation requirements for autonomous planning modules. CE marking under tightened medical device regulations favors established vendors with regulatory infrastructure. The country's statutory health insurance system debates procedure-specific reimbursement codes for robot-assisted spine surgery.
Japan
PMDA regulatory pathways for robotic surgical devices shape commercial entry timelines for manufacturers targeting high-volume spine centers. METI industrial policy supports medical device innovation clusters in the Kanto region. Tokyo-based academic hospitals concentrate complex deformity cases that justify capital-intensive robotic platform acquisitions.
China
NMPA approval processes for Class III medical devices govern market access for international and domestic robotic manufacturers. The country's hospital procurement reform pushes centralized purchasing for high-value medical equipment. Shanghai and Beijing municipal health systems pilot robot-assisted spine procedures in tertiary hospitals with established orthopedic surgery departments.
United Kingdom
NICE technology appraisal processes evaluate cost-effectiveness of robotic spine surgery against conventional techniques for NHS commissioning. MHRA post-Brexit regulatory frameworks align with EU MDR software validation standards for autonomous surgical planning. London teaching hospitals concentrate specialist spine services that attract robotic platform investments.
Spine Surgery Robots Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented vendor tiers. Large diversified medical technology conglomerates leverage installed navigation bases to cross-sell robotic systems through enterprise procurement contracts. Three archetypes dominate: full-platform integrators bundling hardware and software, spine-focused engineering specialists, and navigation-to-robotics cross-sellers. Consolidation through strategic acquisitions and exclusive distribution partnerships reshapes competitive boundaries.
Among full-platform integrators, Stryker and Medtronic occupy positions that exemplify channel-control strategies through integrated delivery network relationships. Globus Medical represents the spine-focused engineering archetype, concentrating development resources on specialized orthopedic applications rather than general surgical diversification. These three companies anchor the competitive structure that smaller specialists and regional technology providers navigate.
| Leading Market Players |
|---|
| Stryker |
| NuVasive |
| Medtronic |
| TINAVI Medical Technologies |
| Brainlab |
| Zimmer Biomet |
| Mazor Robotics |
| CUREXO |
| Globus Medical |
| Others |
Cost & Logistics Intelligence
Optical tracking array and electromechanical arm manufacturing concentrates in precision engineering clusters across Germany, Japan, and the United States, anchoring margin capture in downstream turnkey platform bundling rather than discrete component sales. This upstream concentration forces integrated delivery networks to negotiate enterprise contracts that internalize after-sales support and software update costs into five-year utilization horizons.
Pricing Analysis
Certification level (FDA 510(k)-grade versus CE-marked tiers) creates the primary spread between premium robotic assistance systems and standard navigation modules. Three-tier pricing structure across premium, standard, and economy levels reflects bundled after-sales intensity, optical tracking precision grades, and AI trajectory planning capabilities. Pricing pressure stems from pay-per-procedure financing models that compress upfront hardware margins into usage-based revenue recognition. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize total cost-of-ownership over unit acquisition cost.
Supply Chain Analysis
Contract manufacturing for surgical robot electromechanical assemblies concentrates with specialized medical device EMS providers in Switzerland, Germany, and Massachusetts. Supply chains draw from precision-machined titanium components, high-resolution optical sensors, and FDA-validated software modules. Single-source vulnerability runs through optical tracking array suppliers serving multiple competing OEMs. Distribution runs through direct hospital system contracts negotiated by integrated delivery network procurement committees, bypassing traditional medical device distributors for capital equipment tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spine surgery robotics is crossing into platform-economics territory where navigation-to-robotics interoperability determines vendor stickiness and switching costs. Ecosystem consolidation around turnkey platforms that bundle hardware, software, and after-sales support is reconfiguring competitive moats away from discrete engineering specifications toward data governance and workflow integration depth.
For Market Incumbents: Entrench position through exclusive imaging system partnerships that lock optical tracking compatibility into hospital radiology infrastructure. Deepen backward integration into surgical tool manufacturing to capture disposables revenue streams threatened by third-party instrument suppliers. Priority lever rests on AI trajectory planning R&D that differentiates autonomous screw placement capabilities under tightening FDA software validation requirements. For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgical center pay-per-procedure financing, where capital constraints exclude turnkey platform incumbents from volume penetration. Target cloud-based deployment architectures that appeal to European hospitals navigating EU AI Act algorithmic transparency mandates. Go-to-market angle emphasizes modular navigation upgrades compatible with existing hospital imaging investments rather than rip-and-replace robotics platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed spine-focused engineering specialists possessing EU MDR regulatory infrastructure but lacking integrated delivery network channel control. Five-to-ten year viability hinges on reimbursement parity expansion under CMS frameworks. Signal to watch is procedure-specific coding decisions for robot-assisted thoracolumbar fixation in outpatient settings.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Premarket notification streamlining reduces commercial entry timelines for autonomous planning modules. |
| Hospital System Partnership | Integrated delivery network enterprise contracts consolidate vendor relationships around turnkey platform ecosystems. |
| Software Companion Development | AI trajectory planning applications differentiate platform capabilities under tightening software validation requirements. |
| CE Marking Pathway Investment | EU MDR algorithmic traceability demands favor established regulatory infrastructure over new market entrants. |
| Reimbursement Strategy | CMS procedure-specific coding parity determines capital allocation cycles across hospital procurement committees. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement databases, and EU MDR CE marking registries. Bottom-up procedure volume estimates triangulated against top-down capital expenditure surveys across integrated delivery networks.
Calibration against historical platform deployment rates and utilization curves informed projection modeling across the analysis window. Segmentation dimensions included product type tier, end-user facility category, deployment architecture, and technology maturity gradient. CAGRs were derived from procedure volume elasticity to reimbursement parity shifts and capital expenditure cycle timing. Industry-specific inputs incorporated fluoroscopy reduction mandate intensity under OSHA regulations and AI algorithm regulatory clearance velocity.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, CMS reimbursement rulemaking timelines, or EU MDR software validation interpretation would shift the trajectory. Forecasts reflect documented assumptions regarding procedure migration to ambulatory settings and pay-per-procedure financing penetration rates. Quarterly review of FDA 510(k) clearance cadence and CMS procedure coding updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Nasal Irrigation Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Digital Phoropter Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Next Generation Nebulizers Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
India Biopsy Devices Market