
 Next Generation Nebulizers Market | 2026-2036
Next Generation Nebulizers Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Nebulizers Market Outlook
Modular device platforms that separate drug reservoirs from controller units is realigning how hospitals and homecare buyers evaluate total cost of ownership. Philips leverages its respiratory therapy ecosystem to sustain institutional contracts across European and North American acute care networks. Omron competes through compact, battery-optimized designs that anchor its position in Japanese homecare channels. PARI Pharma differentiates with specialized formulations paired to proprietary nebulizer architectures, occupying a defensible niche in pediatric and cystic fibrosis segments.
Next generation nebulizers are aerosol delivery systems that convert liquid medication into respirable particles, typically targeting mass median aerodynamic diameters between one and five micrometers for optimal deep lung deposition; they serve primarily to administer bronchodilators, corticosteroids, and antibiotics to patients with obstructive or infectious respiratory conditions. Mesh technology leads in value contribution due to silent operation, reduced drug waste, and compatibility with high-viscosity formulations, while portable form factors represent the fastest-expanding configuration as ambulatory care protocols expand. Electronic control systems are concentrating margin pools through connectivity modules that enable dose tracking and remote patient monitoring integration.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape device validation protocols, material biocompatibility testing, and clinical evidence thresholds for market authorization. Japan's PMDA enforces QMS ministerial ordinances that extend manufacturing site inspection requirements to foreign facilities exporting into Japanese distribution. Stakeholders must monitor how reimbursement coding for connected nebulizer systems evolves across Medicare, national health insurance schemes, and private payers to anticipate which feature bundles secure sustainable pricing.
Market Dynamics
Mesh nebulizer technology is electrifying respiratory care delivery by replacing compressor-based systems with silent, battery-powered platforms that enable medication administration outside clinical settings. This shift is compressing hospital dependency for chronic disease management while expanding addressable patient populations through portability and connected monitoring capabilities.
Growth Catalysts
- EU MDR compliance pathways:Harmonized technical documentation requirements under the EU Medical Device Regulation are streamlining CE marking processes for manufacturers, accelerating market access across 27 member states for validated mesh nebulizer platforms.
- Homecare channel expansion:Reimbursement coding revisions in Japan's national health insurance scheme now cover portable nebulizer units for COPD patients, channeling device procurement toward ambulatory settings and reducing acute care utilization.
- Piezoelectric mesh membranes:Advances in micro-perforation manufacturing are improving aerosol consistency and reducing drug residue, enabling high-viscosity antibiotic formulations previously incompatible with traditional jet nebulizers.
Market Restraints
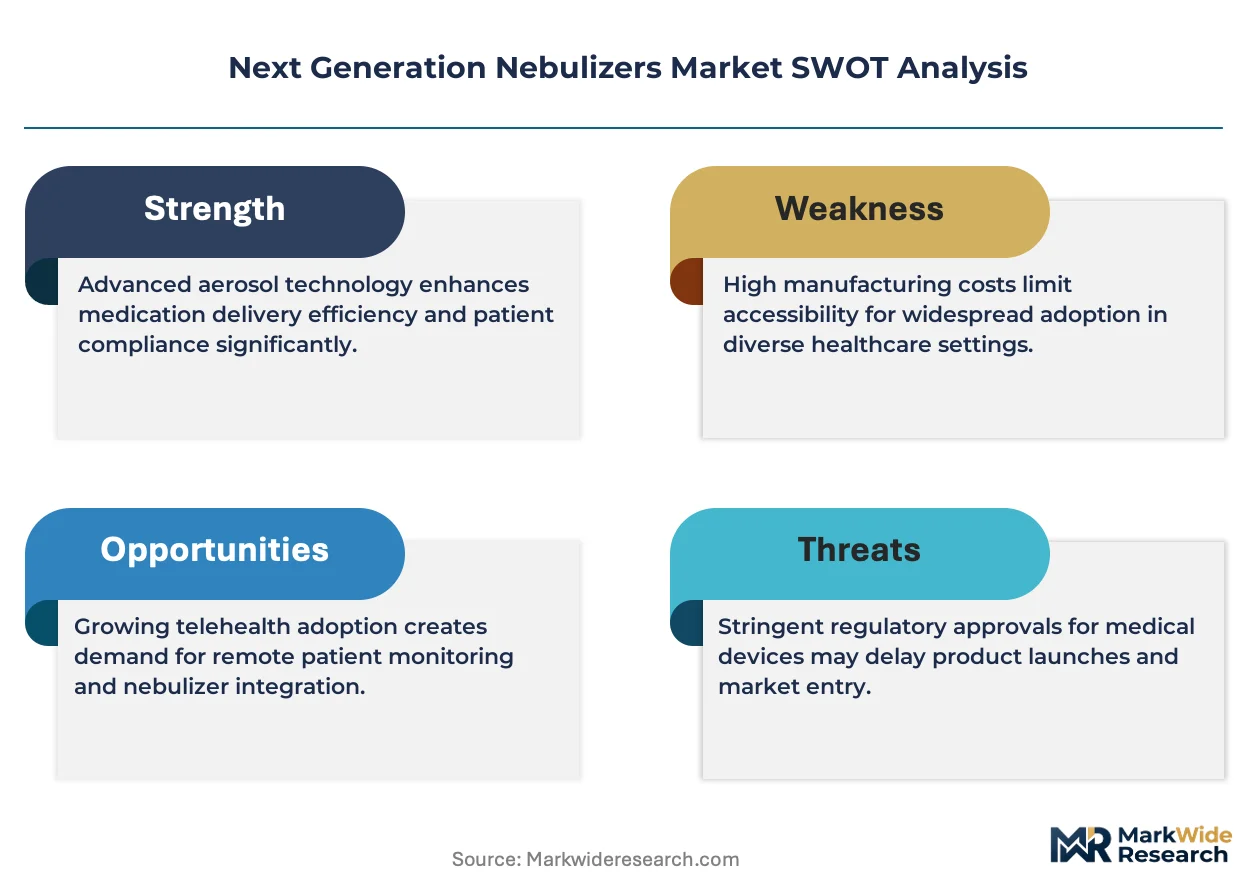
- Precious metal input volatility:Platinum and palladium price fluctuations for piezoelectric transducer coatings are compressing gross margins for manufacturers without long-term supply agreements or alternative material qualifications.
- FDA 510(k) evidentiary thresholds:Substantial equivalence determinations for connected nebulizer systems now require enhanced clinical validation data, extending premarket notification review timelines and deferring revenue recognition for product launches.
- Dry powder inhaler substitution:DPI platforms for bronchodilator delivery are capturing maintenance therapy prescriptions previously served by nebulizers, particularly in asthma management where breath-actuated dosing improves adherence.
Strategic Opportunities
- German cystic fibrosis centers:Specialized care networks in Munich, Berlin, and Hamburg are expanding inhaled antibiotic protocols, creating concentrated demand for high-performance nebulizer systems with validated lung deposition data.
- Bluetooth connectivity modules:Integration of dose-tracking sensors with electronic health record systems is enabling remote patient monitoring reimbursement codes, differentiating premium device tiers through data interoperability.
- US Medicare Advantage supplemental benefits:2024 plan year benefit expansions for connected respiratory devices are opening direct-to-patient distribution channels outside traditional durable medical equipment suppliers.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies for polymer drug reservoir materials are experiencing laboratory backlog, delaying design validation milestones for new product submissions.
- Legacy compressor fleet interoperability:Homecare providers managing mixed device inventories face training complexity and inventory fragmentation as they transition patients from jet to mesh platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Nebulizers Market |
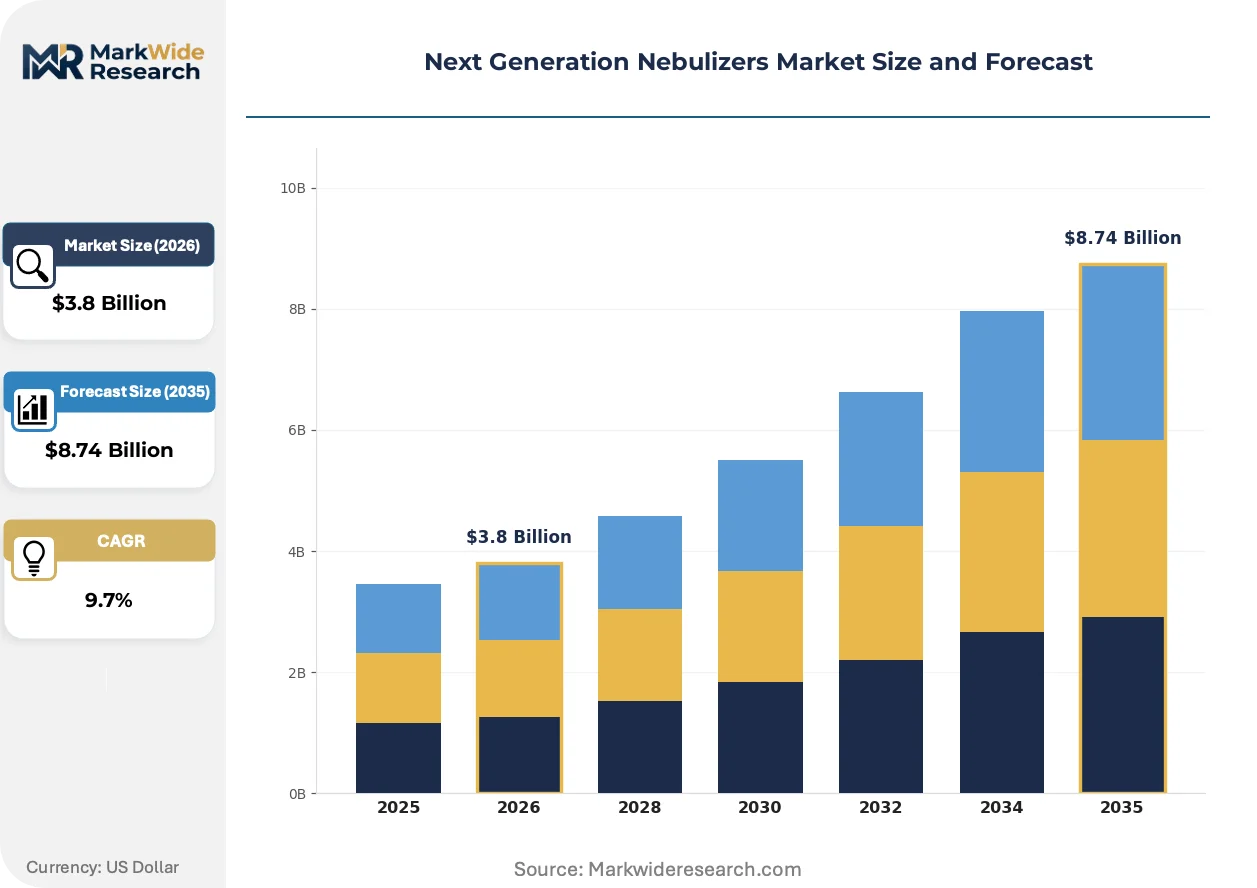
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Handheld, Tabletop, Portable, Ultrasonic Technology: Mesh, Jet, Vibrating, Electronic End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Application: Respiratory Disorders, Anaphylaxis Treatment, Pulmonary Function, Asthma Management |
| Companies Covered | Philips, Omron, PARI Pharma, BD, Briggs Healthcare, Yuwell, Leyi, Folee, 3A Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Nebulizers Market Strategic Shifts
Respiratory device manufacturers are converging hardware miniaturization with software-enabled adherence monitoring, transforming nebulizers from passive delivery tools into active components of integrated disease management ecosystems. This convergence is redefining value capture mechanisms and competitive differentiation strategies.
Vibrating mesh technology is electrifying aerosol generation by replacing compressed air with piezoelectric vibration at 100-200 kHz frequencies, producing consistent 1-5 micron particle distributions. Pediatric pulmonology practices in the United States and Germany are standardizing on these platforms for cystic fibrosis therapy, compressing treatment times from 15-20 minutes to under 10 minutes while improving lung deposition rates.
Japan's PMDA QMS ministerial ordinances are extending manufacturing site inspection requirements to foreign facilities exporting into Japanese distribution, compelling European and North American manufacturers to upgrade quality management documentation and on-site audit readiness. Contract manufacturers in Ireland and Switzerland are investing in dedicated cleanroom capacity to maintain access to this high-value market.
Hospital procurement committees are unbundling device acquisition from consumable supply agreements, shifting toward capital expenditure models that prioritize total cost of ownership calculations over per-unit pricing. This pattern is most visible in United States integrated delivery networks, where standardization across 10-50 facility systems is concentrating purchasing power and favoring vendors with modular platform architectures.
Next Generation Nebulizers Market Segmentation
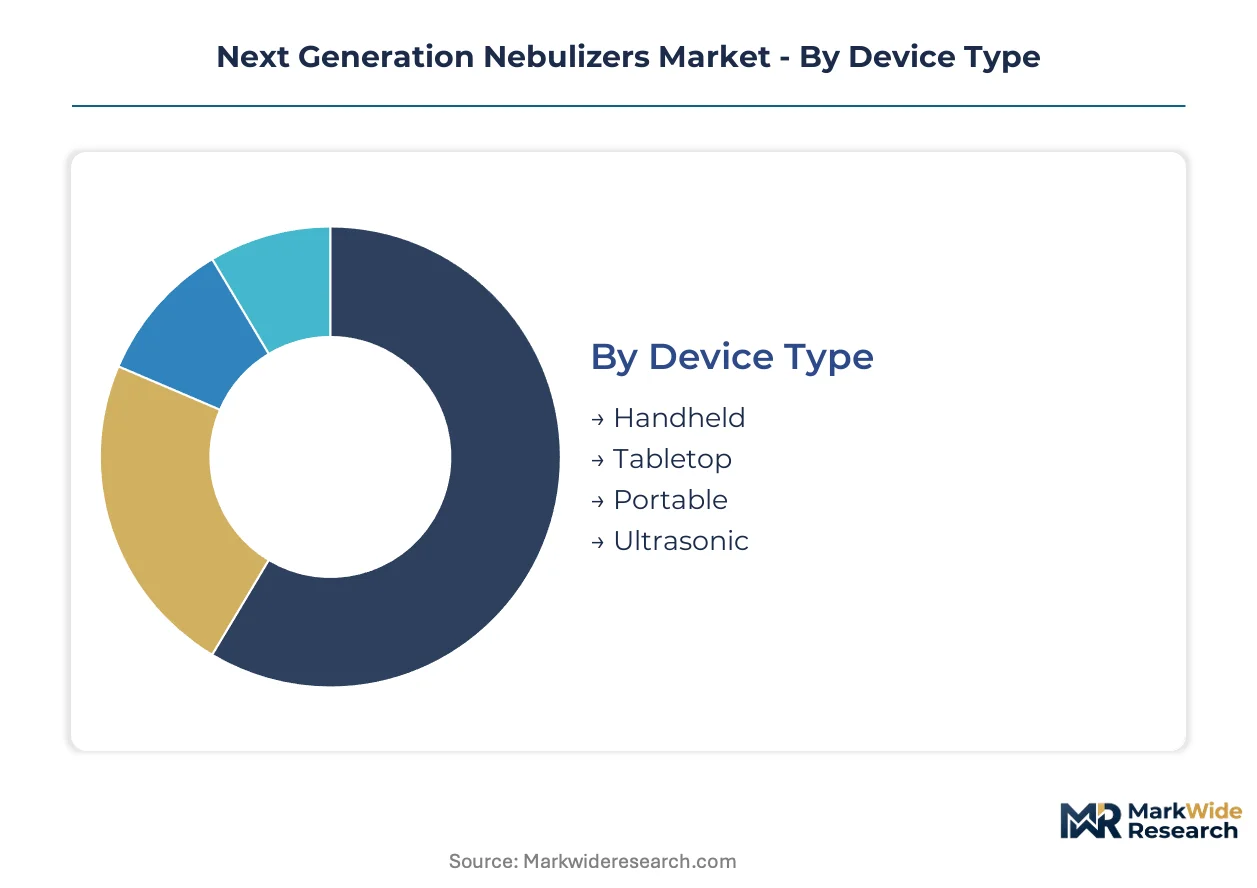
Device configuration determines reimbursement pathways and total cost of ownership for institutional buyers. Technology selection shapes aerosol performance specifications and regulatory submission requirements. Application focus influences clinical validation protocols and prescriber adoption patterns.
Device Type:
Portability requirements drive procurement decisions as care delivery migrates from acute settings to ambulatory environments.
- Handheld:Battery-optimized units weighing under 300 grams enable discrete medication administration during daily activities. Demand clusters in Japanese homecare channels where national health insurance covers portable units for COPD patients, compressing hospital readmission rates.
- Portable:Compact form factors with rechargeable power systems bridge clinical and domestic use cases. German cystic fibrosis centers in Munich and Hamburg are standardizing these platforms for inhaled antibiotic protocols, validating lung deposition data against jet nebulizer benchmarks.
- Tabletop:Stationary units with higher medication capacity serve multi-patient clinical environments. US integrated delivery networks favor these for standardization across facility systems.
- Ultrasonic:High-frequency piezoelectric systems generate aerosol through liquid vibration. Limited adoption due to heat generation affecting thermolabile formulations.
Volume sits with tabletop units in institutional procurement; growth tilts toward handheld configurations as homecare reimbursement expands.
Technology:
Particle generation mechanisms differentiate clinical performance, noise profiles, and formulation compatibility.
- Mesh:Piezoelectric vibration at 100-200 kHz forces medication through micro-perforated membranes, producing consistent 1-5 micron particle distributions. Pediatric pulmonology practices in the United States and Germany favor these for cystic fibrosis therapy, compressing treatment times from 15-20 minutes to under 10 minutes.
- Electronic:Software-controlled dosing with Bluetooth connectivity enables remote patient monitoring integration. US Medicare Advantage supplemental benefits now cover these systems, opening direct-to-patient distribution channels.
- Jet:Compressed air systems remain prevalent in price-sensitive markets and legacy fleet replacements. Homecare providers face training complexity managing mixed inventories during platform transitions.
- Vibrating:Mechanically oscillating elements generate aerosol without compressed air. Niche positioning in specific formulation compatibility scenarios.
Revenue concentrates in mesh platforms; electronic systems are climbing fastest through connected care reimbursement codes.
End User:
Care setting determines device durability requirements, training support needs, and regulatory oversight intensity.
- Homecare:Patient-operated devices require simplified interfaces and adherence monitoring capabilities. Japan's national health insurance scheme revisions channel procurement toward ambulatory settings, reducing acute care utilization for chronic respiratory disease.
- Hospitals:Acute care networks prioritize interoperability with electronic health records and centralized fleet management. Procurement committees unbundle device acquisition from consumable agreements, favoring capital expenditure models.
- Clinics:Outpatient facilities balance patient throughput with capital constraints. Standardization pressures concentrate purchasing power across multi-site systems.
- Rehabilitation Centers:Post-acute facilities manage transitional respiratory therapy. Device selection emphasizes durability under intensive use cycles.
Institutional procurement dominates unit volume; homecare channels show steepest expansion trajectory as chronic disease management shifts beyond hospital walls.
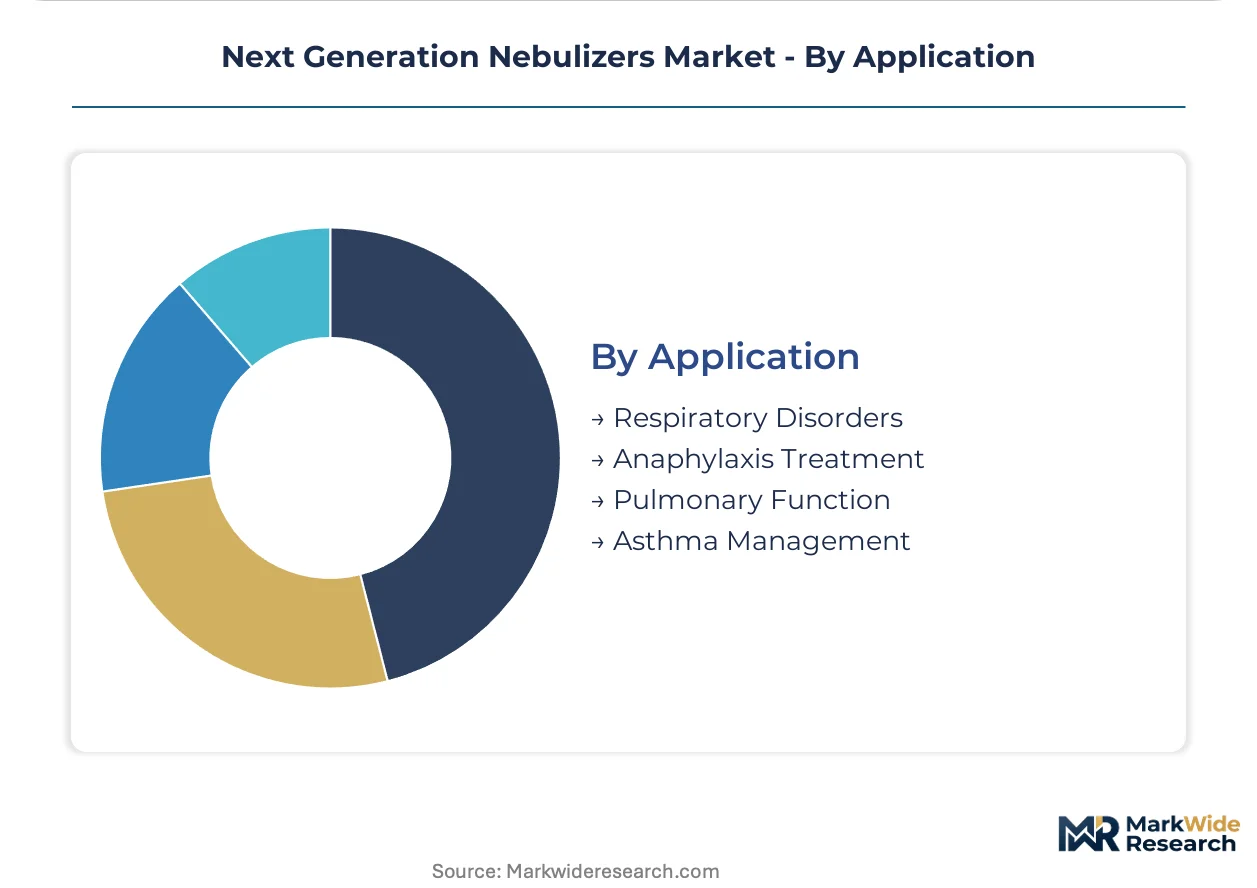
Application:
Therapeutic indication shapes aerosol specification requirements and clinical evidence thresholds for regulatory authorization.
- Respiratory Disorders:Broad category encompassing COPD, bronchiectasis, and interstitial lung disease. FDA 510(k) premarket notifications for connected systems now require enhanced clinical validation data, extending review timelines.
- Asthma Management:Maintenance and rescue therapy applications face substitution pressure from dry powder inhalers capturing bronchodilator prescriptions through breath-actuated dosing.
- Pulmonary Function:Diagnostic and therapeutic aerosol delivery for lung function assessment. Specialized protocols in German care networks drive demand for validated deposition data.
- Anaphylaxis Treatment:Emergency epinephrine delivery via nebulized routes. Niche application with distinct regulatory pathways.
Chronic respiratory disorders anchor installed base; pulmonary function applications are gaining share fastest through specialized care network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate piezoelectric component manufacturing for mesh nebulizer membranes, drawing contract manufacturers seeking proximity to precision electronics supply chains.
United States
Medicare Advantage supplemental benefit expansions for connected respiratory devices are channeling procurement toward ambulatory settings. FDA 510(k) premarket notification requirements now demand enhanced clinical validation data for Bluetooth-enabled systems. Integrated delivery networks in Texas and Florida are standardizing fleet purchases across multi-facility systems.
Germany
Cystic fibrosis centers in Munich, Berlin, and Hamburg are expanding inhaled antibiotic protocols, validating lung deposition data for high-performance nebulizer platforms. EU MDR technical documentation obligations are streamlining CE marking processes for validated mesh devices. Baden-Württemberg's medical technology cluster anchors precision manufacturing for piezoelectric transducer components.
Japan
PMDA QMS ministerial ordinances are extending manufacturing site inspection requirements to foreign facilities exporting into Japanese distribution. National health insurance scheme revisions now cover portable nebulizer units for COPD patients, compressing hospital readmission rates. Kansai region manufacturers dominate compact, battery-optimized designs for homecare channels.
China
Domestic manufacturers are capturing price-sensitive segments through cost-optimized jet nebulizer production. NMPA medical device registration requirements are tightening biocompatibility testing protocols for polymer drug reservoir materials. Yangtze River Delta electronics hubs supply micro-perforation equipment for mesh membrane fabrication.
Switzerland
Swissmedic quality system requirements are elevating documentation standards for manufacturers targeting premium device tiers. Contract manufacturers in Basel and Zurich are investing in dedicated cleanroom capacity to maintain Japanese market access. Precision engineering clusters specialize in piezoelectric transducer coatings using alternative materials to precious metal inputs.
Next Generation Nebulizers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale advantages clash with formulation-specific expertise. The market concentrates around three strategic archetypes: respiratory therapy ecosystem integrators, compact portable device specialists, and formulation-paired platform developers. M&A activity is consolidating component supply chains, while strategic partnerships between device manufacturers and pharmaceutical firms are locking in proprietary nebulizer architectures for specialized therapies.
Within the ecosystem integrator tier, Philips and BD exemplify diversified health technology conglomerates leveraging institutional contracts across acute care networks. Omron occupies a position among Japanese precision manufacturers optimizing battery-efficient designs for homecare channels. PARI Pharma represents the formulation-paired specialist archetype, anchoring defensible positioning in pediatric and cystic fibrosis segments through proprietary device-drug combinations.
| Leading Market Players |
|---|
| Philips |
| Omron |
| PARI Pharma |
| BD |
| Briggs Healthcare |
| Yuwell |
| Leyi |
| Folee |
| 3A Health Care |
| Others |
Value Chain & Pricing Dynamics
EU MDR biocompatibility testing mandates for polymer drug reservoir materials are gating qualified supply access and compressing premium-tier pricing power for manufacturers lacking ISO 10993 validation documentation. This regulatory filter concentrates margin capture among firms with pre-qualified material streams while forcing cost absorption elsewhere.
Pricing Analysis
Margin tightening in economy-tier jet nebulizers reflects Chinese domestic manufacturers capturing price-sensitive segments through cost-optimized production. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance status and Bluetooth connectivity integration. Pricing pressure intensifies in standard-tier mesh devices as Japanese and German manufacturers compete for European homecare contracts. Hospital procurement committees exhibit lowest price sensitivity due to total cost of ownership calculations favoring durability and EHR interoperability.
Supply Chain Analysis
Piezoelectric transducer coatings rest on platinum and palladium inputs sourced from South African and Russian mining operations, creating precious metal dependency for mesh membrane manufacturers. Precision micro-perforation equipment feeds from Yangtze River Delta electronics hubs in China, while polymer drug reservoir molding concentrates in German and Swiss medical device clusters. Single-source vulnerability in piezoelectric ceramic supply exposes manufacturers to commodity price volatility and geopolitical disruption. Distribution runs through specialized durable medical equipment suppliers in North America, direct-to-hospital contracts in Germany, and national health insurance channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocompatibility testing laboratory capacity constraints are propping pricing for qualified manufacturers while extending lead times for market entrants lacking pre-validated material streams.
For Market Incumbents: To counter dry powder inhaler substitution in asthma maintenance therapy, anchor hospital system contracts through modular platform architectures that unbundle device acquisition from consumable supply agreements. Deepen backward integration into piezoelectric transducer production through captive supply agreements with South African precious metal refiners, securing margin insulation against input volatility. For New Entrants and Emerging Players: The price-point gap between premium connected mesh systems and economy jet nebulizers creates white-space opportunity in portable standard-tier devices for Japanese homecare channels. Target reimbursement coding expansion in US Medicare Advantage supplemental benefits as the most penetrable entry vector, leveraging direct-to-patient distribution models outside traditional durable medical equipment supplier networks. For Investors and Strategic Acquirers: FDA 510(k) clearance timelines extending for Bluetooth-enabled systems is the leading indicator that regulatory capacity is constraining competitive entry and supporting incumbent pricing power. Acquisition targets should profile as formulation-paired specialists with proprietary device architectures in pediatric or cystic fibrosis segments, where clinical validation data creates defensible positioning. Watch EU MDR notified body capacity expansion as the signal for accelerated competitive entry into European markets.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation streamlines market access across 27 member states for validated platforms. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida concentrate purchasing power through fleet standardization. |
| Software Companion Development | Bluetooth dose-tracking sensors enable remote patient monitoring reimbursement codes in US Medicare Advantage. |
| Reimbursement Strategy | Japan's national health insurance scheme revisions channel portable unit procurement toward ambulatory settings. |
| Backward Integration | Captive piezoelectric transducer production insulates margins from platinum and palladium price volatility. |
Study Parameters
Document review covered FDA 510(k) premarket notification databases, EU MDR technical documentation guidance, and Japanese PMDA QMS ministerial ordinances, complemented by interviews with respiratory therapy product managers, hospital biomedical engineers, GPO contracts managers, and homecare durable medical equipment suppliers. Secondary validation drew from CMS Medicare reimbursement coding updates, German cystic fibrosis center procurement records, and piezoelectric component trade flow data. Bottom-up unit demand modeling triangulated against top-down market size estimates from regulatory filing analysis.
Cross-referencing historical approval timelines with expert panel input on EU MDR notified body capacity shaped the forecast framework across the analysis window. Segmentation dimensions modeled include device configuration, technology type, end user setting, and therapeutic application. CAGRs derived from growth driver elasticity analysis against reimbursement expansion trajectories and chronic respiratory disease prevalence projections. Forecast inputs incorporated piezoelectric membrane yield rates and biocompatibility testing laboratory throughput constraints.
Underlying measurement precision varies by segment; homecare channel volume estimates carry tighter precision than emerging market replacement projections due to data availability. Forecasts reflect assumptions on regulatory clearance timeline normalization and reimbursement coding stability. Supply chain disruption, precious metal price spikes, or notified body capacity constraints warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nanomedical Devices Market
Medical Devices
Powered Mattress System Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Patellar Implant Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Global Photomedicine Market