
 UAE Respiratory Devices Market | 2026-2036
UAE Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Respiratory Devices Market Analytics
The UAE respiratory devices market is rebalancing between premium connected systems and commodity oxygen delivery equipment as reimbursement tiers diverge under mandatory insurance expansion. ResMed leverages its cloud-connected CPAP ecosystem to anchor the sleep apnea segment across Dubai's private hospital networks. Philips sustains broad portfolio coverage from acute ventilators to home nebulizers, competing on brand recognition with government procurement bodies. Fisher & Paykel Healthcare differentiates through humidification technology leadership, occupying a defensible niche in intensive care applications.
Respiratory devices encompass electromechanical apparatus designed to assist, monitor, or replace spontaneous breathing, incorporating flow sensors, pressure valves, and filtration media typically rated for particle retention below 0.3 microns, with primary purpose spanning chronic disease management, acute respiratory failure intervention, and sleep-disordered breathing correction. CPAP machines and smart inhalers represent the fastest-expanding product categories as digital health integration shifts margin pools toward data-enabled adherence monitoring, while oxygen concentrators remain mature with pricing pressure from standardized procurement. The homecare end user segment is gaining structural prominence as post-discharge protocols and remote patient monitoring platforms reduce hospital length of stay.
MOHAP's medical device registration requirements and the UAE's health insurance mandate shape product standards by requiring clinical evidence submissions and coverage-linked reimbursement codes for market access. BIS-equivalent conformity assessments and post-market surveillance obligations from the Emirates Authority for Standardization and Metrology add compliance layers that favor established multinationals with regulatory affairs infrastructure. Stakeholders must monitor how Dubai's health tourism initiatives and Abu Dhabi's specialized pulmonology center expansions redirect procurement volumes between acute and ambulatory settings.
Market Dynamics
The UAE respiratory devices market is rebalancing around mandatory health insurance expansion and MOHAP's tightened registration pathways, which are compressing margin pools toward clinically validated, reimbursement-eligible systems while marginalizing non-certified equipment.
Growth Catalysts
- MOHAP Registration Tiering:The ministry's risk-based classification system accelerates approval timelines for connected monitoring devices, channeling investment toward digital health-integrated portfolios.
- Homecare Infrastructure:Post-acute discharge protocols across Dubai Health Authority facilities are extending device utilization into residential settings, expanding addressable volume beyond hospital procurement.
- Abu Dhabi Specialist Clustering:Cleveland Clinic Abu Dhabi and Sheikh Shakhbout Medical City's pulmonology centers concentrate demand for high-acuity ventilators and humidification systems.
Market Restraints
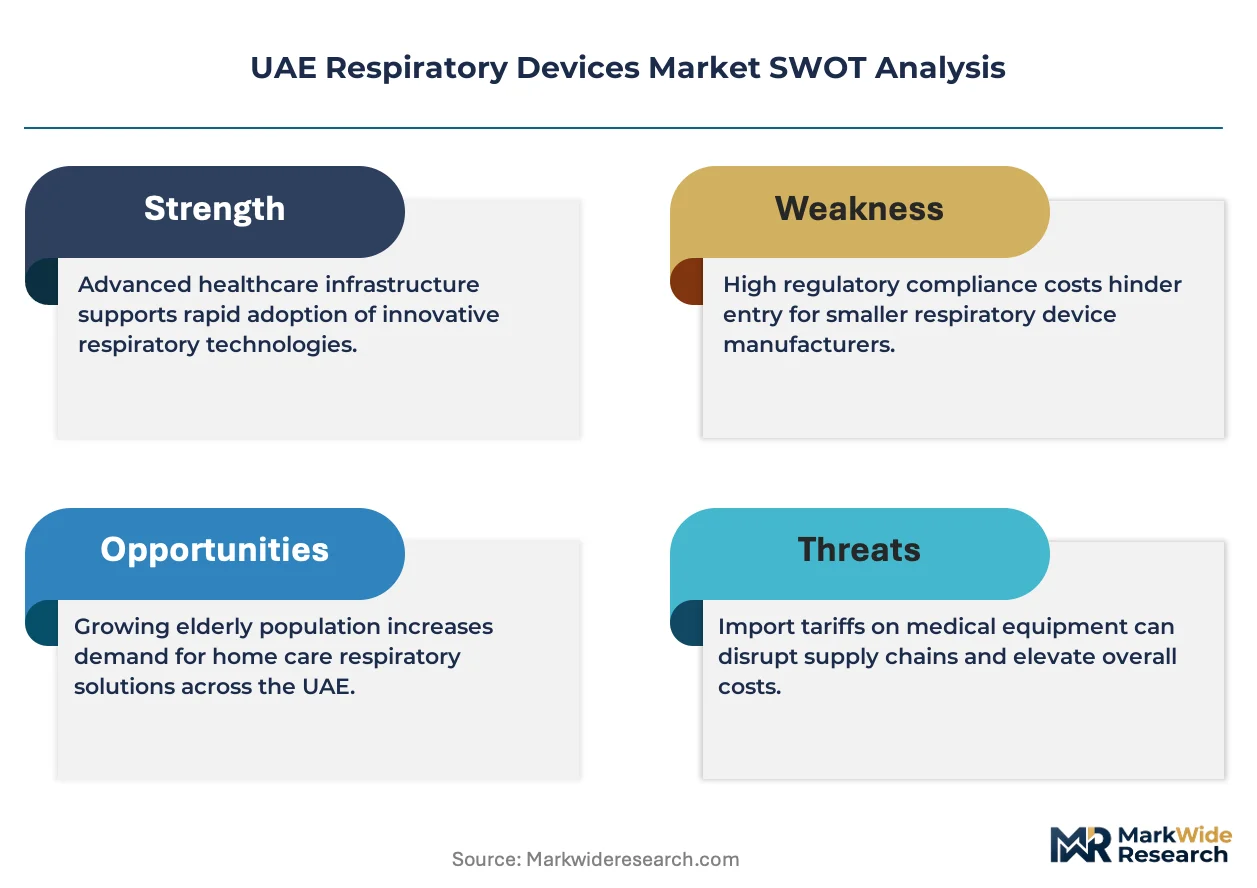
- Import Dependency:Over 90 percent of device supply originates from US, European, and East Asian manufacturing bases, exposing distributors to freight volatility and currency fluctuation.
- Reimbursement Compression:Standardized procurement under mandatory insurance schemes limits price realization on mature oxygen concentrator categories.
- Technical Talent Scarcity:Biomedical engineering specialization in respiratory therapeutics remains underdeveloped within UAE technical institutes, constraining local service infrastructure.
Strategic Opportunities
- Remote Patient Monitoring Convergence:Integration of CPAP adherence data with Dubai Health Authority's electronic health record platforms creates subscription revenue streams for device-software bundles.
- Ras Al Khaimah Manufacturing Zone:Free zone incentives and proximity to Saudi Arabian import corridors position the emirate for regional distribution hub development.
- Health Tourism Protocols:Dubai's medical visa frameworks attract Gulf Cooperation Council patients requiring sleep apnea intervention, expanding private clinic device procurement.
Industry Challenges
- Post-Market Surveillance Burden:Emirates Authority for Standardization and Metrology's adverse event reporting requirements demand dedicated regulatory affairs staffing that strains mid-tier distributor operations.
- Interoperability Fragmentation:Proprietary data protocols between competing connected inhaler platforms complicate hospital IT integration and patient handoff workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Respiratory Devices Market |
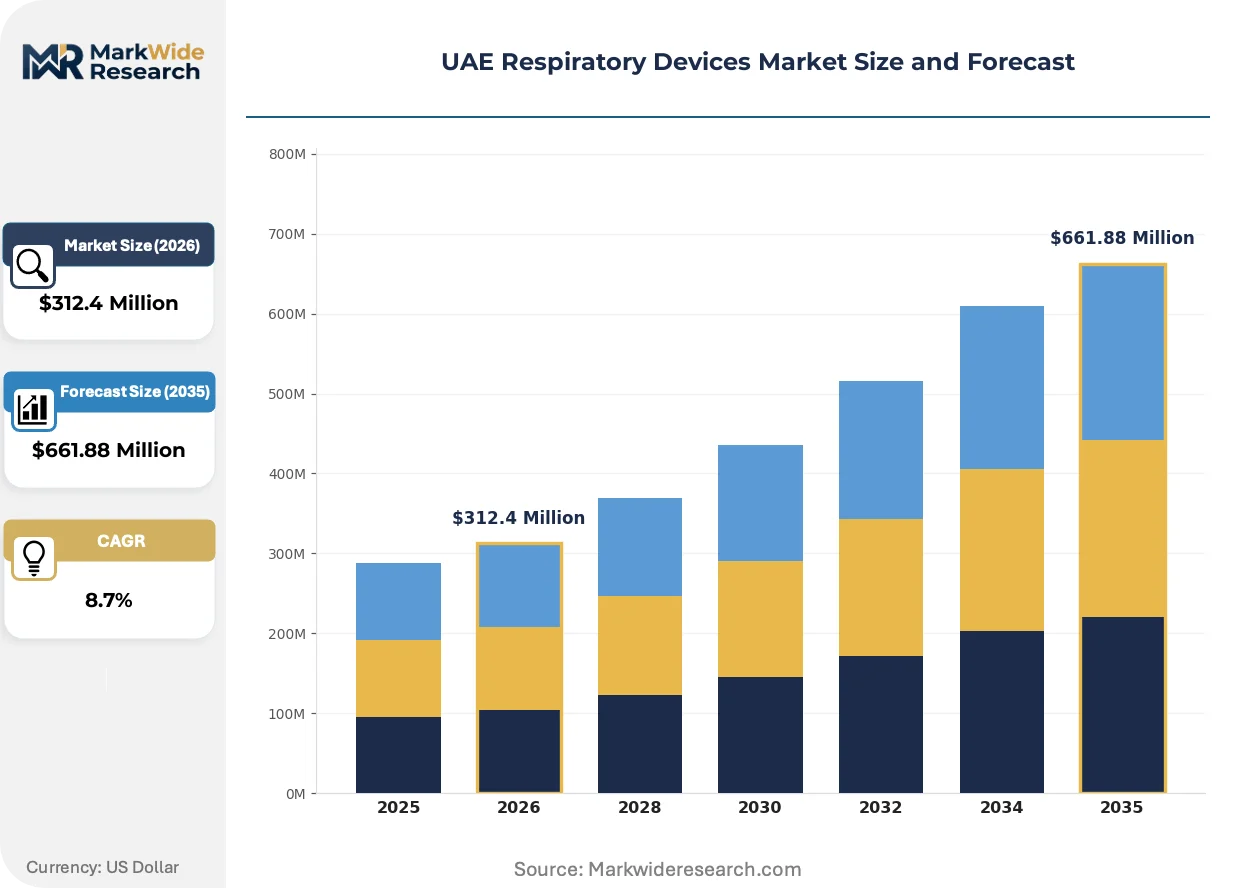
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Machines, Oxygen Concentrators Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Pulmonary Hypertension End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Technology: Electromechanical, Digital Health, Smart Inhalers, Portable Devices |
| Companies Covered | ResMed, Koninklijke Philips N.V, GE Healthcare, Medtronic, Fisher & Paykel Healthcare Ltd, ICU Medical, Drägerwerk AG & Co. KGaA, B. Braun SE, Masimo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Respiratory Devices Market Evolving Landscape
Digital health integration is compressing traditional hardware margins while creating new value pools in adherence analytics and remote therapeutic monitoring across UAE healthcare networks.
Cloud-connected CPAP ecosystems with integrated humidification control and over-the-air pressure adjustment are consolidating the sleep apnea segment around platform vendors capable of delivering longitudinal patient data to payers. Dubai's private hospital networks are prioritizing these systems for health tourism patients requiring documented compliance for insurance continuity. The technology is consolidating procurement decisions toward full-stack providers and marginalizing standalone device distributors lacking software capabilities.
MOHAP's 2023 medical device registration amendments now require clinical evidence submissions for Class II and III respiratory equipment, extending approval timelines but elevating quality benchmarks. Manufacturers are responding by pre-submission engagement with the ministry's technical review committees and investment in local clinical trial infrastructure. The policy most acutely affects nebulizer and ventilator categories where historical self-certification pathways are closing.
Hospital procurement committees are unbundling device acquisition from preventive maintenance contracts, compressing vendor margins on after-sales service while expanding third-party technical service provider opportunities. This disintermediation is most visible in Abu Dhabi's SEHA network facilities, where independent biomedical service firms now compete for multi-year maintenance tenders previously captive to original equipment manufacturers.
UAE Respiratory Devices Market Segmentation
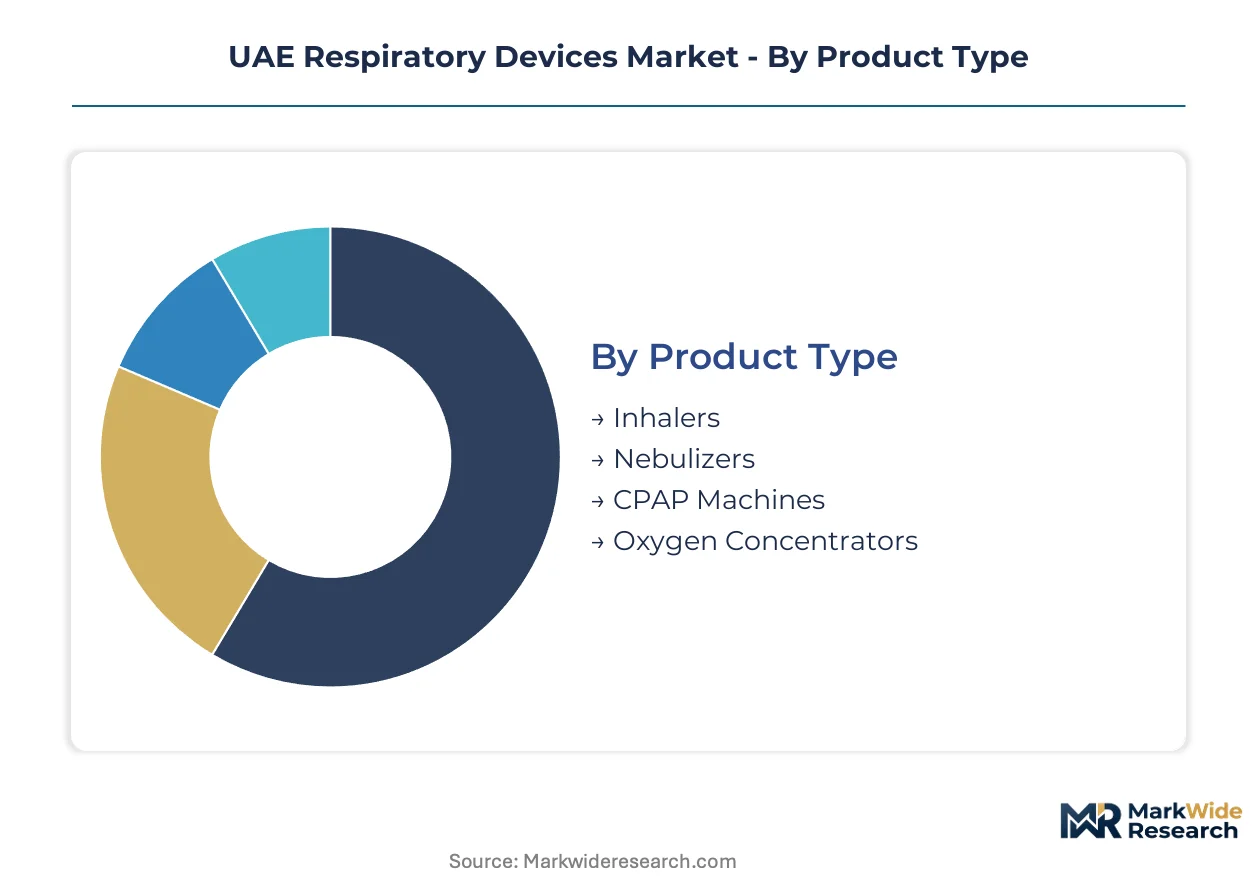
Segmentation in the UAE respiratory devices market reveals distinct procurement patterns across care settings and technology tiers. Understanding these divisions helps stakeholders align product portfolios with reimbursement pathways and facility capabilities.
Product Type:
Cost tier differentiation separates premium connected systems from basic oxygen delivery equipment in hospital and homecare procurement.
- CPAP Machines:Cloud-connected platforms with integrated humidification and remote pressure adjustment dominate sleep apnea management. Dubai's private hospital networks prioritize these systems for health tourism patients requiring documented adherence for insurance continuity.
- Oxygen Concentrators:Pressure swing adsorption units delivering 1-10 liters per minute flow rates face standardized procurement pricing under mandatory insurance schemes. Abu Dhabi SEHA facilities drive volume through post-acute discharge protocols extending into residential settings.
- Inhalers:Metered-dose and dry powder devices for bronchodilator delivery concentrate in asthma and COPD maintenance protocols across UAE outpatient clinics.
- Nebulizers:Compressor and mesh technologies for aerosolized medication delivery serve pediatric and geriatric populations with coordination difficulties in Dubai Health Authority facilities.
CPAP machines lead volumes today; smart inhaler platforms are gaining share fastest through digital health integration.
Application:
Volume concentration tracks disease prevalence and specialist center clustering across emirates.
- Sleep Apnea:Obstructive and central sleep-disordered breathing correction drives demand for diagnostic polysomnography and therapeutic CPAP in Cleveland Clinic Abu Dhabi and Sheikh Shakhbout Medical City pulmonology units.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation management requires long-term oxygen therapy and nebulized bronchodilators among UAE's aging expatriate population in Ras Al Khaimah rehabilitation centers.
- Asthma:Reversible airway obstruction treatment concentrates in pediatric and allergy specialist clinics across Dubai's private healthcare networks.
- Pulmonary Hypertension:Elevated pulmonary artery pressure management demands high-acuity ventilators and inhaled prostacyclin delivery systems in tertiary cardiac-pulmonary units.
COPD applications anchor current procurement volumes; sleep apnea interventions are expanding most quickly through health tourism channels.
End User:
Customer type determines regulatory pathway complexity and service infrastructure requirements.
- Homecare:Post-discharge respiratory support through portable oxygen and CPAP systems extends hospital length-of-stay reduction protocols into residential settings across Dubai Health Authority catchment areas.
- Hospitals:Acute respiratory failure intervention and perioperative ventilation demand intensive care ventilators and humidification systems in Abu Dhabi's SEHA network privatized facilities.
- Clinics:Outpatient diagnostic and maintenance therapy for asthma and sleep apnea concentrates device procurement in Dubai's specialist pulmonology centers.
- Rehabilitation Centers:Post-acute weaning and respiratory muscle training utilize portable ventilators and incentive spirometry in Ras Al Khaimah long-term care facilities.
Hospitals dominate absolute spending today; homecare channels are climbing the fastest as remote monitoring platforms mature.
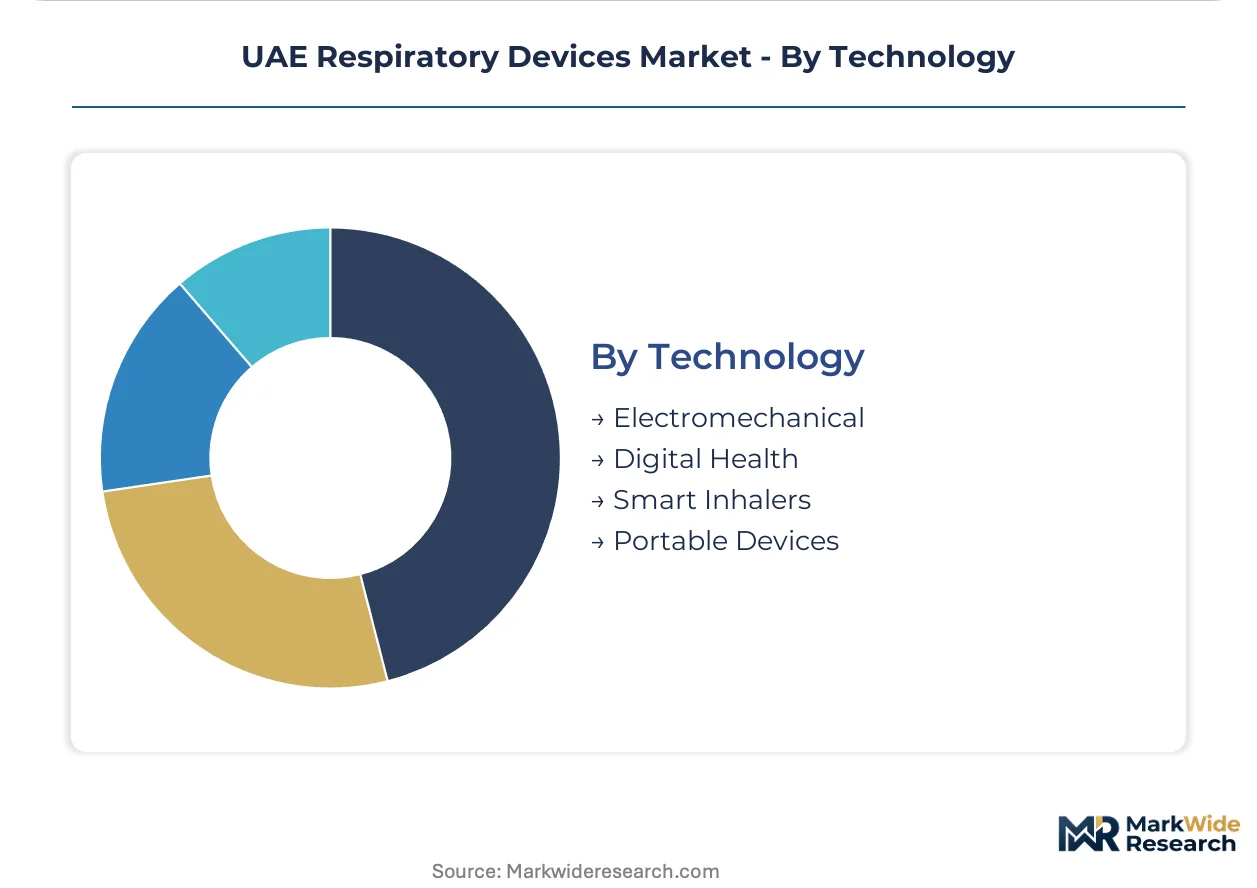
Technology:
Margin structure diverges sharply between commodity electromechanical platforms and data-enabled connected systems.
- Digital Health:Cloud-based adherence monitoring and electronic health record integration create subscription revenue streams alongside hardware sales in Dubai's insurance-linked procurement frameworks.
- Smart Inhalers:Bluetooth-enabled dose counters and geolocation tracking improve medication compliance in pediatric asthma management across UAE specialist clinics.
- Electromechanical:Piston compressors and pressure valves without connectivity face pricing pressure in standardized oxygen concentrator and basic nebulizer categories.
- Portable Devices:Battery-powered miniaturization enables ambulatory oxygen and travel CPAP for health tourism patients requiring treatment continuity across GCC borders.
Electromechanical systems retain volume leadership today; digital health platforms show the steepest expansion trajectory through reimbursement-linked outcomes contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Abu Dhabi command the majority of respiratory device procurement volumes, while Sharjah and the Northern Emirates are developing specialized distribution capabilities to capture spillover demand from the two dominant healthcare hubs.
Dubai
Dubai Health Authority facilities drive concentrated demand for CPAP systems and portable oxygen concentrators through post-acute discharge protocols. MOHAP's medical device registration tiering accelerates approval timelines for connected monitoring equipment entering Dubai's private hospital networks. Dubai Healthcare City clusters specialist pulmonology centers that attract health tourism patients requiring documented adherence for insurance continuity.
Abu Dhabi
SEHA network privatization concentrates procurement of high-acuity ventilators and humidification systems in Cleveland Clinic Abu Dhabi and Sheikh Shakhbout Medical City. Mandatory health insurance expansion under the Thiqa program standardizes reimbursement codes for respiratory therapeutics across Abu Dhabi facilities. Al Ain sub-region rehabilitation centers extend device utilization into residential settings for aging expatriate populations.
Sharjah
Sharjah's University Hospital and specialized respiratory clinics generate steady demand for nebulizers and pediatric asthma management devices. The emirate's medical device distributors leverage proximity to Dubai's procurement committees while maintaining lower operational overhead. Sharjah Healthcare City is attracting secondary pulmonology practices displaced by Dubai's premium real estate costs.
Ras Al Khaimah
Ras Al Khaimah Economic Zone incentives position the emirate for regional distribution hub development targeting Saudi Arabian import corridors. Post-acute rehabilitation facilities in the emirate utilize portable ventilators and incentive spirometry for respiratory muscle training. The northern location offers freight cost advantages for European and East Asian manufacturers serving Gulf Cooperation Council markets.
Northern Emirates
Fujairah and Umm Al Quwain healthcare facilities rely on Dubai-based distributors for respiratory device supply, creating intermediary margin opportunities. MOHAP's standardized registration requirements enable seamless product transfer across emirate borders. Ajman's growing medical tourism segment is developing sleep apnea diagnostic capabilities to capture price-sensitive patients from neighboring emirates.
UAE Respiratory Devices Market Competitive Landscape
Top-tier vendors anchor premium connected system procurement in Dubai and Abu Dhabi private networks, while mid-tier distributors compete on service reach and maintenance contracts for standardized oxygen delivery equipment. The vendor structure stratifies across three archetypes: full-stack platform providers with cloud-connected portfolios, specialized humidification technology developers, and diversified medical technology conglomerates with broad respiratory coverage. Competitive positioning depends on MOHAP registration infrastructure and local clinical trial capabilities. M&A activity concentrates on digital health integration assets, while capacity expansion targets Ras Al Khaimah free zone manufacturing for regional export.
Among the named participants, ResMed and Koninklijke Philips N.V exemplify contrasting platform strategies within the sleep apnea and respiratory monitoring segments. Fisher & Paykel Healthcare Ltd occupies a specialist position in humidification technology for intensive care applications. These three companies represent distinct competitive archetypes: the cloud-connected ecosystem provider, the diversified health technology conglomerate, and the focused therapeutic device specialist.
| Leading Market Players |
|---|
| ResMed |
| Koninklijke Philips N.V |
| GE Healthcare |
| Medtronic |
| Fisher & Paykel Healthcare Ltd |
| ICU Medical |
| Drägerwerk AG & Co. KGaA |
| B. Braun SE |
| Masimo |
| Others |
Value Network & Pricing Analysis
Pressure swing adsorption zeolite beds and compressor motor assemblies originate from East Asian manufacturing clusters, flowing through Dubai's Jebel Ali port to reach Abu Dhabi SEHA procurement committees and Ras Al Khaimah distribution hubs, with freight volatility and currency fluctuation compressing margins on oxygen concentrator categories already squeezed by mandatory insurance reimbursement codes.
Pricing Analysis
Capacity additions in China's respiratory device component sector are reshaping price floors for electromechanical oxygen delivery equipment. Three-tier pricing structure across premium connected systems, standard hospital-grade units, and economy homecare devices separates cloud-integrated CPAP platforms with adherence analytics from basic pressure swing adsorption concentrators. Pricing pressure stems from MOHAP's standardized procurement under mandatory insurance schemes. Homecare patients and post-acute discharge populations exhibit highest price sensitivity; private hospital networks purchasing for health tourism demonstrate lowest sensitivity due to insurance-linked reimbursement continuity.
Supply Chain Analysis
Refurbishment flows for CPAP machines and ventilators circulate through Dubai's biomedical service providers, extending equipment lifecycles and creating secondary parts markets. Manufacturing concentration rests on China, Germany, and the United States for precision flow sensors, pressure valves, and filtration media rated below 0.3 microns. Raw material dependencies include medical-grade polymers, rare-earth magnets for motor assemblies, and lithium-ion cells for portable device power systems. Single-source vulnerability concentrates in semiconductor components for connected monitoring platforms. Distribution runs through Dubai-based authorized distributors serving MOHAP-registered channels across all seven emirates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digital health-integrated portfolios where remote monitoring subscriptions offset hardware commoditization, driven by cloud-connected adherence analytics and preventive maintenance contract unbundling.
For Market Incumbents: Cement platform dominance by deepening software capabilities around electronic health record integration with Dubai Health Authority systems and acquiring local biomedical service firms to capture multi-year maintenance tenders previously captive to original equipment manufacturers. Threat substitution from third-party technical service providers demands channel control through preventive maintenance contract bundling. For New Entrants and Emerging Players: MOHAP's 2023 medical device registration amendments in the UAE open a window for connected inhaler platforms with Bluetooth-enabled dose counters targeting pediatric asthma management in Dubai's specialist clinics. White-space targets include portable ventilator categories for Ras Al Khaimah rehabilitation centers and travel CPAP devices for GCC health tourism corridors. Go-to-market through Dubai Healthcare City specialist pulmonology centers offers lowest regulatory friction. For Investors and Strategic Acquirers: Roll-up economics work for regional distribution platforms because MOHAP registration infrastructure creates high switching costs and captive supplier relationships. Long-term viability over the coming decade hinges on digital health integration capabilities and local clinical trial infrastructure. Target acquisition archetype: mid-tier distributors with established MOHAP registration portfolios and service infrastructure. Monitor Dubai Health Authority's remote patient monitoring platform procurement for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Pre-Submission Engagement | Accelerates approval timelines for Class II and III connected monitoring devices entering Dubai private networks. |
| Cloud-Connected CPAP Ecosystem Development | Captures subscription revenue streams alongside hardware through Dubai insurance-linked outcomes contracts. |
| Local Biomedical Service Firm Acquisition | Secures multi-year maintenance tenders in Abu Dhabi's SEHA privatized facilities disintermediating original equipment manufacturers. |
| Ras Al Khaimah Free Zone Manufacturing Footprint | Positions regional distribution hub targeting Saudi Arabian import corridors with freight cost advantages. |
| Electronic Health Record Integration Partnership | Enables longitudinal patient data delivery to Dubai Health Authority payers for health tourism compliance documentation. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and the Northern Emirates, with primary inputs from each combining structured interviews with hospital procurement committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at MOHAP with secondary validation through hospital procurement databases, GPO contract filings, Emirates Authority for Standardization and Metrology adverse event reports, and customs import records. Bottom-up and top-down triangulation cross-validates segment-level estimates against aggregate market sizing.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology tier with digital health integration intensity as an industry-specific overlay. CAGRs derive from regression analysis of historical procurement patterns against policy variable schedules. Forecast inputs incorporate MOHAP registration pipeline data and Dubai Health Authority discharge protocol adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MOHAP regulatory amendments or freight corridor disruptions. Practitioners should monitor Thiqa program reimbursement code revisions and Cleveland Clinic Abu Dhabi pulmonology center expansion timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bone Screw System Market
Medical Devices
Surgical Mesh Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
North America Advanced Drug Delivery Systems Market