
 EEG Amplifiers Market | 2026-2036
EEG Amplifiers Market Size, Share, and Industry Trends Forecast 2026-2036
EEG Amplifiers Market Analysis
ISO 13485 certification for medical device quality management is collapsing the competitive field, forcing smaller suppliers to exit or consolidate. Brain Products GmbH leverages its German engineering base to dominate high-channel research systems. Nihon Kohden Corporation anchors hospital-grade clinical deployments across Asia. Natus Medical Incorporated competes through channel control in North American sleep and epilepsy monitoring.
EEG amplifiers are electronic instruments that detect, filter, and amplify microvolt-level brain electrical signals through scalp electrodes, typically achieving input impedance exceeding 100 MΩ and common-mode rejection ratios above 80 dB to isolate cortical activity from environmental noise. Their primary purpose is to render neural oscillations interpretable for diagnostic, research, or therapeutic intervention. Portable and wireless product types are capturing margin pools as ambulatory monitoring and decentralized trials expand, while wired systems retain dominance in intraoperative and intensive care settings where signal fidelity is non-negotiable. Digital technology leads volume shipments, though hybrid architectures persist in premium research tiers where analog front-end purity matters.
FDA 510(k) clearance and EU MDR conformity assessment govern market access in the United States and Europe respectively, with both frameworks tightening clinical evidence requirements for novel amplifier configurations. The FDA's Breakthrough Devices Program offers accelerated review for epilepsy monitoring innovations, while Japan's PMDA maintains distinct electromagnetic compatibility standards that shape product redesign cycles for that market. Stakeholders must monitor how emerging AI-integrated amplification systems trigger new software-as-medical-device classifications across multiple jurisdictions.
Market Dynamics
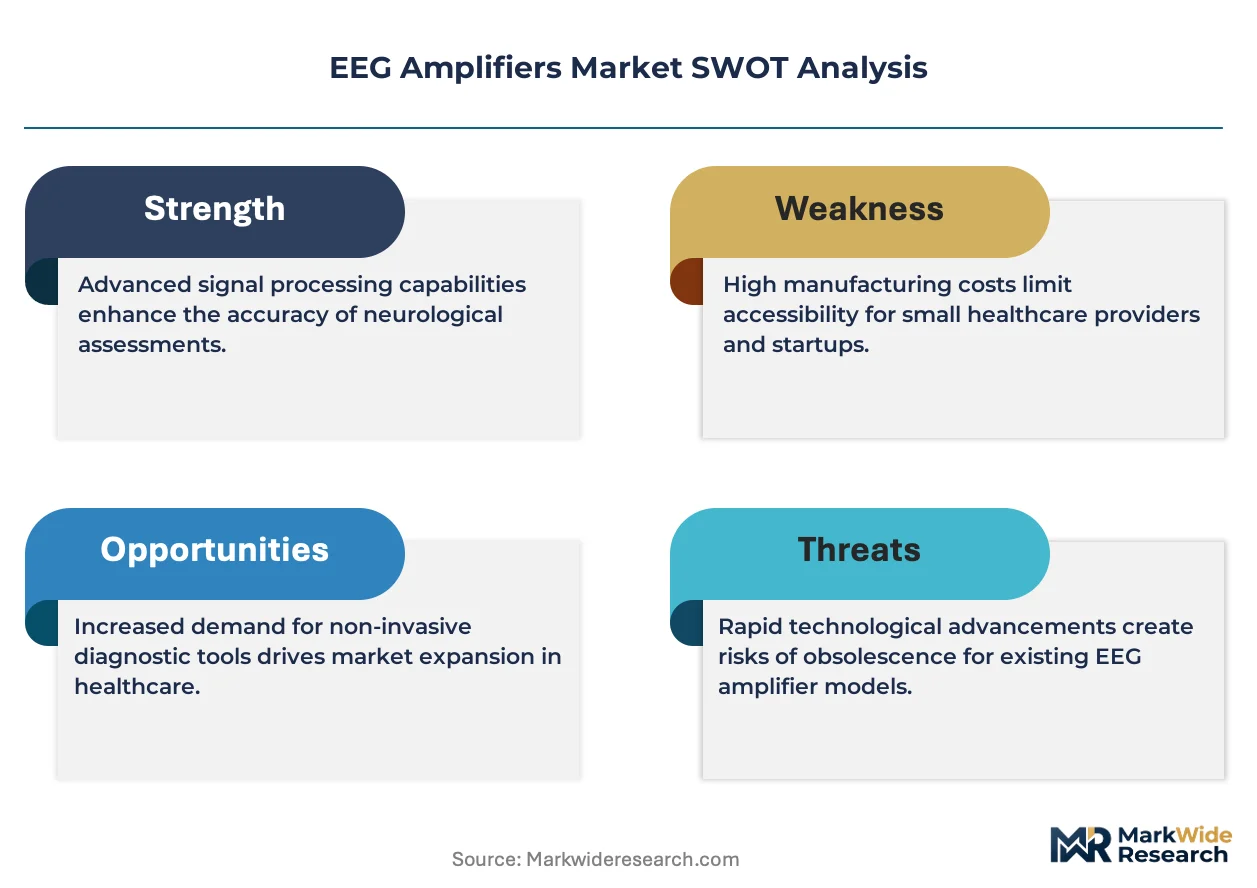
ISO 13485 certification requirements are collapsing the competitive field in EEG amplifiers, forcing smaller suppliers to exit or consolidate while engineering-intensive manufacturers capture premium research and clinical segments.
Growth Catalysts
- Neurofeedback therapy expansion:Clinical psychology practices across Germany and the United States are integrating real-time EEG feedback into treatment protocols for ADHD and anxiety disorders.
- FDA Breakthrough Devices Program:Accelerated review pathways for epilepsy monitoring innovations are compressing time-to-market for novel amplifier configurations targeting drug-resistant seizure disorders.
- Ambulatory monitoring demand:Decentralized clinical trials and home-based neurological monitoring are pulling portable wireless systems into mainstream adoption.
Market Restraints
- Precision analog component costs:Discrete instrumentation amplifiers and ultra-low-noise operational amplifiers face supply volatility from concentrated semiconductor foundry capacity.
- EU MDR conformity assessment:Tightened clinical evidence requirements for novel amplifier configurations are extending certification timelines and elevating documentation burdens.
- fMRI substitution threat:Functional magnetic resonance imaging retains institutional preference for deep-brain localization in pre-surgical epilepsy evaluation.
Strategic Opportunities
- AI-integrated amplification systems:Embedded machine learning for artifact rejection and automated event detection is creating new software-as-medical-device classification pathways.
- Japan PMDA electromagnetic compatibility standards:Distinct shielding and filtering requirements are opening redesign contracts for manufacturers establishing dedicated product lines.
- Telemedicine channel expansion:Remote neurology consultations are creating demand for patient-operated amplifier systems with cloud-based signal transmission.
Industry Challenges
- Biomedical signal processing expertise scarcity:Specialized firmware engineers capable of implementing real-time digital filter banks and adaptive noise cancellation algorithms command premium compensation.
- Legacy system integration complexity:Hospital IT departments face interoperability friction when connecting modern wireless amplifiers to established EEG database architectures and departmental PACS.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EEG Amplifiers Market |
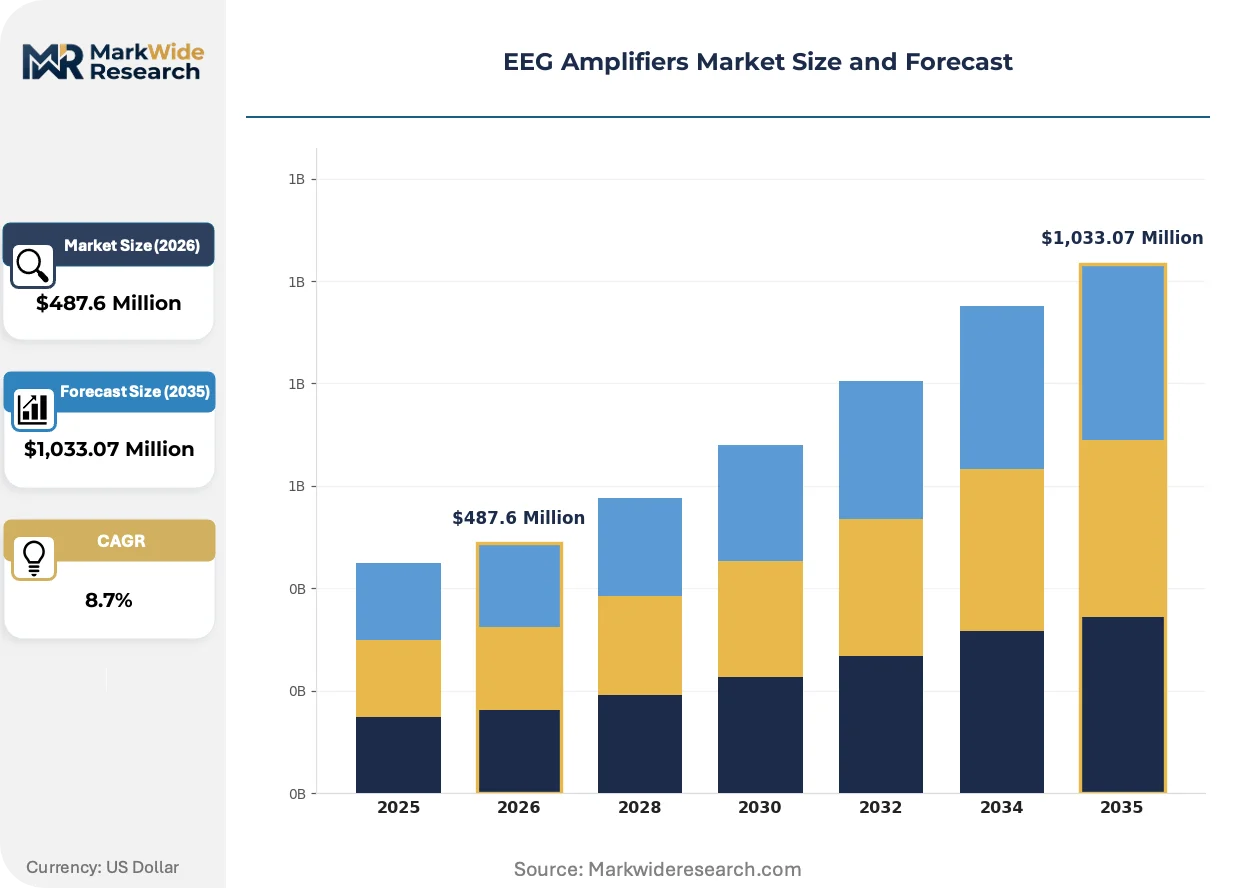
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wired, Wireless, Modular Technology: Digital, Analog, Hybrid, FPGA End User: Healthcare Providers, Research Institutions, Academic Labs, Home Care Application: Neurofeedback, Sleep Study, Epilepsy Monitoring, Cognitive Research |
| Companies Covered | Brain Products GmbH, EB Neuro S.p.A., Nihon Kohden Corporation, Micromed Group, ANT Neuro BV, Natus Medical Incorporated, BioSemi B.V, Electrical Geodesics Inc, Cadwell Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EEG Amplifiers Market Emerging Trajectories
Digital front-end architectures are actively reshaping EEG amplifier design, compressing hardware footprints while expanding software-defined functionality. Three developments are restructuring competitive positioning.
Active electrode technology with integrated impedance buffering and local amplification is supplanting traditional passive electrode arrays in high-density research configurations. Neuroscience laboratories at Max Planck Institute and comparable institutions are adopting these systems to reduce motion artifacts and cable clutter. The shift is compressing demand for conventional shielded cable harnesses while elevating specifications for electrode-site signal processing.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data for Class IIa and above neurological devices. Manufacturers must now maintain vigilance systems tracking amplifier performance in real-world settings. German notified bodies are applying these standards most stringently, creating compliance differentiation between MDR-ready and legacy-certified product portfolios.
Research institutions are unbundling hardware procurement from software licensing and technical support contracts. University purchasing departments now negotiate amplifier acquisitions through consortia arrangements, then separately source analysis platforms from specialized vendors. This fragmentation is most visible in North American academic medical centers, where decentralized buying authority has eroded traditional full-system bundling.
EEG Amplifiers Market Segmentation
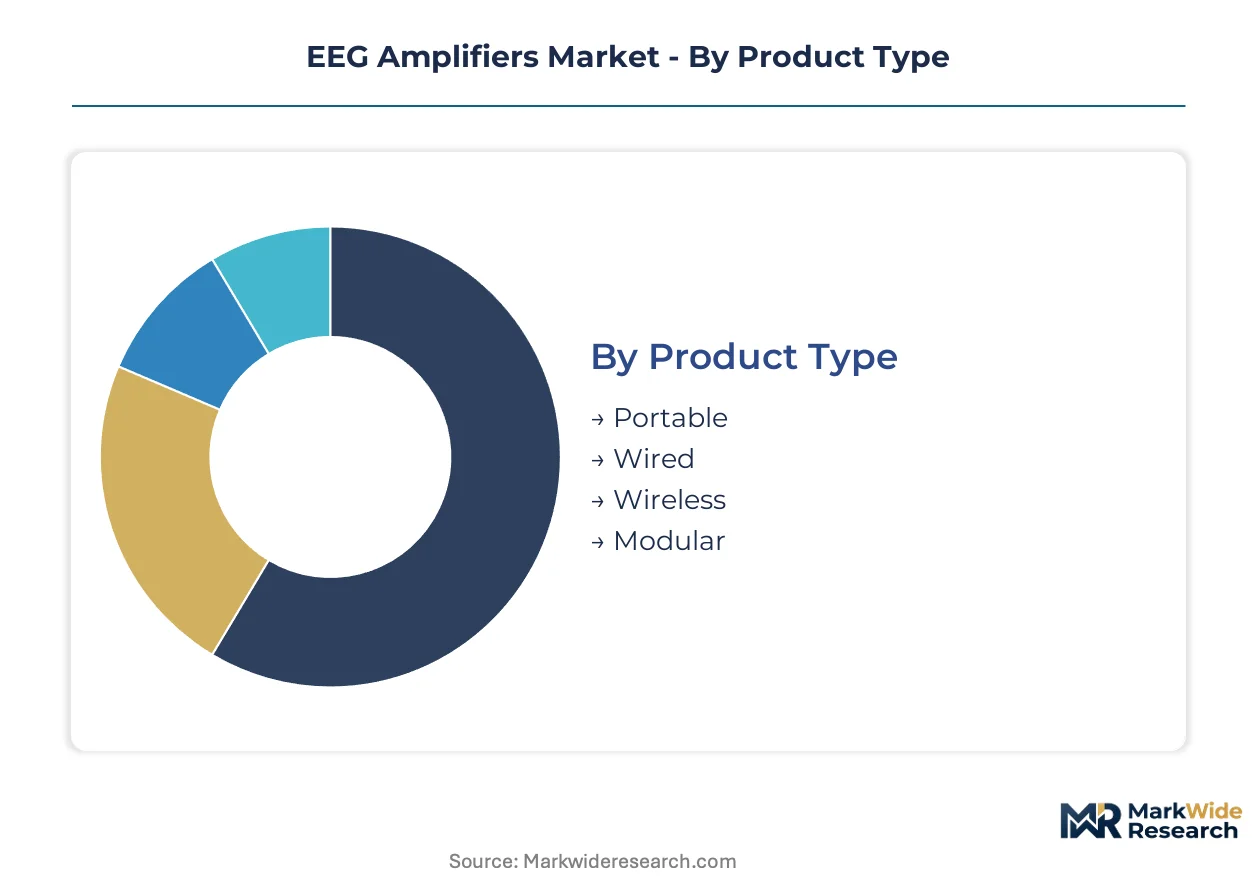
Product architecture in EEG amplifiers determines signal fidelity thresholds, regulatory pathways, and total cost of ownership. Each segmentation dimension carries distinct substitution pressures from competing neuroimaging modalities and alternative brain-computer interface technologies.
Product Type:
Wired configurations face the strongest substitution pressure from wireless alternatives in ambulatory monitoring, while portable systems confront competition from integrated wearable neurotechnology.
- Portable:Battery-powered units with integrated signal processing enable point-of-care neurological assessment outside hospital infrastructure. Demand concentrates in German mobile stroke units and United States rural health clinics where fixed installations are impractical, though battery thermal management limits continuous monitoring duration.
- Wired:Tethered amplifier systems deliver maximum channel count and electromagnetic shielding for intraoperative neurophysiology. Academic medical centers in Japan and Switzerland maintain procurement preference for these configurations during awake craniotomy procedures where signal loss is catastrophic.
- Wireless:Radio-frequency transmission architectures eliminate patient mobility constraints during long-term epilepsy monitoring. Bluetooth Low Energy and proprietary protocols dominate, with FCC Part 15 compliance adding design complexity for United States market entry.
- Modular:Rack-mountable chassis with swappable preamplifier cards support scalable channel expansion from 32 to 256+ electrodes. Max Planck Institute and comparable neuroscience centers deploy these for multimodal integration with MEG and fMRI systems.
Wired systems anchor the volume base while portable configurations gain share at the steepest rate.
Technology:
Cost tier differentiation separates premium hybrid architectures from commoditized digital front-ends, with FPGA-based solutions occupying a narrow high-performance niche.
- Digital:Sigma-delta analog-to-digital converters with integrated digital filtering dominate volume manufacturing. These architectures reduce component count and enable firmware-upgradable feature sets, appealing to hospital procurement committees in France and Italy seeking capital equipment longevity.
- Analog:Discrete instrumentation amplifier chains with manual gain staging persist in specialized research applications. Purist electrophysiology laboratories at institutions like the University of California system specify these for ultra-low-noise requirements below 0.5 microvolts RMS.
- Hybrid:Analog front-end purity combined with digital back-end flexibility commands premium pricing in high-density research tiers. Brain Products GmbH and comparable German manufacturers engineer these systems for cognitive neuroscience applications where artifact rejection algorithms must operate on pristine raw signals.
- FPGA:Field-programmable gate array implementations enable real-time custom filter banks and closed-loop stimulation protocols. Epilepsy monitoring units at Cleveland Clinic and comparable centers deploy these for seizure prediction research requiring sub-millisecond latency.
Digital architectures anchor the volume base while hybrid systems command the steepest pricing premiums.
End User:
Customer type determines procurement authority, with research institutions unbundling hardware from software while healthcare providers demand integrated clinical workflows.
- Healthcare Providers:Hospital neurology departments and dedicated epilepsy centers require FDA 510(k) cleared or CE MDR Class IIa certified devices with EMR integration. Natus Medical and Nihon Kohden dominate this channel through direct sales forces and service contracts.
- Research Institutions:National laboratories and pharmaceutical contract research organizations prioritize channel count and API accessibility over regulatory certification. Consortia purchasing at United States academic medical centers has fragmented traditional full-system bundling.
- Academic Labs:University psychology and neuroscience departments operate under constrained capital budgets favoring refurbished or entry-tier systems. Graduate student training requirements drive demand for intuitive software interfaces over advanced hardware specifications.
- Home Care:Patient-operated systems for remote neurofeedback and sleep monitoring represent an emerging category with evolving reimbursement pathways. Cloud-based signal transmission and automated artifact flagging address the absence of trained technologists in domestic settings.
Healthcare providers anchor the volume base while home care applications expand most quickly.
Application:
Clinical utility and reimbursement status create divergent margin profiles across neurological indications, with cognitive research facing the weakest substitution threat from competing modalities.
- Neurofeedback:Real-time EEG feedback protocols for ADHD and anxiety treatment require amplifiers with low-latency signal processing and intuitive biofeedback displays. Clinical psychology practices in Germany and the Netherlands are integrating these into reimbursable treatment pathways.
- Sleep Study:Polysomnography applications demand synchronized acquisition of EEG, EOG, EMG, and respiratory signals. American Academy of Sleep Medicine accreditation standards specify minimum technical requirements that constrain vendor selection for United States sleep centers.
- Epilepsy Monitoring:Long-term video-EEG monitoring for seizure localization and surgical candidacy evaluation requires 24+ hour continuous operation with minimal electrode impedance drift. FDA Breakthrough Devices Program designation accelerates review for innovations targeting drug-resistant seizure disorders.
- Cognitive Research:Experimental paradigms in perception, memory, and decision-making prioritize temporal resolution and experimental flexibility over clinical certification. Open-source software ecosystems like EEGLAB and FieldTrip drive hardware purchasing decisions in this segment.
Sleep study applications anchor the volume base while neurofeedback therapy climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt Rhine-Main logistics corridor underwrites Germany's central role in European neuroscience equipment distribution, connecting component suppliers in Baden-Württemberg with research hospitals across the continent.
Germany
Max Planck Institute networks and university hospital chains drive demand for high-channel research systems. The country's national medical device regulator enforces EU MDR conformity assessment with particular stringency for Class IIa neurological devices. Baden-Württemberg hosts a dense cluster of precision electronics manufacturers supplying instrumentation amplifier components to amplifier OEMs.
United States
Cleveland Clinic and comparable academic medical centers deploy FPGA-based systems for seizure prediction research. The FDA's Breakthrough Devices Program accelerates review pathways for epilepsy monitoring innovations targeting drug-resistant disorders. Greater Boston's biotechnology corridor concentrates contract research organizations unbundling hardware procurement from software licensing.
Japan
Awake craniotomy procedures at Tokyo and Osaka academic medical centers sustain procurement preference for wired configurations with maximum electromagnetic shielding. The Pharmaceuticals and Medical Devices Agency maintains distinct electromagnetic compatibility standards that shape product redesign cycles for domestic market entry. Kanto region manufacturers supply specialized shielding materials for premium research-tier systems.
Switzerland
Intraoperative neurophysiology units at Zurich and Geneva university hospitals require tethered amplifier systems where signal loss carries catastrophic surgical risk. Swissmedic certification requirements align with EU MDR frameworks while maintaining separate vigilance systems for post-market surveillance. The Basel pharmaceutical corridor drives demand for EEG systems in central nervous system drug trials.
Netherlands
Clinical psychology practices in Amsterdam and Rotterdam integrate real-time EEG feedback into reimbursable treatment protocols for ADHD and anxiety disorders. The country's national health technology assessment body evaluates neurofeedback therapy coverage under statutory insurance. Eindhoven's microelectronics ecosystem supplies sigma-delta analog-to-digital converter components for digital front-end architectures.
EEG Amplifiers Market Vendor Landscape
Listed leaders compete with private specialists across regulatory certification tiers, with publicly traded hospital equipment conglomerates facing off against founder-engineered research instrumentation houses. The vendor base stratifies into three tiers: multinational clinical systems integrators, mid-scale European research specialists, and boutique analog purists serving purist electrophysiology laboratories. Two strategic archetypes dominate competitive maneuvering: engineering-intensive manufacturers capturing premium research segments through hybrid architectures, and channel-control players dominating North American sleep and epilepsy monitoring through direct sales forces. Consolidation pressure operates through ISO 13485 certification barriers forcing smaller suppliers toward exit or acquisition, while technology licensing agreements proliferate around embedded machine learning for artifact rejection.
Among German-engineered research specialists, Brain Products GmbH exemplifies the premium hybrid-architecture archetype, while Nihon Kohden Corporation represents the Asia-Pacific hospital-grade deployment model. Natus Medical Incorporated occupies a position within the North American channel-control tier, competing through service contracts and EMR integration rather than raw hardware specifications.
| Leading Market Players |
|---|
| Brain Products GmbH |
| EB Neuro S.p.A. |
| Nihon Kohden Corporation |
| Micromed Group |
| ANT Neuro BV |
| Natus Medical Incorporated |
| BioSemi B.V |
| Electrical Geodesics Inc |
| Cadwell Industries Inc |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with bundled technical support lock in amplifier procurement pricing across German university hospitals and United States academic medical centers, binding buyers to predictable cost structures while securing manufacturers against component volatility. These arrangements concentrate purchasing power with ISO 13485-certified vendors who control both supply access and price visibility through multi-year equipment refresh cycles.
Pricing Analysis
Volume-discount tiering structures separate premium hybrid-architecture systems from standard digital front-ends and refurbished economy units. Price differentiation hinges on FDA 510(k) clearance tier and channel count scalability, with clinical certification commanding substantial premiums over research-grade configurations. Pricing pressure stems from semiconductor foundry capacity constraints affecting discrete instrumentation amplifier costs. Academic laboratories exhibit highest price sensitivity, while hospital neurology departments prioritize signal fidelity over procurement savings.
Supply Chain Analysis
Inventory lead times for ultra-low-noise operational amplifiers have extended substantially, compressing just-in-time manufacturing schedules at German and Japanese amplifier OEMs. Component sourcing draws from Taiwan for sigma-delta converters, Germany for precision analog semiconductors, and the Netherlands for electrode materials. Single-source vulnerability concentrates in specialized instrumentation amplifier foundries. Distribution runs through direct sales forces for hospital-grade systems and academic consortia for research-tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EEG amplifier markets operate as a regulatory-entrenchment defensive moat, where ISO 13485 certification and FDA 510(k) clearance histories create prohibitive switching costs for hospital procurement committees. This structural advantage protects incumbent positions against technology substitution from fMRI and emerging wearable neurotechnology.
For Market Incumbents: Consolidate component supply security through backward integration into precision analog semiconductor sourcing or captive electrode manufacturing partnerships. Deepen hospital system partnerships with embedded EMR integration and long-term service contracts to defend against portable wireless entrants targeting ambulatory monitoring. Prioritize FPGA-based R&D investment for seizure prediction applications to maintain technological differentiation. For New Entrants and Emerging Players: FDA Breakthrough Devices Program fast-track pathways offer accelerated market entry for epilepsy monitoring innovations targeting drug-resistant disorders. White-space opportunities concentrate in patient-operated home care systems with cloud-based signal transmission, where reimbursement pathways remain unsettled and incumbent presence is weakest. Telemedicine channel partnerships with remote neurology platforms provide viable go-to-market positioning outside established hospital procurement hierarchies. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale European research specialists with established MDR-ready product portfolios and proprietary hybrid-architecture engineering capabilities. Long-term viability across the analysis window favors manufacturers combining analog front-end purity with software-defined digital flexibility. Watch for AI-integrated amplification systems triggering SaMD reclassification as the primary inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Acceleration | CE marking under EU MDR tightens clinical evidence requirements for German notified bodies. |
| Active Electrode Technology Launch | Integrated impedance buffering reduces motion artifacts at Max Planck Institute laboratories. |
| Hospital System Partnership | Direct sales forces with EMR integration dominate Natus Medical's North American channel control. |
| Software Companion Development | Embedded machine learning for artifact rejection triggers SaMD classification pathways. |
| Reimbursement Strategy | Neurofeedback therapy coverage under Dutch statutory insurance expands clinical psychology adoption. |
Methodological Framework
The analysis maps portable wireless systems, wired intraoperative configurations, hybrid research-tier architectures, and FPGA-based epilepsy monitoring platforms, each validated through biomedical engineers at academic medical centers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at notified bodies. Primary interview findings triangulate against FDA 510(k) clearance databases, EU MDR conformity assessment records, hospital procurement databases, and semiconductor trade customs data. Bottom-up channel count and application segmentation reconciles with top-down equipment manufacturer revenue analysis.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, technology architecture, end-user procurement authority, and application-specific reimbursement status as core segmentation dimensions. CAGRs derive from equipment refresh cycle analysis and ambulatory monitoring adoption curves. Forecast inputs incorporate FDA Breakthrough Devices Program pipeline velocity and EU MDR transition timeline impacts on certification availability.
Underlying assumptions cover stable semiconductor foundry capacity, continued FDA 510(k) pathway accessibility, and MDR notified body capacity expansion, with deviation risk concentrated in precision analog component supply disruptions and AI-integrated system reclassification delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transportable Ventilator Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Injection Pen Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Peripheral Interventions Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market