
 High-Resolution Anoscopy Market | 2026-2036
High-Resolution Anoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
High-Resolution Anoscopy Market Foresight
A capital-intensity divergence between integrated imaging conglomerates and specialized endoscope manufacturers is redrawing competitive boundaries in high-resolution anoscopy. Karl Storz SE & Co. KG leverages its surgical optics heritage to dominate rigid anoscope configurations for operative settings. Olympus Corporation sustains channel control through its gastrointestinal endoscopy installed base, cross-selling anoscopy platforms to existing customers. DYSIS Medical specializes in digital colposcopy-adjacent imaging, extending its cervical platform expertise into anal canal applications.
High-resolution anoscopy denotes magnified visual examination of the anal canal using specialized anoscopes with enhanced illumination and optical resolution, typically achieving 6x to 30x magnification through colposcopic or digital imaging attachments to detect squamous intraepithelial lesions. The procedure serves as the diagnostic cornerstone for anal cancer screening in high-risk populations, particularly HIV-positive patients and men who have sex with men, enabling targeted biopsy of suspicious lesions that standard anoscopy misses. Digital anoscope platforms command premium positioning due to integrated documentation and artificial intelligence-assisted lesion detection capabilities, while flexible anoscope designs gain traction in outpatient clinics prioritizing patient comfort during surveillance protocols. LED illumination technology leads installed base metrics given its cost efficiency and color temperature stability, though 3D imaging represents the fastest-advancing segment for academic medical centers pursuing research applications.
FDA 510(k) clearance requirements govern device commercialization in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence standards for anoscope platforms marketed in Europe. The Centers for Medicare & Medicaid Services reimbursement determinations for high-resolution anoscopy with biopsy directly shape provider adoption economics and capital equipment purchasing cycles. Stakeholders must monitor evolving anal cancer screening guidelines from professional societies and payer coverage expansions that could accelerate platform replacement demand across outpatient settings.
Market Dynamics
Specialty colorectal practices are consolidating purchasing power around integrated digital imaging platforms, compressing vendor margins while elevating technical performance requirements for anoscope manufacturers serving HIV-positive and immunocompromised patient surveillance protocols.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearance timelines for digital imaging modalities are reducing time-to-market for advanced anoscope platforms, enabling faster commercialization of AI-assisted lesion detection systems.
- LED illumination cost efficiency:Stable color temperature performance at reduced operational expenditure is driving replacement demand across outpatient clinics previously constrained by halogen maintenance burdens.
- Men who have sex with men screening expansion:Targeted public health initiatives in urban healthcare systems are establishing high-resolution anoscopy as standard-of-care for anal dysplasia detection in this high-risk demographic.
Market Restraints
- Capital equipment intensity:Digital anoscope platforms require substantial upfront investment, limiting adoption in federally qualified health centers and rural settings with constrained equipment budgets.
- EU MDR clinical evidence burden:Strengthened documentation requirements for anoscope platforms marketed in Europe are extending regulatory timelines and increasing compliance costs for manufacturers.
- Flexible sigmoidoscopy substitution:Some colorectal practices continue leveraging existing flexible endoscope inventories for anal canal examination, delaying dedicated high-resolution anoscopy procurement.
Strategic Opportunities
- Academic medical center 3D imaging adoption:Research-intensive institutions are pursuing advanced visualization capabilities for anal cancer screening studies, creating premium segment demand.
- Telemedicine-integrated documentation:Cloud-based image capture and remote consultation capabilities are opening channel expansion into community health networks lacking on-site specialist coverage.
- CMS reimbursement expansion potential:Evolving coverage determinations for high-resolution anoscopy with biopsy could unlock capital equipment replacement cycles across Medicare-dependent practices.
Industry Challenges
- Specialized colposcopic training scarcity:Anal dysplasia screening requires distinct physician competency beyond standard anoscopy, constraining service capacity expansion.
- Legacy EMR integration complexity:Digital anoscope platforms face interoperability friction with established electronic medical record systems, extending implementation timelines.
- Biopsy protocol standardization gaps:Variability in lesion documentation and sampling techniques across institutions complicates multi-site research collaboration and quality benchmarking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Resolution Anoscopy Market |
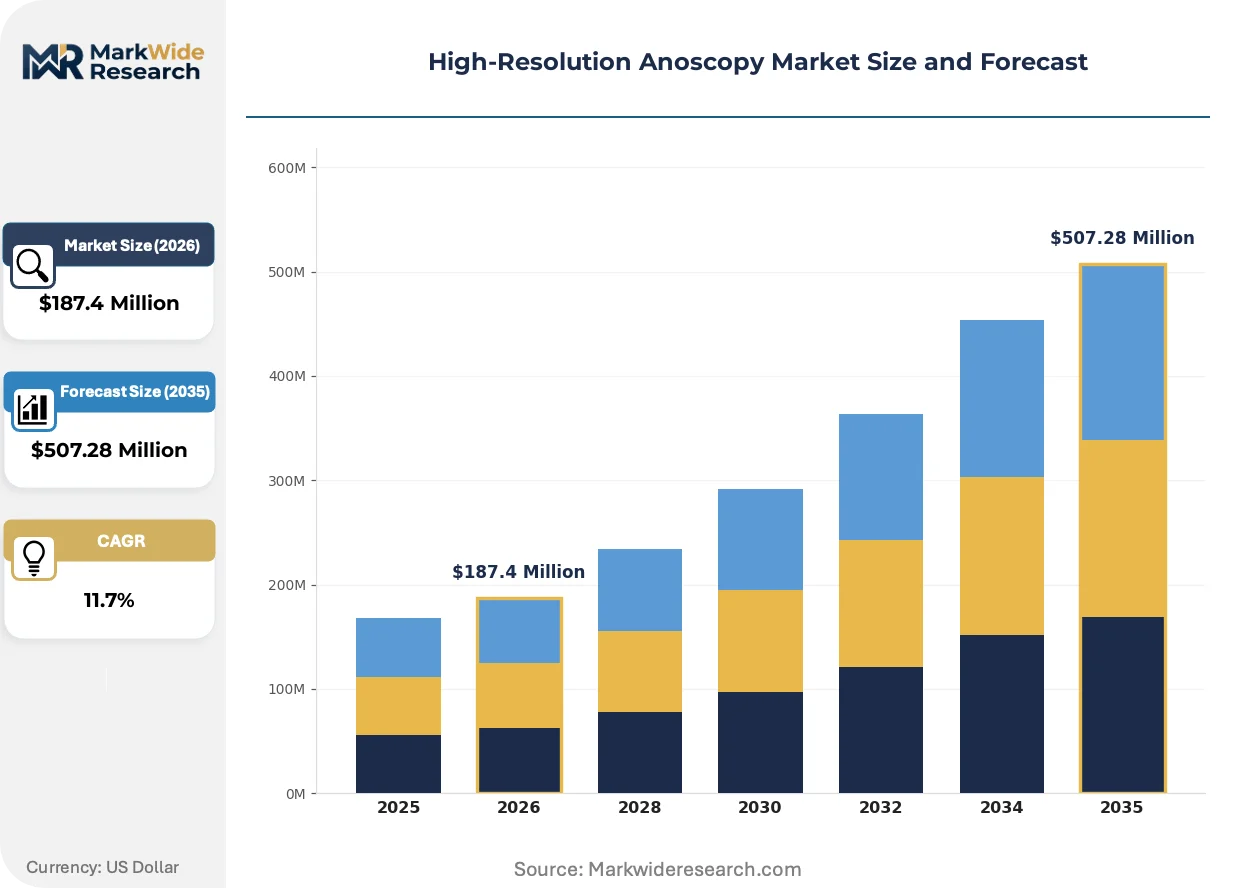
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Anoscope, Rigid Anoscope, Digital Anoscope, Optical Anoscope End User: Hospitals, Clinics, Diagnostic Centers, Specialty Practices Technology: LED Illumination, Fiber Optic, Digital Imaging, 3D Imaging Application: Oncology, Gastroenterology, Pathology, General Surgery |
| Companies Covered | Philips, Optomic, Olympus Corporation, Leisegang, Lutech Medical, Karl Storz SE & Co. KG, Ecleris, DYSIS Medical, Carl Zeiss Meditec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Resolution Anoscopy Market Shifts & Advancements
Artificial intelligence integration is reconfiguring competitive advantage around diagnostic accuracy rather than optical hardware specifications, compressing differentiation windows for incumbent manufacturers.
Machine learning algorithms embedded within digital anoscope platforms are displacing physician-only visual assessment for squamous intraepithelial lesion detection. Academic medical centers in the United States are piloting these systems for resident training and quality assurance. The technology is displacing traditional colposcopic expertise as the primary value determinant in procurement decisions.
The EU Medical Device Regulation imposes post-market surveillance obligations that extend accountability across the product lifecycle for anoscope manufacturers. Clinical evidence requirements now encompass real-world performance data, elevating documentation burdens. European notified bodies are prioritizing digital imaging platforms with embedded AI, compressing review timelines for these categories.
Consolidated purchasing by specialty colorectal practice networks is compressing vendor negotiation cycles and unbundling after-sales service contracts. Independent service organizations are capturing maintenance revenue previously retained by original equipment manufacturers. This pattern is most visible in the United States where private equity-backed practice aggregations command substantial equipment procurement volume.
High-Resolution Anoscopy Market Segmentation
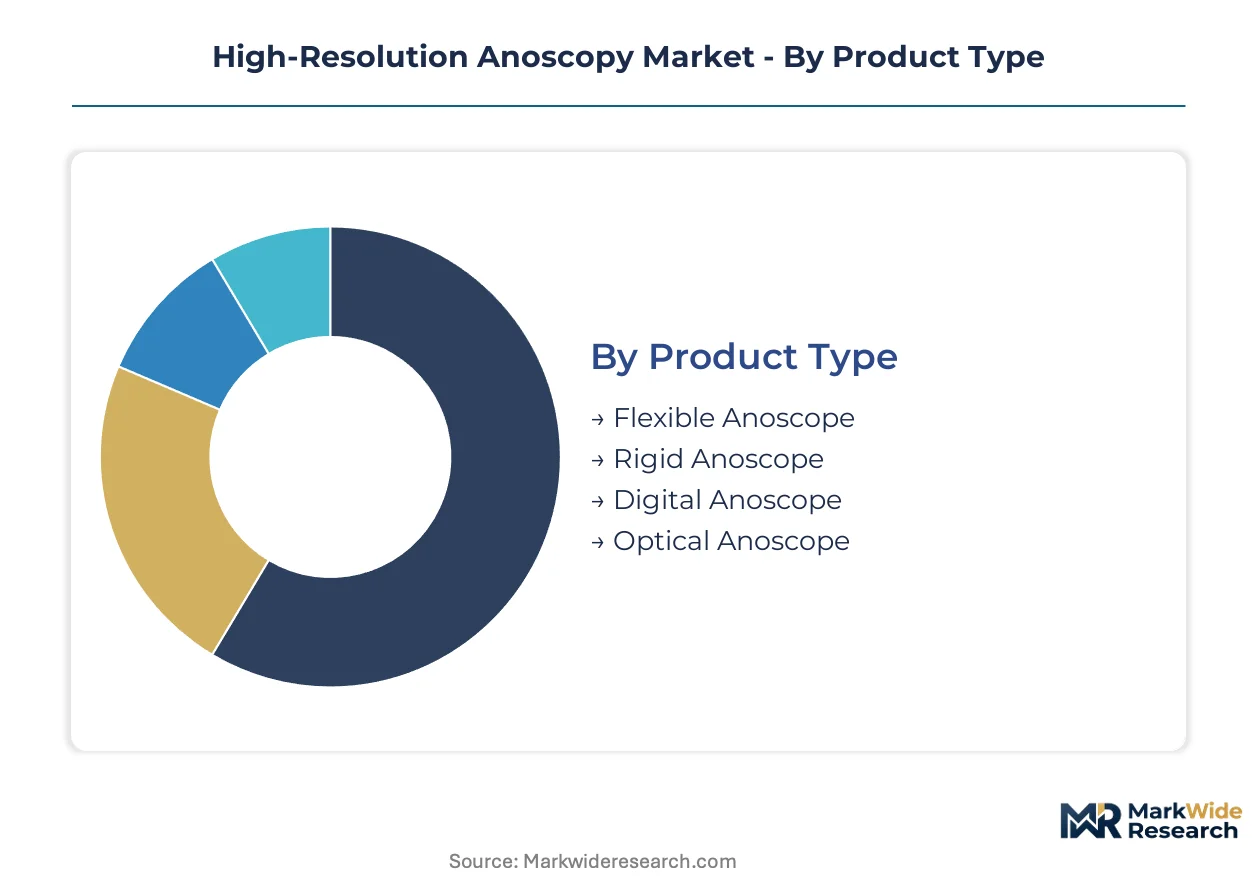
High-resolution anoscopy platforms serve distinct clinical workflows across rigid operative settings, flexible outpatient surveillance, and AI-enhanced diagnostic environments. Channel dynamics vary sharply by product configuration and reimbursement pathway, with capital intensity determining whether procurement flows through hospital supply chains or specialty practice direct purchasing.
Product Type:
Channel mix splits between integrated health system capital committees for premium digital platforms and specialty practice direct procurement for operative rigid configurations.
- Rigid Anoscope:Stainless steel construction with fixed optical pathways delivers superior image stability during biopsy procedures. Demand concentrates in academic medical centers and specialty colorectal practices performing high-volume anal dysplasia screening in urban United States markets, driven by operative precision requirements and durability under sterilization cycles.
- Digital Anoscope:Integrated CMOS sensors with embedded image processing enable real-time documentation and AI-assisted lesion detection. Procurement flows through hospital capital equipment committees in metropolitan United States healthcare systems, constrained by upfront investment thresholds but prioritized where CMS reimbursement coverage supports procedure volume economics.
- Flexible Anoscope:Polymer-based insertion tubes with steerable distal tips optimize patient comfort in surveillance protocols. Outpatient clinics in HIV-focused care networks favor this configuration for reduced procedural anxiety during repeat screening intervals.
- Optical Anoscope:Conventional glass lens systems without digital capture capabilities serve cost-constrained settings. Rural federally qualified health centers retain these platforms where capital replacement cycles extend beyond typical depreciation schedules.
Rigid anoscope dominates installed base. Digital anoscope is where expansion concentrates.
End User:
Procurement authority varies by organizational scale, with centralized purchasing departments governing hospital acquisitions and physician-owners directing specialty practice equipment decisions.
- Hospitals:Integrated delivery networks leverage group purchasing organization contracts for digital platform standardization across multiple sites. Capital budgeting cycles align with fiscal year planning, with replacement decisions tied to procedure volume thresholds and resident training program requirements.
- Specialty Practices:Colorectal and proctology-focused groups prioritize optical performance and biopsy precision over documentation integration. Private equity-backed practice aggregations in the United States are consolidating purchasing power around preferred vendor relationships, compressing negotiation timelines.
- Clinics:Community-based settings serving high-risk populations balance equipment cost against patient throughput constraints. Federally qualified health centers in urban corridors with concentrated HIV-positive demographics represent targeted expansion opportunities for flexible platform manufacturers.
- Diagnostic Centers:Independent pathology-focused facilities require seamless PACS integration for remote consultation workflows. Cloud-based image transmission capabilities are becoming procurement prerequisites for these operators.
Specialty practices dominate installed base. Diagnostic centers are where expansion concentrates.
Technology:
Cost tier stratification separates premium visualization systems from maintenance-burdened legacy illumination, with reimbursement economics determining adoption velocity.
- LED Illumination:Solid-state emitters deliver stable 5600K color temperature with 50,000-hour operational lifespan and minimal heat generation. Cost efficiency drives replacement demand across outpatient United States clinics previously constrained by halogen bulb inventory and thermal degradation issues.
- Digital Imaging:High-definition capture with automated lesion mapping and measurement calibration supports quality assurance protocols. Academic medical centers prioritize these platforms for resident training standardization and multi-site research collaboration.
- Fiber Optic:Bundled glass transmission pathways remain prevalent in legacy rigid anoscope installations. Maintenance complexity and gradual transmission degradation limit new procurement except where electromagnetic interference constraints prohibit electronic systems.
- 3D Imaging:Stereoscopic visualization with depth perception enhancement enables precise lesion margin assessment. Research-intensive institutions in the United States are piloting these systems for anal cancer screening studies, though clinical utility validation remains incomplete.
LED illumination dominates installed base. Digital imaging is where expansion concentrates.
Application:
Volume concentration aligns with disease burden demographics, with oncology and gastroenterology workflows commanding distinct equipment specifications.
- Oncology:Anal dysplasia screening and cancer surveillance protocols demand magnification range from 6x to 30x with targeted biopsy capability. United States-based comprehensive cancer centers with dedicated anorectal malignancy programs drive premium platform procurement.
- Gastroenterology:Integration with existing endoscopy suites and cross-training of nursing staff favor flexible platform configurations. GI-focused practices leverage high-resolution anoscopy as adjunct to colonoscopy screening programs for high-risk patient stratification.
- Pathology:Ex vivo specimen correlation and quality control feedback loops require standardized image documentation. Digital platforms with DICOM compatibility support these workflow integrations.
- General Surgery:Operative hemorrhoidectomy and fistula procedures utilize rigid anoscope platforms for tissue manipulation under direct visualization. Community hospital general surgery departments represent replacement demand for durable mechanical designs.
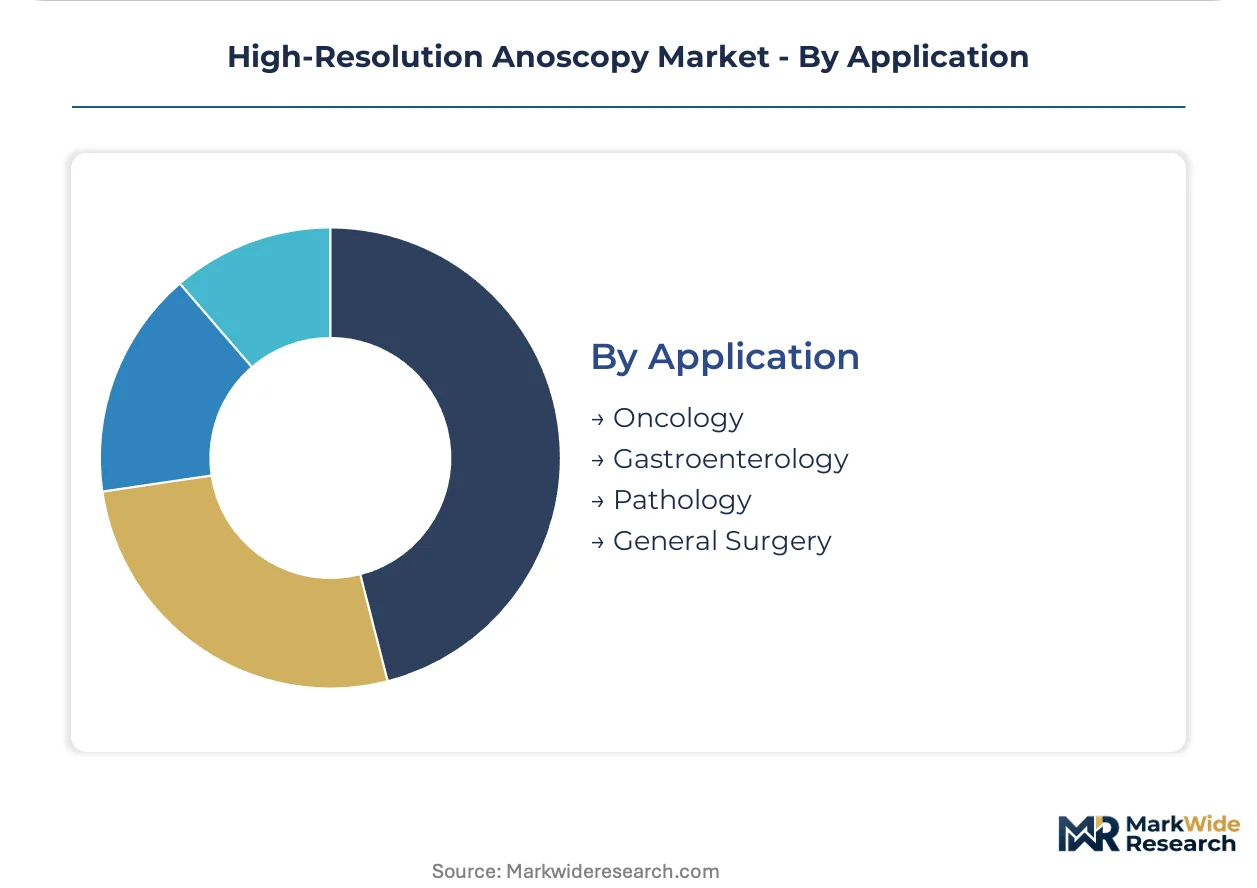
Oncology dominates installed base. Gastroenterology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where CMS reimbursement coverage supports premium digital platform procurement, while European markets face margin compression from EU MDR compliance costs and extended regulatory timelines.
United States
Urban healthcare systems with concentrated HIV-positive populations drive screening protocol expansion for anal dysplasia detection. FDA 510(k) clearance pathways for digital imaging modalities are shortening time-to-market for AI-assisted anoscope platforms. Academic medical centers in New York and San Francisco are piloting 3D imaging systems for research applications.
Germany
Specialty colorectal practices in Bavaria and North Rhine-Westphalia prioritize rigid anoscope configurations for operative precision. The EU Medical Device Regulation imposes strengthened clinical evidence standards that extend regulatory timelines for manufacturers. Medical technology clusters around Tübingen and Berlin are advancing LED illumination integration for outpatient surveillance protocols.
United Kingdom
NHS England screening program expansions for high-risk demographics are establishing dedicated anorectal malignancy services. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR standards while streamlining domestic approval pathways. London-based comprehensive cancer centers are driving demand for digital documentation platforms with PACS integration.
France
ANSM oversight of digital imaging platforms prioritizes AI-embedded systems for accelerated review timelines. Public health initiatives targeting men who have sex with men in Paris and Lyon are standardizing high-resolution anoscopy for anal dysplasia detection. Île-de-France academic hospitals are leading European adoption of telemedicine-integrated documentation systems.
Japan
PMDA regulatory frameworks emphasize real-world performance data for digital anoscope platforms with embedded machine learning. Aging population demographics and rising anal cancer incidence are expanding screening reimbursement coverage. Tokyo and Osaka metropolitan healthcare systems are integrating flexible anoscope platforms into existing gastrointestinal endoscopy suites.
High-Resolution Anoscopy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated imaging conglomerates commanding premium digital segments while specialized endoscope manufacturers dominate operative rigid configurations. The market structure reflects capital-intensity divergence between these archetypes, compressing mid-tier vendor margins. Three strategic archetypes define competitive positioning: surgical optics heritage firms leveraging rigid platform durability, gastrointestinal endoscopy incumbents cross-selling through installed base relationships, and digital colposcopy specialists extending cervical expertise into anal applications. Dominant competitive moves include strategic partnerships for AI algorithm licensing and portfolio diversification into flexible platform configurations for outpatient surveillance.
Within the surgical optics heritage tier, Karl Storz SE & Co. KG and Olympus Corporation occupy positions reflecting distinct geographic and structural profiles. Karl Storz SE & Co. KG, a German GmbH, exemplifies the operative precision archetype through its rigid anoscope dominance in academic medical center settings. Olympus Corporation, a Japanese Co., Ltd., anchors the gastrointestinal cross-selling strategy through its endoscopy installed base control. DYSIS Medical, a UK-based specialist, represents the digital colposcopy extension archetype, leveraging cervical platform expertise for anal canal applications.
| Leading Market Players |
|---|
| Philips |
| Optomic |
| Olympus Corporation |
| Leisegang |
| Lutech Medical |
| Karl Storz SE & Co. KG |
| Ecleris |
| DYSIS Medical |
| Carl Zeiss Meditec |
| Others |
Supply & Pricing Matrix
LED illumination modules displacing halogen bulb assemblies in digital anoscope platforms simultaneously concentrate component sourcing in East Asian electronics manufacturing corridors and compress aftermarket pricing power for legacy service providers. This substitution dynamic redistributes value capture from bulb replacement networks to semiconductor-integrated system vendors while flattening maintenance revenue curves across installed equipment bases.
Pricing Analysis
The customization-premium spread between configured-to-order digital anoscope platforms and standard rigid configurations spans three distinct pricing tiers. Transactional per-unit pricing dominates capital equipment procurement, with differentiation driven by FDA 510(k) clearance tier and embedded AI algorithm licensing status. Cost compression in standard optical configurations is intensifying because group purchasing organizations aggregate specialty practice demand, while academic medical centers show least price sensitivity due to research grant funding flexibility.
Supply Chain Analysis
Strategic stockpiling of CMOS sensors and LED emitter arrays characterizes procurement behavior among tier-one anoscope manufacturers facing extended semiconductor lead times. Component sourcing draws from Japan, South Korea, and Taiwan for imaging sensors, with German and Swiss suppliers anchoring precision optical glass production. Single-source vulnerability in advanced CMOS fabrication creates supply chain risk, while distribution runs through hospital supply chain consignment agreements and specialty practice direct purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-resolution anoscopy market constitutes a defensive-moat opportunity anchored in regulatory entrenchment, where FDA 510(k) clearance timelines and clinical evidence requirements create structural barriers against rapid competitive displacement.
For Market Incumbents: Fortify installed base control through backward integration into LED illumination module production and captive servicing networks for digital platforms. The threat of AI-native entrants with cloud-first architectures demands accelerated EMR interoperability investments. Prioritize certification maintenance for EU MDR compliance to preserve European market access against notified body capacity constraints. For New Entrants and Emerging Players: Differentiate on telemedicine-integrated documentation capabilities targeting federally qualified health centers in urban HIV-focused care networks. The most penetrable segment lies in flexible anoscope configurations for outpatient surveillance protocols, where patient comfort positioning displaces incumbent optical performance narratives. Pursue channel partnerships with independent service organizations to bypass established OEM maintenance relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors surgical optics heritage firms with established colorectal specialist relationships. Long-term viability rests on AI algorithm differentiation rather than hardware commoditization trajectories. Acquisition targets should demonstrate embedded software recurring revenue streams. The signal to watch is CMS reimbursement determination expansion for high-resolution anoscopy with biopsy, which would trigger capital equipment replacement cycles across Medicare-dependent practices.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Shortened clearance timelines enable faster commercialization of AI-assisted lesion detection systems. |
| CE Marking Pathway Investment | EU MDR compliance secures access to German and French academic medical center procurement channels. |
| Hospital System Partnership | Integrated delivery network contracts standardize digital platform deployment across multiple sites. |
| Software Companion Development | Cloud-based image capture opens expansion into community health networks lacking specialist coverage. |
| Reimbursement Strategy | CMS coverage expansion advocacy unlocks capital equipment replacement cycles in Medicare-dependent practices. |
Research Methodology
Cross-validation between primary interviews with colorectal surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and professional society screening guideline publications anchors the qualitative findings. Bottom-up demand modeling from procedure volume assumptions and top-down market sizing from equipment shipment data complete the triangulation.
Sensitivity analysis around CMS reimbursement scenario variations and AI algorithm adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, end-user organizational scale, illumination technology tier, and application workflow type. CAGRs derive from equipment replacement cycle analysis and procedure volume elasticity to reimbursement coverage, with inputs from HIV-positive population screening protocol expansion rates and academic medical center research funding trajectories.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement support or accelerated EU MDR notified body capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding screening guideline adoption timelines and AI regulatory clearance pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Global Endoscopes Market
Endoscopy
Sigmoidoscope Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscopy Device Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Esophageal Stents Market
Endoscopy
Single Use Bronchoscopes Market