
 Global Medical Kiosk Market | 2026-2036
Global Medical Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Kiosk Market Foresight
Equipment leasing and pay-per-use financing is narrowing the competitive field for capital-constrained health systems seeking medical kiosk deployments. NCR Corporation leverages its financial services arm to bundle hardware with managed service contracts, sustaining recurring revenue streams across hospital networks. KIOSK Information Systems anchors its position through vertically integrated manufacturing in North America, controlling component costs and lead times. Olea Kiosks Inc. differentiates via custom enclosure engineering that meets ADA compliance and infection control standards, occupying a premium niche in clinical environments.
A medical kiosk is a self-service, interactive terminal engineered for healthcare settings, typically incorporating touchscreens, biometric sensors, payment modules, and encrypted data transmission protocols operating on HL7 or FHIR interoperability standards. Its primary purpose is to automate patient registration, vital collection, payment processing, and clinical triage while reducing staff workload and minimizing physical contact points. Diagnostic kiosks lead product type revenue due to higher unit costs and recurring consumable attachments, while telemedicine kiosks represent the fastest-growing category as virtual care reimbursement expands. Among end users, hospitals dominate absolute volume, though corporate wellness centers are emerging as a concentrated margin pool due to shorter sales cycles and standardized deployment templates.
The FDA enforces 510(k) clearance and cybersecurity controls under its premarket notification framework, elevating compliance costs but creating barriers against low-cost imports. In Europe, the Medical Device Regulation and GDPR jointly shape product design, mandating clinical evidence for diagnostic functions and strict patient data governance. China's NMPA and GB standards impose additional localization requirements for software and hardware components. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring services, as these will determine whether kiosk-delivered diagnostics achieve sustainable utilization rates outside pilot programs.
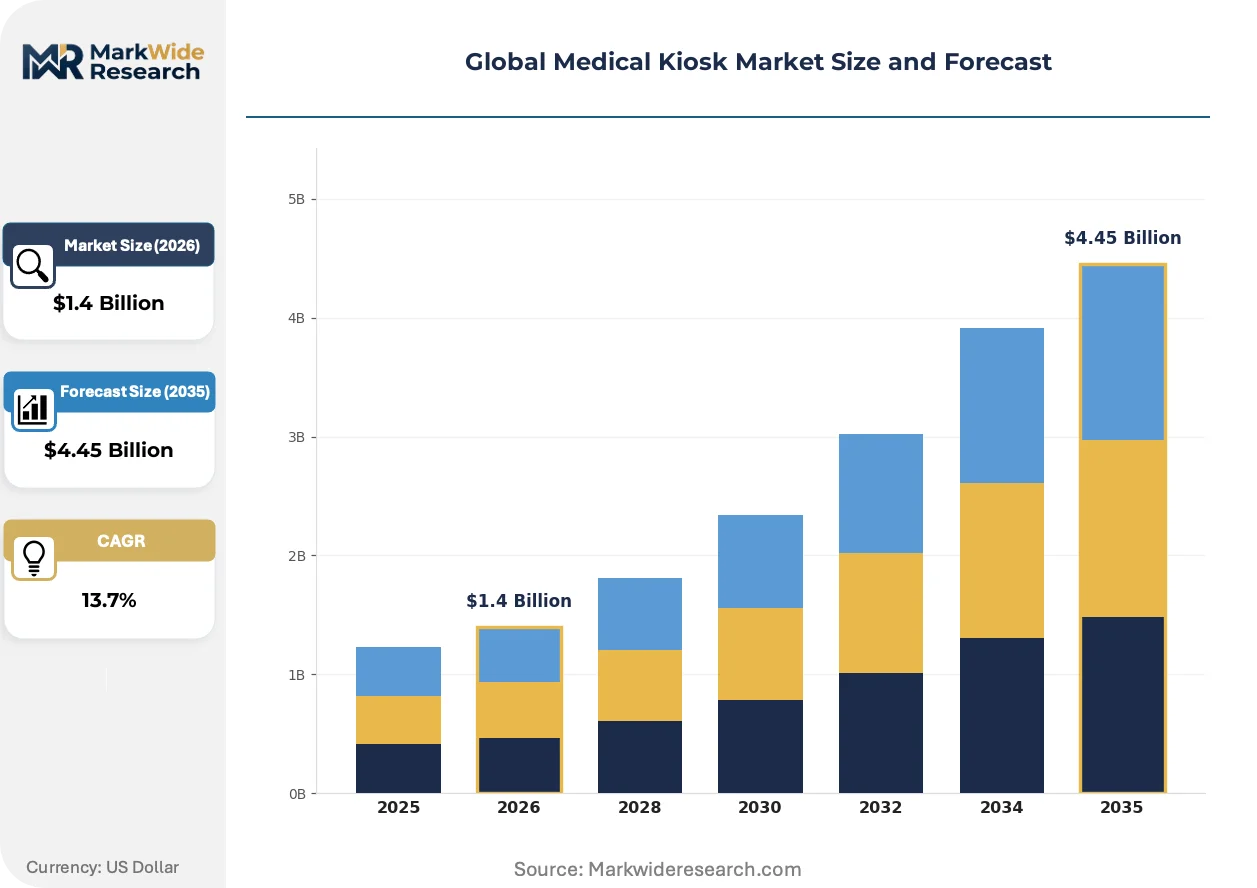
Market Dynamics
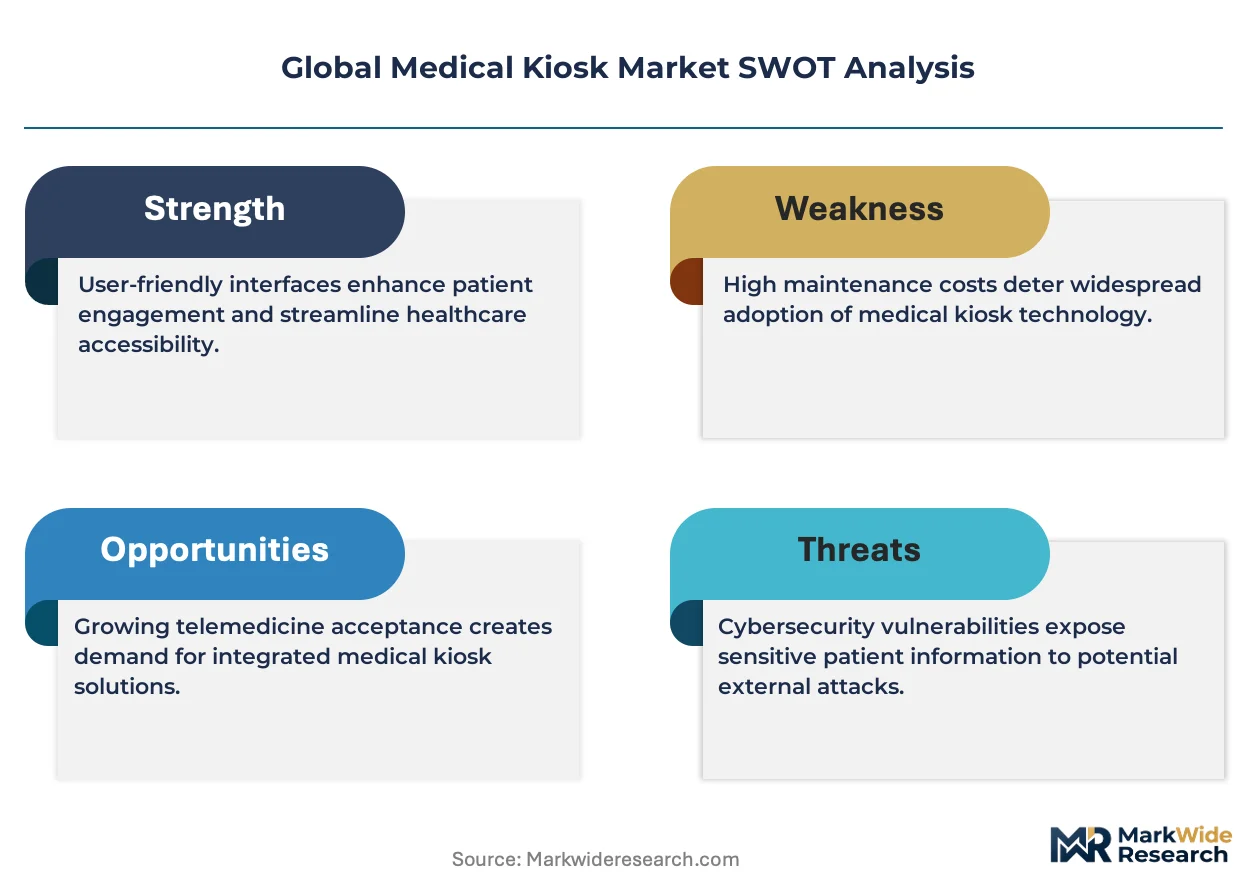
Hospital digitization mandates and FDA cybersecurity tightening are compressing vendor qualification timelines while elevating capital requirements for kiosk manufacturers seeking institutional contracts.
Growth Catalysts
- Digital Care Act procurement windows:Germany's hospital digitization mandates under this framework are accelerating tender volumes for integrated diagnostic terminals across acute care networks.
- FHIR interoperability protocols:Healthcare IT departments are standardizing on Fast Healthcare Interoperability Resources to reduce integration friction with electronic health record systems.
- Corporate wellness center standardization:Employer-sponsored health programs are deploying templated kiosk configurations to reduce per-site deployment costs and accelerate rollout velocity.
Market Restraints
- Semiconductor component volatility:Touchscreen controller and biometric sensor supply chains remain concentrated in East Asian foundry networks, exposing manufacturers to input cost swings.
- 510(k) clearance timelines:FDA premarket notification requirements for connected diagnostic functions extend product development cycles by 12-18 months versus non-medical kiosk categories.
- Smartphone-based health apps:Consumer-facing symptom checkers and vital monitoring applications are capturing low-acuity patient interactions outside clinical settings.
Strategic Opportunities
- Rural health clinic underpenetration:Federally Qualified Health Centers in the United States lack self-service infrastructure, creating whitespace for diagnostic kiosk deployments with RPM reimbursement coding.
- Telemedicine kiosk convergence:Virtual care reimbursement expansion is enabling hybrid models that combine synchronous video consultation with asynchronous vital capture.
- Equipment-as-a-service financing:Managed service contracts bundling hardware, software, and maintenance are displacing capital purchase models in liquidity-constrained health systems.
Industry Challenges
- Embedded systems cybersecurity expertise:Manufacturers face acute shortages of firmware engineers capable of implementing FDA-mandated threat modeling and penetration testing protocols.
- Legacy EHR integration complexity:Hospital IT departments require custom HL7 interface development to connect kiosks with aging electronic health record architectures from multiple vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Kiosk Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kiosks, Telemedicine Kiosks, Self-Service Check-In Kiosks, Health Information Kiosks Application: Chronic Disease Management, Preventive Care, Patient Check-In, Clinical Diagnostics End User: Hospitals, Pharmacies, Corporate Wellness Centers, Community Health Centers Deployment: Standalone Units, Integrated Systems, Mobile Kiosks, Fixed Location Kiosks |
| Companies Covered | NCR Corporation, KIOSK Information Systems, Olea Kiosks Inc., Meridian Kiosks, Fabcon, RedyRef Interactive Kiosks, Oracle Corporation, imageHOLDERS, Advantech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Kiosk Market Shifts & Advancements
Edge computing architectures and biometric sensor miniaturization are enabling diagnostic-grade vital capture outside traditional clinical settings, compressing the physical footprint required for self-service health infrastructure.
Multi-parameter biometric sensor arrays are consolidating pulse oximetry, blood pressure, and ECG capture into single hardware modules. Outpatient clinics and pharmacy chains are adopting these integrated terminals to reduce per-patient staff touchpoints. The technology is virtualizing the traditional triage station, enabling distributed vital collection without dedicated nursing personnel.
The EU Medical Device Regulation's clinical evidence requirements for diagnostic functions are forcing kiosk manufacturers to sponsor prospective validation studies. This regulatory burden is elevating compliance costs but creating defensible market positions for vendors with notified body certifications. Diagnostic kiosk product lines face the steepest documentation requirements, with Class IIa and IIb classifications triggering annual surveillance audits.
Buyers are unbundling after-sales service contracts from hardware procurement, selecting specialized third-party maintainers for firmware updates and field repair. Hospital procurement departments are driving this fragmentation to reduce vendor lock-in and improve uptime service-level agreements. The United Kingdom's National Health Service trusts are most advanced in this disaggregation, with separate tender processes for equipment supply and multi-vendor maintenance panels.
Global Medical Kiosk Market Segmentation
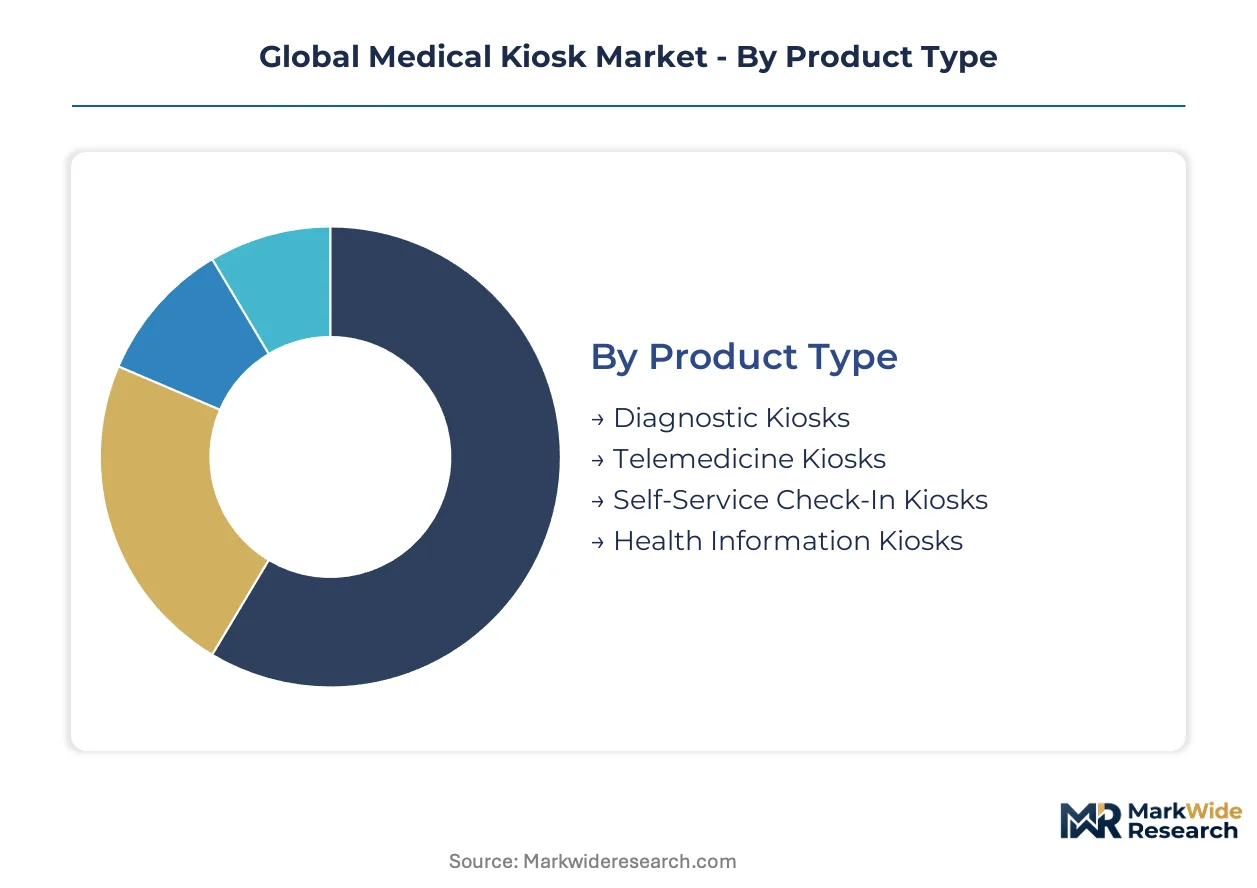
Medical kiosk segmentation reveals divergent service intensity requirements across hardware configurations. Product architecture determines firmware update frequency, sensor calibration cycles, and field engineering dispatch rates.
Product Type:
After-sales service intensity varies dramatically by diagnostic capability tier.
- Diagnostic Kiosks:Multi-parameter biometric arrays integrate pulse oximetry, blood pressure cuffs, and ECG modules requiring quarterly calibration protocols. Hospital networks in Germany concentrate procurement under Digital Care Act tenders, prioritizing devices with notified body certifications for Class IIa diagnostic functions.
- Telemedicine Kiosks:Synchronous video consultation terminals demand continuous software patching for HIPAA-compliant encryption and FDA cybersecurity guidance adherence. Corporate wellness centers in the United States deploy standardized templates, accelerating rollout velocity through templated configurations.
- Self-Service Check-In Kiosks:Registration and payment terminals with HL7/FHIR interoperability modules serve high-volume hospital reception areas.
- Health Information Kiosks:Educational touchscreen terminals with wayfinding and general health content occupy lower-acuity clinical spaces.
Diagnostic kiosks hold the largest share; momentum sits with telemedicine kiosks as virtual care reimbursement expands.
Application:
Clinical workflow integration depth determines hardware specification tiers.
- Chronic Disease Management:Remote patient monitoring reimbursement codes drive demand for connected vital capture stations. Federally Qualified Health Centers in rural United States locations underpenetrated by self-service infrastructure represent whitespace deployment opportunities.
- Preventive Care:Screening terminals for cardiovascular risk assessment and diabetes detection occupy pharmacy chain footprints. China's NMPA localization requirements for software components shape product development cycles for manufacturers targeting retail clinic networks.
- Patient Check-In:Administrative automation reduces nursing staff touchpoints in acute care reception areas.
- Clinical Diagnostics:Point-of-care testing integration with laboratory information systems elevates regulatory scrutiny under FDA 510(k) frameworks.
Patient check-in dominates absolute volume; chronic disease management climbs fastest as RPM coding stabilizes.
End User:
Procurement sophistication and capital availability segment the customer base.
- Hospitals:Acute care networks negotiate enterprise-wide managed service contracts bundling hardware, software, and maintenance. The United Kingdom's National Health Service trusts disaggregate equipment supply from multi-vendor maintenance panels.
- Corporate Wellness Centers:Employer-sponsored health programs demand rapid deployment with minimal IT integration friction. Shorter sales cycles and standardized configurations produce concentrated margin pools for kiosk vendors.
- Pharmacies:Retail health clinics seek diagnostic-grade terminals for minor ailment triage and medication adherence programs.
- Community Health Centers:Nonprofit and municipal facilities prioritize equipment-as-a-service financing over capital purchases.
Hospitals anchor absolute demand; corporate wellness centers gain share fastest through standardization.
Deployment:
Physical footprint and connectivity architecture shape total cost of ownership.
- Standalone Units:Self-contained terminals with edge computing capabilities reduce network dependency for biometric processing. Semiconductor component volatility in East Asian touchscreen controller supply chains elevates input cost exposure.
- Integrated Systems:Hardwired installations within hospital IT infrastructure demand custom HL7 interface development for legacy EHR architectures.
- Mobile Kiosks:Battery-powered units on wheeled chassis enable flexible redeployment across clinical departments.
- Fixed Location Kiosks:Wall-mounted or countertop configurations minimize floor space requirements in constrained reception areas.
Integrated systems command the largest installed base; mobile kiosks expand most quickly through departmental flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks command premium pricing for integrated diagnostic terminals under Digital Care Act mandates, while United States procurement patterns favor managed service contracts that compress hardware margins. This pricing-power asymmetry shapes vendor resource allocation across development and certification budgets.
United States
Hospital networks in Texas and Florida are scaling self-service patient intake infrastructure to reduce administrative bottlenecks in high-volume emergency departments. FDA cybersecurity guidance for connected medical devices tightens software validation requirements, extending vendor qualification timelines. The Greater Boston cluster concentrates telemedicine kiosk development as virtual care reimbursement expands through regional payer networks.
Germany
Acute care networks under the Digital Care Act framework are accelerating tender volumes for integrated diagnostic terminals with Class IIa notified body certifications. The EU Medical Device Regulation mandates clinical evidence for diagnostic functions, elevating compliance documentation burdens. Bavaria's hospital digitization programs concentrate procurement decisions in Munich and Nuremberg metropolitan procurement consortia.
China
Retail pharmacy chains in Shanghai and Beijing are deploying diagnostic-grade terminals for cardiovascular risk screening under preventive care expansion programs. NMPA localization requirements for software components and GB standards impose additional hardware adaptation cycles. The Yangtze River Delta manufacturing base supplies touchscreen controllers and biometric sensor modules to domestic and export markets.
United Kingdom
National Health Service trusts are disaggregating equipment supply from multi-vendor maintenance panels to reduce vendor lock-in and improve uptime service-level agreements. GDPR patient data governance shapes kiosk architecture decisions for encrypted transmission protocols. London and Southeast England procurement clusters lead standardization efforts for templated corporate wellness deployments.
Japan
Corporate wellness centers in Tokyo and Osaka are adopting standardized kiosk configurations to accelerate rollout velocity through employer-sponsored health programs. METI industrial policy supports sensor miniaturization R&D for edge-computing diagnostic modules. The Kansai region's precision manufacturing base supplies multi-parameter biometric arrays to regional kiosk integrators.
Global Medical Kiosk Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor modules and enclosure engineering. The vendor base organizes around three strategic archetypes: financial services bundlers with captive leasing arms, vertically integrated manufacturers controlling North American production, and custom enclosure engineers occupying ADA-compliant premium niches. Consolidation pressure concentrates among capital-constrained mid-tier players facing 12-18 month FDA clearance timelines. Dominant competitive moves include equipment-as-a-service financing displacement of capital purchases and multi-vendor maintenance panel fragmentation of after-sales contracts.
Within the financial services bundler archetype, NCR Corporation represents the integrated hardware-leasing model through its managed service contract structure. KIOSK Information Systems anchors the vertically integrated manufacturing tier with North American production control. Olea Kiosks Inc. occupies the custom enclosure engineering position, exemplifying premium niche specialization through ADA compliance and infection control standards.
| Leading Market Players |
|---|
| NCR Corporation |
| KIOSK Information Systems |
| Olea Kiosks Inc. |
| Meridian Kiosks |
| Fabcon |
| RedyRef Interactive Kiosks |
| Oracle Corporation |
| imageHOLDERS |
| Advantech Co., Ltd. |
| Others |
Supply & Pricing Matrix
Semiconductor component volatility in East Asian foundry networks determines both the spread between premium diagnostic tiers and economy check-in terminals and the geographic clustering of final assembly capacity. Touchscreen controller and biometric sensor supply concentration compresses margins on mid-range configurations while elevating pricing power for vendors with captive component inventories or North American manufacturing footprints.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers based on diagnostic capability certification and after-sales bundling intensity. FDA 510(k) clearance tier and notified body certification under EU MDR create steep price differentiation between Class IIa diagnostic kiosks and administrative registration terminals. Cost compression in the standard tier intensifies as Asian contract manufacturers enter the check-in kiosk segment with stripped-down FHIR connectivity modules. Federally Qualified Health Centers exhibit acute price sensitivity due to capital constraints, while German acute care networks under Digital Care Act mandates demonstrate reduced elasticity for certified diagnostic configurations.
Supply Chain Analysis
Touchscreen controllers and biometric sensor modules feed from concentrated manufacturing bases in Taiwan, South Korea, and the Yangtze River Delta region of China. Multi-parameter sensor arrays, edge computing processors, and ADA-compliant enclosure materials constitute critical input dependencies. Single-source vulnerability in East Asian foundry exposure creates procurement risk for vendors lacking dual-qualified suppliers. Distribution runs through direct enterprise contracts with hospital networks and GPO-mediated procurement channels in the United States, supplemented by regional systems integrators in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical kiosk sector is recovering from extended FDA clearance backlogs, with reimbursement code stabilization for remote patient monitoring creating cyclical uplift in capital deployment velocity.
For Market Incumbents: Build regulatory certification moats through accelerated FDA 510(k) submission pipelines and EU MDR notified body pre-certification investments. Smartphone-based health apps threaten low-acuity patient capture; counter through deeper EHR integration partnerships with legacy hospital systems. Backward integration into biometric sensor module production reduces East Asian supply exposure. For New Entrants and Emerging Players: Pursue Federally Qualified Health Center deployments in rural United States markets where self-service infrastructure remains underpenetrated and RPM reimbursement coding creates sustainable utilization economics. Corporate wellness centers offer shorter sales cycles with templated configuration requirements. Position through equipment-as-a-service financing to bypass capital purchase barriers. For Investors and Strategic Acquirers: FDA cybersecurity guidance finalization reshapes the acquisition landscape by elevating firmware engineering capabilities to premium valuation status. Long-term viability centers on vendors with embedded systems security expertise and established hospital IT integration track records. Monitor telemedicine reimbursement expansion rates as the primary inflection signal for hybrid kiosk model adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Reduces 12-18 month clearance timelines that block institutional contract eligibility. |
| EU MDR Notified Body Certification | Unlocks German Digital Care Act tender participation with Class IIa diagnostic authority. |
| Hospital System Partnership | Secures multi-site managed service contracts with embedded HL7/FHIR integration requirements. |
| Biometric Sensor Module Development | Captures value from multi-parameter vital capture consolidation in diagnostic-grade terminals. |
| Reimbursement Strategy Investment | Aligns kiosk-delivered diagnostics with expanding RPM coding for sustainable utilization. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineers, GPO contracts directors, and kiosk manufacturing executives anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body registries, CMS reimbursement code updates, and hospital procurement tender records. Bottom-up unit deployment estimates triangulated with top-down market sizing across product type, application, end user, and deployment configuration segments.
Scenario-bracketing around reimbursement code adoption curves and semiconductor supply normalization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include diagnostic capability tier, clinical workflow integration depth, procurement sophistication level, and physical deployment architecture. CAGRs derived from weighted average of deployment velocity assumptions and average selling price trajectories. Industry-specific forecast inputs incorporated Digital Care Act tender pipeline visibility and virtual care reimbursement expansion rates.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or East Asian semiconductor output would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance timelines and reimbursement coding stability. Material shifts in FDA cybersecurity enforcement intensity or EU MDR clinical evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Cervical Spine System Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Ablation Devices Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Cytology Brush Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Medical Laser Cutting Device Market