
 Digital Phoropter Market | 2026-2036
Digital Phoropter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Phoropter Market Insights
Optical equipment distribution through regional wholesalers is fragmenting as manufacturers build direct relationships with large hospital networks and optical retail chains. Topcon Corporation leverages its established ophthalmic imaging portfolio to sustain dominance in premium digital phoropter installations across Japanese and North American eye care facilities. Nidek Co., Ltd. competes aggressively on automated refraction workflow integration, while Carl Zeiss Meditec AG anchors its position through combined diagnostic suite offerings that bundle phoropters with optical coherence tomography systems.
A digital phoropter is an automated refractive instrument that replaces manual lens wheels with precision stepper motors and liquid crystal displays, typically achieving refractive resolution of 0.12 diopters or finer through programmable lens combinations. Its primary purpose is to streamline subjective refraction examinations, reduce operator variability, and integrate measurement data directly into electronic health records. Digital phoropters command the highest margins within the product type segmentation as clinics prioritize workflow automation over manual alternatives, while portable phoropters represent the fastest-expanding category fueled by mobile screening programs and satellite clinic deployments. Among end users, eye clinics absorb the largest unit volumes, though optical retail stores increasingly specify smartphone-integrated phoropters that enable remote consultation and digital prescription sharing.
FDA 510(k) clearance requirements and EU MDR conformity assessment shape product development cycles and market access timelines for digital phoropter manufacturers. ISO 10993 biocompatibility standards and IEC 60601 electrical safety protocols further constrain material selection and electromagnetic compatibility design. Stakeholders must monitor how reimbursement policy shifts toward value-based eye care models will reshape capital equipment purchasing criteria across ambulatory settings.
Market Dynamics
Workflow automation demands from eye care chains are compressing capital equipment replacement cycles, forcing manufacturers to prioritize software interoperability over standalone hardware performance.
Growth Catalysts
- EU MDR conformity pathways:Accelerated CE marking timelines for automated refraction systems are opening synchronized market access across Germany, France, and Italy.
- Mobile screening programs:Government-funded rural vision initiatives in India are absorbing portable phoropter volumes at triple the rate of stationary installations.
- Optical coherence tomography integration:Combined diagnostic suites bundling phoropters with anterior segment imaging are locking in multi-year service contracts at large hospital networks.
Market Restraints
- Precision stepper motor supply:Japanese and German component suppliers control 80% of sub-arcminute positioning hardware, creating single-source vulnerability.
- FDA 510(k) review timelines:Software-as-medical-device classifications for cloud-connected phoropters are extending clearance durations by 8-14 months versus hardware-only submissions.
- Manual lens wheel substitutes:Low-cost conventional phoropters retain 35-40% share in price-sensitive Latin American and Southeast Asian procurement.
Strategic Opportunities
- Suburban optical retail expansion:Franchise networks in India's tier-2 cities are specifying smartphone-integrated phoropters for remote prescription validation.
- Tele-ophthalmology convergence:Pairing automated refraction with synchronous video consultation is creating reimbursable service lines in US Medicare Advantage plans.
- ISO 13485 certification arbitrage:Contract manufacturers in South Korea and Taiwan are offering faster quality management system pathways than legacy European suppliers.
Industry Challenges
- Electromagnetic compatibility testing:IEC 60601-1-2 compliance for liquid crystal display phoropters requires specialized anechoic chamber access that only three certified labs in North America provide.
- Legacy EMR integration:DICOM-compliant output formats from newer phoropter models fail to parse in 15-year-old practice management systems still operating in 40% of US independent optometry offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Phoropter Market |
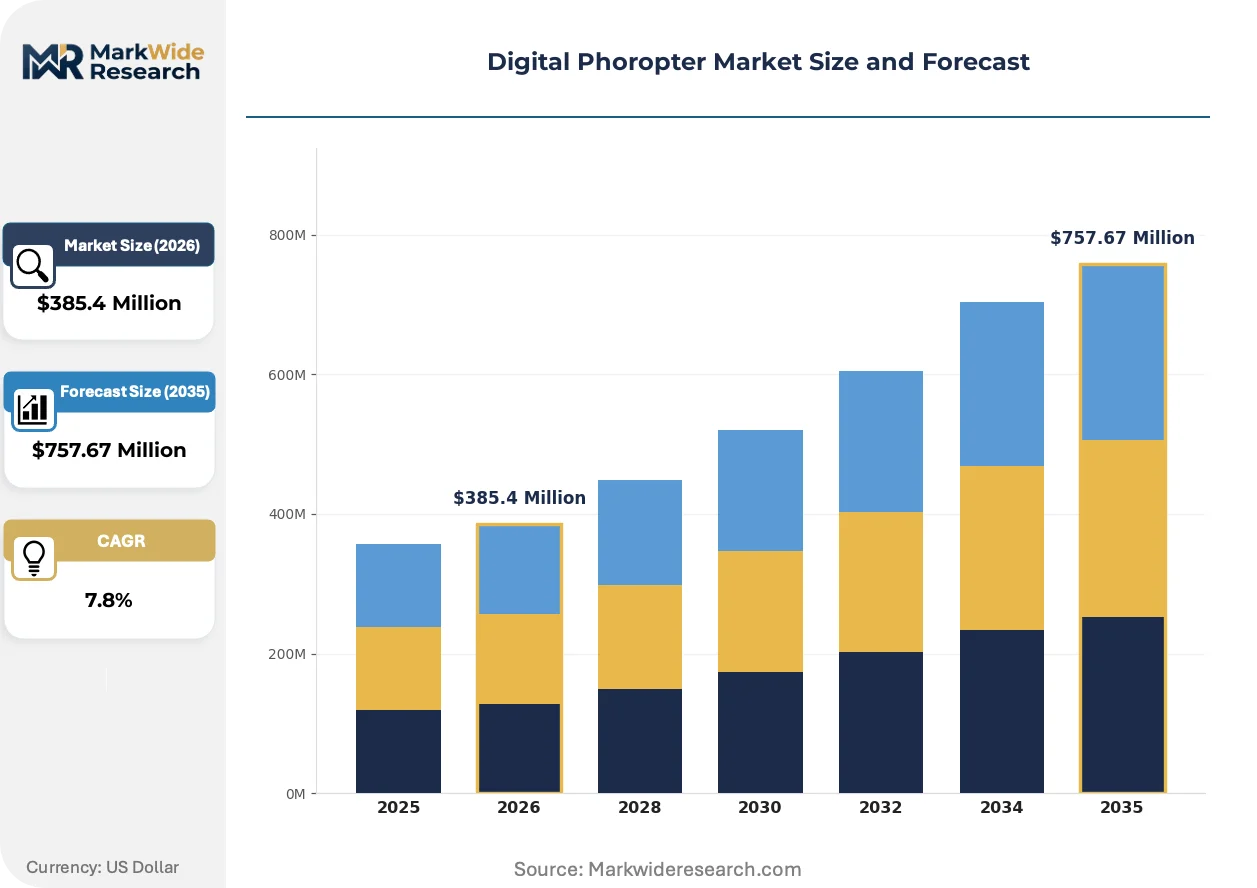
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Phoropters, Digital Phoropters, Portable Phoropters, Hybrid Phoropters End User: Hospitals, Eye Clinics, Optical Retail Stores, Educational Institutions Technology: Touchscreen, Remote Operated, Optical Coherence Tomography, Smartphone Integration Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Topcon Corporation, Nidek Co., Ltd., Reichert, Inc., Carl Zeiss Meditec AG, Essilor Instruments, Rexxam Co., Ltd., Huvitz Co., Ltd., Marco Technologies, Haag-Streit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Phoropter Market Trends and Innovations
Digital refraction technology is fragmenting into three distinct innovation vectors: precision hardware miniaturization, cloud-native software architectures, and service-based revenue models that displace outright equipment ownership.
Liquid crystal lens technology is migrating from research laboratory prototypes into commercial phoropter deployments. Early adopters at university-affiliated eye institutes in Japan and the Netherlands are validating sub-0.12 diopter resolution in clinical workflows. This precision threshold is compressing the performance gap between automated systems and skilled manual refractionists, forcing training programs to recertify technicians on interpretation rather than operation.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data from phoropter installations. Manufacturers must now embed automated adverse event reporting into device firmware, creating recurring cloud infrastructure costs that legacy hardware vendors struggle to absorb. German notified bodies are rejecting 510(k)-cleared US devices for CE marking gaps in software lifecycle documentation.
Optical retail chains are unbundling after-sales service from capital purchase contracts. Large networks in India and Brazil now demand per-exam pricing models with guaranteed uptime SLAs, transferring maintenance risk to manufacturers. This consumption-based structure is most visible in Reliance-backed Vision Express and Lenskart procurement specifications, which exclude traditional warranty terms entirely.
Digital Phoropter Market Segmentation
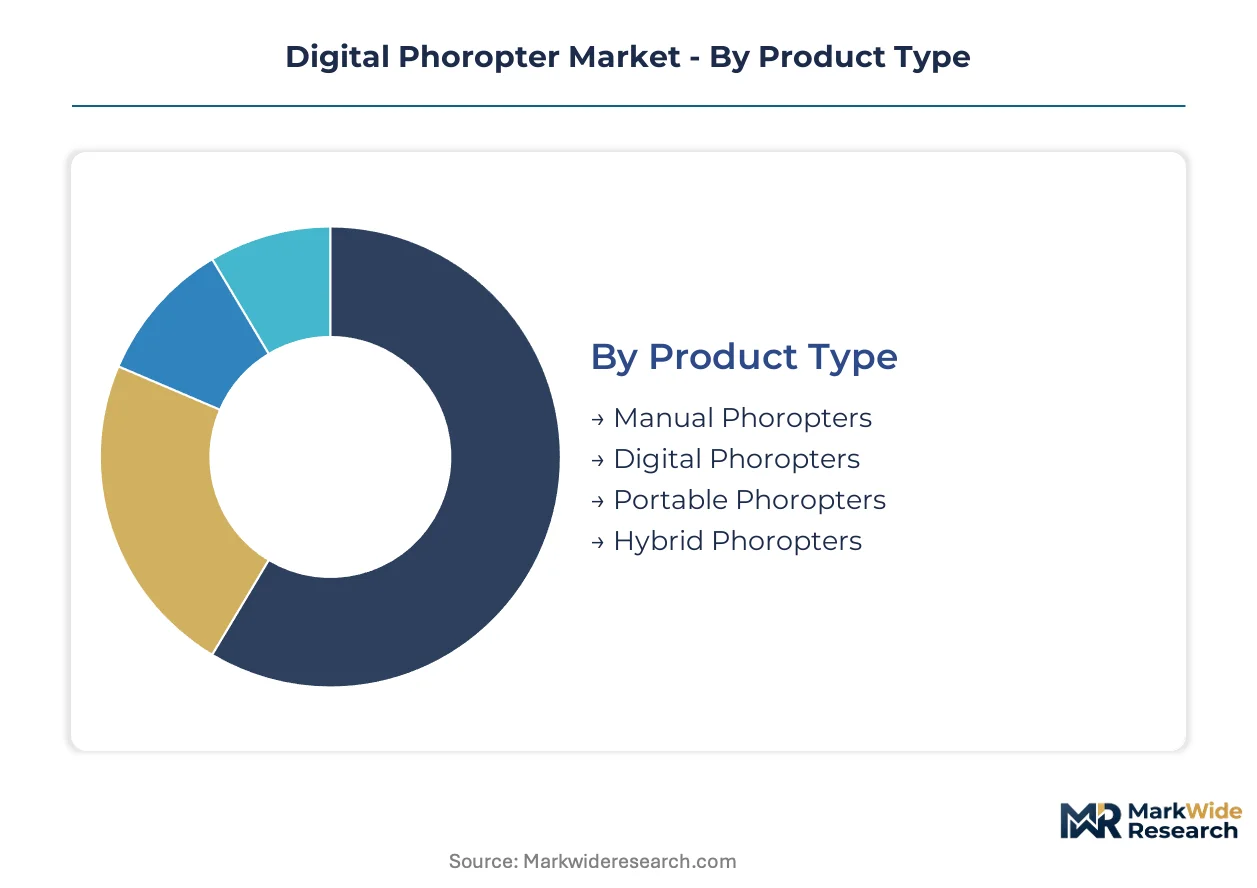
Segmentation in the digital phoropter market reveals how procurement patterns diverge between high-throughput hospital networks and fragmented independent practices. Equipment specifications, connectivity requirements, and service contract structures vary sharply across these divides.
Product Type:
After-sales service intensity escalates dramatically with automation level, as precision stepper motors and liquid crystal displays demand specialized calibration protocols that manual wheel systems avoid.
- Manual Phoropters:Conventional lens wheel assemblies with mechanical detent positioning dominate price-sensitive procurement in Latin American and Southeast Asian markets. Demand concentrates in rural clinics where capital constraints override workflow efficiency priorities.
- Digital Phoropters:Precision stepper motor systems achieve 0.12 diopter resolution through programmable lens combinations. Japanese and North American eye care facilities absorb the highest unit values as they prioritize electronic health record integration and reduced operator variability.
- Portable Phoropters:Battery-powered compact units with simplified optical trains serve mobile screening programs. Government-funded rural vision initiatives in India deploy these at triple the rate of stationary installations.
- Hybrid Phoropters:Dual-mode systems switch between automated and manual operation for training environments. Educational institutions in Germany and the Netherlands specify these for technician certification programs.
By volume, manual phoropters lead. By growth pace, portable phoropters are ahead.
End User:
Capital equipment purchasing authority concentrates differently across customer types, with optical retail chains wielding consolidated procurement power that independent practices cannot match.
- Hospitals:Integrated diagnostic suites bundling phoropters with anterior segment imaging systems lock in multi-year service contracts. Large hospital networks in Japan and Germany specify combined offerings from established ophthalmic imaging portfolios.
- Eye Clinics:Suburban and rural facilities expanding diagnostic capabilities drive automated refraction system adoption. These settings absorb the largest absolute unit volumes across all geographies.
- Optical Retail Stores:Franchise networks in India's tier-2 cities specify smartphone-integrated phoropters for remote prescription validation and digital prescription sharing.
- Educational Institutions:University-affiliated eye institutes validate emerging liquid crystal lens technology in clinical workflows. Early adoption concentrates in Japanese and Dutch training programs.
Eye clinics dominate unit shipments. Optical retail stores show the steepest expansion trajectory.
Technology:
Software architecture choices determine electromagnetic compatibility testing burdens and FDA 510(k) review timelines, with cloud-connected systems facing extended clearance durations.
- Touchscreen:Capacitive interface panels replace physical controls for streamlined technician workflows. These systems face IEC 60601-1-2 compliance requirements that only three certified North American labs can validate.
- Remote Operated:Network-enabled refraction enables synchronous video consultation for tele-ophthalmology service lines. US Medicare Advantage plans are creating reimbursable codes for these configurations.
- Optical Coherence Tomography:Bundled anterior segment imaging creates combined diagnostic suites. Large hospital networks specify these for comprehensive ophthalmic assessment workflows.
- Smartphone Integration:Bluetooth-connected phoropters enable remote consultation and digital prescription sharing. Optical retail chains in India and Brazil mandate this capability in procurement specifications.
Touchscreen interfaces hold the installed base. Smartphone integration is climbing the fastest.
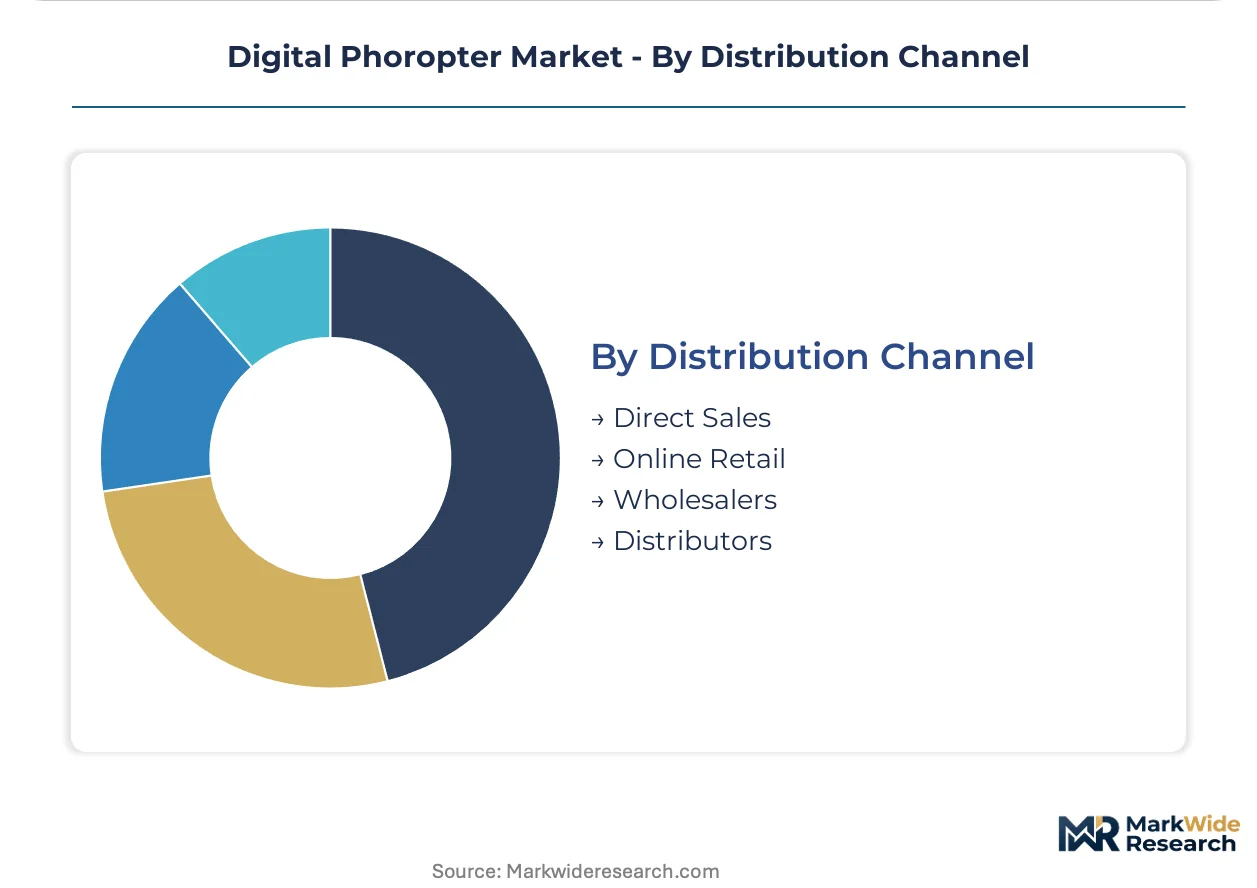
Distribution Channel:
Channel strategy directly shapes margin capture, with direct relationships preserving manufacturer pricing power that wholesale intermediaries erode.
- Direct Sales:Manufacturer relationships with large hospital networks and optical retail chains bypass regional wholesalers. Topcon Corporation and Carl Zeiss Meditec AG leverage established ophthalmic portfolios for premium installations.
- Online Retail:E-commerce platforms serve small independent practices with standardized configurations. These channels carry limited service contract options.
- Wholesalers:Regional optical equipment distributors fragment as manufacturers build direct relationships. Remaining wholesalers concentrate on replacement lens inventories and consumables.
- Distributors:Authorized partners with ISO 13485 certification provide faster quality management system pathways in South Korea and Taiwan compared to legacy European suppliers.
Direct sales generate the highest revenue per unit. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government vision screening programs and private optical retail expansion are concentrating procurement activity in specific national markets, with regulatory pathways shaping manufacturer prioritization across jurisdictions.
United States
Eye care chains and Medicare Advantage plans are driving automated refraction system adoption. FDA 510(k) clearance requirements for cloud-connected phoropters extend review timelines by 8-14 months versus hardware-only submissions. Independent optometry offices in the Midwest and Southeast still operate 15-year-old practice management systems that struggle with DICOM-compliant output formats from newer devices.
Germany
Large hospital networks specify combined diagnostic suites bundling phoropters with anterior segment imaging systems. EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up data, with German notified bodies rejecting devices for gaps in software lifecycle documentation. University-affiliated eye institutes in Heidelberg and Tübingen validate emerging liquid crystal lens technology.
India
Government-funded rural vision initiatives absorb portable phoropter volumes at triple the rate of stationary installations. CDSCO medical device regulations and state-level procurement policies shape public sector purchasing. Franchise networks in tier-2 cities including Pune, Jaipur, and Lucknow specify smartphone-integrated phoropters for remote prescription validation.
Japan
Premium digital phoropter installations dominate eye care facilities, with PMDA regulatory frameworks aligning with international standards. METI industrial policy supports precision stepper motor component supply chains. University-affiliated eye institutes in Tokyo and Osaka lead clinical validation of sub-0.12 diopter resolution liquid crystal lens systems.
Brazil
Optical retail chains unbundle after-sales service from capital purchase contracts, demanding per-exam pricing models with guaranteed uptime SLAs. ANVISA medical device registration requirements influence product development timelines. Large networks in São Paulo and Rio de Janeiro exclude traditional warranty terms entirely from procurement specifications.
Digital Phoropter Market Competitive Landscape
On the supply side, the industry is consolidating around established ophthalmic imaging portfolios and automated refraction workflow integration. Japanese and German component suppliers control precision positioning hardware, creating tiered dependency structures. Three strategic archetypes dominate: diversified optical equipment conglomerates, specialized refraction system manufacturers, and contract manufacturers offering accelerated quality certification pathways. Competitive moves center on direct relationship-building with hospital networks and optical retail chains, plus service-based revenue models that displace outright equipment ownership.
Within the diversified conglomerate tier, Topcon Corporation and Carl Zeiss Meditec AG exemplify players leveraging established ophthalmic portfolios for premium installations. Nidek Co., Ltd. represents the specialized automation vector, competing on workflow integration rather than bundled diagnostic suites. These three anchors demonstrate how geographic origin and company structure correlate with strategic positioning: Tokyo-based Topcon and Nidek occupy distinct automation-versus-imaging niches, while German AG-structured Carl Zeiss Meditec anchors combined diagnostic suite offerings.
| Leading Market Players |
|---|
| Topcon Corporation |
| Nidek Co., Ltd. |
| Reichert, Inc. |
| Carl Zeiss Meditec AG |
| Essilor Instruments |
| Rexxam Co., Ltd. |
| Huvitz Co., Ltd. |
| Marco Technologies |
| Haag-Streit Group |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese and German precision stepper motor suppliers determines both pricing tier spreads and supply chain shape across the digital phoropter market. Manufacturers absorbing component cost volatility pass through premium positioning to hospital networks while compressing margins on portable units destined for government screening programs.
Pricing Analysis
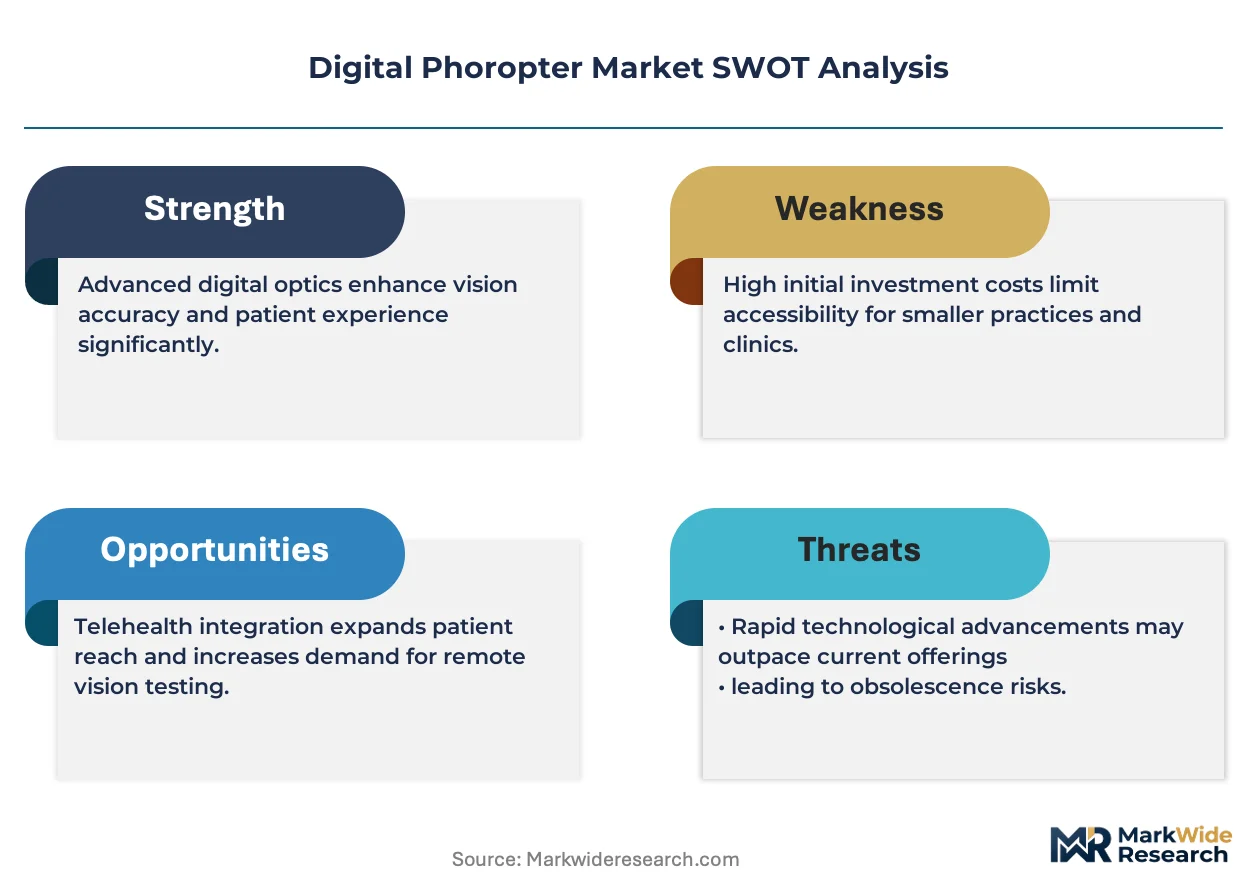
Certification level (FDA 510(k)-grade versus CE-marked tiers) creates the primary spread between premium installations and economy alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth, with bundled service contracts commanding 40-60% lifetime value premiums over hardware-only transactions. Cost compression in the portable segment intensifies because Indian state procurement policies cap unit prices for rural vision initiatives. Independent optometry offices in the US Midwest exhibit highest price sensitivity due to legacy EMR replacement burdens, while Japanese hospital networks show lowest sensitivity given METI-supported equipment depreciation schedules.
Supply Chain Analysis
Extended payment terms from South Korean and Taiwanese contract manufacturers now finance 90-120 day inventory cycles for mid-tier phoropter assemblers. Precision stepper motor production concentrates in Japan and Germany, while liquid crystal display panels source primarily from South Korea and Taiwan. The supply chain rests on single-source vulnerability for sub-arcminute positioning hardware controlled by two component suppliers. Distribution runs through direct manufacturer relationships with large hospital networks, bypassing regional wholesalers that previously intermediated 60% of optical equipment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital phoropter market represents high-growth disruption as EU MDR Article 10 post-market surveillance mandates force firmware-level adverse event reporting that legacy vendors cannot absorb.
For Market Incumbents: Entrench through backward integration into precision stepper motor supply chains and accelerated ISO 13485 certification arbitrage via South Korean contract manufacturers. Lock in multi-year service contracts with large hospital networks before cloud-native entrants achieve FDA 510(k) clearance for software-as-medical-device classifications. The threat of liquid crystal lens technology validation at university-affiliated eye institutes demands R&D investment in sub-0.12 diopter resolution systems. For New Entrants and Emerging Players: Build out smartphone-integrated phoropter platforms targeting India's tier-2 optical retail franchise networks, where Reliance-backed Vision Express and Lenskart procurement specifications exclude traditional warranty terms entirely. The most penetrable segment lies in portable units for government-funded rural vision initiatives, which absorb volumes at triple the rate of stationary installations. A per-exam pricing model with guaranteed uptime SLAs unlocks capital-constrained procurement committees. For Investors and Strategic Acquirers: EU MDR conformity pathway acceleration reshapes the acquisition landscape toward notified body relationships and software lifecycle documentation capabilities. Long-term viability centers on service-based revenue models that displace outright equipment ownership across optical retail chains. The signal to monitor is ANVISA registration timeline compression in Brazil, where per-exam pricing adoption indicates market readiness for consumption-based structures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance opens synchronized access across German, French, and Italian hospital networks. |
| Hospital System Partnership | Combined diagnostic suite bundling with anterior segment imaging locks in multi-year service contracts at Japanese networks. |
| Software Companion Development | Cloud-native firmware embedding automated adverse event reporting satisfies post-market surveillance mandates. |
| Reimbursement Strategy | Medicare Advantage reimbursable codes for tele-ophthalmology configurations drive US optical retail adoption. |
| Backward Integration | In-house production of precision stepper motor components reduces single-source vulnerability from Japanese suppliers. |
Research Methodology
Operator-level perspectives from ophthalmic equipment procurement managers, biomedical engineers at hospital networks, optical retail chain category directors, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CDSCO medical device registrations, and hospital procurement databases. Bottom-up unit shipment modeling and top-down value triangulation cross-checked segment assumptions across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type automation level, end-user purchasing authority concentration, technology connectivity architecture, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating liquid crystal lens technology adoption curves and smartphone integration penetration rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software entrants or accelerated EU MDR enforcement would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Machine Battery Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Russia Viscosupplementation Market