
 Anti-Aging Devices Market | 2026-2036
Anti-Aging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging Devices Market Analysis
Multi-source component sourcing for laser and RF modules is expanding as manufacturers diversify beyond single Japanese or German optics suppliers. Alma Laser leverages its vertically integrated manufacturing in Israel to control diode quality and reduce lead times. Lumenis sustains R&D intensity across three continents, anchoring its position in surgical and aesthetic laser platforms. Cynosure competes through specialized distribution partnerships with dermatology practice networks in North America.
Anti-aging devices are electromechanical or photonic systems engineered to deliver controlled energy—typically 1-20 MHz radiofrequency, 532-1064 nm laser wavelengths, or 415-660 nm LED spectra—to dermal tissue for collagen remodeling, melanin targeting, or epidermal resurfacing. Their primary commercial purpose is to provide non-invasive or minimally invasive alternatives to surgical cosmetic procedures in clinical and consumer settings. RF devices and laser devices command the deepest margin pools in professional channels, where treatment pricing reflects capital equipment amortization and consumable attachment rates. LED light therapy represents the fastest-expanding device type, driven by falling semiconductor costs and direct-to-consumer channel maturation. Home users now constitute a structurally distinct end-user segment, with NuFACE and Solawave occupying premium and mass-market tiers respectively through differentiated price-positioning and channel control.
The FDA's 510(k) clearance framework governs market access for laser and RF devices in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for Class IIa and IIb aesthetic equipment sold in Europe. Japan's PMDA maintains distinct technical standards for high-intensity laser devices, creating additional compliance layers for manufacturers seeking Asian market entry. Stakeholders must monitor evolving MDR implementation timelines and FDA software-as-medical-device guidance for AI-enabled skin analysis features.
Market Dynamics
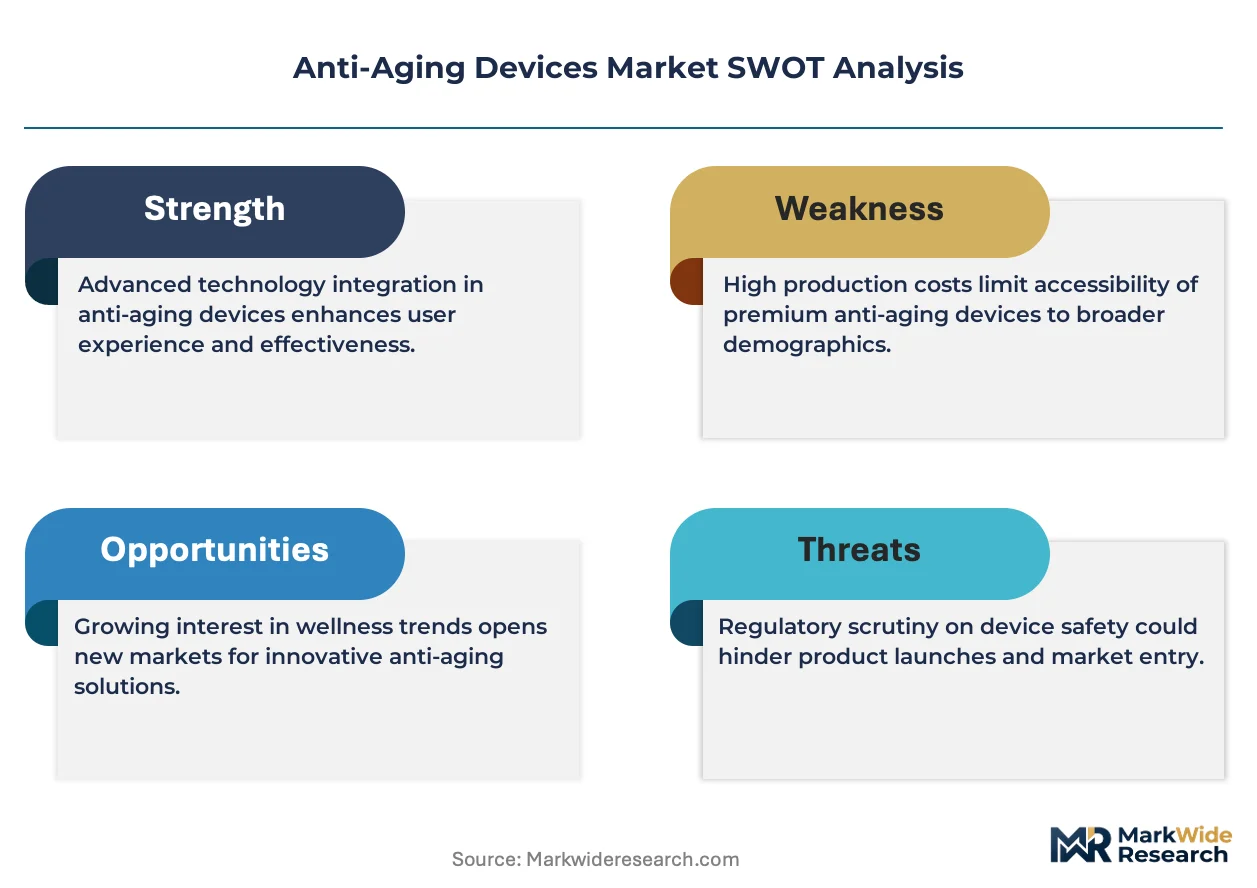
The anti-aging devices sector pivots on semiconductor cost deflation enabling consumer-grade LED and RF platforms to replicate clinical efficacy thresholds previously gated by capital-intensive laser systems.
Growth Catalysts
- EU MDR harmonization:Streamlined Class IIa aesthetic device pathways in Europe reduce redundant clinical trials, accelerating multi-country launches for manufacturers with existing FDA 510(k) clearances.
- Medspa consolidation:Roll-up strategies by US dermatology practice networks concentrate procurement volume, favoring vendors offering lease-to-own financing and bundled consumable contracts.
- GaN-on-Si diode fabrication:Silicon-substrate gallium nitride production cuts LED component costs by half versus sapphire-based alternatives, unlocking mass-market price points for home-use devices.
Market Restraints
- Optics supply concentration:German and Japanese specialty glass manufacturers control 80% of high-transmission lens substrates for fractional laser handpieces, creating single-source vulnerability.
- RF electrode material volatility:Palladium and platinum spot price swings directly impact consumable electrode costs for microneedling-RF combination devices.
- FDA software-as-medical-device guidance:Unclear AI-enabled skin analysis classification thresholds delay feature rollouts and expand compliance budgets for connected device platforms.
Strategic Opportunities
- India's medical aesthetics liberalization:CDSCO streamlined import licensing for non-ablative lasers creates first-mover advantage for brands establishing training infrastructure in Mumbai and Delhi.
- Subscription hardware models:Device-as-a-service pricing for professional-grade home units captures recurring revenue streams while lowering consumer entry barriers.
- Photobiomodulation-neuroscience convergence:LED wavelengths targeting mitochondrial function in cognitive wellness applications extend addressable market beyond dermatology into wellness clinics.
Industry Challenges
- Biomedical optics engineering scarcity:PhD-level talent capable of integrating thermal modeling with tissue optics simulation commands premium compensation and extends R&D timelines.
- Legacy practice management system integration:New device platforms require API connectivity with established electronic health record workflows, complicating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging Devices Market |
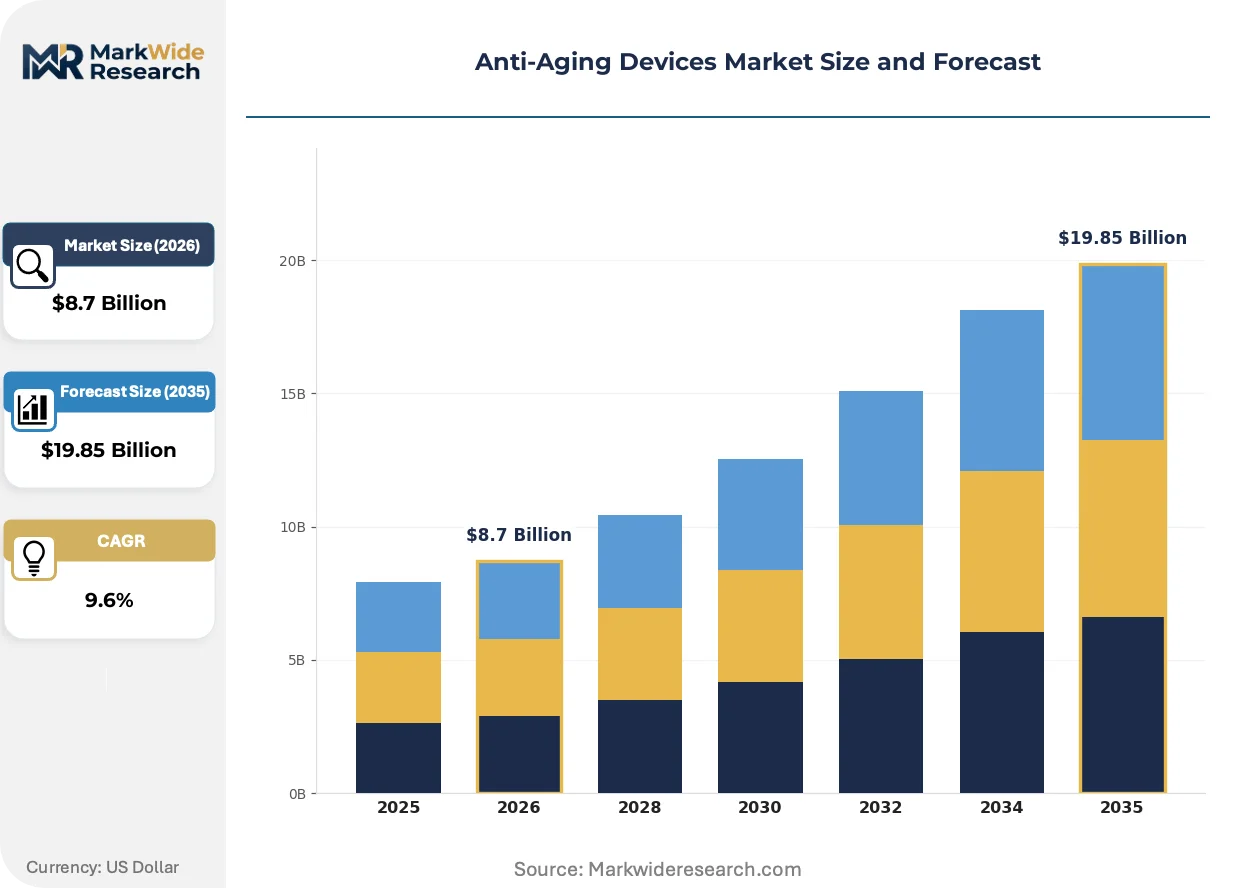
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.85 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Devices, Microdermabrasion Tools, LED Light Therapy, RF Devices Tech Method: Ultrasound, Radiofrequency, Chemical Peels, Microneedling End User: Health Clinics, Beauty Spas, Home Users, Dermatology Practices Target Area: Facial Treatment, Neck Treatment, Body Treatment, Eye Area |
| Companies Covered | Allergan, Alma Laser, Cynosure, Lumenis, Photomedex, Solta Medical, NuFACE, Solawave, CurrentBody, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging Devices Market Emerging Trajectories
Multi-wavelength platform architectures and AI-guided treatment protocols are compressing the capability gap between clinical and consumer device tiers, while regulatory frameworks scramble to keep pace with software-enabled feature expansion.
Fractional laser technology is consolidating around erbium-doped and thulium fiber platforms that deliver controlled microthermal zones without epidermal ablation. US dermatology practices are standardizing on these modalities for melasma and acne scar protocols. The shift is consolidating capital equipment purchasing around vendors offering modular handpiece ecosystems rather than single-wavelength systems.
Japan's PMDA revised technical standards for high-intensity laser classification in 2023, tightening documentation requirements for beam divergence and eye safety interlocks. Domestic manufacturers must now submit extended biological safety data for devices exceeding specific fluence thresholds. Professional channel players are responding by pre-certifying platforms for both PMDA and FDA pathways to streamline Asian market entry.
Direct-to-consumer brands now bundle telemedicine consultations with device purchases, replacing traditional retail channel markups with subscription-based expert access. This model disrupts legacy medspa referral networks that previously captured home-use device recommendations. The transformation is most visible in US urban markets where dermatology appointment wait times exceed eight weeks.
Anti-Aging Devices Market Segmentation
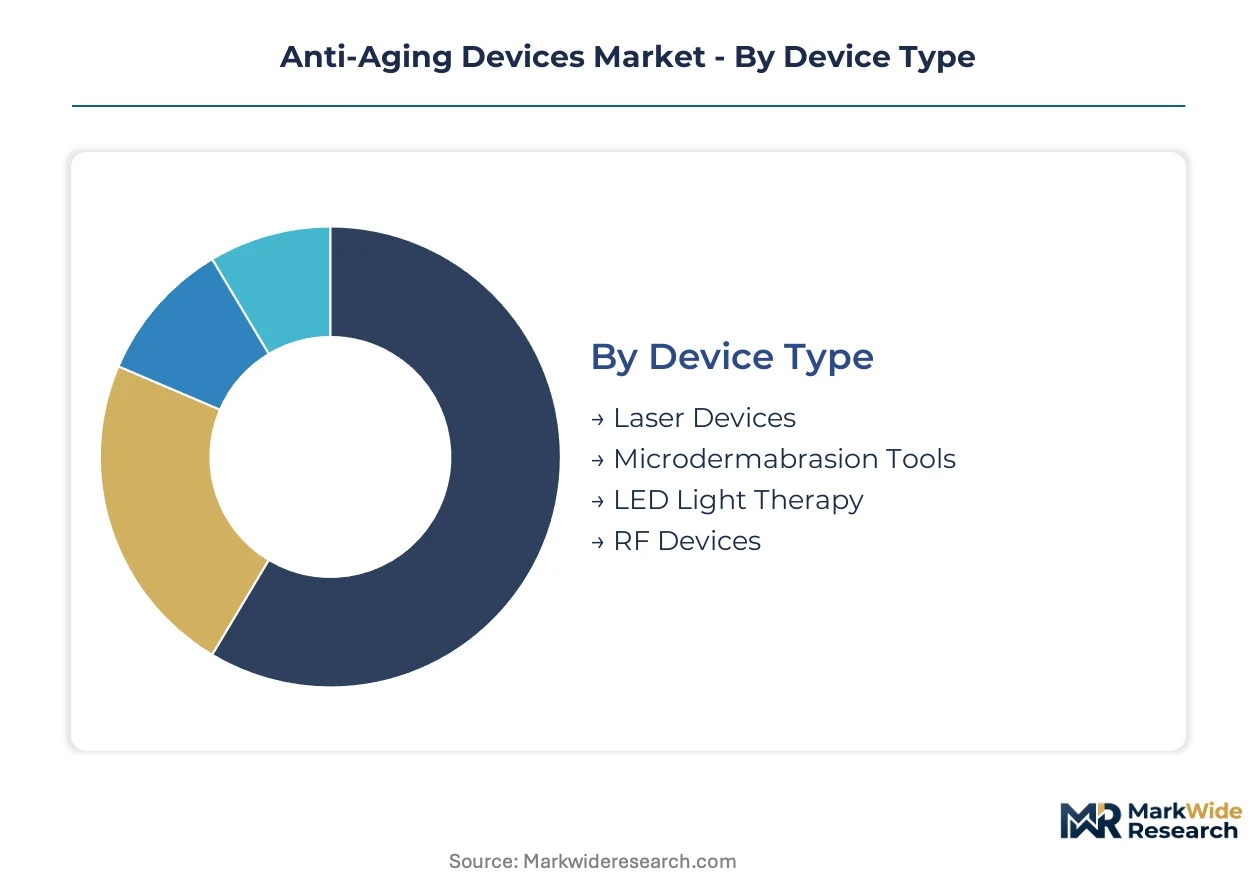
Device segmentation in anti-aging technology separates capital-intensive professional systems from accessible consumer platforms. Each category reflects distinct energy delivery mechanisms, clinical validation requirements, and channel economics that shape manufacturer R&D priorities.
Device Type:
Volume concentration clusters in lower-cost photonic systems, while premium capture remains with capital equipment requiring clinical infrastructure.
- RF Devices:Electromagnetic energy delivery at 1-20 MHz penetrates dermal layers to induce collagen neogenesis through controlled thermal injury. Dermatology practices in the United States favor these systems for their predictable downtime profiles and high patient throughput capacity.
- LED Light Therapy:Semiconductor arrays emitting 415-660 nm wavelengths trigger photobiomodulation at the mitochondrial level. Home users in urban markets with limited dermatology appointment availability drive unit volume expansion as component costs decline.
- Laser Devices:Coherent light systems at 532-1064 nm enable precise chromophore targeting for resurfacing and pigmentation protocols.
- Microdermabrasion Tools:Mechanical exfoliation devices utilizing aluminum oxide crystals or diamond-tipped wands for epidermal renewal.
Mature deployment sits with laser devices requiring extensive training infrastructure. Newer deployment is concentrated in LED platforms bypassing clinical gatekeepers entirely.
Tech Method:
Application setting determines energy intensity thresholds and corresponding regulatory classification burdens.
- Radiofrequency:Thermal collagen remodeling through tissue impedance generates consistent outcomes across skin phototypes. Medspa chains in California and Florida standardize on monopolar and bipolar configurations for body contouring protocols.
- Microneedling:Percutaneous collagen induction combined with RF energy delivery addresses acne scarring and textural irregularities. Dermatology practices seeking procedure differentiation drive adoption of insulated needle arrays with adjustable depth control.
- Ultrasound:Microfocused thermal coagulation at specific tissue depths enables non-invasive lifting applications.
- Chemical Peels:Acid-based exfoliation systems ranging from superficial glycolic formulations to deep phenol solutions.
Established clinical workflows center on chemical peel protocols. Emerging adoption concentrates in microneedling-RF combinations offering additive efficacy claims.
End User:
Channel structure fragments between institutional procurement with extended sales cycles and direct-to-consumer velocity with compressed margins.
- Home Users:Consumer-grade devices with simplified interfaces and safety interlocks replicate subset clinical outcomes. Metropolitan markets with dermatology appointment wait times exceeding eight weeks show steepest expansion trajectory for handheld LED and microcurrent systems.
- Dermatology Practices:Physician-supervised settings demand FDA 510(k) cleared platforms with documented efficacy data and training certification programs.
- Beauty Spas:Non-medical aesthetic venues operate under state board cosmetology regulations with restricted energy delivery parameters.
- Health Clinics:Integrative medicine settings incorporate photobiomodulation for wellness applications beyond cosmetic indications.
Revenue concentration persists in dermatology practices commanding premium per-procedure pricing. Volume expansion is gaining share fastest in home user segments as telemedicine consultation bundles replace traditional retail distribution.
Target Area:
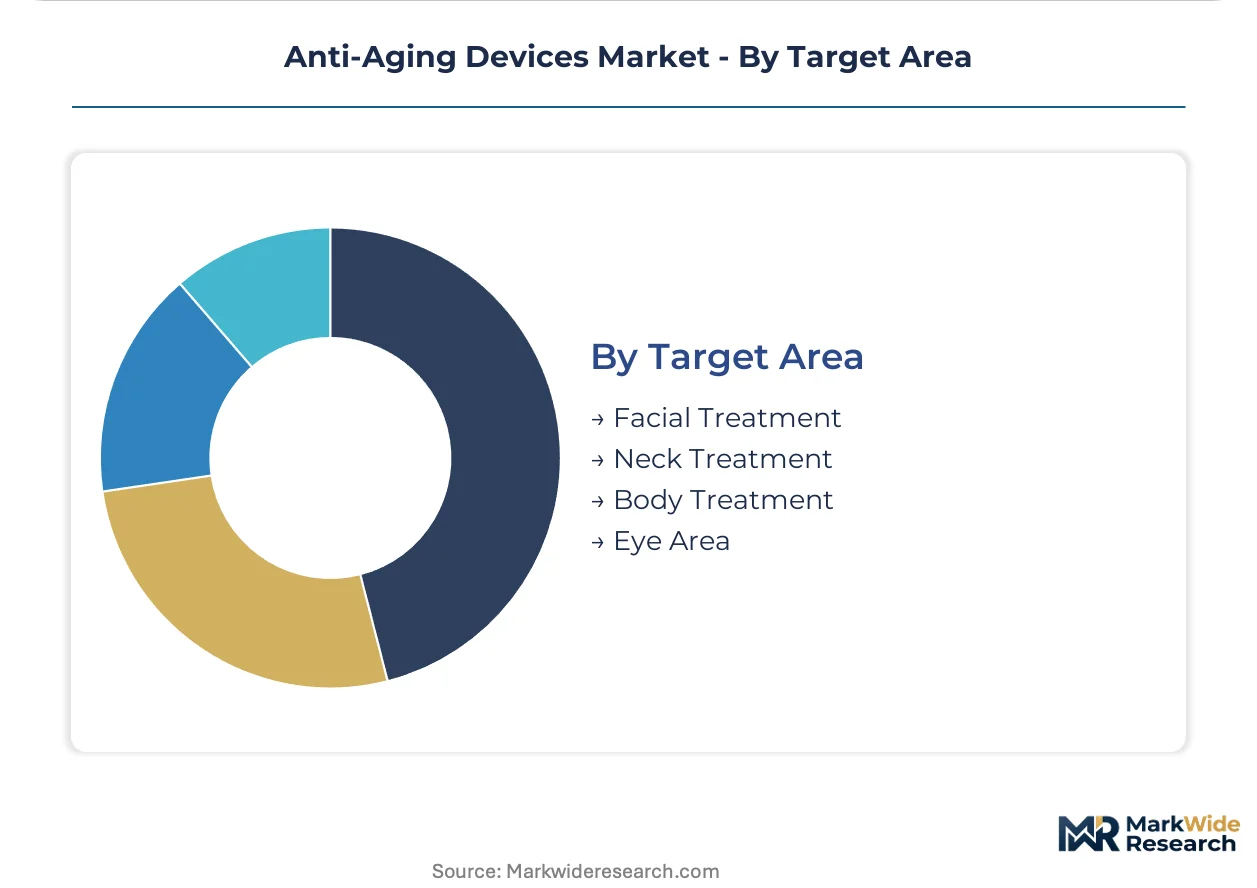
Anatomical specificity dictates device form factor, energy delivery precision, and corresponding price positioning.
- Facial Treatment:Full-face platforms address rhytides, dyschromia, and laxity through modular handpiece ecosystems. United States medspa networks prioritize multi-wavelength systems capable of sequential treatment protocols without equipment changeover.
- Eye Area:Periorbital anatomy requires specialized delivery mechanisms with reduced spot sizes and enhanced cooling systems to protect delicate tissue.
- Neck Treatment:Submental contouring and décolletage rejuvenation applications utilize adapted facial protocols with modified energy parameters.
- Body Treatment:Larger surface areas and adipose tissue penetration requirements drive distinct device architectures with expanded treatment heads.
Equipment standardization is most advanced in facial treatment modules. Innovation investment is concentrating in eye area specialization as manufacturers seek differentiation in crowded facial aesthetics markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli diode fabrication facilities supply critical semiconductor substrates to manufacturers worldwide, anchoring the upstream material base for photonic anti-aging systems across North America, Europe, and Asia.
United States
Medspa consolidation in California and Florida concentrates procurement volume for professional-grade RF and laser platforms. FDA 510(k) clearance pathways govern market access timelines, with dermatology practices in Manhattan and Los Angeles driving premium device adoption through lease-to-own financing structures.
Germany
Specialty glass manufacturers in Bavaria and Baden-Württemberg control high-transmission lens substrates for fractional laser handpieces. EU MDR harmonization streamlines Class IIa aesthetic device pathways, reducing redundant clinical trials for manufacturers with existing FDA clearances.
Israel
Vertically integrated manufacturing clusters in Caesarea and Yokne'am control diode quality and reduce lead times for global OEM customers. The country's advanced optics engineering talent pool supports thermal modeling and tissue optics simulation for next-generation platform development.
Japan
Domestic manufacturers in Tokyo and Osaka face tightened PMDA technical standards for high-intensity laser classification implemented in 2023. Extended biological safety data requirements for devices exceeding specific fluence thresholds favor pre-certified platforms targeting both PMDA and FDA pathways.
India
CDSCO streamlined import licensing for non-ablative lasers creates first-mover advantage for brands establishing training infrastructure in Mumbai and Delhi. Metropolitan dermatology appointment wait times exceeding eight weeks accelerate home-use device penetration in Bangalore and Hyderabad.
Anti-Aging Devices Market Vendor Landscape
Global majors compete with regional champions across regulatory certification and distribution channel control. The vendor base separates into three tiers: capital equipment specialists with vertically integrated manufacturing, direct-to-consumer brands with telemedicine bundling capabilities, and component suppliers capturing value from semiconductor cost deflation. Strategic moves concentrate on lease-to-own financing structures for professional channels and subscription hardware models for consumer segments.
Within the capital equipment tier, Alma Laser and Lumenis exemplify vertically integrated specialists controlling upstream diode production. Cynosure occupies a position emphasizing specialized distribution partnerships with dermatology practice networks. Among direct-to-consumer entrants, NuFACE and Solawave represent differentiated price-positioning strategies across premium and mass-market tiers through channel control and simplified safety interlocks.
| Leading Market Players |
|---|
| Allergan |
| Alma Laser |
| Cynosure |
| Lumenis |
| Photomedex |
| Solta Medical |
| NuFACE |
| Solawave |
| CurrentBody |
| Others |
Supply Flow & Price Mechanics
EU MDR harmonization and evolving FDA software-as-medical-device guidance gate qualified supply access and premium-tier pricing power, as manufacturers absorbing extended clinical validation timelines and AI-enabled feature compliance costs pass these burdens through to professional-grade device tiers while consumer segments face margin compression from semiconductor cost deflation.
Pricing Analysis
Warranty and service bundling separates professional RF and laser platforms from unbundled consumer LED devices, with dermatology practices paying premium rates for multi-year maintenance contracts and training certification while home users absorb replacement risk. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, optical component grade, and software feature depth. Cost compression in home-use tiers is intensifying because GaN-on-Si diode fabrication cuts LED substrate costs, with metropolitan home users showing highest price sensitivity and institutional dermatology practices least sensitive due to per-procedure revenue recovery.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and domestic-content mandates in medical device procurement are reshaping sourcing strategies for brands seeking tariff-advantaged positions in Asian markets. German and Japanese specialty glass manufacturers supply high-transmission lens substrates, while Israeli fabrication facilities control gallium nitride diode quality for global OEM customers. Palladium and platinum spot price volatility creates raw material risk for microneedling-RF electrode consumables. Distribution runs through specialized dermatology practice networks and direct-to-consumer telemedicine bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor-based LED platforms are displacing legacy laser systems in consumer channels, compressing the capability gap between clinical and home-use tiers and forcing strategic repositioning across manufacturer categories.
For Market Incumbents: Extend platform modularity to defend against pure-play LED entrants, integrating multi-wavelength handpiece ecosystems that lock dermatology practices into consumable attachment revenue. Backward integration into gallium nitride diode production secures supply continuity as Israeli fabrication capacity tightens. Channel control through lease-to-own financing structures preserves procurement relationships against subscription-hardware challengers. For New Entrants and Emerging Players: AI-guided treatment protocol software offers a technology-first wedge into the professional tier, bypassing capital-intensive optical hardware requirements. India's streamlined CDSCO import licensing for non-ablative lasers represents the most penetrable geography for first-mover training infrastructure investment. Telemedicine consultation bundling replaces traditional retail markups with recurring expert-access revenue. For Investors and Strategic Acquirers: FDA 510(k) clearance backlog duration is the leading indicator that regulatory capacity constraints will favor acquirers of pre-cleared platform assets over de novo development. Acquisition targets should show vertically integrated manufacturing footprints in Israel or Germany, captive diode supply, and established GPO contracts with US dermatology networks. Photobiomodulation-neuroscience convergence applications signal long-term addressable market expansion beyond cosmetic indications.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Wavelength Platform Integration | Modular handpiece ecosystems enable sequential facial protocols without equipment changeover in Manhattan and Los Angeles practices. |
| GaN-on-Si Diode Fabrication Scale-Up | Silicon-substrate production cuts LED component costs and unlocks mass-market price points for home-use devices. |
| Telemedicine Consultation Bundling | Subscription-based expert access disrupts legacy medspa referral networks in US urban markets with eight-week appointment waits. |
| PMDA-FDA Dual Pathway Certification | Pre-certification for both Japanese and US regulators streamlines Asian market entry amid tightened beam divergence standards. |
| Photobiomodulation Wellness Extension | Mitochondrial-targeting LED wavelengths extend device applications into integrative medicine clinics beyond dermatology. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across device engineering directors, dermatology practice purchasing managers, biomedical optics PhD researchers, and medspa chain procurement leads. FDA 510(k) clearance databases, EU MDR technical documentation, Japan PMDA submission records, and CDSCO import licensing registries supplied validation. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Granularity-level modeling captured device type, technology method, end-user channel, and target anatomical area across the projection horizon. RF frequency bands, laser wavelength categories, and LED spectra ranges defined technical segmentation. Professional versus consumer price positioning and consumable attachment rates informed revenue per unit assumptions. CAGRs derived from semiconductor cost curves, regulatory pathway timelines, and channel penetration saturation analysis.
Several conditions sit outside the modeled scope, including unforeseen FDA software-as-medical-device reclassification, palladium supply disruption from geopolitical events, and breakthrough non-photonic anti-aging modalities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Annuloplasty System Market
Medical Devices
Dosing Units Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Global Spirometers Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market