
 Subcutaneous Drug Delivery Devices Market | 2026-2036
Subcutaneous Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Subcutaneous Drug Delivery Devices Market Intelligence
Home care is repositioning as the dominant end-use setting for subcutaneous drug delivery, displacing hospital-centric administration for chronic therapies. Becton, Dickinson and Company anchors this shift through its extensive portfolio of pre-filled syringes and pen injectors designed for patient self-use. Ypsomed AG specializes in automated patch pump platforms that reduce training burdens for non-clinical caregivers. Insulet Corporation dominates tubeless insulin delivery with its wearable form factors that integrate continuous glucose monitoring data streams.
Subcutaneous drug delivery devices are mechanical or electromechanical systems engineered to administer therapeutic agents into the adipose tissue layer beneath the dermis, typically operating at injection depths of 4-10 millimeters and volumes ranging from 0.5 mL to 10 mL depending on device class. These systems serve the primary commercial purpose of enabling non-venous administration for biologics, peptides, and small-molecule drugs that require sustained absorption profiles or patient-managed dosing regimens. Wearable injectors represent the fastest-expanding product category as pharmaceutical sponsors seek alternatives to intravenous infusion for high-volume biologics previously confined to clinical settings. Patch pumps within the technology dimension command premium positioning due to their programmable basal-bolus capabilities and Bluetooth connectivity for remote monitoring. Home care as an end-user segment captures disproportionate margin pools because device makers can bundle training services, digital adherence platforms, and recurring consumable revenue streams.
FDA combination product regulations, EMA medical device directives under MDR, and ISO 11608 standards for needle-based injection systems collectively govern device design validation, human factors testing, and post-market surveillance obligations. These frameworks elevate barriers for new entrants while rewarding incumbents with established quality management systems and regulatory dossier libraries. Stakeholders must monitor evolving pharmacovigilance requirements for drug-device combination products as health technology assessment bodies increasingly demand real-world adherence evidence alongside traditional efficacy data.
Market Dynamics
Wearable injector platforms are compressing the traditional hospital-to-home transition timeline for biologic therapies, forcing device manufacturers to integrate connectivity, training, and adherence monitoring into single product ecosystems.
Growth Catalysts
- ISO 11608 harmonization:Unified needle-based injection standards across FDA and EMA jurisdictions reduce duplicate validation studies for combination product sponsors.
- Home care infrastructure:Reimbursement pathways for self-administered biologics in Germany and Japan now cover device training and remote monitoring services.
- Adipose tissue pharmacokinetics:Sustained absorption profiles for monoclonal antibodies enable less frequent dosing versus intravenous alternatives.
Market Restraints
- Polymer supply concentration:Cyclic olefin copolymer for pre-filled syringe barrels sources predominantly from Japanese and German chemical suppliers.
- MDR technical documentation:European notified body capacity constraints extend CE marking timelines for Class IIb wearable injectors.
- Needlestick safety mandates:OSHA bloodborne pathogen standards and EU sharps directives impose redundant engineering controls on legacy pen injector designs.
Strategic Opportunities
- India chronic disease burden:Diabetes and rheumatoid arthritis prevalence outpaces infusion center capacity in tier-2 and tier-3 cities.
- Bluetooth-enabled adherence platforms:Convergence of drug delivery hardware with smartphone applications creates recurring software revenue streams.
- Japan PMDA Sakigake designation:Expedited review pathways for innovative drug-device combinations accelerate market entry for first-in-class therapies.
Industry Challenges
- Human factors engineering talent:Shortage of specialists capable of executing FDA-required usability validation for elderly and pediatric patient populations.
- Combination product dossier complexity:Synchronized pharmaceutical and device quality systems demand cross-functional regulatory expertise rarely housed within single organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subcutaneous Drug Delivery Devices Market |
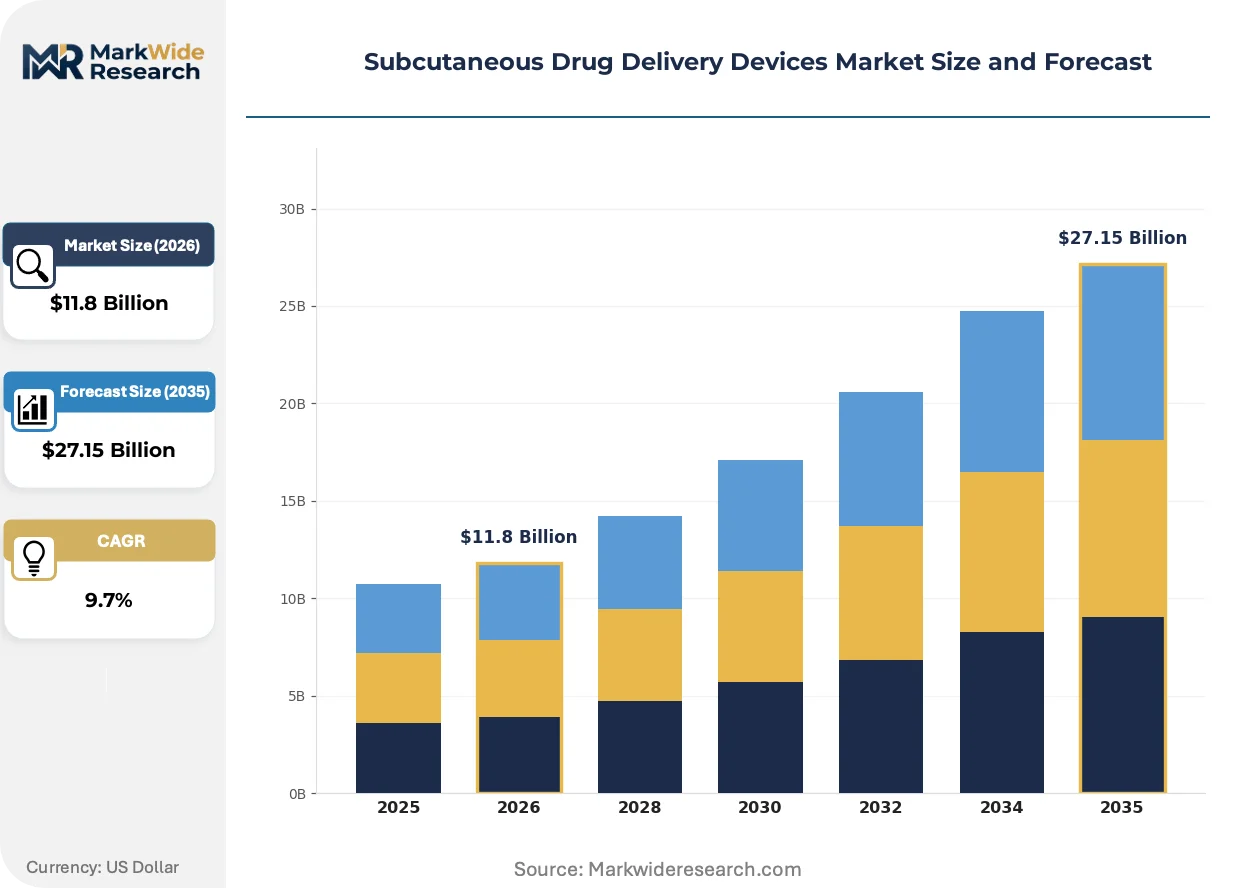
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $27.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Infusion Pumps, Pre-filled Syringes, Wearable Injectors Technology: Microneedle Technology, Electroporation, Patch Pumps, Traditional Syringes End User: Home Care, Hospitals, Specialty Clinics, Retail Pharmacies Delivery Mode: Bolus Delivery, Continuous Delivery, Image-guided Delivery, Manual Delivery |
| Companies Covered | Becton, Dickinson and Company, Ypsomed AG, Gerresheimer AG, Insulet Corporation, Medtronic Plc, Novo Nordisk, West Pharmaceutical Services, Inc., Owen Mumford, Elcam Medical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subcutaneous Drug Delivery Devices Market Strategic Shifts & Innovations
Electromechanical delivery mechanisms are displacing purely mechanical systems across high-volume biologic categories, embedding sensors and feedback loops that transform passive devices into active therapeutic companions.
Large-volume wearable injectors are consolidating the administration of 2-10 mL biologic formulations previously restricted to clinical infusion suites. Oncology and immunology patient populations in the United States and Germany are adopting these platforms at rates exceeding prior self-injection categories. This consolidation is compressing site-of-care economics and reallocating margin from hospital pharmacies to ambulatory device ecosystems.
EMA Medical Device Regulation Article 117 requirements now mandate notified body involvement for all drug-device combination products seeking European market authorization. Device sponsors must submit technical documentation alongside pharmaceutical dossiers, eliminating previous self-certification pathways. Wearable injector platforms with proprietary delivery mechanisms face the steepest compliance burden under this framework.
Pharmaceutical sponsors are unbundling device procurement from drug supply agreements, creating direct purchasing relationships between health systems and device manufacturers. Hospital pharmacy directors in the United States now negotiate device specifications independently from formulary committees. This disintermediation is most visible in integrated delivery networks seeking standardized pen injector platforms across multiple therapeutic franchises.
Subcutaneous Drug Delivery Devices Market Segmentation
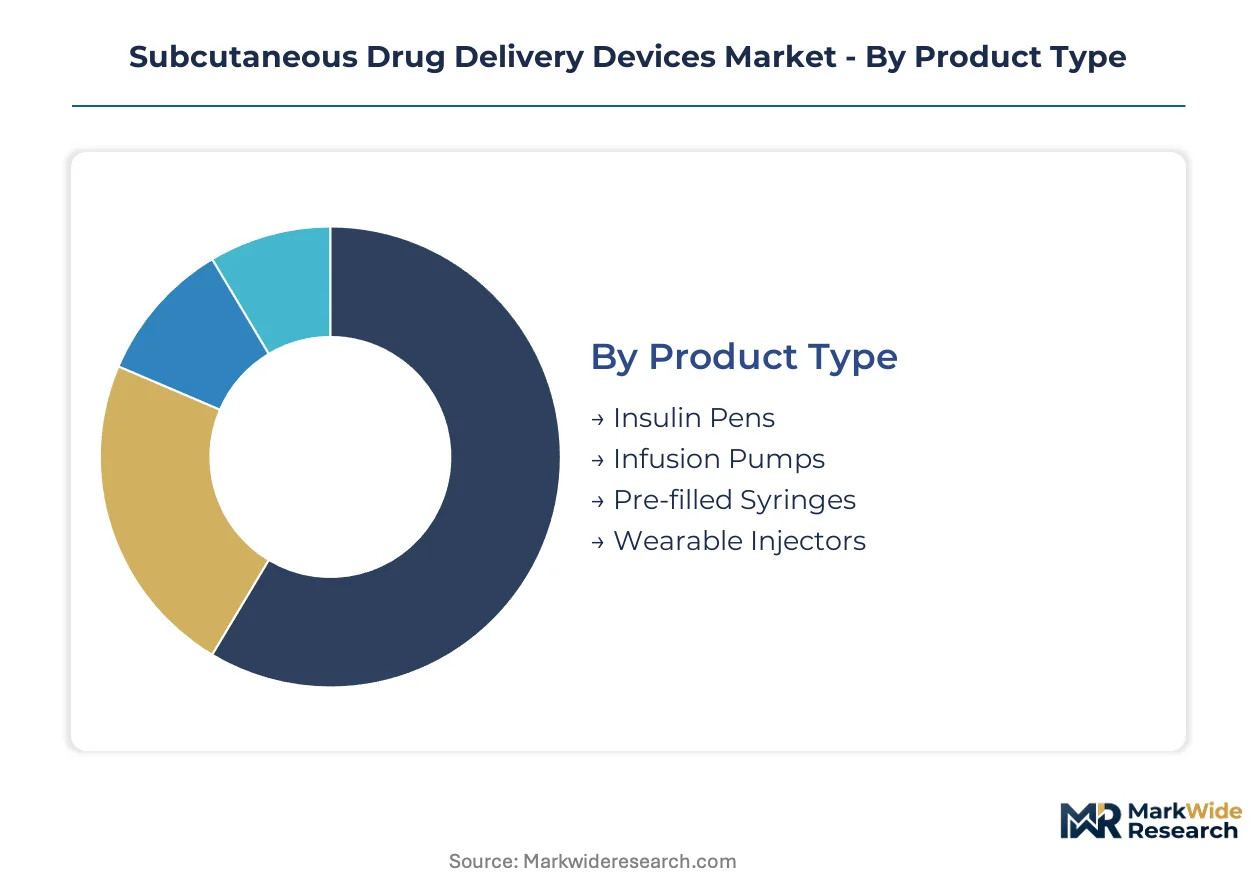
Device segmentation in subcutaneous delivery reveals distinct procurement patterns across patient-managed versus clinician-administered settings. Each category reflects divergent technical requirements, reimbursement pathways, and human factors constraints that shape manufacturer R&D priorities.
Product Type:
Buyers differentiate primarily by therapy duration and injection frequency, with chronic daily regimens demanding ergonomic portability while episodic treatments prioritize dose precision.
- Wearable Injectors:Electromechanical platforms engineered for 2-10 mL biologic volumes integrate Bluetooth connectivity and adherence sensors. Demand concentrates in the United States among oncology and immunology patients transitioning from infusion suites, driven by site-of-care cost compression and payer incentives for home administration.
- Pre-filled Syringes:Glass or polymer barrels with integrated stoppers and plunger rods deliver fixed-dose formulations in 0.5-5 mL ranges. Germany's hospital procurement networks favor these for rheumatoid arthritis biologics, constrained by cyclic olefin copolymer supply concentration from Japanese chemical suppliers.
- Insulin Pens:Reusable or disposable pen injectors with dose-adjustment dials dominate diabetes management protocols across retail pharmacy channels in Japan and the United States.
- Infusion Pumps:Ambulatory electromechanical systems with programmable basal rates serve continuous subcutaneous insulin infusion and pain management indications.
Wearable injectors lead volumes today; pre-filled syringes are gaining share fastest in European outpatient settings.
Technology:
Technology selection hinges on formulation viscosity and required absorption kinetics, with high-concentration monoclonal antibodies demanding advanced delivery mechanisms.
- Patch Pumps:Adhesive-mounted disposable pumps with programmable basal-bolus capabilities and smartphone connectivity command premium positioning. United States diabetes patients adopt these platforms at accelerating rates, propelled by integration with continuous glucose monitoring data streams and remote physician oversight.
- Microneedle Technology:Arrays of sub-millimeter projections penetrating stratum corneum enable painless macromolecule delivery. Japanese cosmetic and vaccine applications drive early commercialization, constrained by manufacturing scale-up challenges for titanium or dissolvable polymer arrays.
- Traditional Syringes:Conventional luer-lock or integrated needle systems remain standard for acute care and immunization programs across hospital networks.
- Electroporation:Pulsed electrical field methods temporarily permeabilize cell membranes to enhance large-molecule uptake, currently limited to research and specialized dermatology applications.
Patch pumps dominate revenue concentration; microneedle platforms show the steepest expansion trajectory in Asia-Pacific cosmetic and vaccine segments.
End User:
End-user economics diverge sharply between reimbursed self-administration and institutional procurement, with home care capturing recurring consumable revenue streams.
- Home Care:Patient-managed settings encompass self-injection training, digital adherence monitoring, and remote clinical support. Germany's statutory health insurance now covers device training and telemedicine follow-up, accelerating biologic therapy decentralization from hospital infusion centers.
- Hospitals:Acute care facilities require needlestick safety engineering and EMR integration for inpatient subcutaneous administration. United States integrated delivery networks negotiate standardized pen injector specifications across therapeutic franchises, disintermediating traditional pharmaceutical supply agreements.
- Specialty Clinics:Outpatient infusion centers and rheumatology practices administer biologics requiring clinical monitoring during initial dosing.
- Retail Pharmacies:Community dispensing channels provide patient education and refill coordination for diabetes and hormone replacement therapies.
Home care leads volumes today; specialty clinics are gaining share fastest as biosimilar competition compresses hospital pharmacy margins.
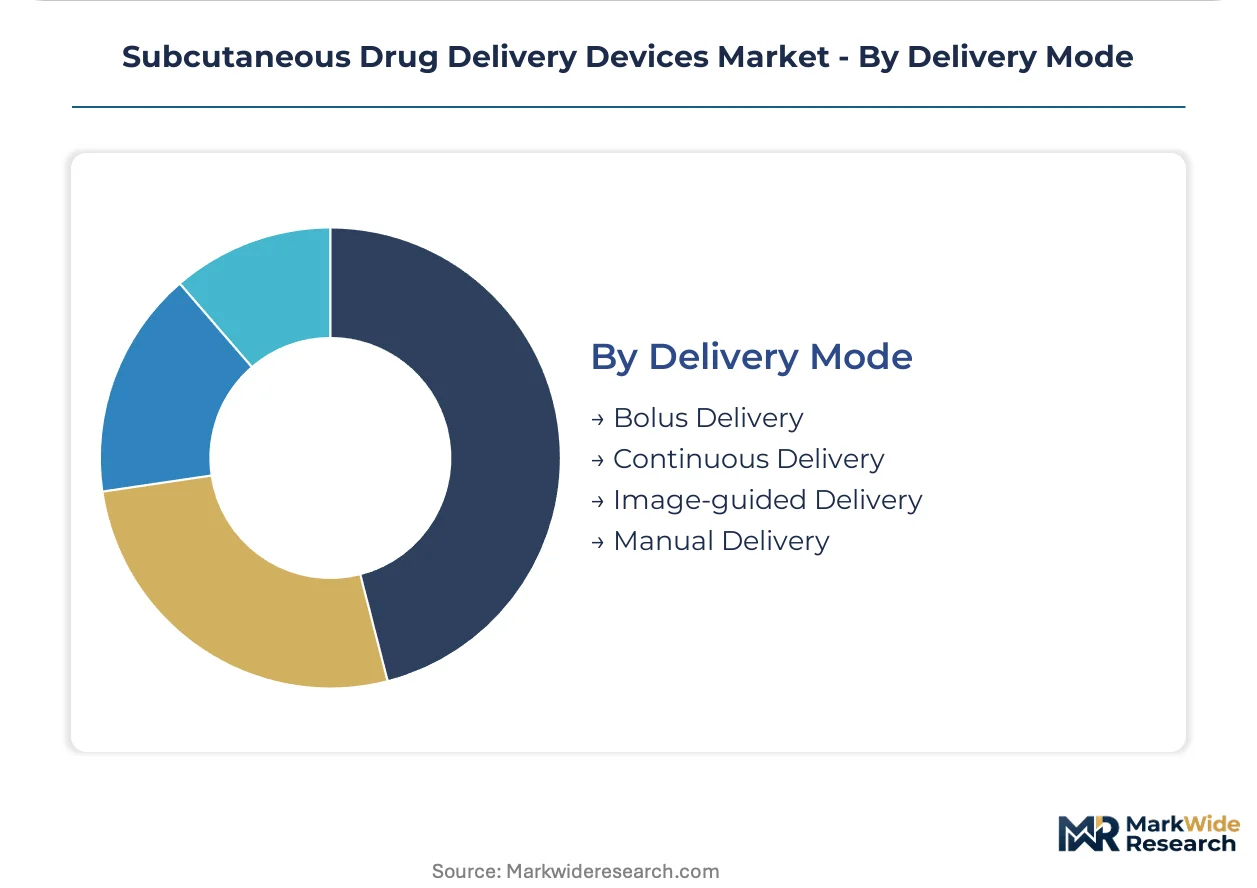
Delivery Mode:
Delivery mode selection reflects pharmacokinetic requirements and patient capability profiles, with programmable systems enabling personalized titration.
- Continuous Delivery:Steady basal infusion with patient-triggered bolus capability mimics physiological hormone secretion patterns. United States type 1 diabetes populations adopt tubeless pump systems integrating with automated insulin dosing algorithms, driven by outcomes-based reimbursement contracts.
- Bolus Delivery:Discrete dose administration on demand suits meal-time insulin, emergency anaphylaxis treatment, and scheduled biologic injections. Japan's aging patient base demands simplified single-button activation with audio-visual confirmation.
- Manual Delivery:Unpowered spring or plunger mechanisms remain prevalent for low-cost immunization and emergency medication kits.
- Image-guided Delivery:Ultrasound or optical feedback systems assist adipose tissue targeting in obese patients or precision anatomical placement.
Bolus delivery leads volumes today; continuous delivery is gaining share fastest among pediatric and adolescent diabetes populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as device sponsors migrate technical documentation and quality system audits toward jurisdictions with faster notified body turnaround and lower compliance overhead. Production clusters in Germany, Switzerland, and the United States retain premium positioning due to FDA and EMA dossier familiarity, while assembly operations disperse to contract manufacturers in Ireland and Singapore seeking MDR transition relief.
United States
Oncology and immunology patient populations drive wearable injector adoption as integrated delivery networks compress site-of-care economics. FDA combination product regulations under 21 CFR 3.2(e) mandate synchronized pharmaceutical and device quality systems, elevating barriers for sponsors lacking established 510(k) or PMA pathways. The Greater Boston corridor anchors human factors engineering talent pools serving elderly and pediatric usability validation studies.
Germany
Statutory health insurance reimbursement for self-administered biologics now covers device training and remote monitoring, accelerating decentralization from hospital infusion centers. EMA Medical Device Regulation Article 117 requirements impose notified body involvement for all drug-device combinations, extending CE marking timelines for Class IIb wearable injectors. The Rhine-Main cluster around Frankfurt concentrates pre-filled syringe barrel molding operations dependent on cyclic olefin copolymer supply.
Japan
Aging demographics and rheumatoid arthritis prevalence outpace infusion center capacity in Osaka and Nagoya metropolitan zones. PMDA Sakigake designation expedites review pathways for innovative drug-device combinations, attracting first-in-class therapy sponsors seeking accelerated market entry. The Kanto region around Tokyo hosts pharmaceutical-device alliance headquarters coordinating regional launch strategies.
Switzerland
Precision manufacturing heritage and dual FDA-EMA dossier capability position Swiss device engineering firms as preferred partners for global biologic launches. Swissmedic medical device regulations align with MDR technical documentation standards, reducing duplicate validation burdens for European market access. The Basel-Zurich corridor concentrates combination product development operations serving both pharmaceutical sponsors and contract manufacturing organizations.
India
Diabetes and autoimmune disease prevalence in tier-2 and tier-3 cities exceeds clinical administration infrastructure, creating demand for patient-managed delivery platforms. CDSCO medical device rules under the Drugs and Cosmetics Act now classify wearable injectors as Class C devices, requiring import license and quality system audits for foreign manufacturers. The Hyderabad-Bangalore corridor hosts contract research organizations executing human factors studies for Western sponsors seeking cost-efficient validation.
Subcutaneous Drug Delivery Devices Market Key Industry Players
Strategic partnerships dominate the current landscape as device manufacturers seek pharmaceutical sponsor alliances to secure volume commitments before committing to dedicated production lines. The vendor base stratifies across three tiers: diversified medical technology conglomerates with full regulatory dossier libraries, mid-cap specialists concentrated in single device categories, and regional contract manufacturers serving emerging market distribution. Two archetypes define competitive positioning: technology licensors monetizing proprietary delivery mechanisms through royalty structures, and vertically integrated fabricators controlling polymer conversion through captive molding operations. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with sponsors unbundling device procurement from drug supply agreements to negotiate directly with health systems.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Medtronic Plc occupy positions anchored by extensive quality management systems and multi-jurisdiction regulatory approvals. Ypsomed AG exemplifies the mid-cap specialist archetype, representing concentrated expertise in automated patch pump platforms. Among diabetes-focused innovators, Insulet Corporation and Novo Nordisk sit within the connectivity-integrated delivery ecosystem, though their strategic positioning diverges across tubeless pump hardware versus pen injector and biologic delivery portfolios.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Ypsomed AG |
| Gerresheimer AG |
| Insulet Corporation |
| Medtronic Plc |
| Novo Nordisk |
| West Pharmaceutical Services, Inc. |
| Owen Mumford |
| Elcam Medical Group |
| Others |
Cost & Logistics Intelligence
Cyclic olefin copolymer resin pricing indices from Japanese and German chemical suppliers cascade through three distinct procurement tiers, with polymer cost volatility compressing margins for pre-filled syringe converters while amplifying pricing power for backward-integrated device manufacturers holding captive molding operations.
Pricing Analysis
Distributor margin layers in European hospital procurement networks absorb 12-18 percent of ex-works device values before reaching formulary committees. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled wearable injectors from basic pen injectors and commodity pre-filled syringes. Cost compression in standard-tier pre-filled syringes is intensifying because biosimilar sponsors negotiate volume-based contract structures. Retail pharmacy channels in Japan exhibit highest price sensitivity, while integrated delivery networks in the United States prioritize interoperability specifications over unit cost.
Supply Chain Analysis
Refurbishment flows for electromechanical wearable injectors remain underdeveloped, with end-of-life devices typically shredded for polymer recovery rather than remanufactured. Manufacturing concentrates in Germany, Switzerland, and the United States for precision molding and final assembly, while polymer resin draws from Japanese and German chemical suppliers. Single-source vulnerability pervades cyclic olefin copolymer barrel production, with two dominant suppliers serving the pre-filled syringe ecosystem. Distribution runs through pharmaceutical wholesaler networks in developed markets and direct-to-hospital contracts in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The subcutaneous drug delivery devices market represents a late-cycle quality story where patient-managed administration specifications now command premium positioning over basic clinical delivery systems.
For Market Incumbents: Hedge against biosimilar-driven commoditization in pre-filled syringes by accelerating proprietary connectivity platform development for wearable injectors. Backward integration into polymer conversion in the Rhine-Main corridor secures supply continuity against Japanese supplier concentration. Reinforce regulatory dossier libraries through preemptive MDR technical documentation investments ahead of notified body capacity constraints. For New Entrants and Emerging Players: PMDA Sakigake designation in Japan opens a window for first-in-class drug-device combination sponsors seeking accelerated review timelines. Target tier-2 and tier-3 Indian cities where diabetes prevalence outpaces clinical infrastructure, deploying simplified bolus-delivery platforms with audio-visual confirmation for aging patient populations. Pursue direct purchasing relationships with United States integrated delivery networks bypassing traditional pharmaceutical supply agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing electromechanical delivery expertise and established FDA 510(k) pathways but limited pharmaceutical sponsor relationships. Long-term viability hinges on recurring software revenue from adherence platforms rather than transactional device sales. Watch for inflection when hospital pharmacy directors unbundle device procurement from drug supply agreements at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth-Enabled Adherence Platform Development | Creates recurring software revenue streams alongside hardware sales for diabetes and immunology applications. |
| MDR Technical Documentation Investment | Secures CE marking pathways for Class IIb wearable injectors under EMA Article 117 requirements. |
| Pharmaceutical Sponsor Alliance Formation | Locks volume commitments before dedicated production line investments for high-volume biologic launches. |
| Human Factors Engineering Talent Acquisition | Addresses FDA usability validation requirements for elderly and pediatric patient populations in Boston corridor. |
| Cyclic Olefin Copolymer Supply Diversification | Reduces single-source dependency on Japanese and German chemical suppliers for pre-filled syringe barrels. |
Research Approach
Multiple input streams — regulatory filing databases, hospital procurement contract records, and polymer supply chain documentation — were reconciled against primary interviews with device engineering executives, regulatory affairs specialists, hospital pharmacy directors, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EMA MDR technical documentation submissions, ISO 11608 standards documentation, and hospital formulary databases. Bottom-up volume modeling across device categories was cross-checked against top-down pharmaceutical sponsor spending allocations.
Historical shipment data was cross-referenced against panel input from procurement managers to establish baseline penetration rates across the projection horizon. Segmentation dimensions modeled include device class, delivery mechanism technology, end-user setting, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curves for comparable therapeutic device categories, incorporating pharmacoeconomic evidence requirements from health technology assessment bodies and reimbursement pathway evolution in Germany and Japan.
Revisions become necessary when notified body capacity constraints extend CE marking timelines beyond sponsor planning assumptions or when polymer supply disruptions alter device manufacturing economics. Forecasts reflect documented assumptions regarding patient self-administration preference shifts and pharmaceutical sponsor pipeline transitions from intravenous to subcutaneous formulations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ehealth Devices Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Hearing Loop Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Transport Chairs Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Neuromodulation Market
Medical Devices
Biliary Catheters Market
Medical Devices
Submucosal Injections Market
Medical Devices
Uterine Fibroid Embolization Devices Market