
 Intrasaccular Embolization Systems Market | 2026-2036
Intrasaccular Embolization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Intrasaccular Embolization Systems Market Foresight
North American manufacturing capacity for nitinol-based delivery catheters is narrowing as domestic suppliers face competition from precision wire-forming specialists in Ireland and Switzerland. Medtronic Plc leverages its integrated neurovascular portfolio to sustain high-volume coil production across multiple continents. Stryker Corporation anchors its position through dedicated R&D facilities focused on next-generation polymer formulations for liquid embolic agents. Penumbra, Inc. differentiates via proprietary aspiration-compatible delivery architectures that compete directly with conventional microcatheter systems.
Intrasaccular embolization systems are implantable or injectable devices designed to achieve complete occlusion of saccular aneurysms through mechanical filling, flow disruption, or endothelial promotion, typically delivered via microcatheter under fluoroscopic guidance with nickel-titanium alloy or platinum-tungsten structural elements. These systems serve the primary commercial purpose of preventing aneurysmal rupture while preserving parent vessel patency in neurointerventional procedures. Coil-based platforms occupy the largest revenue pool due to established reimbursement pathways and broad physician familiarity, though stent-like flow diverters represent the fastest-expanding segment as operators gain proficiency with intrasaccular deployment techniques. Liquid embolic agents command premium pricing in vascular malformation applications where conventional coil packing proves anatomically impractical.
FDA neurovascular device guidance, EU MDR Class III implant requirements, and Japan PMDA orphan device frameworks collectively shape clinical trial design, post-market surveillance obligations, and market access timelines across major jurisdictions. The EU F-Gas Regulation and REACH substance restrictions additionally influence polymer and solvent selection in embolic agent formulations, particularly for European market entry. Stakeholders must monitor evolving real-world evidence requirements from national health technology assessment bodies as payers shift toward outcome-based reimbursement for aneurysm repair procedures.
Market Dynamics
Flow-diverting intrasaccular devices are compressing procedural timelines for wide-neck aneurysm repair, forcing coil manufacturers to defend reimbursement positioning against stent-assisted techniques that promise single-device occlusion.
Growth Catalysts
- FDA breakthrough device designations:Accelerated clinical validation timelines for neuroendovascular implants reduce regulatory friction for novel embolization platforms seeking US market entry.
- German stroke center consolidation:Specialized procurement networks aggregate demand for next-generation embolization systems, creating volume anchors for premium device categories.
- Nitinol wire-forming specialization:Precision metallurgy advances in Ireland and Switzerland expand manufacturing capacity for complex delivery catheter architectures.
Market Restraints
- Platinum-tungsten alloy cost volatility:Raw material price swings for coil windings compress margin structures for high-volume disposable manufacturers.
- EU MDR Class III implant requirements:Enhanced post-market surveillance obligations extend certification timelines and inflate clinical evidence costs for European market access.
- Liquid embolic substitution pressure:Onyx and similar non-coil agents capture vascular malformation cases where dense coil packing proves anatomically impractical.
Strategic Opportunities
- Japan PMDA orphan device frameworks:Expedited review pathways for rare neurovascular indications create first-mover advantages for specialized embolization technologies.
- Polymer-solvent formulation innovation:REACH-compliant solvent systems open European market entry for next-generation liquid embolic agents previously blocked by substance restrictions.
- Aspiration-compatible delivery architectures:Convergence of embolization and thrombectomy workflows enables platform consolidation in integrated neurointerventional suites.
Industry Challenges
- Microcatheter navigation skill scarcity:Operator proficiency gaps in intrasaccular deployment techniques limit adoption velocity for flow-diverting platforms outside tertiary referral centers.
- Real-world evidence collection infrastructure:National health technology assessment bodies demand outcome-based documentation that existing hospital data systems cannot readily generate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrasaccular Embolization Systems Market |
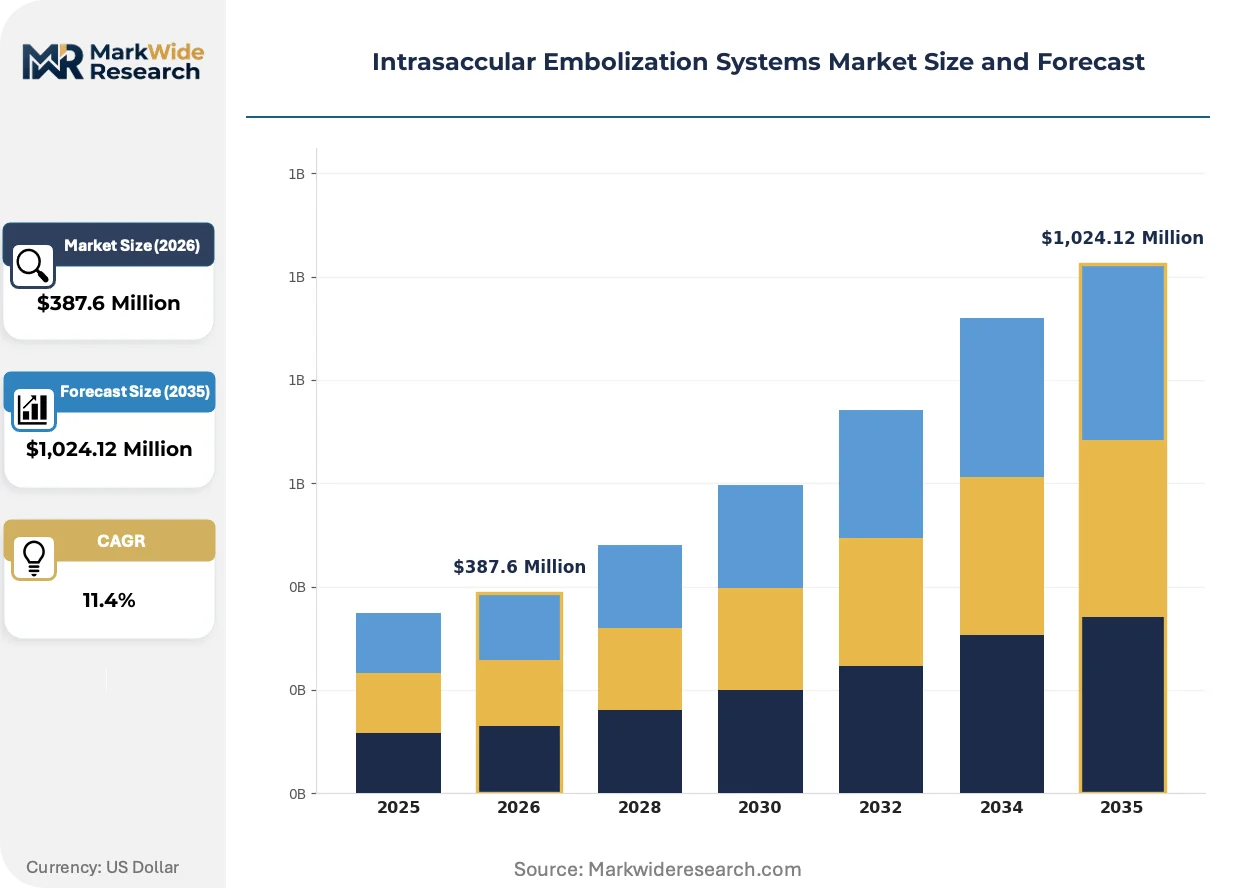
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coils, Liquid Embolic Agents, Stent-like Devices, Delivery Systems Application: Intracranial Aneurysms, Vascular Malformations, Tumor Embolization, Peripheral Vascular Disorders End User: Hospitals, Surgical Centers, Outpatient Clinics, Research Institutions Technology: Fluoroscopy, MRI-guided Interventions, CT-guided Techniques, Robotic Assistance |
| Companies Covered | Medtronic Plc, Stryker Corporation, Penumbra, Inc., MicroVention, Inc., Terumo Corporation, Johnson & Johnson, Cook Medical, B. Braun Melsungen AG, Kaneka Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrasaccular Embolization Systems Market Shifts & Advancements
Device architectures are converging around aspiration-compatibility and single-session completion, compressing the traditional separation between embolization and thrombectomy toolsets.
Next-generation flow diverters are migrating from braided nitinol mesh constructions toward laser-cut closed-cell designs that permit intrasaccular deployment without parent vessel stenting. Neurovascular centers in the United States are adopting these platforms for wide-neck aneurysms previously requiring stent-assisted coiling. The structural consequence is compression of the microcatheter-coil complex toward simpler, lower-cost configurations in anatomically favorable cases.
REACH substance restrictions and the EU F-Gas Regulation are forcing reformulation of liquid embolic solvents and polymer carriers for European market compliance. Manufacturers must substitute legacy dimethyl sulfoxide vehicles with alternative carrier systems that maintain precipitation kinetics. German and Swiss stroke centers are prioritizing devices with pre-validated MDR technical documentation to avoid procurement delays.
Hospital purchasing committees are unbundling device procurement from procedural reimbursement, creating direct price visibility that coil manufacturers previously avoided through bundled payment structures. German hospital networks and US integrated delivery systems now negotiate separate device contracts from physician preference item allowances. This shift is most visible in consolidated stroke center alliances where procurement officers hold veto authority over interventional cardiology and neuroradiology supply selection.
Intrasaccular Embolization Systems Market Segmentation
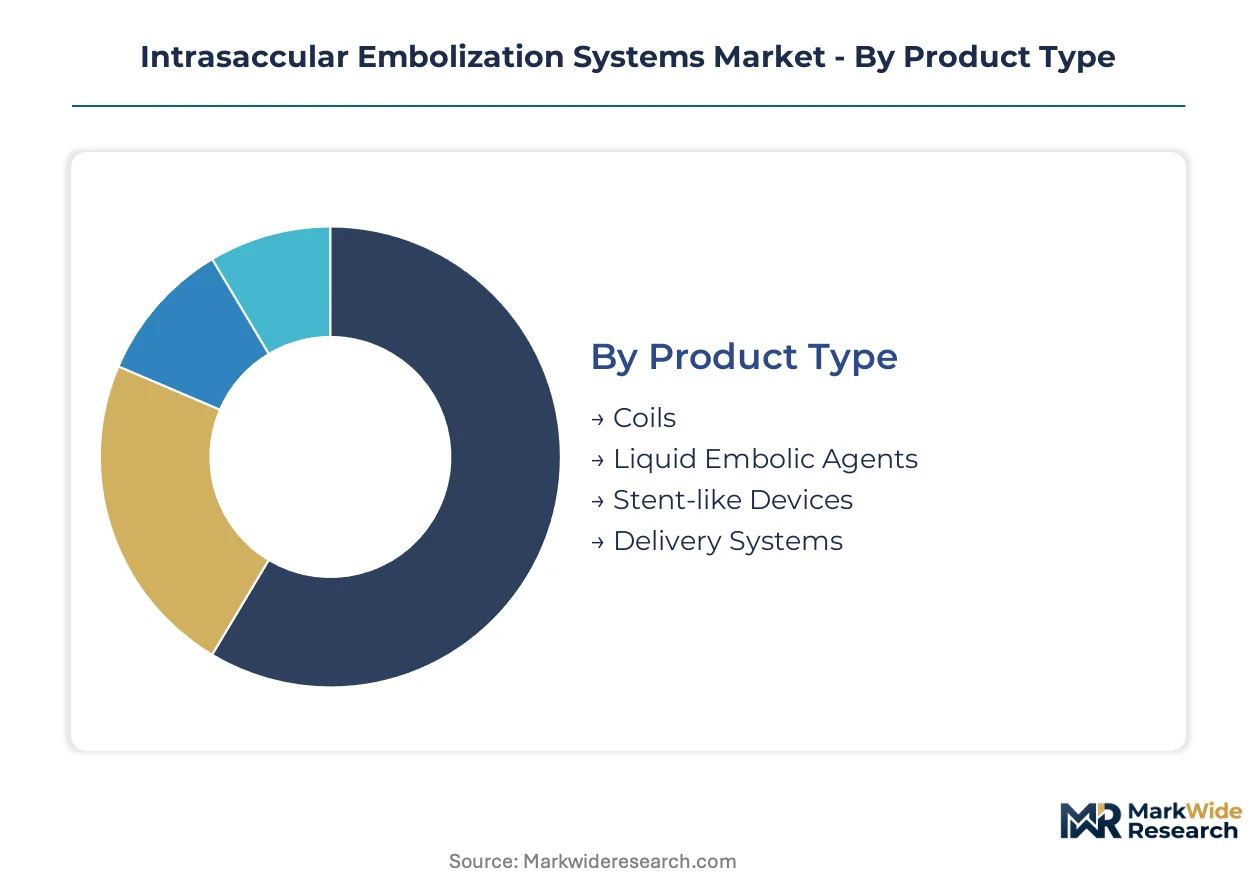
Segmentation in intrasaccular embolization systems reveals distinct procurement patterns across device categories, with coil-based platforms commanding volume leadership while flow-diverting architectures capture premium expansion. Understanding these divides enables manufacturers to align R&D investment with reimbursement trajectories and operator training requirements.
Product Type:
Use cases span mechanical occlusion, flow disruption, and liquid polymerization, each demanding differentiated manufacturing capabilities and clinical evidence packages.
- Coils:Platinum-tungsten alloy windings deliver mechanical filling of aneurysm sacs through detachable deployment mechanisms. German stroke centers and US neurovascular hubs anchor procurement volume for these established platforms, though reimbursement compression from stent-assisted alternatives constrains pricing power.
- Liquid Embolic Agents:Precipitating polymer systems achieve conformal filling in complex vascular geometries where coil packing fails. Demand concentrates in vascular malformation cases across Swiss and Irish specialized centers, driven by anatomical necessity rather than elective substitution.
- Stent-like Devices:Flow-diverting intrasaccular platforms enable single-device occlusion of wide-neck aneurysms.
- Delivery Systems:Microcatheter and guidewire architectures determine procedural success rates.
Established volume favors coils; emerging adoption favors stent-like devices.
Application:
Anatomical targets range from intracranial saccular aneurysms to peripheral vascular territories, each presenting distinct regulatory pathways and outcome documentation requirements.
- Intracranial Aneurysms:Saccular cerebral vessel dilations represent the primary commercial indication with mature reimbursement frameworks. US neurovascular centers and German university hospitals drive procedural volume, with FDA breakthrough designations accelerating access for novel device categories.
- Vascular Malformations:Arteriovenous malformations and fistulas demand conformal embolic agents due to irregular luminal geometries. Swiss neuroradiology departments and Japanese stroke centers prioritize liquid polymer platforms where dense coil packing proves anatomically impractical.
- Tumor Embolization:Preoperative devascularization of hypervascular neoplasms.
- Peripheral Vascular Disorders:Aneurysm repair outside the cerebral circulation.
Reimbursement maturity anchors intracranial aneurysms; technical complexity elevates vascular malformations.
End User:
Procurement authority varies across facility types, from consolidated hospital networks to dispersed outpatient settings with divergent capital equipment requirements.
- Hospitals:Tertiary neurovascular centers with 24/7 interventional capability anchor high-volume coil consumption and complex flow-diverter adoption. German hospital networks and US integrated delivery systems exercise centralized purchasing leverage over device selection.
- Surgical Centers:Focused facilities concentrate on elective aneurysm procedures with streamlined device protocols.
- Outpatient Clinics:Limited to diagnostic workup and post-procedural monitoring rather than interventional deployment.
- Research Institutions:Academic medical centers generate clinical evidence for regulatory submissions and real-world outcome databases.
Procurement scale favors hospitals; evidence generation concentrates in research institutions.
Technology:
Imaging and navigation modalities determine procedural precision, reimbursement coding, and capital equipment requirements across installation sites.
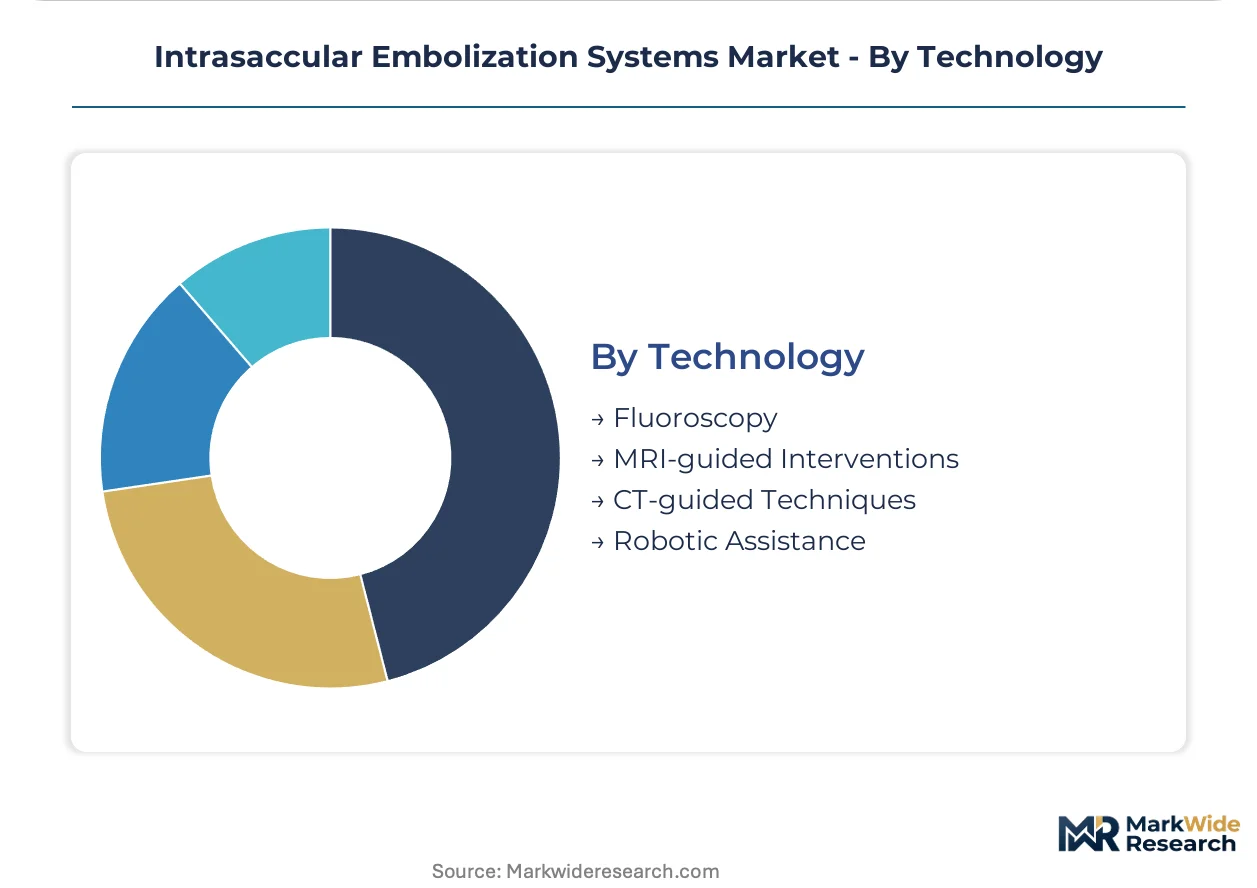
- Fluoroscopy:X-ray guidance remains the dominant intraoperative imaging standard for coil deployment and liquid embolic injection. Every commercial neurovascular suite in the US, Germany, and Switzerland maintains fixed angiography installations with dedicated neurointerventional configurations.
- MRI-guided Interventions:Real-time magnetic resonance visualization enables soft-tissue assessment without ionizing radiation.
- CT-guided Techniques:Computed tomography angiography supports pre-procedural planning and post-treatment surveillance.
- Robotic Assistance:Telemanipulation platforms address microcatheter navigation skill scarcity in tertiary referral networks.
Installed base dominance secures fluoroscopy; capability expansion favors robotic assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations anchor the United States as the dominant regulatory force shaping neuroendovascular market access, while specialized stroke centers in Germany and Switzerland drive European procurement consolidation for next-generation embolization platforms.
United States
Neurovascular centers in Cleveland Clinic, Mayo Clinic, and Johns Hopkins networks expand flow-diverter adoption for wide-neck aneurysm repair. FDA updated guidance for neuroendovascular implants compresses clinical validation timelines. The Greater Boston medical device corridor anchors nitinol delivery catheter R&D and precision wire-forming capabilities.
Germany
Specialized stroke centers in Berlin, Munich, and Hamburg consolidate procurement for coil-based and liquid embolic platforms. EU MDR Class III implant requirements extend certification timelines but create competitive moats for pre-validated technical documentation. The Baden-Württemberg precision engineering cluster supplies complex microcatheter architectures to domestic and export markets.
Switzerland
Swissmedic regulatory frameworks align with EU MDR while offering expedited pathways for orphan neurovascular indications. Zurich and Geneva university hospitals prioritize liquid embolic agents for vascular malformation cases. The Swiss precision metallurgy sector in the Jura Arc supplies nitinol wire-forming capacity for European catheter manufacturers.
Japan
PMDA orphan device frameworks create first-mover advantages for specialized embolization technologies targeting rare cerebral aneurysm morphologies. Tokyo and Osaka stroke centers drive adoption of aspiration-compatible delivery architectures. The Kobe medical device cluster supports localized manufacturing partnerships for global neurovascular suppliers.
United Kingdom
NICE health technology assessment requirements demand outcome-based documentation for aneurysm repair reimbursement. London and Manchester neurointerventional networks evaluate flow-diverting platforms against established stent-assisted coiling protocols. The Cambridge-Oxford medical technology corridor generates clinical evidence for regulatory submissions to EMA and FDA.
Intrasaccular Embolization Systems Market Competitive Landscape
Capability concentration sits with precision metallurgy and polymer formulation specialists; scale advantage sits with diversified medical device conglomerates with integrated neurovascular portfolios. The market structures around three tiers: multinational platform holders with global distribution, regional catheter and coil manufacturers with specialized wire-forming expertise, and niche liquid embolic developers with proprietary solvent systems. Dominant competitive moves include strategic partnerships between device manufacturers and stroke center networks, plus geographic expansion through regulatory-first market entry in Japan and Germany.
Among diversified platform holders, Medtronic Plc and Stryker Corporation exemplify scale-driven neurovascular portfolio integration across multiple continents. Penumbra, Inc. occupies a distinct position within the aspiration-compatible delivery architecture segment. These three anchors represent divergent strategic postures: integrated manufacturing depth versus specialized interventional workflow convergence.
| Leading Market Players |
|---|
| Medtronic Plc |
| Stryker Corporation |
| Penumbra, Inc. |
| MicroVention, Inc. |
| Terumo Corporation |
| Johnson & Johnson |
| Cook Medical |
| B. Braun Melsungen AG |
| Kaneka Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Undercapacity in Swiss nitinol wire-forming facilities is compressing delivery timelines for complex catheter architectures and amplifying pricing leverage among precision metallurgy suppliers serving neurovascular OEMs. This utilization squeeze forces manufacturers to accept longer-term offtake commitments or premium spot pricing, reshaping procurement negotiations across German and US hospital networks.
Pricing Analysis
Geographic price spreads between US neurovascular centers and German stroke networks reflect divergent reimbursement compression trajectories, with European procurement committees extracting steeper discounts through consolidated hospital alliances. Three-tier pricing structure across premium flow-diverters, standard detachable coils, and economy bare-metal platforms segments buyer tiers by procedural complexity and outcome documentation requirements. Pricing pressure stems from liquid embolic substitution in vascular malformation cases where dense coil packing fails anatomically. Academic medical centers and research institutions demonstrate lowest price sensitivity due to grant-funded procurement and evidence-generation mandates, while community hospitals face acute budget constraints under bundled payment structures.
Supply Chain Analysis
Upstream feedstock for platinum-tungsten alloy windings draws from specialized refiners in Germany, Japan, and the United States, with limited secondary sourcing creating vulnerability to commodity price volatility. Nitinol shape-memory alloy feedstock hinges on titanium and nickel supply from Russian and Chinese mining operations, exposing catheter manufacturers to tariff and sanctions risk. REACH-compliant solvent systems for liquid embolic agents face regulatory restriction bottlenecks at European formulation facilities. Distribution runs through GPO-contracted channels in the United States and direct hospital network agreements in Germany, with Swiss stroke centers increasingly adopting consignment inventory models to reduce working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
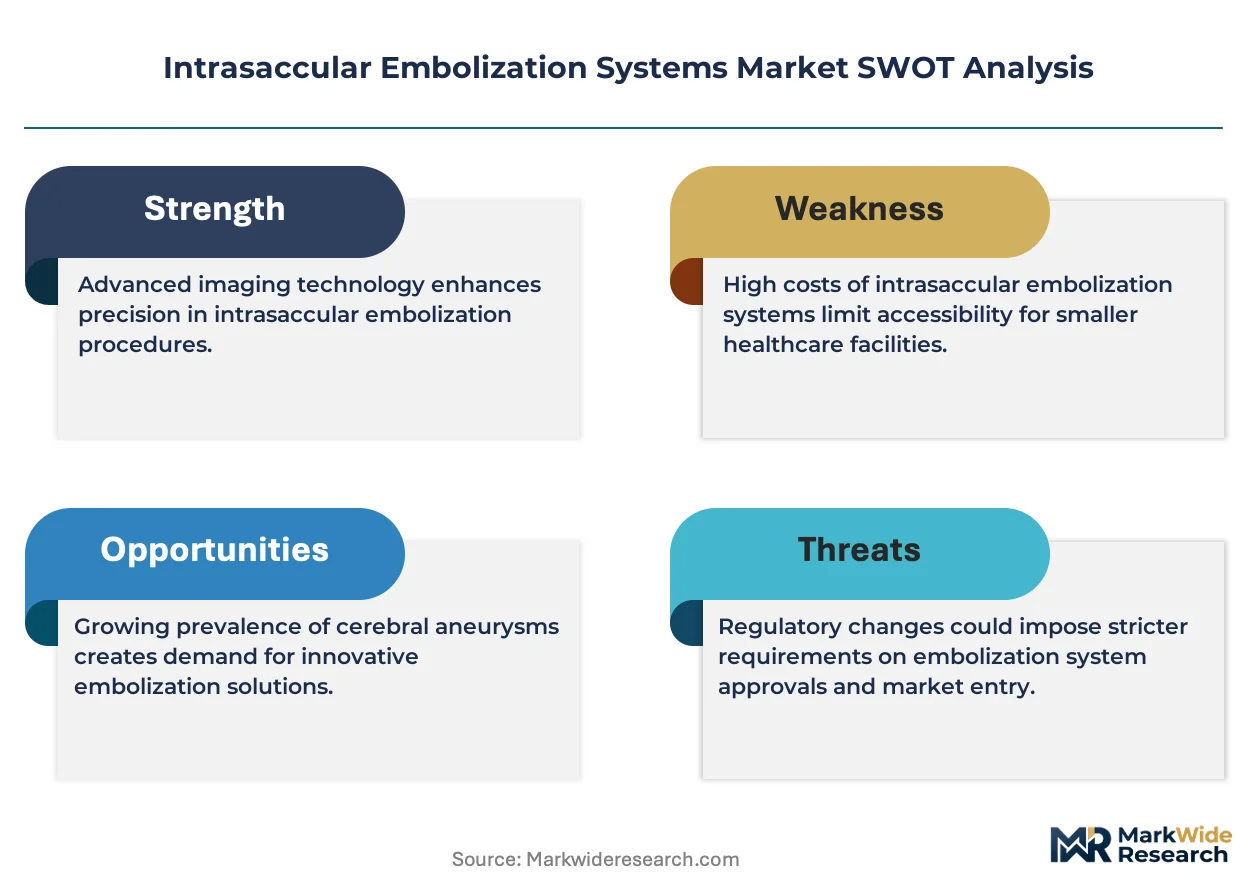
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA breakthrough designations and EU MDR technical documentation requirements create multi-year certification barriers that protect incumbent positions against rapid competitive displacement.
For Market Incumbents: Entrench position through backward integration into nitinol wire-forming capacity in Ireland or Switzerland, securing captive supply of precision delivery catheter architectures against emerging metallurgy specialists. Deepen hospital system partnerships with pre-validated MDR documentation to exploit procurement delays facing competitors. Liquid embolic substitution in vascular malformation cases represents the primary substitution threat requiring defensive formulation investment. For New Entrants and Emerging Players: Aspiration-compatible delivery architectures for integrated neurointerventional suites represent the most penetrable entry point, as workflow convergence creates demand for novel catheter geometries outside established patent thickets. Japanese PMDA orphan device pathways offer expedited regulatory traction for specialized embolization technologies targeting rare cerebral aneurysm morphologies. Go-to-market execution should prioritize academic medical center pilot programs generating peer-reviewed outcome data to support reimbursement negotiations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid embolic formulation facilities due to REACH-compliant solvent substitution requirements and expanded post-market surveillance infrastructure. Five-to-ten year viability favors platform holders with diversified neurovascular portfolios capable of absorbing regulatory compliance cost inflation. Acquisition targets should display pre-validated MDR technical documentation or FDA breakthrough designations. The signal to watch is German hospital network procurement committee consolidation velocity, as centralized purchasing leverage reshapes vendor pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated clinical validation compresses market access timelines for novel flow-diverting platforms. |
| CE Marking Under EU MDR | Enhanced post-market surveillance obligations extend certification timelines but create competitive moats for prepared submitters. |
| Hospital System Partnership | Direct procurement contracts with German stroke center networks secure volume anchors for premium device categories. |
| Software Companion Development | Real-time procedural navigation tools address microcatheter deployment skill scarcity in tertiary referral centers. |
| Reimbursement Strategy | Outcome-based contracting with US integrated delivery systems aligns device pricing with aneurysm repair success metrics. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with neurointerventionalists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up triangulation across product-level shipment data and top-down cross-checks against national health expenditure statistics ensured consistency in volume and value estimates.
Forecast inputs considered procedural volume trajectories across intracranial aneurysm, vascular malformation, and peripheral vascular application segments, with technology adoption curves for flow-diverting versus coil-based platforms modeled separately. Segmentation dimensions included product type, anatomical target, end-user facility tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to historical procedural volumes and projected reimbursement pathway evolution across the analysis window.
Practitioners should monitor FDA guidance document revisions, EU MDR implementing regulation updates, and platinum-tungsten alloy commodity price movements for early signals necessitating forecast adjustment. Cross-checking against national health technology assessment body reimbursement determinations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Micro Syringes Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Posture Correction Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Global Medical Implants Market