
 Spherical Silica Market | 2026-2036
Spherical Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Spherical Silica Market Intelligence
Japanese chemical producers is realigning spherical silica capacity toward sub-micron grades for advanced semiconductor encapsulation. Shin-Etsu Chemical leverages captive polysilicon feedstock to sustain cost discipline across high-purity product lines. Denka Company Limited anchors its position through proprietary flame hydrolysis technology that dominates epoxy molding compound formulations. Sibelco competes via integrated mining-to-refining operations spanning Belgian quartz deposits.
Spherical silica consists of amorphous silicon dioxide particles engineered into near-perfect spherical morphology, typically ranging from 0.5 to 50 micrometers in diameter, produced through flame hydrolysis or sol-gel processes to achieve controlled particle size distribution and exceptional flow characteristics. Electronics applications command premium positioning as flip-chip and system-in-package architectures demand filler materials with coefficient of thermal expansion below 10 ppm per degree Celsius. Precipitated silica occupies mature volume pools in plastics compounding where cost-performance ratios favor established rheology modification. Colloidal silica segments extend into chemical mechanical planarization slurries where particle monodispersity determines wafer surface quality.
EPA National Ambient Air Quality Standards and OSHA respirable crystalline silica limits shape workplace exposure controls and product handling protocols throughout North American manufacturing. REACH registration requirements and EU Green Deal industrial emissions directives enforce full supply chain transparency for silica imports into European electronics and coatings value chains. Stakeholders must monitor evolving IEC material standards for 5G base station substrates and automotive radar modules where dielectric constant stability determines filler selection criteria.
Market Dynamics
Advanced semiconductor packaging architectures are compressing particle size specifications below 500 nanometers while simultaneously tightening thermal expansion tolerances, forcing feedstock and processing investments that favor integrated chemical conglomerates over standalone specialty silica producers.
Growth Catalysts
- Flip-chip underfill formulations:Memory and logic device manufacturers in South Korea and Taiwan specify ultra-low alpha spherical silica to prevent soft errors in high-density interconnects.
- REACH registration tier escalation:ECHA substance volume thresholds above 1000 tonnes annually compel European electronics compounders to document full supply chain purity certificates for imported spherical silica.
- Flame hydrolysis yield improvements:Process intensification through plasma-assisted droplet generation reduces energy consumption per kilogram while maintaining sub-micron monodispersity.
Market Restraints
- High-purity quartz feedstock concentration:Belgian and Norwegian crystalline silica deposits supply over 80 percent of semiconductor-grade spherical silica feedstock, creating geographic concentration risk.
- Fused silica substitution in optical applications:Synthetic fused silica from chemical vapor deposition processes displaces spherical silica in precision lens molding where isotropic thermal properties outweigh cost considerations.
- OSHA respirable crystalline silica enforcement:Workplace exposure limits below 50 micrograms per cubic meter increase personal protective equipment and ventilation capital requirements for North American processing facilities.
Strategic Opportunities
- India electronics manufacturing clusters:PLI scheme incentives for semiconductor packaging and mobile device assembly create virgin demand for epoxy molding compound fillers with localized technical support requirements.
- Automotive radar substrate integration:Millimeter-wave antenna modules operating at 77 gigahertz require dielectric constant stability below 4.0, opening spherical silica formulation work for thermoset laminates.
- 5G base station thermal interface materials:Power amplifier packages in macro cells specify boron-doped spherical silica to manage junction temperatures above 150 degrees Celsius.
Industry Challenges
- Sub-micron particle metrology expertise:Laser diffraction and dynamic light scattering calibration for narrow distributions below 300 nanometers requires specialized analytical chemistry talent scarce outside Japan and Germany.
- Flame hydrolysis reactor scale-up timelines:Construction and commissioning of production lines exceeding 5000 tonnes annual capacity demand 24-36 month capital deployment cycles with uncertain offtake agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spherical Silica Market |
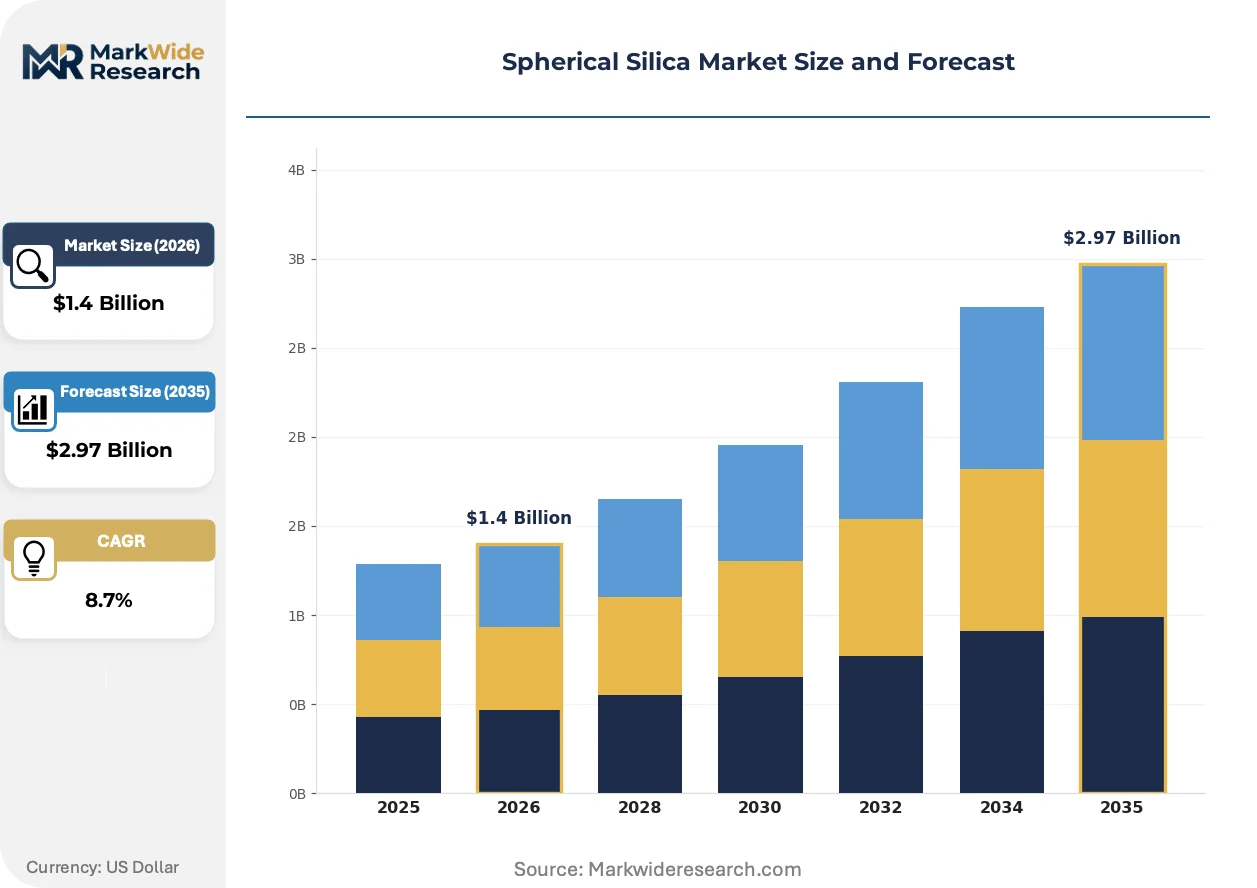
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fumed Silica, Precipitated Silica, Colloidal Silica, Spray Dried Silica Application: Electronics, Plastics, Paints, Coatings End User: Automotive, Consumer Goods, Healthcare, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Sibelco, Shin-Etsu Chemical, Denka Company Limited, Heraeus, AGC Inc., Admatechs Co., Ltd., Tatsumori Co., Ltd., Fuji Silysia Chemical, Micron Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spherical Silica Market Strategic Shifts & Innovations
Process intensification and regulatory disclosure requirements are compressing the viable producer base while opening formulation partnerships between chemical specialists and compounders.
Sol-gel spherical silica synthesis is decentralizing production economics for sub-micron grades. Electronics sealant manufacturers in Germany and the United States adopt continuous flow sol-gel reactors to bypass flame hydrolysis energy intensity. This technology is decentralizing capital requirements away from integrated petrochemical sites toward modular installations near compounder facilities.
EU Green Deal industrial emissions directives tighten monitoring obligations for carbon-intensive silica processes. ETS phase-in for chemical manufacturing above 20 megawatts thermal input forces producers to document Scope 1 and Scope 2 intensities. Belgian and French processing sites face the steepest compliance ramps, accelerating heat recovery and hydrogen combustion pilot programs.
Compounders are consolidating supplier panels to dual-source maximum with audited single-origin certificates. Automotive electronics Tier 1s in Germany and Japan now require quarterly impurity testing documentation with chain-of-custody verification. This consolidation concentrates volume with producers maintaining captive analytical laboratories and regional warehousing networks.
Spherical Silica Market Segmentation
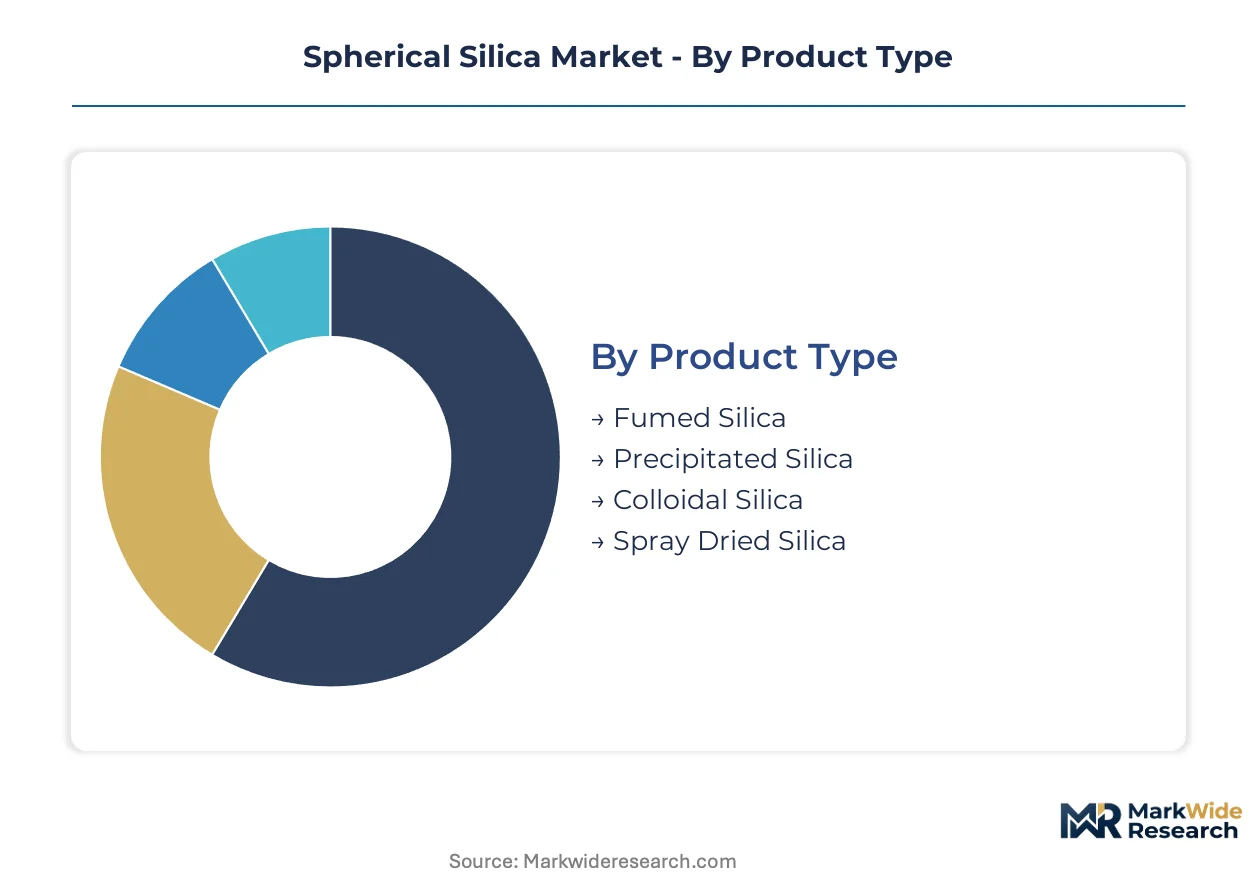
Spherical silica markets fragment across integration depths, from standalone filler materials sold directly to compounders through embedded formulations in pre-mixed epoxy molding compounds. Understanding where value accumulates—raw material, intermediate formulation, or finished encapsulant—determines procurement strategy and margin capture for chemical producers and their customers.
Product Type:
Fumed silica commands standalone premium positioning in high-performance applications, while precipitated and colloidal grades embed deeper into customer supply chains through toll manufacturing arrangements.
- Fumed Silica:Produced through flame hydrolysis of silicon tetrachloride, yielding nanoscale primary particles with surface areas exceeding 200 square meters per gram. Semiconductor packaging manufacturers in South Korea and Taiwan specify this grade for flip-chip underfill where ultra-low alpha emission prevents soft errors in high-density memory interconnects.
- Precipitated Silica:Synthesized via aqueous precipitation from sodium silicate solutions, offering controlled porosity and lower cost structures. Tire manufacturers and rubber compounders in Germany and the United States embed this grade directly into masterbatch formulations, removing standalone purchasing decisions from end users.
- Colloidal Silica:Monodisperse aqueous suspensions serving chemical mechanical planarization slurry producers.
- Spray Dried Silica:Aggregated powders for plastics compounding where flow properties and dust control matter.
Fumed silica leads volumes today; colloidal silica is gaining share fastest.
Application:
Electronics applications concentrate value in specialized formulations, while paints and coatings distribute spherical silica through broader formulation channels with thinner margin structures.
- Electronics:Epoxy molding compounds for semiconductor encapsulation represent the deepest integration point, with spherical silica locked into proprietary formulations by Japanese and South Korean compounders. System-in-package architectures and 2.5D/3D stacking drive specifications below 500 nanometers with coefficient of thermal expansion tolerances tightening to sub-10 ppm per degree Celsius.
- Plastics:Engineering resin compounders in automotive supply chains specify spherical silica for dimensional stability in under-hood components, though procurement typically flows through polymer distributors rather than direct silica sourcing.
- Paints:Matting agents and rheology modifiers where stand-alone purchasing persists.
- Coatings:Anti-corrosion and barrier applications with moderate technical differentiation.
Electronics commands premium pricing; plastics shows steepest expansion trajectory.
End User:
Automotive and healthcare verticals impose the strictest qualification requirements, embedding spherical silica suppliers deep into tiered supply chains with multi-year approval cycles.
- Automotive:Electric vehicle power electronics and advanced driver-assistance systems drive demand for thermally stable encapsulants. German Tier 1 suppliers now require quarterly impurity testing with chain-of-custody verification, compressing the qualified supplier base to producers with captive analytical laboratories.
- Healthcare:Medical device manufacturers specify USP-grade spherical silica for diagnostic consumables and implantable component coatings, with FDA master file submissions creating switching costs that favor incumbent suppliers.
- Consumer Goods:Cosmetics and personal care applications with moderate regulatory barriers.
- Construction:Concrete admixtures and specialty mortars where cost-performance ratios favor precipitated grades.
Automotive leads absolute consumption; healthcare posts the most rapid qualification pipeline expansion.
Distribution Channel:
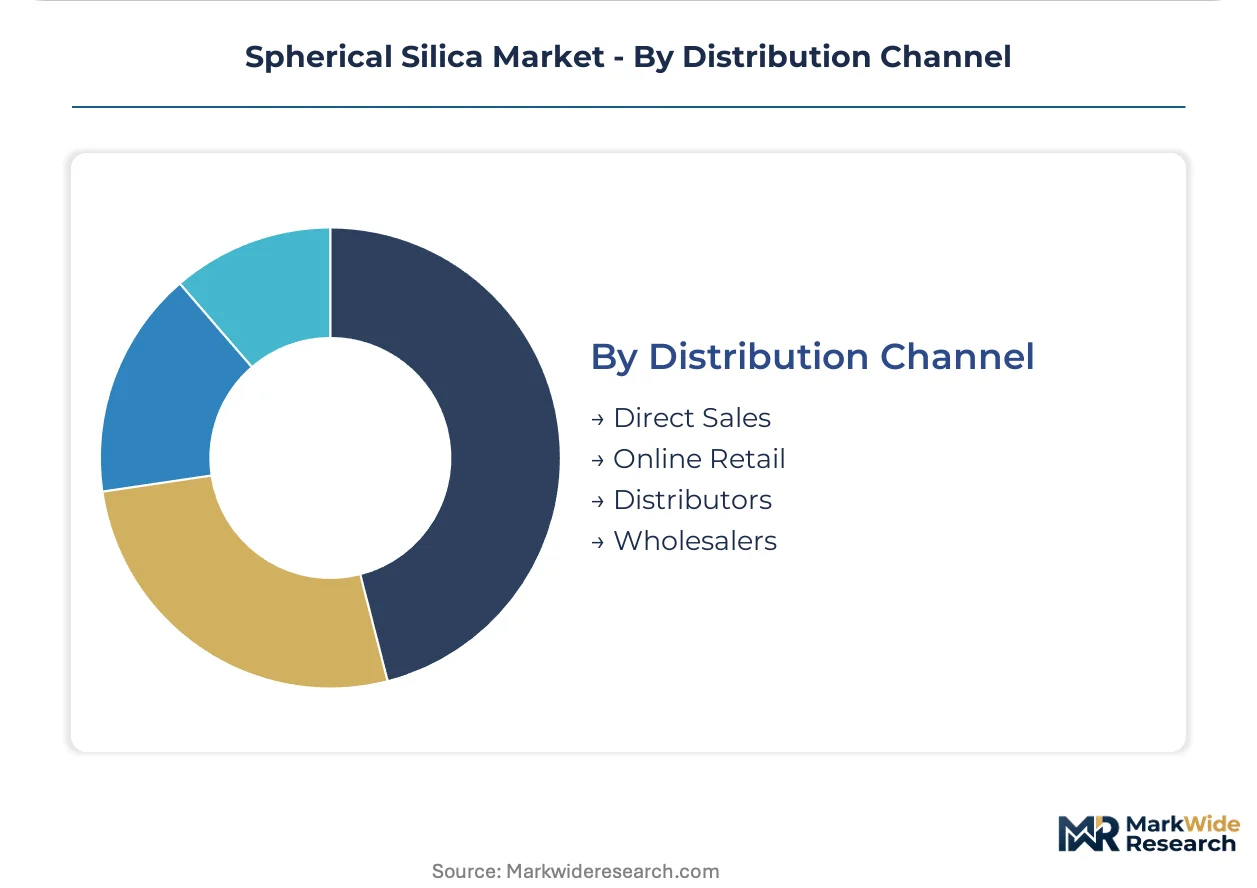
Direct sales dominate high-volume electronics and automotive accounts, while distributor networks fragment reach into smaller compounders and regional formulators.
- Direct Sales:Integrated chemical conglomerates—Shin-Etsu Chemical, Denka Company Limited, Sibelco—maintain dedicated technical service teams co-located with major epoxy molding compound producers in Japan, South Korea, and Taiwan. These relationships span formulation development, joint specification work, and consignment inventory arrangements.
- Distributors:Brenntag and Univar Solutions hold spherical silica inventories for mid-tier plastics compounders and coatings formulators in North America and Europe, absorbing working capital requirements that standalone producers avoid.
- Online Retail:Laboratory and pilot-scale quantities through specialty chemical marketplaces.
- Wholesalers:Bulk commodity grades for construction and industrial applications with limited technical support.
Direct sales capture the majority of value; distributor channels are expanding most quickly into India electronics manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates advanced packaging demand while Belgium dominates high-purity feedstock supply, creating a bifurcated geography where East Asian compounders depend on European quartz deposits.
Japan
Epoxy molding compound producers in Tokyo and Osaka drive sub-micron spherical silica consumption for memory device encapsulation. METI's semiconductor resilience subsidies under the Economic Security Promotion Act channel funding toward domestic filler supply chains. The Kyushu region hosts multiple advanced packaging facilities where flip-chip underfill formulations require ultra-low alpha grades.
South Korea
Memory semiconductor manufacturers in Gyeonggi Province specify spherical silica for high-density interconnect protection. MFDS workplace chemical exposure standards enforce respirable silica monitoring at compounder facilities. The Pyeongtaek cluster anchors national demand through system-in-package production lines serving mobile and server applications.
United States
Automotive radar substrate developers in Michigan and Arizona source thermally stable fillers for 77-gigahertz antenna modules. OSHA respirable crystalline silica enforcement below 50 micrograms per cubic meter elevates capital requirements for processing facilities. The Pacific Northwest hosts specialty chemical distributors serving electronics compounders with quarterly impurity documentation.
Germany
Automotive Tier 1 suppliers in Bavaria and Baden-Württemberg mandate chain-of-custody verification for encapsulant fillers in electric vehicle power electronics. EU Green Deal industrial emissions directives through ETS phase-in compel carbon intensity disclosure for imported spherical silica. The Frankfurt-Rhine-Main logistics corridor warehouses regional inventories for just-in-time delivery to compounders.
India
Electronics manufacturing clusters in Karnataka and Tamil Nadu generate virgin demand for epoxy molding compound fillers under PLI scheme incentives. BIS certification requirements for imported chemicals create qualification timelines that favor suppliers with localized technical support. The Sriperumbudur electronics corridor near Chennai anchors semiconductor packaging investments targeting mobile device assembly.
Spherical Silica Market Key Industry Players
Japanese producers anchor the premium formulation tier; Belgian mining-to-refining specialists hold feedstock security advantages. The market structures around three to five integrated chemical conglomerates controlling flame hydrolysis capacity, with mid-scale sol-gel operators occupying modular niches. Two dominant competitive moves are emerging: captive quartz deposit acquisition for supply security, and joint development agreements with compounders for sub-micron grade qualification.
Within the integrated conglomerate tier, Shin-Etsu Chemical and Denka Company Limited exemplify producers with captive polysilicon or proprietary technology positions. Sibelco represents the mining-integrated archetype leveraging Belgian quartz deposits. Admatechs Co., Ltd. occupies a specialized position among sub-micron grade developers. These company patterns illustrate how feedstock control and process technology differentiation separate viable competitors from marginal participants in qualification-intensive segments.
| Leading Market Players |
|---|
| Sibelco |
| Shin-Etsu Chemical |
| Denka Company Limited |
| Heraeus |
| AGC Inc. |
| Admatechs Co., Ltd. |
| Tatsumori Co., Ltd. |
| Fuji Silysia Chemical |
| Micron Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Captive polysilicon feedstock integration anchors both supply security and pricing power for Japanese chemical conglomerates serving semiconductor packaging markets. This backward control over silicon tetrachloride precursors insulates premium-grade producers from Belgian quartz deposit volatility while sustaining margin structures against sol-gel process competitors.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for sub-micron spherical silica grades. Three-tier pricing structure across premium, standard, and economy levels separates ultra-low alpha semiconductor grades from industrial filler tiers. Price differentiation hinges on particle monodispersity certification and quarterly impurity documentation. Cost compression in standard grades is intensifying because sol-gel modular reactors reduce capital barriers. Plastics compounders show highest price sensitivity; automotive radar substrate developers exhibit lowest.
Supply Chain Analysis
Dual-sourcing mandates from German automotive Tier 1s and Japanese epoxy molding compound producers compel qualification of secondary suppliers across Belgian, Norwegian, and Japanese feedstock streams. Geographic supply concentrates in Belgium, Japan, and South Korea. Raw material dependencies include high-purity crystalline silica deposits, silicon tetrachloride precursors, and hydrogen combustion feedstock. Single-source vulnerability persists for sub-micron metrology calibration standards. Distribution runs through direct technical service teams for electronics accounts and distributor networks for plastics compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between EU ETS carbon-intensive processing sites and India's PLI-subsidized electronics manufacturing clusters, where regulatory cost differentials exceed feedstock logistics premiums.
For Market Incumbents: Acquire captive quartz mining concessions in Norway or Belgium to secure semiconductor-grade feedstock against Sibelco's integrated position. Denka Company Limited's proprietary flame hydrolysis technology demonstrates how process patents defend margin structures against sol-gel entrants. Invest in sub-micron particle metrology laboratories in Germany to meet automotive Tier 1 quarterly documentation requirements. For New Entrants and Emerging Players: Direct-to-compounder digital platforms bypass established distributor markups in India's Karnataka and Tamil Nadu electronics corridors. White-space targets include continuous flow sol-gel reactor installations near epoxy molding compound facilities and boron-doped spherical silica for 5G base station thermal interface materials. Partner with German automotive radar substrate developers for 77-gigahertz qualification pipelines. For Investors and Strategic Acquirers: Consolidation pressure builds where flame hydrolysis reactor scale-up timelines exceed 24-month capital deployment cycles. Long-term viability favors producers with captive analytical laboratories and regional warehousing networks. Target acquisition archetype: mid-scale sol-gel operators with modular reactor technology and localized technical support capabilities. Watch ECHA REACH registration tier escalation above 1000 tonnes as inflection signal for European supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Mining | Belgian and Norwegian deposit control secures semiconductor-grade feedstock purity certificates. |
| Joint Development Agreement with Compounders | Shin-Etsu Chemical's co-location model locks in flip-chip underfill formulation specifications. |
| Sol-Gel Modular Reactor Deployment | Continuous flow installations near compounder facilities bypass flame hydrolysis energy intensity. |
| Automotive Tier 1 Qualification Pipeline | German electric vehicle power electronics demand drives chain-of-custody verification requirements. |
| India PLI Scheme Localization | BIS certification timelines favor suppliers with Chennai and Bangalore technical service presence. |
Research Approach
Multiple input streams — primary interviews with epoxy molding compound procurement leads, flame hydrolysis plant managers, and automotive Tier 1 encapsulant engineers, alongside secondary validation through customs trade data, SEC chemical producer filings, and ECHA REACH registration databases — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from Japanese and South Korean semiconductor packaging clusters. Segmentation dimensions modeled include product grade tier, end-use industry vertical, and regional production hub configuration. CAGRs were derived from installed capacity expansion announcements and compounder offtake agreement disclosures. Forecast inputs incorporated EPA respirable crystalline silica enforcement timelines and EU ETS phase-in schedules for chemical manufacturing.
Feedstock deposit depletion rates, flame hydrolysis yield improvement trajectories, and automotive radar substrate qualification delays are the dominant revision risks. Deviation in REACH registration compliance timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Manufacturing Market
Glass
Silica Sand for Glass Making Market
Glass
Tinted Glass Market
Glass
India Flat Glass Market
Glass
North America Industrial Silica Sand Market
Glass
Borosilicate Glass Market
Glass
Coated Glass Market
Glass
Global Glassware Market
Glass
Latin America Flat Glass Market
Glass
Insulating Glass Market
Glass
Europe Glassware Market
Glass
Asia-Pacific Flat Glass Market
Glass
Insulated Glass Market
Glass
Metallic Glass Market
Glass
Glass Mat Market
Glass
Ultra Violet Glass Bottles Market