
 Borosilicate Glass Market | 2026-2036
Borosilicate Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Borosilicate Glass Market Analysis
European specialty glass producers is repositioning capacity toward pharmaceutical-grade tubing as healthcare supply chains prioritize thermal shock resistance and chemical durability. SCHOTT AG dominates medical packaging tubing through backward integration into melting and forming technology. Gerresheimer AG leverages its vial and syringe manufacturing footprint to anchor demand for high-hydrolytic-resistance borosilicate across European and North American pharma networks. Corning Incorporated competes in laboratory glassware through material science R&D intensity in fused silica and borosilicate hybrids.
Borosilicate glass contains elevated boron oxide content, typically 12-13 percent by weight, which yields a low coefficient of thermal expansion near 3.3 × 10⁻⁶ K⁻¹ and enables direct flame heating without fracture; manufacturers achieve this through isothermal melting in platinum-lined furnaces followed by precision drawing or pressing. Transparent borosilicate leads volume in laboratory equipment and cookware segments where optical clarity and thermal performance command premium positioning, while amber variants capture margin pools in pharmaceutical packaging where UV protection extends drug shelf stability. Tube form factors sustain the fastest growth trajectory, driven by parenteral packaging and LED lighting substrates, whereas sheet formats remain mature in architectural and appliance applications.
EMA medical device regulations and REACH chemical safety frameworks govern borosilicate composition limits and leachable thresholds for European healthcare applications, while FDA Type I glass standards in the United States enforce equivalent hydrolytic resistance benchmarks for injectable drug contact materials. ISO 719 and ISO 720 testing protocols provide international reference methods for hydrolytic class certification, creating harmonized but jurisdictionally enforced barriers to market entry. Stakeholders must monitor evolving pharmacopeial standards for elemental impurity limits and assess captive melting capacity against rising energy costs in specialty glass production.
Market Dynamics
Pharmaceutical packaging manufacturers are consolidating supply relationships around borosilicate tubing producers with captive melting capacity, as thermal shock resistance and hydrolytic stability become non-negotiable specifications for injectable drug containment.
Growth Catalysts
- EMA Medical Device Regulation:The MDR framework mandates enhanced material traceability for Class III devices, pushing pharmaceutical companies toward certified borosilicate suppliers with documented melting and forming records.
- LED substrate expansion:Borosilicate tube formats are capturing substrate demand from semiconductor lighting manufacturers seeking thermal management properties that soda-lime alternatives cannot match.
- German production clustering:Specialized melting and precision drawing capabilities concentrate in Mainz and Düsseldorf corridors, creating localized supply security that attracts pharmaceutical packaging investment.
Market Restraints
- Platinum-lined furnace dependency:Isothermal melting requires platinum-rhodium alloy linings that concentrate equipment supply among precious metal fabricators, exposing producers to rhodium price volatility.
- Energy intensity:Specialty glass melting consumes 3-5 GJ per tonne of finished product, rendering European producers vulnerable to natural gas price fluctuations and carbon border adjustment mechanisms.
- Aluminosilicate competition:High-performance cookware and laboratory equipment segments face substitution from aluminosilicate glass with comparable thermal properties and lower boron oxide requirements.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO's alignment with ICH Q3D elemental impurity guidelines creates certification pathways for European borosilicate suppliers to serve injectable drug manufacturing in Hyderabad and Ahmedabad clusters.
- EU F-Gas Regulation phase-down:Refrigeration equipment manufacturers are evaluating borosilicate sight glasses and pressure vessels as fluorinated gas containment solutions face supply constraints.
- Digital melt control integration:Convergence of platinum thermocouple arrays with machine vision systems enables real-time viscosity management, reducing forming defect rates and expanding addressable precision tubing markets.
Industry Challenges
- ISO 720 hydrolytic certification timelines:Batch testing protocols require 60-day minimum cycles for Class HGA1 classification, constraining speed-to-market for new melting campaigns and recipe adjustments.
- Specialized forming technician scarcity:Precision drawing and Danner process operation depend on tacit knowledge accumulated over 10-15 year careers, with limited vocational training pipelines replenishing the workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borosilicate Glass Market |
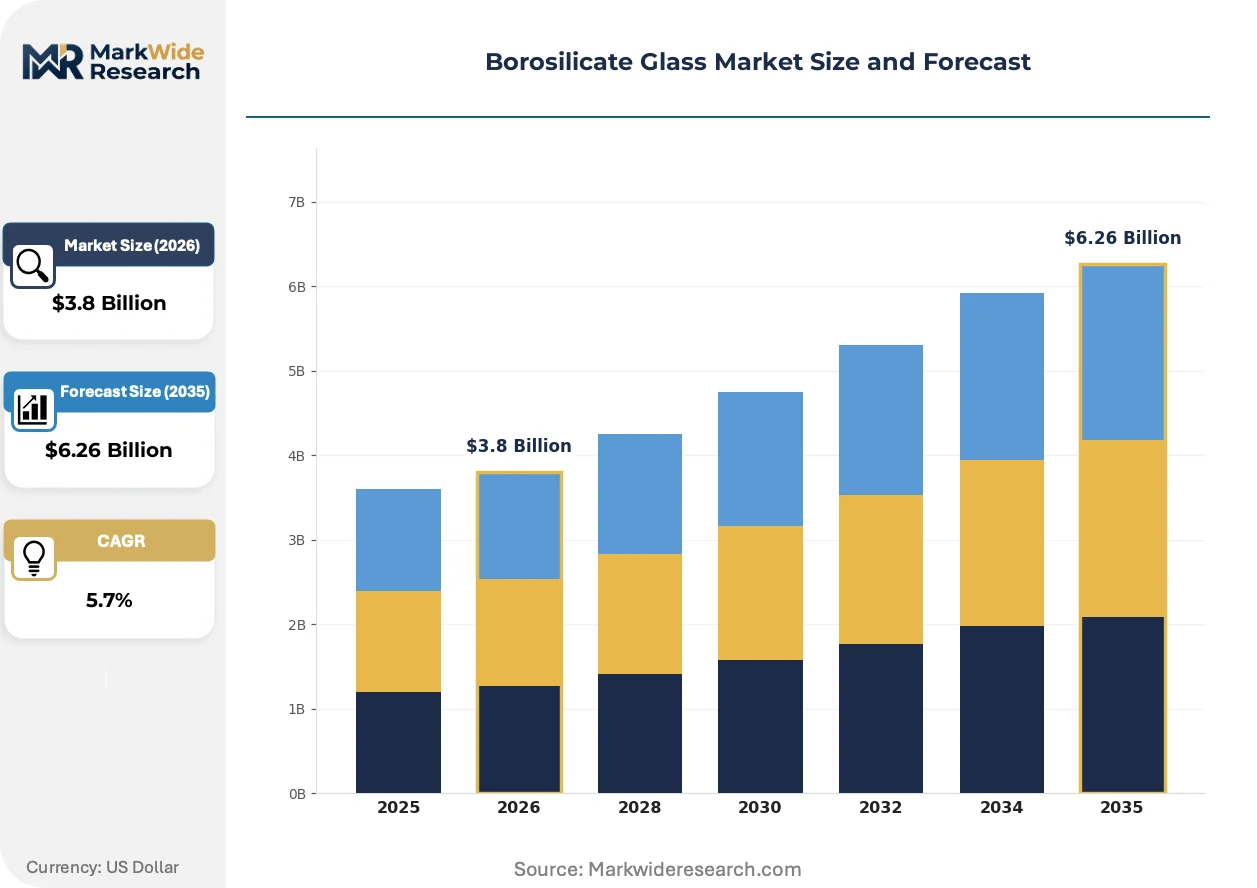
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Amber, Colored, Frosted Application: Laboratory Equipment, Cookware, Pharmaceutical Packaging, Electronics Form: Sheet, Tube, Rod, Custom Shapes End User: Healthcare, Education, Food Service, Research Institutions |
| Companies Covered | Gerresheimer AG, Nippon Electric Glass Co., Ltd., Corning Incorporated, Hilgenberg GmbH, SGD Pharma, SCHOTT AG, Borosil Limited, Kavalierglass, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borosilicate Glass Market Emerging Trajectories
Material science advances and regulatory harmonization efforts are compressing development cycles for pharmaceutical-grade borosilicate while expanding performance boundaries in thermal and optical applications.
Machine vision-assisted forming control is automating defect detection during precision tube drawing, enabling pharmaceutical packaging manufacturers to reduce incoming inspection sampling rates. German and Swiss tubing producers are deploying these systems across multi-furnace operations. Real-time dimensional feedback is automating process parameter adjustments that previously required manual operator intervention.
REACH chemical safety frameworks are tightening boron oxide leachable thresholds for healthcare applications, forcing reformulation of traditional borosilicate compositions. ECHA's 2024 substance evaluation roadmap targets specific migration limits for boron compounds in prolonged drug contact scenarios. Amber borosilicate variants with modified boron-to-alumina ratios are emerging as compliant alternatives for UV-sensitive biologic storage.
Pharmaceutical procurement departments are consolidating tubing supply agreements under single-source qualification models, reversing previous dual-sourcing strategies. Large molecule drug manufacturers in Massachusetts and North Carolina are negotiating direct melting capacity reservations with specialized producers. This concentration pattern is most visible in monoclonal antibody packaging, where batch consistency requirements override price competition considerations.
Borosilicate Glass Market Segmentation
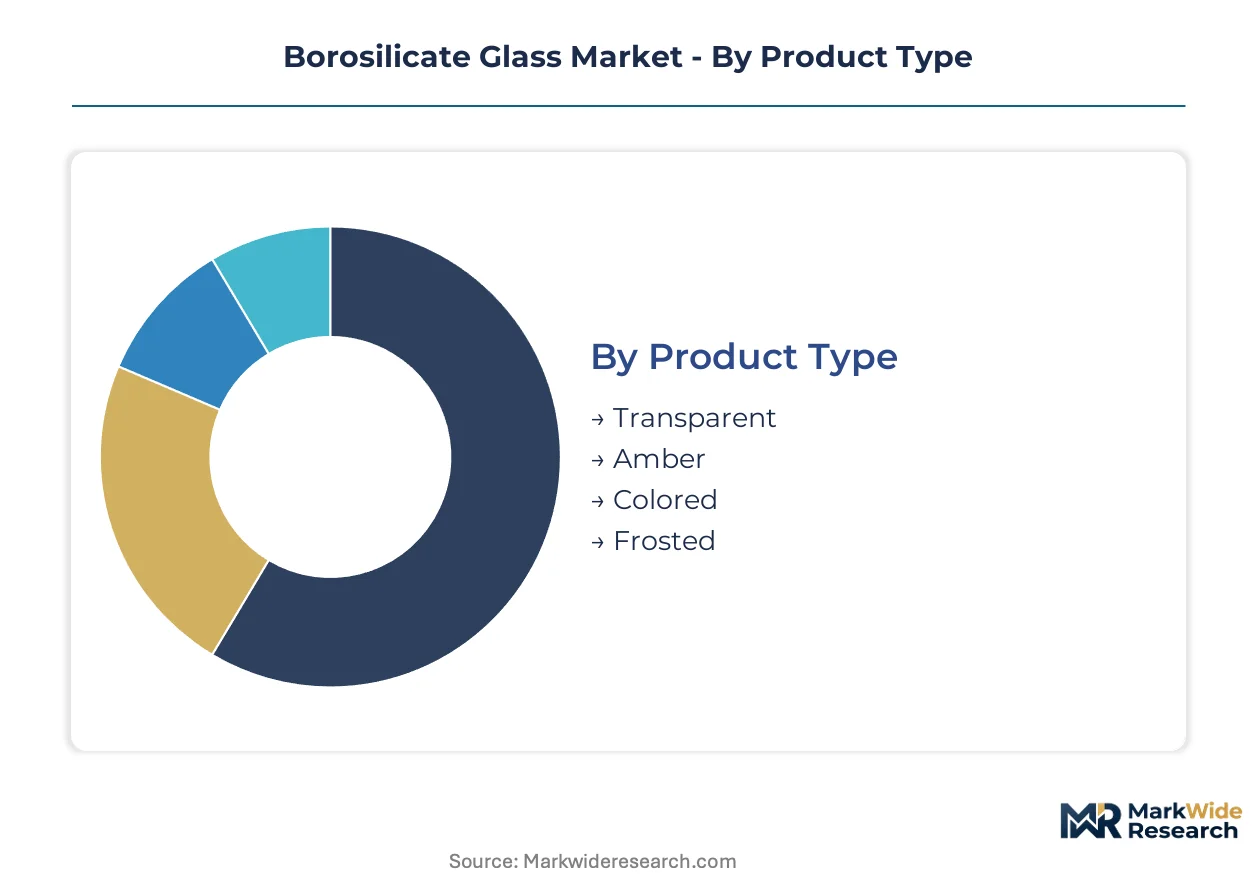
Borosilicate glass markets fragment across technical specifications that determine thermal performance, optical properties, and regulatory compliance. Each segmentation dimension carries distinct margin structures and captive customer relationships that shape supplier strategy.
Product Type:
Upgrade cycles in pharmaceutical packaging and laboratory equipment drive replacement demand toward higher-specification variants with documented hydrolytic resistance certification.
- Transparent:Standard borosilicate contains 12-13 percent boron oxide by weight, achieving thermal expansion coefficients near 3.3 × 10⁻⁶ K⁻¹. Laboratory equipment manufacturers in Germany and Switzerland specify transparent grades for direct flame heating applications where optical clarity enables reaction monitoring.
- Amber:Iron and sulfur doping creates UV absorption below 450 nanometers, extending drug shelf stability for light-sensitive biologics. Pharmaceutical packaging procurement in Massachusetts and North Carolina clusters is consolidating supply agreements around amber tubing with modified boron-to-alumina ratios that meet tightening REACH migration limits.
- Colored:Transition metal oxides produce aesthetic and functional tints for architectural and specialty lighting applications.
- Frosted:Acid-etched or sandblasted surface treatments reduce glare in display cases and decorative cookware.
Transparent sits at the top of the volume ranking, with Amber climbing the fastest.
Application:
Cost tier differentiation separates premium-certified pharmaceutical grades from standard laboratory and consumer segments.
- Laboratory Equipment:Beakers, flasks, and distillation apparatus require thermal shock resistance across repeated autoclave cycles. German producers anchor supply through captive melting and precision forming capabilities concentrated in Mainz.
- Pharmaceutical Packaging:Injectable drug containment demands Type I hydrolytic resistance per FDA standards and equivalent EMA certification. Tubing formats for vials and syringes command price premiums tied to batch consistency documentation and 60-day ISO 720 testing protocols.
- Cookware:Thermal performance positioning competes against aluminosilicate alternatives in high-end consumer segments.
- Electronics:LED substrate and semiconductor applications favor tube formats with precise dimensional tolerances.
Pharmaceutical Packaging captures the steepest margin expansion, with Electronics gaining share fastest.
Form:
Supply concentration in precision drawing capabilities favors tube formats where Danner process expertise limits qualified producer counts.
- Tube:Parenteral packaging and LED lighting substrates drive expansion. Multi-furnace operations in Germany deploy machine vision systems for real-time dimensional control during precision drawing.
- Sheet:Architectural and appliance applications remain mature with limited growth trajectory.
- Rod:Scientific instrument components and specialty lighting applications.
- Custom Shapes:Prototyping and low-volume precision applications requiring specialized mold fabrication.
Tube dominates current output volumes, with Custom Shapes expanding most quickly in prototyping segments.
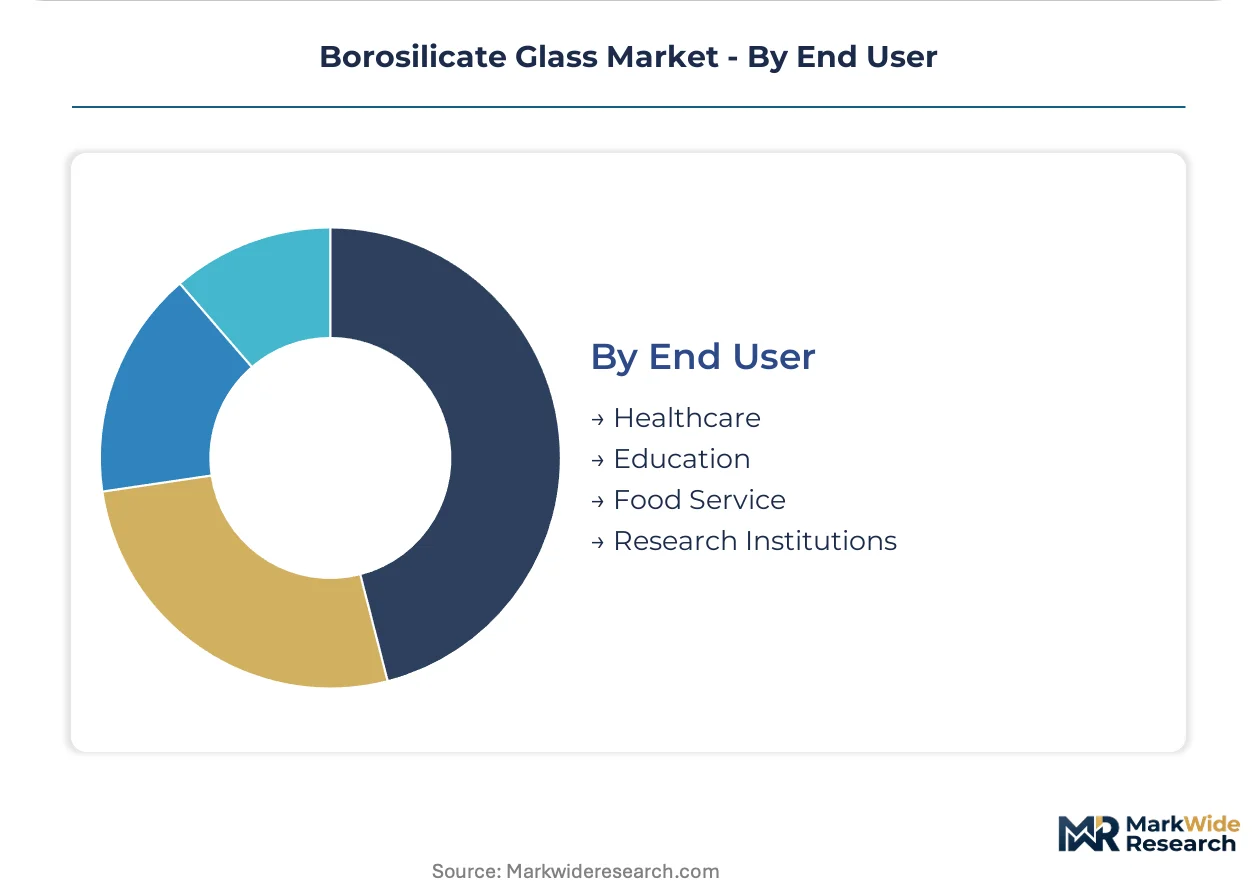
End User:
Customer type determines specification stringency, with healthcare procurement imposing documentation requirements that exclude commodity suppliers.
- Healthcare:Hospitals, clinics, and pharmaceutical manufacturers require complete material traceability for Class III device compliance under EU MDR frameworks. CDSCO alignment with ICH Q3D guidelines in India is opening certification pathways for European suppliers.
- Research Institutions:University and government laboratories balance thermal performance specifications against budget constraints.
- Education:Secondary and undergraduate laboratory programs prioritize durability over optical precision.
- Food Service:Commercial kitchens and hospitality segments evaluate thermal shock resistance against total cost of ownership.
Healthcare commands the specification ceiling, with Research Institutions representing the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as energy costs and compliance stringency diverge across jurisdictions. German producers absorb elevated natural gas expenses within captive melting networks, while Indian fabricators leverage CDSCO harmonization to capture pharmaceutical packaging contracts.
Germany
EMA Medical Device Regulation traceability requirements concentrate pharmaceutical-grade tubing demand around Mainz and Düsseldorf production corridors. The EU F-Gas Regulation phase-down accelerates sight glass substitution in refrigeration equipment. SCHOTT AG and Gerresheimer AG anchor specialized melting clusters that supply European and North American pharma networks with documented hydrolytic resistance certification.
United States
FDA Type I glass standards enforce hydrolytic resistance benchmarks for injectable drug containment, consolidating procurement around certified suppliers. Massachusetts and North Carolina biomanufacturing clusters negotiate direct melting capacity reservations. Corning Incorporated leverages material science R&D intensity in fused silica and borosilicate hybrids to serve laboratory equipment demand.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines opens certification pathways for European borosilicate suppliers. Hyderabad and Ahmedabad pharmaceutical manufacturing clusters expand injectable drug capacity. Borosil Limited anchors domestic production of laboratory and consumer glassware segments.
Japan
PMDA pharmaceutical packaging standards harmonize with FDA and EMA benchmarks, enabling qualified supplier reciprocity. LED substrate manufacturers in Osaka and Nagoya corridors specify borosilicate tube formats for thermal management. Nippon Electric Glass Co., Ltd. represents integrated production capability across electronic and pharmaceutical applications.
Czech Republic
REACH chemical safety frameworks govern boron oxide leachable thresholds for healthcare applications exported to EU markets. Kavalierglass maintains precision drawing operations serving Central European laboratory and lighting equipment manufacturers. The country's position within EU regulatory jurisdiction attracts pharmaceutical packaging investment seeking tariff-free access to German and French distribution networks.
Borosilicate Glass Market Vendor Landscape
German producers anchor the premium pharmaceutical-grade tier; Asian specialists hold volume positions in laboratory and consumer segments. The vendor base concentrates around backward-integrated melting operations with captive platinum-lined furnace capacity. Three archetypes dominate: integrated glass-ceramic conglomerates with multi-furnace networks, precision tubing specialists with Danner process expertise, and regional fabricators serving standardized laboratory ware. Competitive dynamics center on capacity reservation agreements with pharmaceutical manufacturers and machine vision integration for defect reduction.
Among German-based fabricators, SCHOTT AG and Gerresheimer AG exemplify the integrated archetype through captive melting and forming technology control. Corning Incorporated represents the material science-intensive tier with hybrid composition development. These three companies occupy positions that align with the highest specification ceilings in pharmaceutical packaging and advanced laboratory applications.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Nippon Electric Glass Co., Ltd. |
| Corning Incorporated |
| Hilgenberg GmbH |
| SGD Pharma |
| SCHOTT AG |
| Borosil Limited |
| Kavalierglass |
| AGC Inc. |
| Others |
Supply Flow & Price Mechanics
Rhodium price volatility in platinum-rhodium alloy linings feeds directly into pharmaceutical-grade tubing premiums, with German producers passing furnace metal replacement costs through to Massachusetts and North Carolina biomanufacturing clusters under long-term capacity reservation contracts.
Pricing Analysis
Distributor margins compress transparent borosilicate laboratory ware through competitive commoditization, while direct-to-OEM pharmaceutical tubing contracts sustain premium positioning via ISO 720 hydrolytic certification documentation. Three-tier pricing structure across premium, standard, and economy levels separates amber pharmaceutical grades with REACH-compliant boron-to-alumina ratios from standard transparent laboratory equipment and consumer cookware alternatives. Price erosion runs through standard laboratory segments as Indian fabricators expand export capacity. Research institutions exhibit highest price sensitivity, whereas monoclonal antibody manufacturers prioritize batch consistency over unit economics.
Supply Chain Analysis
Dual-sourcing requirements in pharmaceutical procurement are contracting toward single-source qualification models as EMA MDR traceability mandates consolidate supply relationships around German producers with captive melting capacity. Germany, the United States, and India anchor production networks, with Czech Republic precision drawing operations feeding Central European distribution. Boron oxide and platinum-rhodium alloys constitute critical input dependencies. Single-source vulnerability concentrates in platinum-lined furnace fabrication, where precious metal fabricators limit equipment supply. Distribution runs through direct pharmaceutical procurement channels and laboratory equipment distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural gas cost differentials between European melting operations and Asian fabrication hubs create geographic-arbitrage opportunities for producers relocating precision drawing capacity to lower-energy-cost jurisdictions.
For Market Incumbents: Deepen backward integration into boron oxide sourcing to offset REACH reformulation cost pressures, while expanding machine vision-equipped furnace capacity in Mainz and Düsseldorf corridors to defend against aluminosilicate substitution in laboratory equipment segments. For New Entrants and Emerging Players: Direct-to-pharma digital procurement platforms offer white-space entry around ISO 720 certification services and batch documentation automation, targeting Indian CDSCO-aligned manufacturers in Hyderabad seeking European supplier qualification without legacy distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where platinum-lined furnace expertise concentrates among aging technician cohorts with 10-15 year tacit knowledge accumulation. Five-to-ten year viability favors acquisition of precision tubing specialists with Danner process capabilities and existing pharmaceutical customer qualifications. Watch for ECHA boron migration limit enforcement as inflection signal for amber reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Oxide Supply | Captive raw material sourcing insulates German producers from REACH-driven reformulation cost volatility. |
| Machine Vision Furnace Control Deployment | Real-time viscosity management reduces pharmaceutical tubing defect rates below ISO 720 rejection thresholds. |
| CDSCO Certification Pathway Investment | European suppliers accessing Indian pharmaceutical clusters in Hyderabad bypass saturated North American procurement. |
| Amber Composition Reformulation | Modified boron-to-alumina ratios anticipate ECHA migration limits for UV-sensitive biologic storage applications. |
| Platinum Furnace Technician Training Pipeline | Vocational programs replenish Danner process expertise threatened by 10-15 year career accumulation requirements. |
Methodological Framework
Bottom-up pharmaceutical packaging modeling reconciled against top-down specialty glass production tracking forms the analytical core, combining primary interviews with furnace operations managers, pharmaceutical procurement directors, laboratory equipment distributors, and EMA regulatory affairs specialists with secondary validation from FDA Type I glass filings, ECHA substance evaluation roadmaps, SEC 10-K disclosures from listed producers, and German trade association production statistics.
Historical trendline analysis of borosilicate tubing shipments across pharmaceutical, laboratory, electronics, and consumer end-uses establishes baseline growth patterns, with segmentation across product type, application, form factor, and end-user category informing volume and value projections throughout the forecast period. CAGR derivation incorporates platinum price volatility indices, natural gas cost trajectories, and pharmacopeial standard evolution timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for aluminosilicate substitution in thermal shock applications would alter the outlook. Deviation in ECHA boron oxide migration limit enforcement or rhodium supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Low-E Glass Market
Glass
Recycled Glass Aggregates Market
Glass
Glass Mat Market
Glass
Europe Glassware Market
Glass
GCC Flat Glass Market
Glass
Decorative Glass Market
Glass
Cellular Glass Market
Glass
Glass Grade Dolomite Market
Glass
Mirrored Glass Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Optical Materials Market
Glass
Global Vitrification Market
Glass
North America and Australia Silica Market
Glass
Foam Glass Granulate Market
Glass
North America Industrial Silica Sand Market
Glass
Coated Solar Control Glass Market