
 Glass Mat Market | 2026-2036
Glass Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Mat Market Intelligence
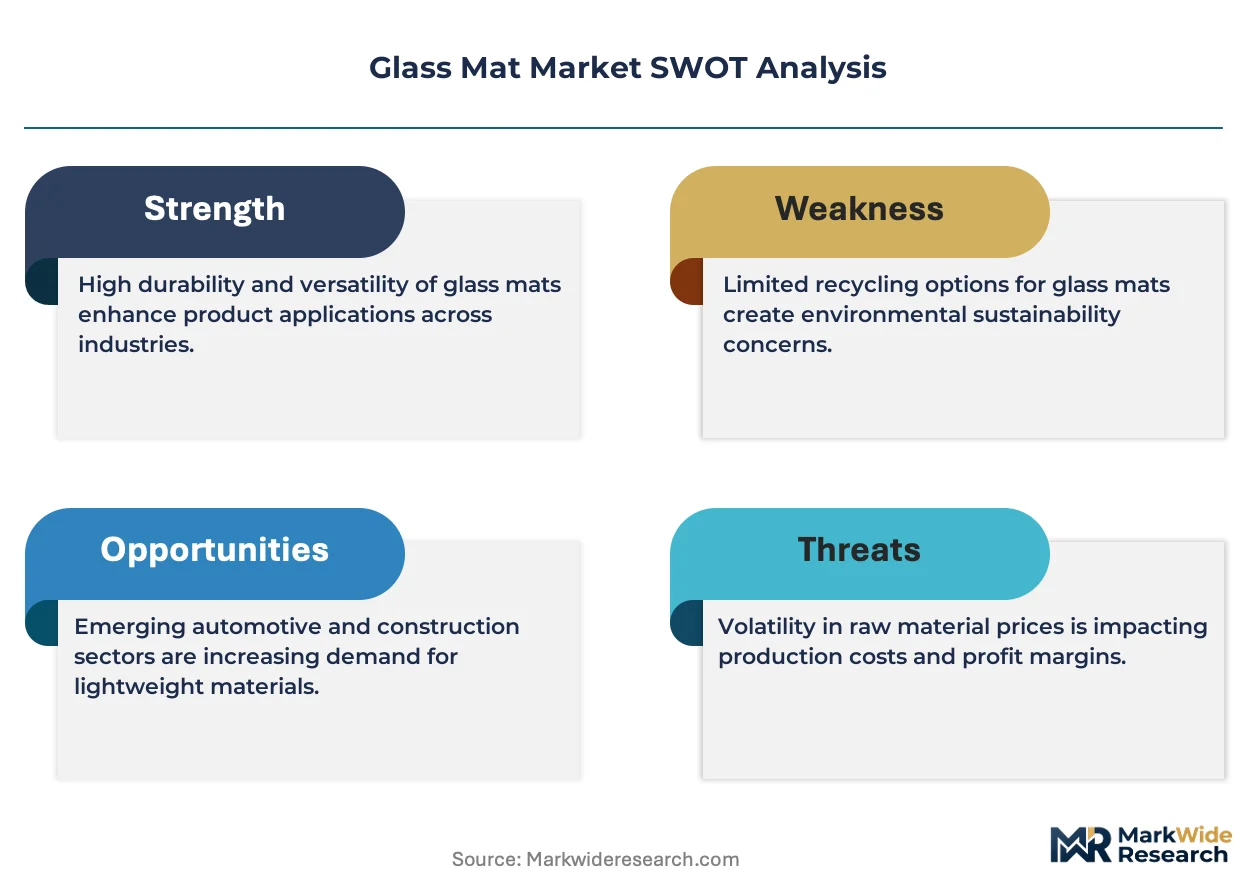
Wind energy blade fabrication is recalibrating its glass mat consumption profiles as longer offshore rotors demand heavier reinforcement schedules. Owens Corning leverages its North American manufacturing scale to supply certified mats directly to blade molders. Taishan Fiberglass anchors its position through backward integration into glass fiber melting and controlled filament diameter consistency. Nippon Electric Glass Co., Ltd. competes on high-modulus formulations that reduce blade weight without sacrificing laminate stiffness.
Glass mat consists of randomly oriented or directionally aligned glass fibers bound into sheet form using powder or emulsion binders, typically weighing 150–900 g/m² depending on structural load requirements. Chopped strand mat dominates volume consumption in hand lay-up and closed-mold processes where rapid resin wet-out and conformability matter most. Continuous strand mat occupies premium positioning in pultrusion and filament winding applications where unidirectional strength retention commands higher pricing. Specialty mats, including surfacing veils and combination fabrics, concentrate margin pools in electrical insulation and corrosion-resistant lining segments where certification barriers limit supplier entry.
China's MEE enforces emissions caps on glass fiber furnace operations under dual carbon targets, while the EU F-Gas Regulation and REACH framework restrict binder chemistries used in European-bound mat production. ISO 9001 and GB/T quality standards shape product acceptance protocols for composite manufacturers qualifying suppliers across multiple geographies. Stakeholders must monitor binder technology transitions and furnace fuel-switching timelines to anticipate which production regions will capture certified supply contracts.
Market Dynamics
Wind turbine blade scaling is the dominant structural force compressing glass mat supply chains as manufacturers race to meet 15+ meter root diameters requiring denser reinforcement schedules and certified supply continuity.
Growth Catalysts
- Offshore wind buildout:Coastal provinces across China are anchoring integrated manufacturing clusters that concentrate mat offtake near blade molding facilities.
- REACH framework compliance:European-bound production lines are upgrading binder chemistries to meet restricted substance protocols, opening certified supply contracts for compliant producers.
- Filament diameter precision:Controlled melting operations are yielding consistent fiber geometry that reduces resin consumption per laminate layer.
Market Restraints
- Natural gas price volatility:Glass fiber furnace operations face input cost swings that compress margin predictability across melting-intensive production.
- Supplier concentration in coastal China:Furnace capacity clusters in Jiangsu and Zhejiang provinces create geographic risk exposure for blade molders requiring just-in-time mat delivery.
- Recycled fiber substitution limits:Mechanical recycling of thermoset composites remains technically constrained, limiting circular feedstock alternatives for cost-sensitive applications.
Strategic Opportunities
- India wind installation targets:The country's renewable capacity auctions are creating localized demand for certified mat supply that currently relies on import channels.
- Hydrogen storage tank filament winding:Pressure vessel manufacturers are specifying continuous strand mat for Type III and IV composite tank reinforcement.
- EU F-Gas Regulation phase-down:Binder formulation transitions are mandating low-emission chemistries that favor suppliers with proven alternative binder platforms.
Industry Challenges
- Composite technician certification gaps:Hand lay-up and closed-mold operations face skilled labor shortages as blade production scales faster than vocational training pipelines.
- Multi-standard qualification timelines:Suppliers must simultaneously maintain ISO 9001, GB/T, and blade-specific certifications that extend customer approval cycles.
- Furnace fuel-switching execution:China's MEE emissions caps are forcing operational transitions from coal-gas to electric or hydrogen-fired melting that disrupt output consistency during retrofit periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Mat Market |
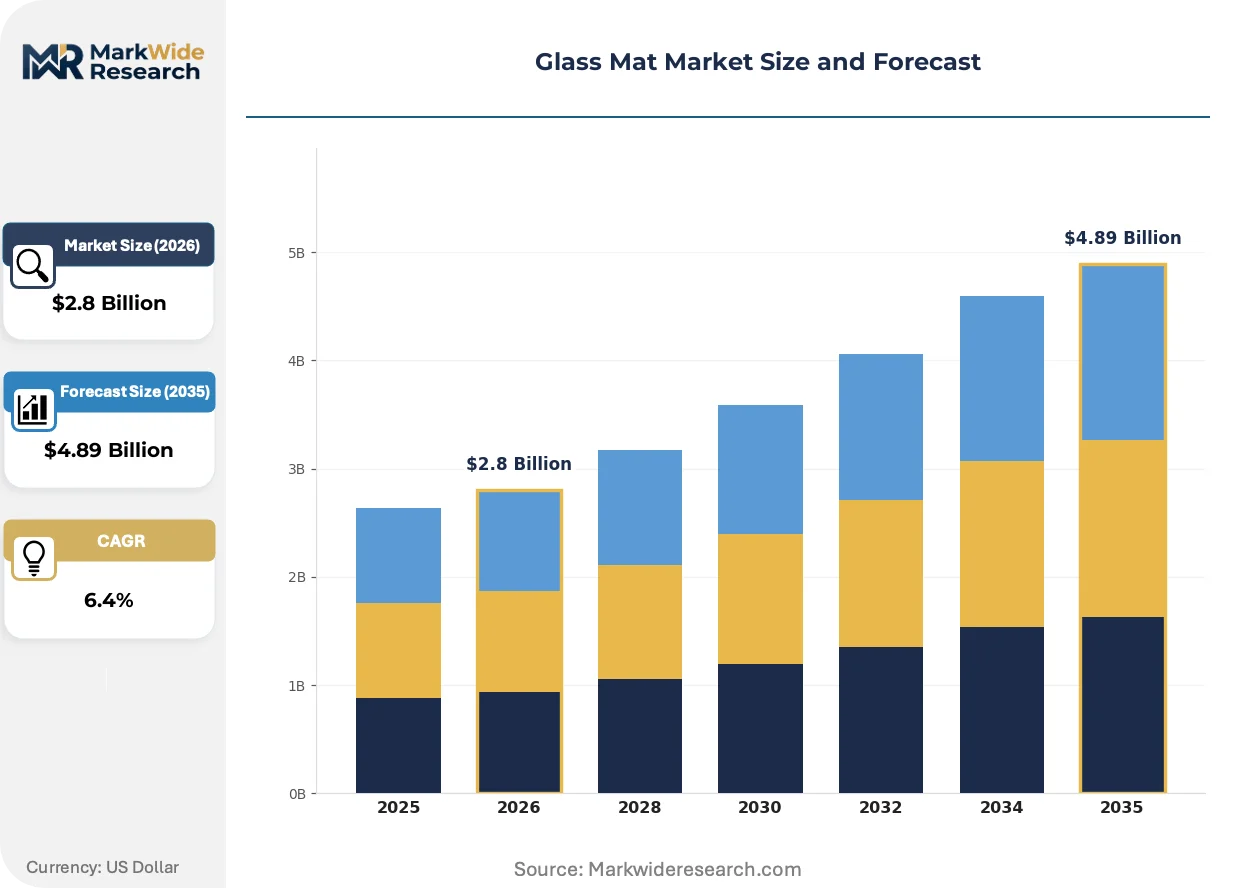
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped Strand Mat, Continuous Strand Mat, Woven Roving, Specialty Mats Application: Construction, Marine, Wind Energy, Electrical Insulation, Filtration End User Industry: Composite Manufacturers, Electronics Producers, Renewable Energy Firms, Transportation Equipment Makers Manufacturing Stage: Glass Fiber Production, Mat Formation, Surface Treatment, Quality Inspection |
| Companies Covered | 3B Fiberglass, Nippon Electric Glass Co., Ltd., Owens Corning, Taishan Fiberglass, China Beihai Fiberglass Co., Ltd., China Jushi Co., Ltd., Johns Manville, Saint-Gobain, Chongqing Polycomp International Corporation (CPIC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Mat Market Strategic Shifts & Innovations
Glass mat manufacturing is undergoing binder chemistry and furnace technology transitions that are compressing legacy process windows while opening certified supply positions for early movers.
Tailored powder binder systems are rewriting resin wet-out performance standards by enabling faster impregnation in thick laminate stacks without compromising drape conformability. Offshore blade molders in northern Europe are specifying these formulations for 100+ meter rotor segments where infusion cycle time directly determines mold utilization rates. The technology is rewriting competitive positioning among mat suppliers by separating certified low-emission binder platforms from conventional emulsion-bound alternatives.
China's GB standards for composite reinforcement are tightening filament diameter tolerance requirements under MIIT industrial upgrading directives. Domestic furnace operators are retrofitting bushing designs and automated winding controls to meet the updated specifications. Chopped strand mat destined for electrical insulation and corrosion-resistant applications faces the most stringent compliance verification, with batch testing protocols extending quality documentation requirements.
Direct mill relationships are displacing distributor intermediaries as blade manufacturers consolidate supplier panels and negotiate multi-year offtake agreements. Tier-one wind OEMs in Denmark and Germany are establishing captive inventory positions at molding facilities to buffer against supply volatility. This concentration is most visible in the North Sea offshore corridor where project finance timelines demand guaranteed mat availability across 18-month blade production cycles.
Glass Mat Market Segmentation
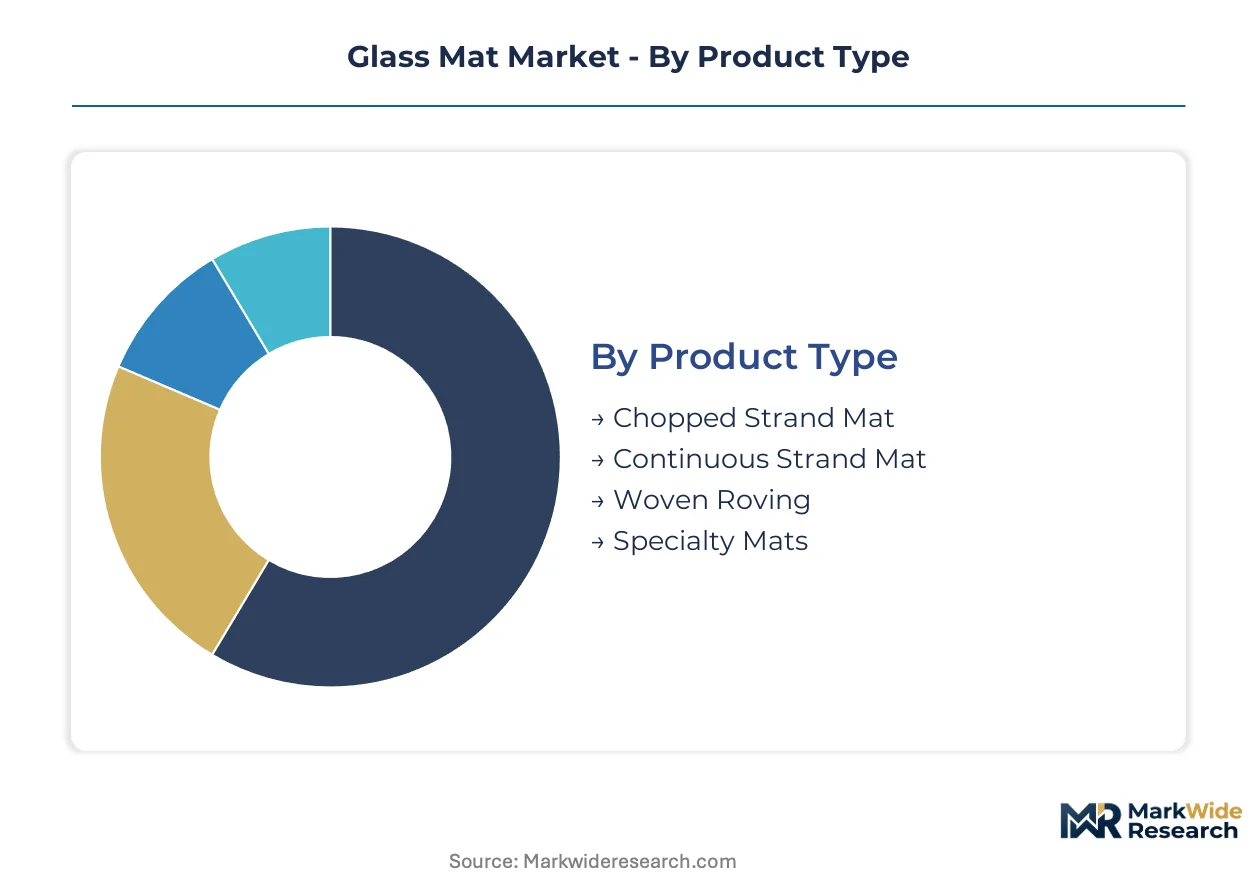
Glass mat segmentation tracks how fiber architecture, end-use performance requirements, and manufacturing precision interact to determine supplier selection and pricing power. Understanding these category boundaries reveals where certification barriers concentrate margin pools and where commodity competition erodes returns.
Product Type:
Technical specifications around fiber orientation, binder chemistry, and areal weight define competitive positioning across mat architectures.
- Chopped Strand Mat:Randomly oriented glass fibers bound with powder or emulsion binders, typically 300–600 g/m², dominate hand lay-up and closed-mold processes. Demand concentrates in wind turbine blade root sections and marine hull fabrication across Jiangsu and Zhejiang provinces, where rapid resin wet-out determines mold cycle economics.
- Continuous Strand Mat:Unidirectional or multidirectional continuous filaments deliver superior tensile retention for pultrusion and filament winding. Offshore wind blade manufacturers in northern Europe specify these formulations for 100+ meter rotors, paying premium pricing for certified low-emission binder platforms that comply with ECHA REACH protocols.
- Woven Roving:Bidirectional or multiaxial woven constructions provide structural reinforcement in high-load laminates.
- Specialty Mats:Surfacing veils, combination fabrics, and corrosion-resistant grades serve electrical insulation and chemical lining applications where GB/T and ISO certification barriers limit supplier entry.
Chopped strand mat leads on scale; continuous strand mat leads on momentum.
Application:
End-use performance thresholds separate specification-driven procurement from price-sensitive volume buying.
- Wind Energy:Rotor blade manufacturing consumes the heaviest reinforcement schedules as root diameters exceed 15 meters. Coastal manufacturing clusters in China and North Sea corridor molders drive certified mat offtake under multi-year supply agreements.
- Construction:GFRP panels, roofing membranes, and infrastructure rehabilitation create steady demand for standard-grade chopped strand mat. Building code adoption of composite reinforcement varies by province and municipality, fragmenting procurement specifications.
- Marine:Boat hulls and deck structures require conformable mats for complex curvature molding.
- Electrical Insulation:Transformer boards, motor slot liners, and printed circuit substrates demand tightly controlled filament diameter and dielectric consistency.
- Filtration:Air and liquid filter media use fine-diameter glass fiber veils with specialized surface treatments.
Wind energy commands the steepest expansion trajectory; construction maintains the broadest geographic footprint.
End User Industry:
Customer technical capabilities and certification requirements shape supplier relationship structures and contract terms.
- Composite Manufacturers:Tier-one wind blade molders and boat builders consolidate supplier panels, negotiating direct mill relationships that displace distributor intermediaries. These buyers specify binder chemistry, filament diameter tolerance, and batch traceability documentation.
- Renewable Energy Firms:Wind and hydrogen storage project developers impose supply continuity guarantees across 18-month production cycles, favoring producers with captive furnace capacity and backward integration into glass fiber melting.
- Electronics Producers:PCB and insulation material fabricators require GB/T and ISO 9001 compliance verification with extended quality documentation.
- Transportation Equipment Makers:Rail, automotive, and aerospace composite fabricators specify high-modulus formulations for weight-critical structural components.
Composite manufacturers lead on procurement sophistication; renewable energy firms lead on contract duration.
Manufacturing Stage:
Process control points determine output consistency, emissions compliance, and cost structure across the value chain.
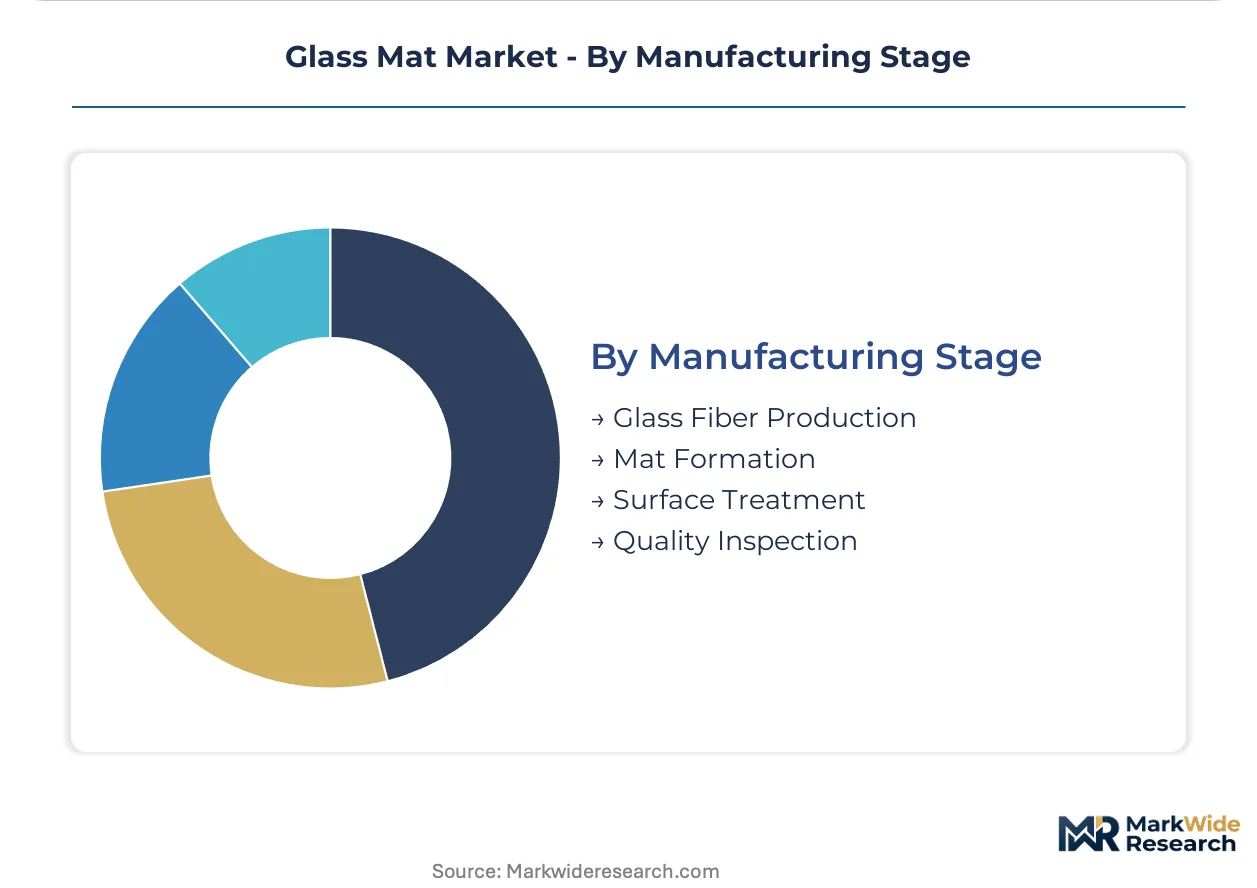
- Glass Fiber Production:Furnace melting operations face China's MEE emissions caps under dual carbon targets, forcing fuel-switching from coal-gas to electric or hydrogen-fired systems. Filament diameter precision at the bushing stage propagates through downstream quality.
- Mat Formation:Chopping, dispersing, and binding operations convert continuous filaments into sheet form. Powder binder systems are displacing emulsion alternatives for faster resin wet-out in thick laminate stacks.
- Surface Treatment:Sizing chemistry and coating applications tailor fiber-matrix adhesion for specific resin systems.
- Quality Inspection:Automated vision systems and mechanical testing protocols verify areal weight, tensile strength, and binder distribution against GB standards and customer specifications.
Glass fiber production leads on capital intensity; mat formation leads on technology transition activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration tracks diverging compliance costs across furnace operations, with manufacturers arbitraging emissions caps and energy pricing differentials to secure certified supply positions.
China
Wind turbine blade manufacturing concentrates in Jiangsu and Zhejiang provinces where integrated clusters link furnace capacity directly to molders. The MEE enforces dual carbon emissions caps on glass fiber melting operations, forcing fuel-switching retrofits from coal-gas to electric or hydrogen-fired systems. Taishan Fiberglass anchors backward integration into controlled filament diameter production in Shandong province.
Germany
Offshore wind OEMs in northern Germany specify continuous strand mat for 100+ meter rotors under REACH-compliant binder protocols. The ECHA framework restricts substance chemistries in European-bound production, extending supplier qualification timelines. Blade molders along the North Sea corridor negotiate multi-year offtake agreements with captive inventory positions.
United States
North American blade fabricators source certified mats for utility-scale wind installations across the Great Plains and Texas wind corridors. The EPA regulates air emissions from glass melting furnaces while state-level renewable portfolio standards drive procurement volumes. Owens Corning leverages domestic manufacturing scale to supply direct mill relationships.
India
Renewable capacity auctions are creating localized demand for glass mat supply currently dependent on import channels. The MNRE wind installation targets face supply chain gaps as domestic furnace capacity lags blade molding expansion. Gujarat and Tamil Nadu are anchoring coastal manufacturing clusters for rotor component fabrication.
Japan
High-modulus glass fiber formulations serve precision electrical insulation and advanced composite applications under METI industrial upgrading directives. The PMDA and JIS standards shape quality verification protocols for dielectric consistency. Nippon Electric Glass Co., Ltd. competes on filament diameter precision for weight-critical laminates.
Glass Mat Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with furnace-integrated producers commanding premium positioning in certified wind energy supply chains while regional converters serve price-sensitive construction applications. The vendor base organizes around three strategic archetypes: backward-integrated glass fiber melters with captive mat formation, independent converters sourcing filament from merchant markets, and specialty formulators targeting electrical insulation and corrosion-resistant niches. Capacity expansion and binder chemistry transitions represent the dominant competitive moves, as producers retrofit operations to meet low-emission regulatory mandates.
Among furnace-integrated specialists, Owens Corning, Taishan Fiberglass, and Nippon Electric Glass Co., Ltd. occupy positions defined by geographic manufacturing scale and certification depth. Owens Corning represents North American supply continuity for blade molders requiring multi-year contract structures. Taishan Fiberglass anchors Chinese production gravity through in-house melting and controlled filament operations. Nippon Electric Glass Co., Ltd. exemplifies high-modulus formulation specialization for premium composite applications.
| Leading Market Players |
|---|
| 3B Fiberglass |
| Nippon Electric Glass Co., Ltd. |
| Owens Corning |
| Taishan Fiberglass |
| China Beihai Fiberglass Co., Ltd. |
| China Jushi Co., Ltd. |
| Johns Manville |
| Saint-Gobain |
| Chongqing Polycomp International Corporation (CPIC) |
| Others |
Cost & Logistics Intelligence
Backward integration into glass fiber melting anchors both supply security and pricing power for furnace-integrated producers serving wind energy blade molders. China's MEE emissions caps and the EU REACH framework are compressing margins for non-compliant converters while rewarding certified suppliers with multi-year offtake premiums.
Pricing Analysis
Distributor margin compression is accelerating as tier-one wind OEMs negotiate direct mill relationships that bypass traditional channel intermediaries. Three-tier pricing structure across certified premium, standard-grade, and economy-level mats reflects REACH compliance status and filament diameter precision. Pricing pressure stems from natural gas volatility in melting operations, with composite manufacturers in construction showing highest price sensitivity while offshore blade molders accept premiums for supply continuity guarantees.
Supply Chain Analysis
Domestic-content mandates in India's MNRE wind installation targets are reshaping sourcing patterns for blade manufacturers seeking to avoid import dependency. Raw material flows draw from furnace clusters in China, Germany, and the United States, with boron and silica sand feeding melting operations. Single-source vulnerability concentrates in Jiangsu and Zhejiang provinces where MEE emissions caps threaten output consistency. Distribution runs through direct mill relationships for wind energy customers and regional distributors for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's dual carbon goals and the EU F-Gas Regulation phase-down are mandating low-emission binder transitions that favor certified incumbents.
For Market Incumbents: Anchor furnace-integrated positions by retrofitting coal-gas melting to electric or hydrogen-fired systems before MEE enforcement tightens. Deepen backward integration into controlled filament diameter production to meet GB standards for composite reinforcement. Defend against emerging regional converters in India by establishing captive inventory positions at coastal blade molding clusters. For New Entrants and Emerging Players: Mid-sized composite manufacturers in India's Gujarat and Tamil Nadu corridors represent the most penetrable buyer archetype currently dependent on import channels. Target hydrogen storage tank filament winding applications where Type III and IV pressure vessel specifications favor continuous strand mat suppliers with alternative binder platforms. Pursue qualification partnerships with domestic furnace operators lacking REACH-compliant formulation capabilities. For Investors and Strategic Acquirers: Roll-up economics work for specialty mat converters with GB/T and ISO certification depth because fragmented electrical insulation and corrosion-resistant lining segments lack scaled competitors. Focus on five-to-ten year viability windows for binder technology transitions. Monitor furnace fuel-switching execution timelines in Shandong and Jiangsu provinces as the primary inflection signal for supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Melting | Captive furnace capacity secures filament diameter control under tightening GB standards. |
| Low-Emission Binder Platform Development | REACH-compliant chemistries unlock European wind blade supply contracts at premium pricing. |
| Direct Mill Relationship Expansion | Eliminating distributor layers captures margin from tier-one wind OEM consolidation. |
| Coastal Manufacturing Cluster Proximity | Jiangsu and Zhejiang proximity reduces logistics risk for just-in-time blade molding. |
| Multi-Standard Certification Investment | Simultaneous ISO 9001, GB/T, and blade-specific qualification accelerates customer approval cycles. |
Research Approach
Multiple input streams — primary interviews with furnace operators and blade procurement directors, secondary validation through customs data and MIIT industrial upgrading directives, and technical literature on binder chemistry transitions — were reconciled to construct supply and demand estimates. Conversations captured perspectives from composite manufacturers, renewable energy project developers, and glass fiber R&D leads across China, Germany, and India. SEC filings from publicly traded suppliers, ECHA substance restriction databases, and wind installation auction results provided triangulation anchors for bottom-up and top-down verification.
Data-stream reconciliation applied across product type, application, and manufacturing stage dimensions to model volume and value trajectories over the projection horizon. CAGRs derived from segment-level growth differentials weighted by end-use exposure to regulatory compliance timelines. Forecast inputs incorporated furnace capacity utilization rates under MEE emissions caps and offshore wind rotor diameter scaling curves for reinforcement intensity per blade.
Underlying measurement precision varies by segment; wind energy and electrical insulation applications carry tighter precision than construction-grade volumes given certification documentation depth. Forecasts reflect assumptions around binder technology transition timelines and fuel-switching retrofit completion rates. Supply disruption from MEE enforcement delays or natural gas price spikes could materially revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Mirrored Glass Market
Glass
GCC Flat Glass Market
Glass
Glass Prepreg Market
Glass
Soda Feldspar Market
Glass
Glass Alternative Materials Market
Glass
Global Glass Flake Coatings Market
Glass
Solar Control Glass Market
Glass
Heat Resistant Glass Market
Glass
Mexico Flat Glass Market
Glass
Glass Substrate Market
Glass
Global Ultra-Thin Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
North America Flat Glass Market
Glass
Glass Manufacturing Market
Glass
North America Glass Insulators Market