
 Coated Glass Market | 2026-2036
Coated Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Glass Market Analysis
Silver-based low-emissivity coatings is shifting toward copper and dielectric alternatives as raw material costs and supply security reshape product economics. AGC Inc. leverages integrated magnetron sputtering lines across Japan and Southeast Asia to sustain cost leadership in architectural low-E glass. Saint-Gobain anchors its position through captive float glass capacity in Europe and North America. Guardian Industries competes on regional distribution density, controlling last-mile logistics for commercial glazing contractors.
Coated glass consists of flat glass substrates modified with thin metallic or ceramic films, typically deposited at thicknesses between 100 and 400 nanometers, engineered to manipulate solar transmittance, thermal emissivity, and visible light transmission for energy management and aesthetic control. Magnetron sputtering dominates production of high-performance architectural low-E glass due to precise layer control and reproducibility, while sol-gel coating occupies niche interior design applications where lower capital investment offsets reduced optical precision. Application demand in architecture leads value generation, though solar panel integration represents the fastest-expanding segment as photovoltaic manufacturers specify anti-reflective coated cover glass to boost module efficiency.
Europe's Ecodesign Directive and REACH framework tighten chemical transparency and thermal performance thresholds, compelling reformulation of coating stacks and third-party certification for market access. The US EPA Energy Star program and California Title 24 building standards create parallel compliance pathways that fragment product specifications across jurisdictions. China's GB standards for building energy efficiency, enforced by SAMR and provincial construction authorities, mandate coated glass in new commercial buildings above specified floor areas. Stakeholders must monitor divergence between regional energy performance metrics and coating durability test protocols when configuring product portfolios.
Market Dynamics
Raw material substitution from silver to copper and dielectric alternatives is restructuring coated glass economics, as magnetron sputtering lines retool for supply security rather than optical performance alone. This shift compresses legacy coating stack margins while opening process innovation pathways.
Growth Catalysts
- China's GB standards for building energy efficiency:SAMR and provincial construction authorities mandate coated glass in new commercial buildings above specified floor areas, locking in baseline demand across tier-one cities.
- Photovoltaic module integration:Anti-reflective coated cover glass specified by solar manufacturers to boost module efficiency represents the fastest-expanding application segment.
- Architectural facade retrofits:Commercial building energy upgrades across Germany, France, and the United Kingdom accelerate replacement cycles for thermal performance glass.
Market Restraints
- Silver price volatility:Precious metal input costs in traditional low-emissivity stacks create margin compression that copper alternatives have not yet fully offset.
- Magnetron sputtering equipment concentration:Specialized deposition system suppliers cluster in Germany and Japan, creating capex bottlenecks for new entrants.
- REACH chemical transparency requirements:ECHA reformulation mandates for coating stacks extend third-party certification timelines and raise compliance overhead.
Strategic Opportunities
- India's green building codes:BIS energy efficiency standards and state-level commercial construction mandates in Maharashtra and Karnataka remain underpenetrated relative to installed glazing capacity.
- Sol-gel interior applications:Lower-capital coating methods for decorative and functional interior glass open segments where magnetron sputtering economics fail.
- California Title 24 alignment:Building standards that exceed federal baselines create premium product tiers for manufacturers with thermal performance certification.
Industry Challenges
- Cross-jurisdictional certification complexity:Divergence between European U-value metrics, American SHGC ratings, and Chinese K-value standards forces parallel product configurations.
- Float glass integration requirements:Captive flat glass supply or long-term offtake agreements are necessary to guarantee substrate quality for high-performance coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Glass Market |
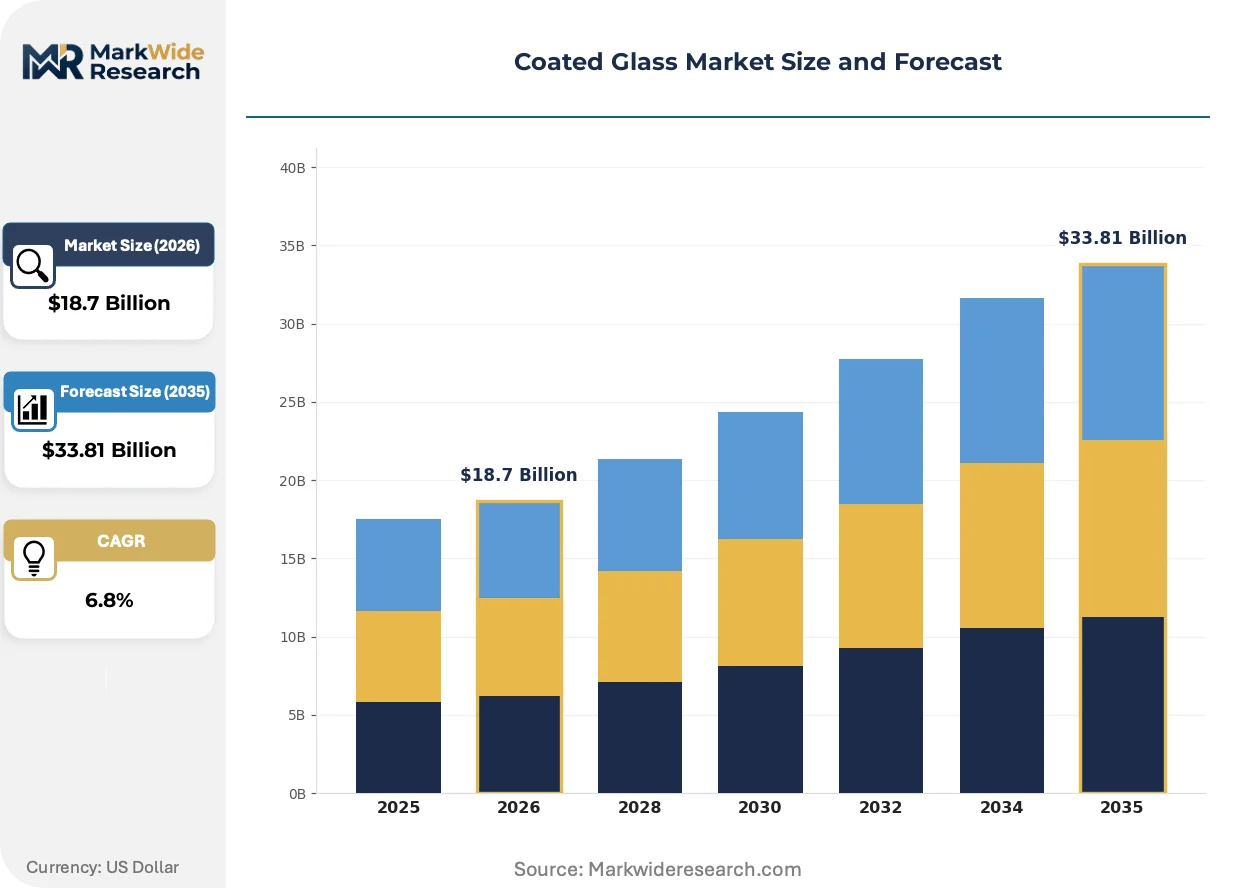
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-E Glass, Laminated Glass, Tinted Glass, Reflective Glass Technology: Magnetron Sputtering, Chemical Vapor Deposition, Sol-Gel Coating, Plasma Coating Application: Architecture, Automotive, Solar Panels, Interior Design End User: Construction, Automotive Manufacturers, Solar Energy Providers, Interior Designers |
| Companies Covered | AGC Inc., Saint-Gobain, Nippon Sheet Glass Co., Ltd., Guardian Industries, PPG Industries, Inc., Corning Incorporated, Vitro, Fuyao Glass Industry Group Co., Ltd., Xinyi Glass Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Glass Market Emerging Trajectories
Coating deposition methods and performance specifications are diverging by end-use, with architectural and photovoltaic applications demanding incompatible optimization paths. Equipment suppliers and glass processors are configuring separate production lines rather than universal platforms.
Copper-based low-emissivity coatings is overtaking silver stacks in cost-sensitive architectural segments. Mid-market commercial glazing contractors in North America and Europe specify copper alternatives for projects where thermal performance thresholds permit slight optical degradation. The technology is overtaking legacy silver dominance in new construction bids where raw material hedging determines contract viability.
Europe's Ecodesign for Energy-Related Products Directive tightens thermal performance thresholds on a staged implementation timeline. Manufacturers reformulate coating stacks to meet descending U-value targets, with 2027 and 2030 compliance gates forcing R&D prioritization. Commercial facade retrofits in Germany, the Netherlands, and Belgium face compressed installation windows as building codes anticipate directive milestones.
Specification authority is consolidating among engineering procurement construction firms managing large commercial projects. Regional glazing contractors lose influence over coating stack selection as EPCs centralize material standards across multi-site portfolios. This concentration is most visible in the United Kingdom and France, where infrastructure and office development pipelines favor bundled facade packages over discrete glass procurement.
Coated Glass Market Segmentation
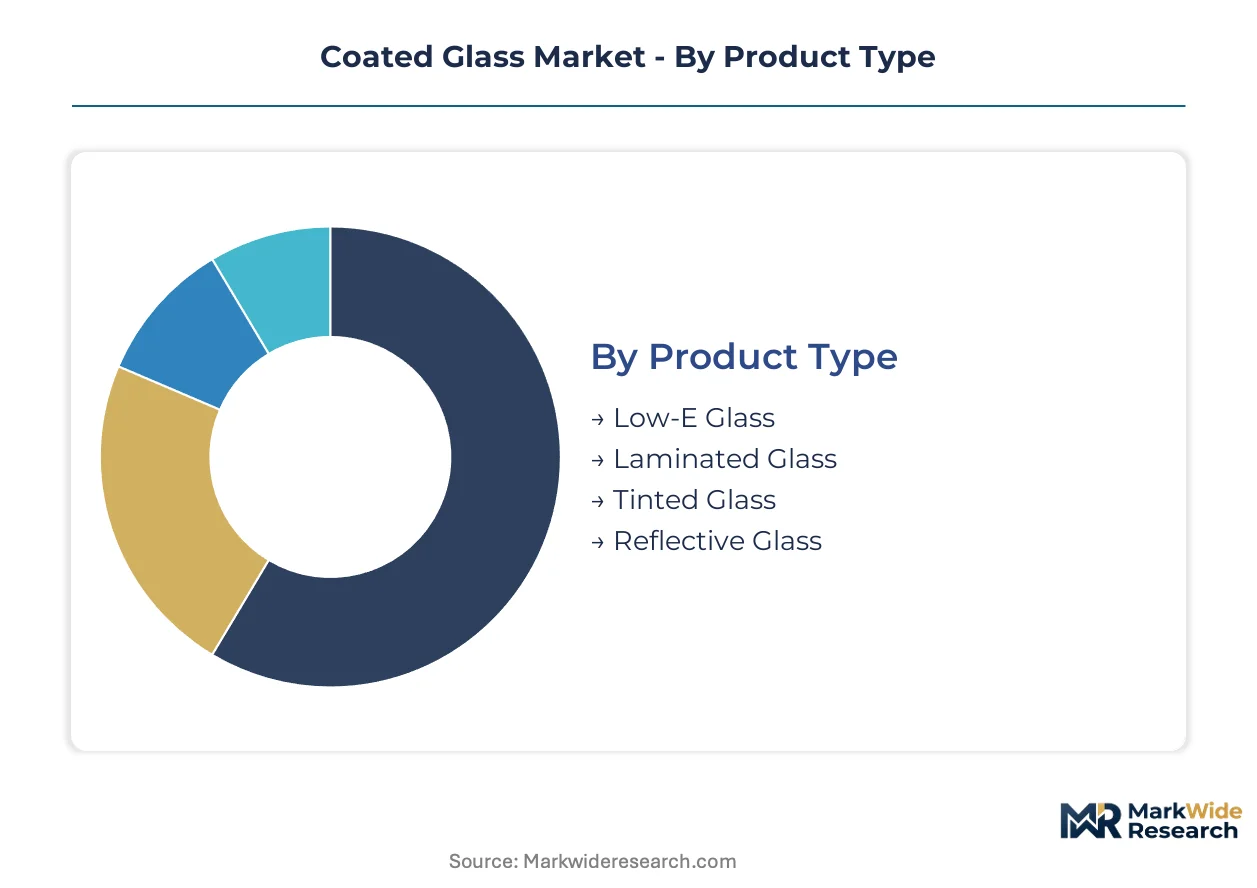
Coated glass segmentation reveals how substrate properties, deposition precision, and end-use thermal requirements create incompatible optimization paths. Manufacturers configure dedicated production lines rather than flexible platforms because architectural low-E specifications diverge sharply from photovoltaic anti-reflective demands.
Product Type:
Customization intensity varies from commodity tinted substrates to engineered multi-stack low-E systems where coating sequence determines thermal performance.
- Low-E Glass:Multi-layer metallic or dielectric stacks deposited at 100-400 nanometers manipulate thermal emissivity and solar transmittance. Demand concentrates in China's tier-one cities where GB standards mandate specified performance thresholds in commercial buildings above floor area minimums.
- Laminated Glass:Interlayer films bonded between coated glass substrates deliver acoustic damping and safety fragmentation control. Automotive manufacturers in Germany and Japan specify laminated configurations for acoustic performance in premium electric vehicle segments.
- Tinted Glass:Bulk colorants in the glass melt reduce solar heat gain through absorption rather than spectral selectivity.
- Reflective Glass:Single-layer metallic coatings create mirror aesthetics with limited thermal precision for cost-sensitive facade applications.
Leading the category by volume: Low-E Glass. Expanding most quickly: Laminated Glass.
Technology:
Capital intensity and optical precision separate deposition methods, with magnetron sputtering commanding architectural high-performance segments and sol-gel occupying decorative niches.
- Magnetron Sputtering:Vacuum deposition with precise layer control dominates architectural low-E production where U-value reproducibility is mandatory. Equipment suppliers cluster in Germany and Japan, creating capex bottlenecks for new entrants seeking coating line expansion.
- Chemical Vapor Deposition:Gas-phase precursor reactions deposit functional layers at atmospheric or reduced pressure. Solar panel manufacturers specify CVD-processed anti-reflective coatings for cover glass integration where module efficiency gains justify process costs.
- Sol-Gel Coating:Liquid-phase ceramic precursors enable lower-capital deposition for interior decorative applications.
- Plasma Coating:Ionized gas activation enhances adhesion and density for specialized optical filters.
Magnetron Sputtering captures the dominant revenue share. Sol-Gel Coating offers the lowest barrier to entry for regional processors.
Application:
Energy performance mandates and aesthetic requirements fragment demand across building envelopes, transportation glazing, and renewable energy integration.
- Architecture:Facade and fenestration systems drive value generation through thermal performance compliance. Europe's Ecodesign Directive staged implementation tightens U-value thresholds, compelling coating stack reformulation for 2027 and 2030 compliance gates.
- Solar Panels:Anti-reflective coated cover glass specified by photovoltaic manufacturers represents the steepest expansion trajectory as module efficiency specifications intensify.
- Automotive:Windshield and sunroof applications demand optical clarity combined with infrared rejection.
- Interior Design:Decorative and functional partitions utilize lower-specification coatings where capital constraints favor sol-gel methods.
Architecture generates the largest absolute revenue. Solar Panels climb the fastest on percentage basis.
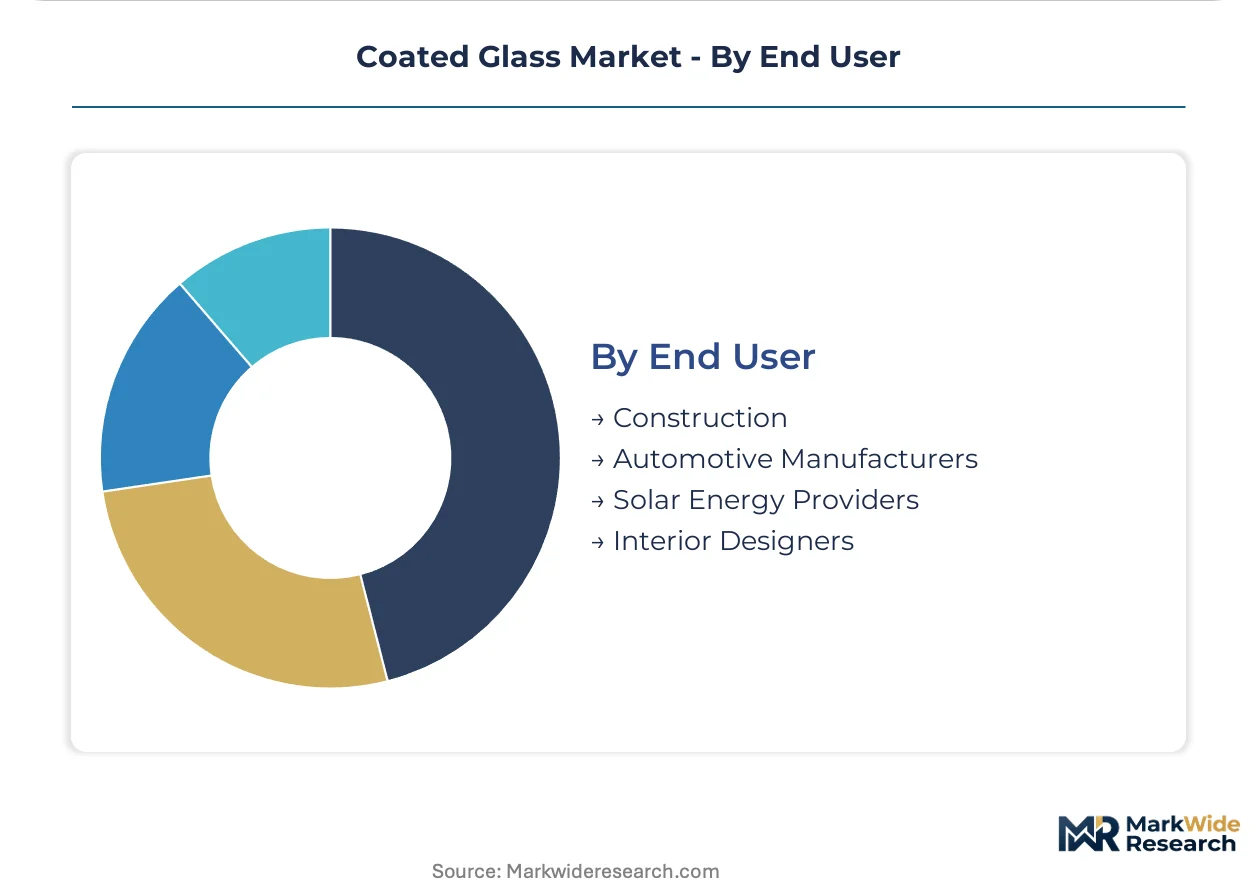
End User:
Procurement authority concentrates among engineering procurement construction firms for commercial glazing, while automotive and solar verticals maintain captive specification control.
- Construction:Commercial building developers and facade contractors procure coated glass through EPC-managed material standards. Specification authority in the United Kingdom and France has consolidated among bundled facade package providers.
- Solar Energy Providers:Photovoltaic module assemblers specify cover glass coatings with transmission-optimized stacks. Procurement patterns favor long-term offtake agreements with float-integrated coaters.
- Automotive Manufacturers:OEM glazing divisions source laminated and infrared-rejecting configurations.
- Interior Designers:Project-based procurement of decorative coated glass for hospitality and corporate fit-outs.
Construction commands the largest procurement volume. Solar Energy Providers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of coated glass consumption, with tier-one cities enforcing the strictest green building mandates. Germany and the United States follow as mature markets where facade retrofit cycles and solar integration drive replacement demand. Japan and India represent contrasting growth profiles—established high-performance specifications versus emerging code adoption.
China
Commercial construction in Shanghai, Beijing, and Shenzhen absorbs the majority of low-E glass volume under GB standards enforced by SAMR. Provincial construction authorities mandate coated glass in new commercial buildings above specified floor areas, locking in baseline demand. The Yangtze River Delta hosts the densest concentration of float-integrated coating facilities serving both domestic and export markets.
Germany
Building energy upgrades across commercial portfolios accelerate replacement cycles for thermal performance glass. The Ecodesign for Energy-Related Products Directive tightens U-value thresholds on staged timelines through 2027 and 2030. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate magnetron sputtering equipment suppliers and facade engineering firms.
United States
California Title 24 building standards exceed federal baselines, creating premium product tiers for certified manufacturers. The EPA Energy Star program runs parallel compliance pathways that fragment specifications across jurisdictions. Texas and Florida commercial construction markets favor cost-optimized copper-based coatings where thermal performance thresholds permit optical trade-offs.
Japan
Automotive and architectural glazing specifications demand precise optical clarity combined with infrared rejection. METI efficiency standards and JIS certification requirements maintain high technical barriers for imported products. The Kanto region around Tokyo anchors domestic float glass capacity with captive coating lines for premium residential and commercial applications.
India
Maharashtra and Karnataka state-level commercial construction mandates remain underpenetrated relative to installed glazing capacity. BIS energy efficiency standards are tightening, though enforcement lags behind tier-one city adoption in China. The Delhi-NCR corridor shows early concentration of green building certification projects specifying imported low-E systems.
Coated Glass Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated float-coat operations commanding architectural specifications and regional processors serving cost-sensitive retrofits. The market structure tiers around captive raw glass supply, deposition technology access, and certification breadth. Three archetypes dominate: multinational integrated glassmakers with global float capacity, regional coaters dependent on third-party substrate supply, and photovoltaic-focused specialists optimizing anti-reflective stacks. Competitive moves center on backward integration into float glass production and selective technology licensing to bypass equipment supply bottlenecks.
Within the integrated multinational tier, AGC Inc., Saint-Gobain, and Nippon Sheet Glass Co., Ltd. occupy positions defined by geographic production footprints and captive substrate control. AGC exemplifies the Asia-Pacific anchored archetype with magnetron sputtering concentration in Japan and Southeast Asia. Saint-Gobain represents the European-North American dual-base model with float capacity on both continents. Nippon Sheet Glass sits within the precision-focused tier where automotive and architectural specifications demand overlapping technical capabilities.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain |
| Nippon Sheet Glass Co., Ltd. |
| Guardian Industries |
| PPG Industries, Inc. |
| Corning Incorporated |
| Vitro |
| Fuyao Glass Industry Group Co., Ltd. |
| Xinyi Glass Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Europe's Ecodesign for Energy-Related Products Directive gates qualified supply and premium-tier pricing access by mandating descending U-value thresholds that only certified coating stacks can satisfy. SAMR enforcement of China's GB standards and California's Title 24 create parallel compliance barriers that concentrate premium pricing power among float-integrated coaters with captive certification breadth.
Pricing Analysis
High-volume architectural contracts trade margin for scale while precision photovoltaic and automotive specifications command 40-60% premiums. Three-tier pricing structure across premium, standard, and economy levels separates magnetron-sputtered low-E systems from copper-alternative retrofits and commodity tinted substrates. Cost compression in mid-market commercial glazing intensifies because raw material substitution from silver to copper has not fully offset precious metal volatility. Regional glazing contractors exhibit acute price sensitivity compared to engineering procurement construction firms managing bundled facade packages.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns that control last-mile logistics for commercial glazing contractors. Float glass supply concentrates in China, Germany, and Japan where captive coating lines guarantee substrate quality for high-performance stacks. Silver, copper, and dielectric sputtering targets draw from concentrated metallurgical suppliers in South Korea and Chile. Single-source vulnerability in specialized magnetron sputtering equipment from German and Japanese vendors creates capex bottlenecks for capacity expansion. Distribution runs through EPC-managed material standards rather than discrete glass procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetron sputtering equipment concentration props pricing by constraining qualified supply expansion, creating durable margin pools for certified incumbents.
For Market Incumbents: Lock in float glass supply or long-term offtake agreements to guarantee substrate quality as coating stack reformulation accelerates under Ecodesign Directive timelines. Deepen backward integration into captive float capacity where regional competitors rely on third-party substrate access. Prioritize certification investment in California Title 24 and China's GB standards to defend specification authority against emerging copper-alternative specialists. For New Entrants and Emerging Players: Sol-gel coating technology offers a technology-first wedge into interior decorative applications where magnetron sputtering economics fail and capital barriers are lowest. Target Maharashtra and Karnataka state mandates in India where BIS energy efficiency standards remain underpenetrated relative to installed glazing capacity. Pursue project-based procurement relationships with hospitality and corporate fit-out designers rather than competing for EPC-managed commercial bundles. For Investors and Strategic Acquirers: Equipment order backlogs at German and Japanese sputtering system suppliers are the leading indicator that coating capacity expansion will lag demand growth through the medium term. Position for five-to-ten year holding periods where float-integrated coaters with certification breadth compound pricing power. Monitor provincial construction authority enforcement intensity in China's tier-two cities as the signal for demand inflection beyond baseline tier-one mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass | Captive substrate supply guarantees coating quality for Ecodesign-compliant low-E stacks. |
| Copper-Based Coating Stack Development | Raw material substitution hedges silver price volatility for cost-sensitive commercial bids. |
| Photovoltaic Anti-Reflective Partnership | Long-term offtake agreements with module assemblers lock in fastest-expanding application demand. |
| Regional Distribution Density Expansion | Last-mile logistics control reinforces specification authority among glazing contractors. |
| Third-Party Certification Acceleration | Parallel REACH, Title 24, and GB standard compliance opens multi-jurisdictional product tiers. |
Methodological Framework
Independent corroboration across regulatory filings, customs trade data, and equipment supplier order books underwrites the qualitative findings in this study. Primary interviews with coating line engineers, commercial glazing procurement managers, EPC facade specialists, and solar module manufacturing directors combined with secondary validation from SAMR enforcement bulletins, ECHA substance registrations, and EPA Energy Star certification databases. Bottom-up demand modeling across building construction permits and top-down capacity assessment from float glass furnace announcements established convergent estimates.
Comparable-period anchoring to historical retrofit cycles and solar installation trajectories calibrated the projection framework across the analysis window. Segmentation dimensions modeled include coating technology precision tier, end-use thermal performance requirement, and regional regulatory compliance cluster. CAGRs derived from installed base turnover rates and efficiency mandate implementation timelines incorporated silver price volatility scenarios and equipment delivery lead times as sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt precious metal price spikes or Ecodesign Directive acceleration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Tinted Glass Market
Glass
Impact Resistant Glass Market
Glass
Solar Control Glass Market
Glass
Global Glass Tempering System Market
Glass
Heat Resistant Glass Market
Glass
North America and Australia Silica Market
Glass
Patterned Glass Market
Glass
Glass Vials Market
Glass
Glass Balustrade Lamination Market
Glass
Glass Product Market
Glass
Middle East and Africa Glassware Market
Glass
Flexible Glass Market
Glass
Antiglare Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Glass Mat Market
Glass
Silica Market