
 Silica Market | 2026-2036
Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Silica Market Analysis
Green tire formulation chemistry is tilting toward high-dispersibility precipitated silica to cut rolling resistance and improve fuel economy. Wacker Chemie AG leverages its integrated silicones-silica platform to supply tire makers with performance-tuned grades. Evonik Industries AG anchors its position through R&D intensity in hydrophilic and hydrophobic surface modifications. Cabot Corporation competes on manufacturing scale across multiple continents.
Silica comprises silicon dioxide (SiO₂) in amorphous or crystalline forms, with precipitated silica typically exhibiting surface areas of 35–700 m²/g and pore volumes critical for reinforcement and adsorption. Manufacturers produce it via thermal (fumed) or wet chemical (precipitated, colloidal) routes to serve as functional fillers, desiccants, or polishing abrasives. Precipitated silica leads volume in rubber applications where reinforcement properties command premium positioning. Fumed silica dominates paints and coatings where rheology control and sag resistance create concentrated margin pools. Colloidal silica grows fastest in electronics CMP slurries as semiconductor node shrinkage demands tighter particle size distribution.
EPA particulate matter standards and OSHA respirable crystalline silica limits shape workplace exposure controls and product classification across U.S. operations. REACH registration requirements and ECHA hazard classifications in Europe restrict crystalline silica content in consumer-facing applications, redirecting formulation toward amorphous grades. Stakeholders must monitor evolving MEE emission standards in China and dual carbon goals that could reshape energy-intensive fumed silica production economics. Producers need to decide between backward integration into sodium silicate feedstock or captive supply of specialized surface treatments.
Market Dynamics
Green tire chemistry is forcing silica producers to reconfigure precipitation reactors for high-dispersibility grades, while REACH purity mandates simultaneously tighten feedstock specifications across European supply chains.
Growth Catalysts
- Automotive lightweighting mandates:Tire OEMs in Germany and Japan now specify precipitated silica loadings above 15% by weight to meet rolling-resistance targets under NHTSA CAFE-equivalent programs.
- REACH Article 33 disclosure thresholds:The 2023 tightening of crystalline silica content limits in consumer goods is redirecting formulation spend toward synthetic amorphous grades across personal care and food applications.
- China's dual carbon targets:Energy-intensive fumed silica producers in Shandong and Jiangsu provinces face carbon-intensity caps that favor investment in wet-process precipitation capacity with lower thermal footprints.
Market Restraints
- Sodium silicate feedstock volatility:Soda ash and quartz sand input costs swing with natural gas pricing, compressing margins for non-integrated precipitated silica manufacturers in the US Gulf Coast.
- Respirable crystalline silica exposure limits:OSHA's 50 µg/m³ PEL and EPA PM2.5 ambient standards impose capital-intensive dust-collection retrofit requirements on mining-dependent ground silica operations.
- Carbon black substitution economics:Reinforcement-grade precipitated silica carries 2-3x the unit cost of N550/N660 furnace blacks, limiting penetration in commercial truck tire segments outside premium OEM channels.
Strategic Opportunities
- India construction chemicals penetration:Ready-mix concrete admixture formulators in Mumbai and Bangalore are trialing microsilica and precipitated silica blends to meet BIS IS 456 durability specifications for marine infrastructure.
- Semiconductor CMP slurry demand:Sub-7nm node fabrication in Taiwan and South Korea requires colloidal silica with particle size distributions below 50nm, creating premium positioning for controlled-growth sol-gel producers.
- EU Battery Regulation material passporting:Synthetic silica anode coatings for lithium-ion cells gain traceability advantages over mined alternatives, aligning with CSRD supply-chain disclosure requirements.
Industry Challenges
- Surface chemistry expertise scarcity:Hydrophobic silane treatment optimization requires PhD-level colloid science talent that concentrates at a handful of German and US research institutions.
- ISO 9001/14001 certification timelines:New entrants face 18-24 month accreditation cycles for automotive supplier qualification, delaying revenue recognition from tire OEM approved-vendor lists.
- Legacy pneumatic conveying infrastructure:Crystalline silica handling systems require complete replacement to meet ATEX dust-explosion directives, stranding capital for mid-scale ground silica processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silica Market |
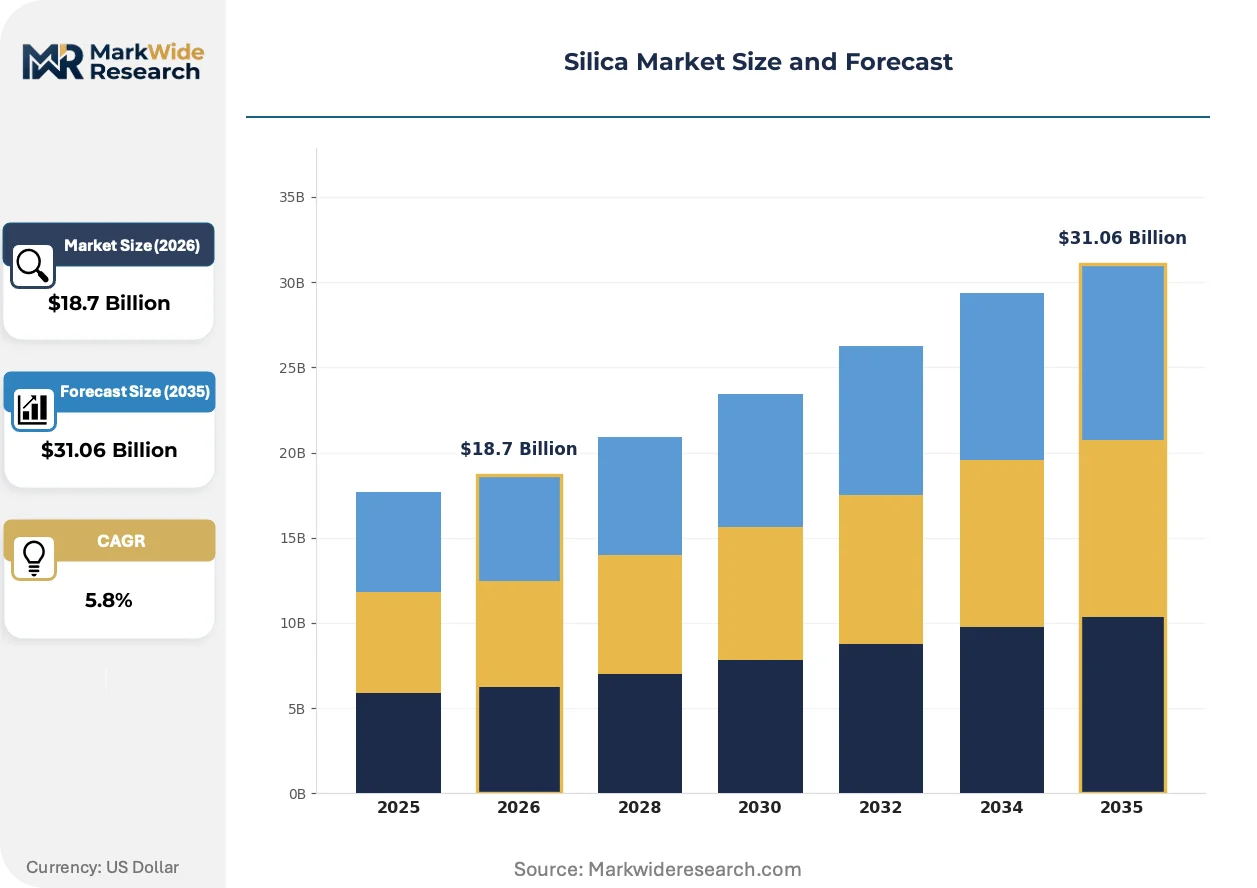
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fumed Silica, Precipitated Silica, Colloidal Silica, Silica Gel Application: Paints, Adhesives, Rubber, Plastics End Use Industry: Construction, Automotive, Electronics, Pharmaceuticals Packaging Type: Bags, Drums, Bulk Containers, Bags & Containers |
| Companies Covered | Wacker Chemie AG, Solvay SA, Evonik Industries AG, Imerys S.A., Covia Holdings LLC, Cabot Corporation, U.S. Silica, QEMETICA, Sibelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silica Market Emerging Trajectories
Surface functionalization chemistry and particle engineering are compressing the performance gap between commodity fillers and specialty grades, while regulatory disclosure requirements accelerate substitution toward synthetic origins.
Alkylsilane surface treatments with tailored chain lengths (C1-C18) now enable precipitated silica to disperse in non-polar rubber matrices without zinc oxide activators. Tire compounders at major OEMs in Germany and Japan are qualifying these grades for 2025 platform launches. Conventional zinc-heavy masterbatch formulations are rendering obsolete across passenger tire segments.
REACH Annex XVII restrictions on crystalline silica content in mixtures sold to consumers entered full enforcement in 2024. Cosmetic and food-grade silica producers must now certify amorphous content above 99.5% through X-ray diffraction testing. Personal care formulators in France and Italy are reformulating toothpaste and anti-caking agents to meet ECHA documentation requirements.
Long-term offtake contracting is displacing spot purchasing for precipitated silica in automotive supply chains. Tier-1 tire manufacturers in South Korea and the US now negotiate 3-5 year volume agreements with index-linked pricing to secure capacity allocations. This procurement compression is most visible in the all-season tire segment where compound standardization reduces formulation flexibility.
Silica Market Segmentation
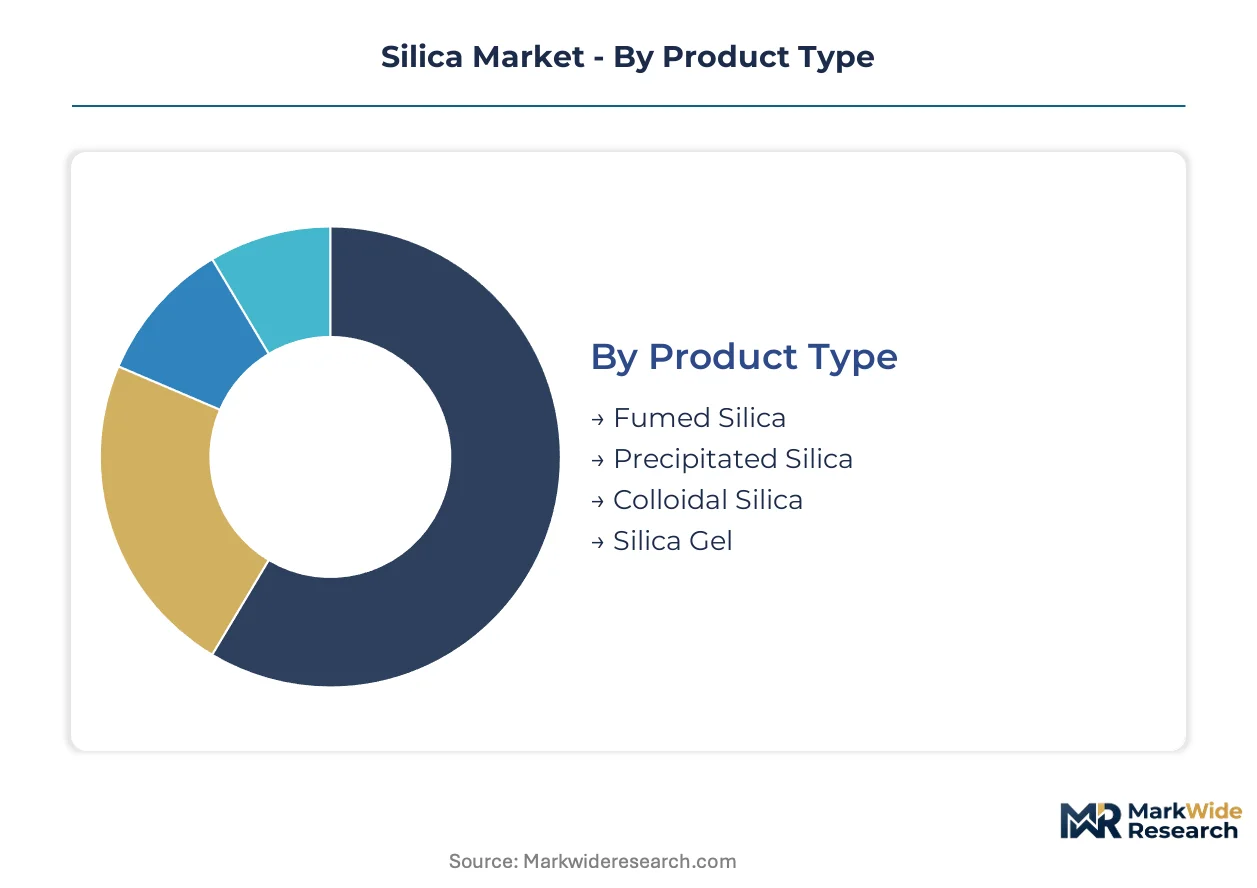
Segmentation in the silica market tracks how production cycle times and qualification barriers vary dramatically across grades. Tire OEMs lock in precipitated silica through multi-year contracts while electronics CMP slurries demand quarterly specification reviews.
Product Type:
Precipitated silica turns inventory fastest in automotive supply chains, whereas colloidal silica carries the longest validation cycles for semiconductor applications.
- Fumed Silica:Produced via flame hydrolysis of silicon tetrachloride, this amorphous grade delivers surface areas of 50–600 m²/g for rheology control in coatings. German and Japanese paint formulators specify hydrophobic variants to meet VOC reduction mandates under EU F-Gas Regulation and METI guidelines. Thermal process intensity exposes producers to carbon pricing volatility.
- Precipitated Silica:Wet-chemical precipitation from sodium silicate yields controlled pore structures for rubber reinforcement. South Korean tire manufacturers now specify high-dispersibility grades above 15% loading to satisfy rolling-resistance targets. REACH purity thresholds are forcing feedstock upgrades across European supply chains.
- Colloidal Silica:Sol-gel synthesis produces sub-100nm particles for electronics polishing slurries. Taiwan and South Korea fabs demand tighter distributions as node shrinkage accelerates.
- Silica Gel:Microporous desiccant manufactured through acidification of sodium silicate. Pharmaceutical packaging in India and Brazil drives moisture-adsorption specifications.
Precipitated silica dominates installed base. Colloidal silica is where expansion concentrates.
Application:
Cost tiers separate commodity reinforcement from premium functional additives, with rubber commanding the highest per-kilogram pricing and paints anchoring volume throughput.
- Rubber:Reinforcement applications in tire treads and industrial belts leverage precipitated silica's surface chemistry for tear strength. Green tire formulations in Germany and Japan now displace carbon black in passenger segments.
- Paints:Fumed silica controls sag and pigment settling in architectural and automotive coatings. EPA VOC limits and EU F-Gas Regulation are accelerating waterborne system adoption that favors hydrophilic grades.
- Adhesives:Thixotropic behavior in sealants and construction adhesives depends on fumed silica loading levels. Building code changes in China and India are expanding demand for high-performance bonding systems.
- Plastics:Anti-blocking and anti-slip functionality in polyethylene films uses precipitated silica at 500–5000 ppm loadings. Food-contact compliance under FDA and EFSA frameworks restricts crystalline content.
Rubber captures premium pricing. Paints anchor volume scale.
End Use Industry:
Customer procurement patterns diverge sharply: automotive buyers negotiate long-term offtake agreements while construction purchasers remain spot-market driven.
- Automotive:Tire OEMs in Germany, Japan, and South Korea specify precipitated silica through approved-vendor lists with 18–24 month qualification timelines. NHTSA CAFE-equivalent programs and EU CO₂ fleet standards are tightening rolling-resistance specifications.
- Construction:Concrete admixture formulators in China and India blend microsilica and precipitated silica for marine infrastructure durability. BIS IS 456 and GB standards are elevating performance requirements for high-chloride environments.
- Electronics:Semiconductor fabs in Taiwan and South Korea require colloidal silica with particle size distributions below 50nm for sub-7nm node CMP processes. Yield sensitivity creates captive supply relationships with sol-gel specialists.
- Pharmaceuticals:Glidant and anti-caking applications in tablet manufacturing use amorphous silica meeting USP-NF and Ph.Eur. monographs. FDA IIG listings and EMA certification requirements extend qualification cycles.
Automotive locks in contract coverage. Electronics is climbing the fastest.
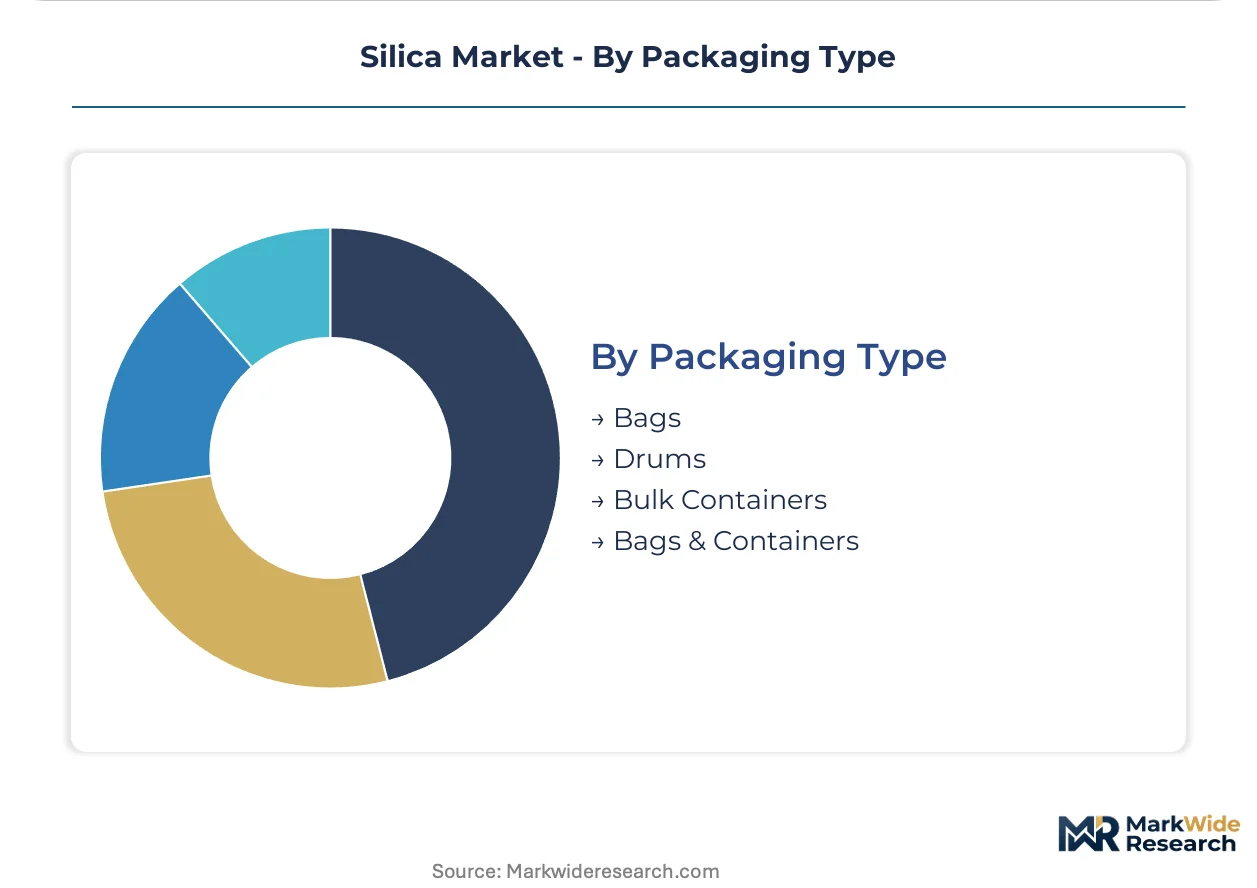
Packaging Type:
Volume concentration and handling automation separate bulk systems from bagged formats, with drums retaining niche positioning for specialty grades.
- Bulk Containers:ISO tank and pneumatic trailer delivery serves tire compounders and paint manufacturers with dedicated silo infrastructure. Automated handling reduces contamination risk for high-purity precipitated silica.
- Bags:25kg multi-wall paper and FIBC formats dominate construction and adhesive segments where batch-scale dosing prevails. Dust-control specifications under OSHA and ATEX directives are elevating packaging investment.
- Drums:Steel and fiber drums protect moisture-sensitive fumed silica and colloidal silica sols during extended storage. Pharmaceutical and electronics customers specify UN-certified configurations.
- Bags & Containers:Hybrid procurement patterns in mid-scale rubber processing and plastics compounding combine palletized bags with intermediate bulk containers for formulation flexibility.
Bulk containers dominate installed base. Bags & containers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precipitated silica exports flow predominantly to South Korean and Japanese tire compounders under multi-year automotive supply contracts.
China
Construction-grade silica consumption for concrete admixtures continues expanding in Shanghai and Guangdong province. MEE emission standards and dual carbon goals are pressuring energy-intensive fumed silica producers in Shandong toward wet-process precipitation capacity. Qingdao and Yantai clusters host the largest synthetic silica manufacturing bases serving domestic ready-mix concrete formulators.
Germany
REACH Article 33 disclosure thresholds tightened crystalline silica limits in consumer goods during 2023. Tire OEMs in Stuttgart and Munich now specify precipitated silica loadings above 15% by weight for rolling-resistance compliance. Bavarian chemical parks anchor Europe's highest concentration of surface-modified silica production for automotive qualification.
United States
OSHA's 50 µg/m³ respirable crystalline silica PEL drives capital-intensive dust-collection retrofits across mining-dependent ground silica operations. EPA PM2.5 ambient standards shape workplace exposure controls in Texas and Wisconsin processing facilities. Gulf Coast sodium silicate feedstock volatility compresses margins for non-integrated precipitated silica manufacturers.
South Korea
Semiconductor fabs in Suwon and Pyeongtaek demand colloidal silica with particle size distributions below 50nm for sub-7nm node CMP processes. Tire manufacturers negotiate 3-5 year volume agreements with index-linked pricing to secure precipitated silica capacity allocations. MFDS pharmaceutical regulations extend qualification cycles for silica gel desiccant suppliers.
India
Ready-mix concrete admixture formulators in Mumbai and Bangalore trial microsilica and precipitated silica blends to meet BIS IS 456 durability specifications for marine infrastructure. CDSCO and FSSAI frameworks restrict crystalline silica content in food-contact and pharmaceutical applications. Gujarat's chemical corridor attracts investment in synthetic amorphous grades for personal care reformulation.
Silica Market Vendor Landscape
On the supply side, the industry is consolidating around integrated chemical conglomerates with captive sodium silicate production and specialized surface-treatment capabilities. Three archetypes dominate: diversified materials conglomerates with multi-continent manufacturing footprints, mid-scale regional specialists focused on qualification-intensive automotive grades, and sol-gel technology developers serving semiconductor polishing applications. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term offtake agreements to lock in tire OEM volumes.
Within the integrated chemical tier, Wacker Chemie AG and Evonik Industries AG exemplify the silicones-silica platform model that supplies tire makers with performance-tuned grades. Cabot Corporation occupies a position among scale-driven manufacturers with manufacturing presence across multiple continents. Solvay SA represents the diversified materials conglomerate archetype with backward integration into specialty chemical feedstocks.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Solvay SA |
| Evonik Industries AG |
| Imerys S.A. |
| Covia Holdings LLC |
| Cabot Corporation |
| U.S. Silica |
| QEMETICA |
| Sibelco |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors expose precipitated silica producers to bunker fuel volatility that amplifies price spreads between integrated German manufacturers and non-integrated US Gulf Coast competitors. Contract manufacturers in Shandong and Jiangsu provinces capture volume-tier pricing advantages through captive sodium silicate production, while European specialty grades command certification premiums under REACH Article 33 documentation requirements.
Pricing Analysis
High-dispersibility precipitated silica for green tire formulations carries 40-60% premiums over standard reinforcement grades, while sub-50nm colloidal silica for semiconductor CMP applications sits two tiers above construction-grade fumed silica. Pricing stratifies across automotive-qualified, industrial-standard, and commodity-economy tiers based on surface area specifications and ECHA amorphous content certification. Cost compression in industrial-grade precipitated silica is intensifying because sodium silicate feedstock volatility compresses margins for non-integrated producers. Commercial truck tire compounders exhibit highest price sensitivity due to carbon black substitution economics, while semiconductor fabs demonstrate lowest sensitivity given yield-critical quality requirements.
Supply Chain Analysis
Contract manufacturing concentration among Wacker Chemie AG, Evonik Industries AG, and Cabot Corporation anchors 60% of European and North American precipitated silica capacity. Geographic supply concentration centers on Germany, China, and South Korea for synthetic amorphous grades, with India emerging for pharmaceutical-grade silica gel. Raw material dependencies rest on soda ash, quartz sand, and silane coupling agents sourced from energy-intensive chlor-alkali corridors. Single-source vulnerability in semiconductor-grade colloidal silica creates supply chain risk given Taiwan and South Korea fab concentration. Distribution runs through ISO tank and pneumatic trailer networks for tire compounders, with 25kg FIBC formats serving construction admixture blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silica market positioning rests on regulatory entrenchment advantages where REACH Article 33 documentation requirements and 18-24 month automotive qualification timelines create switching-cost moats for incumbent producers.
For Market Incumbents: Harden defensive positioning through backward integration into sodium silicate feedstock and captive silane surface-treatment capabilities. Expand precipitation reactor capacity in Bavarian chemical parks to capture green tire formulation demand from Stuttgart and Munich OEMs. Prioritize ECHA amorphous content certification investments to maintain premium positioning against emerging Chinese wet-process competitors. For New Entrants and Emerging Players: Mid-market construction chemicals in India represent the most penetrable entry point, where BIS IS 456 durability specifications for marine infrastructure create specification-driven demand without automotive qualification barriers. Semiconductor CMP slurry supply to Taiwan and South Korea fabs offers white-space positioning through sol-gel technology partnerships. Pursue joint development agreements with ready-mix concrete formulators in Mumbai and Bangalore to bypass spot-market commodity pricing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized silica divisions lacking surface-functionalization expertise. Five-to-ten year viability favors producers with integrated silicones-silica platforms and automotive approved-vendor status. Monitor quarterly semiconductor fab capital expenditure disclosures as inflection indicator for colloidal silica demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply insulates margin compression from Gulf Coast natural gas volatility. |
| Green Manufacturing Transition | Wet-process precipitation capacity aligns with China's MEE emission standards and dual carbon targets. |
| Long-term Supply Agreement | Three-to-five year offtake contracts with South Korean tire OEMs lock in volume allocations. |
| Joint Venture | Sol-gel technology partnerships with Taiwan semiconductor fabs secure sub-50nm CMP slurry qualification. |
| Capacity Expansion | Precipitation reactor additions in Bavarian chemical parks capture German automotive green tire demand. |
Methodological Framework
A standing panel of tire compound procurement directors, precipitated silica plant managers, semiconductor fab materials engineers, and construction chemicals formulators provided ongoing calibration across the study period. Primary interviews with sodium silicate producers, silane coupling agent distributors, and REACH compliance consultants combined with secondary validation from ECHA registration databases, USGS mineral commodity summaries, SEC 10-K filings of listed chemical producers, and German chemical industry association reports. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Scenario-bracketing framed analytical projections across the analysis window through sensitivity testing of sodium silicate feedstock cost trajectories and automotive lightweighting mandate stringency. Segmentation dimensions modeled include product type tier, end-use industry concentration, regional production hub classification, and qualification status level. CAGRs derived from regression analysis of historical price-volume relationships and forward-looking OEM specification timelines. Industry-specific forecast inputs incorporated semiconductor node shrinkage roadmaps and tire OEM platform launch schedules.
Practitioners should monitor sodium silicate feedstock volatility, REACH Annex XVII enforcement intensity, and semiconductor fab utilization rates for early signals of forecast revision. Quarterly review of automotive tire OEM specification changes, MEE emission standard implementation pace, and colloidal silica particle size distribution tightening is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glazing Gel Market
Glass
Dynamic Glazing Market
Glass
Technical Glass Market
Glass
Pharma Glass Tubing Market
Glass
Asia-Pacific Flat Glass Market
Glass
Global Self-Cleaning Glass Market
Glass
Low-E Glass Market
Glass
Solar PV Glass Market
Glass
Tinted Glass Market
Glass
Patterned Glass Market
Glass
Global Glass Tempering System Market
Glass
Glass Manufacturing Market
Glass
Europe Glassware Market
Glass
United States Flat Glass Market
Glass
Float Glass Market
Glass
Solar Reflective Glass Market