
 Asia-Pacific Flat Glass Market | 2026-2036
Asia-Pacific Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
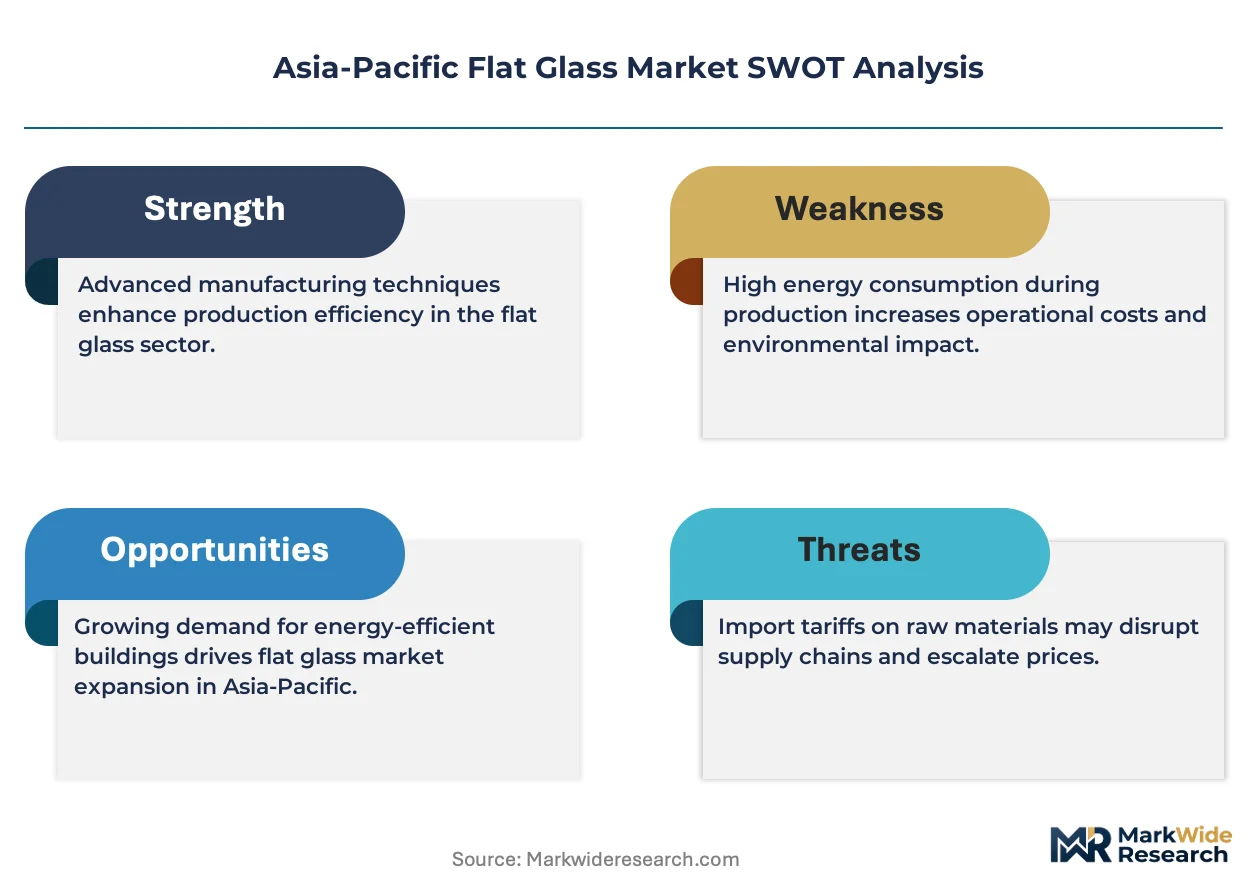
Asia-Pacific Flat Glass Market Analysis
Market Context with Strategic Players
Skilled furnace technicians and specialized float-line engineers across coastal China is unwinding capacity bottlenecks that had constrained ultra-thin glass output. Xinyi Glass Holdings Co. Ltd. leverages captive silica sand reserves and integrated soda ash production to sustain cost leadership across architectural float volumes. AGC Inc. anchors premium laminated and coated glass supply through technology leadership in solar-control coatings for Southeast Asian commercial towers. Fuyao Group dominates automotive OEM channels with disciplined manufacturing scale across its Fujian and Hubei complexes.
Technical Definition and Structural Segments
Asia-Pacific flat glass denotes sheet glass manufactured primarily through the float process, where molten silica sand, soda ash, and limestone flow across a tin bath to achieve thickness tolerances between 0.4 mm and 25 mm with uniform optical clarity. This material serves as a structural and functional substrate for architectural glazing, vehicle windscreens, solar panel covers, and display panels across the region's manufacturing base. Float glass occupies the largest revenue pool given its ubiquity in construction, though coated glass carries superior margin structures as India's BIS and China's GB standards tighten thermal performance requirements. Laminated glass competes aggressively in automotive and high-rise safety applications, while patterned glass retains niche positions in furniture and interior partitioning segments across Japan and South Korea.
Regulatory Frame and Forward-Looking Close
China's MEE enforces dual carbon emission ceilings that elevate low-carbon float furnace retrofits from optional to mandatory, while India's BIS certification and China's GB standards dictate minimum thermal transmittance values for building-integrated glazing. Japan's METI guides industrial efficiency benchmarks that filter through JIS standards into procurement specifications for electronics and automotive glass. Stakeholders must monitor how rapidly India's PLI scheme for solar module manufacturing translates into certified tempered and coated glass demand, and whether furnace fuel-switching timelines in Shandong and Guangdong provinces outpace regional natural gas infrastructure buildout.
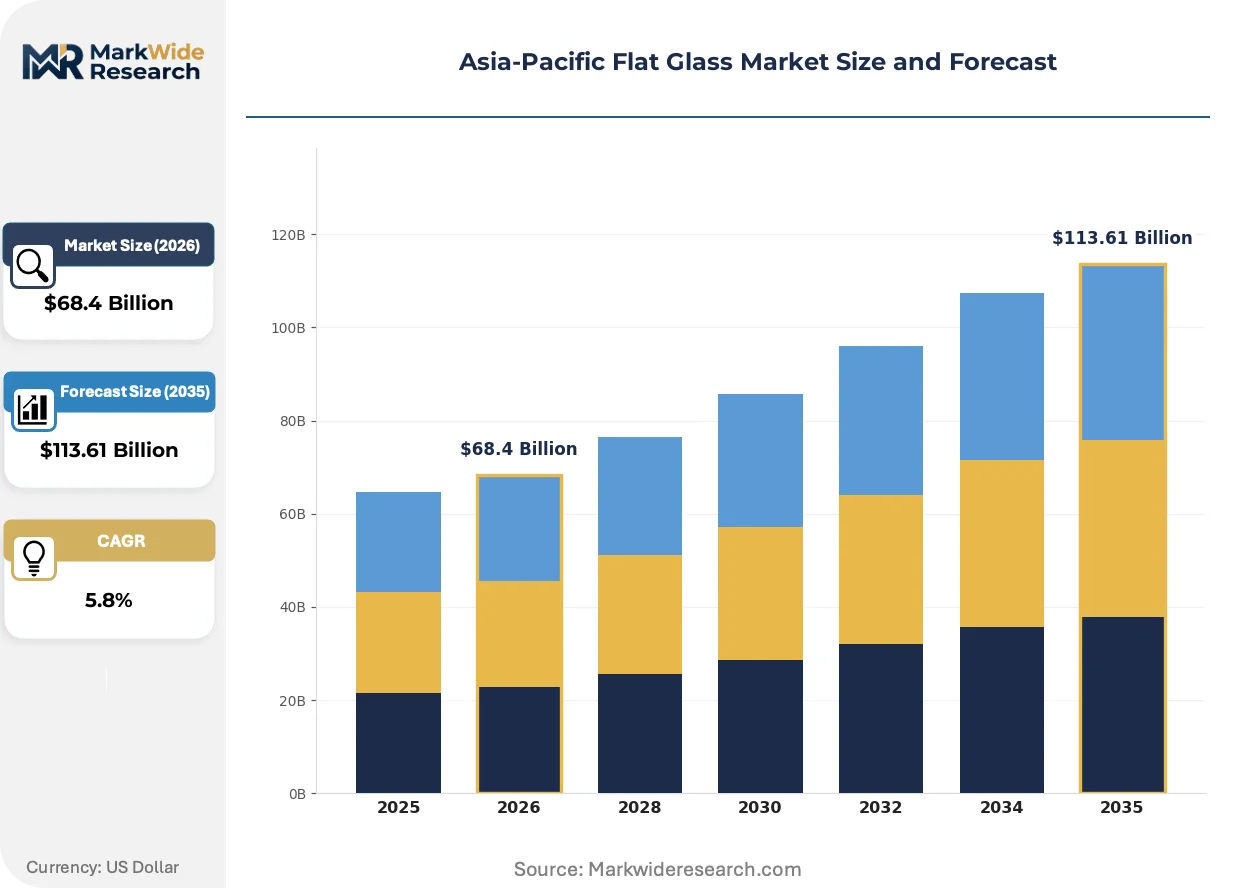
Market Dynamics
China's dual carbon mandates from MEE are forcing furnace fuel-switching timelines that outpace regional natural gas infrastructure buildout, compressing supply elasticity across the Asia-Pacific flat glass value chain.
Growth Catalysts
- India's PLI scheme for solar modules:Certified tempered and coated glass procurement is accelerating as domestic module manufacturing scales, pulling high-performance substrates into the country's western and southern state clusters.
- Float furnace retrofits:Low-carbon furnace technology adoption is unlocking capacity expansion in Shandong and Guangdong provinces where MEE emission ceilings have tightened.
- Southeast Asian commercial construction:Solar-control coated glass volumes are lifting across Vietnam, Thailand, and Indonesia as high-rise development concentrates in Ho Chi Minh City and Bangkok corridors.
Market Restraints
- Soda ash and silica sand cost volatility:Input price swings constrain margin stability for non-integrated producers lacking captive mineral reserves.
- Ultra-thin glass supply concentration:Skilled furnace technician scarcity across coastal China bottlenecks output below 2mm thickness specifications for electronics substrates.
- Natural gas infrastructure gaps:Pipeline delivery shortfalls in India's western states delay furnace fuel-switching compliance with BIS energy-efficiency mandates.
Strategic Opportunities
- India's urban infrastructure renewal:Western and southern state clusters present white-space demand for low-emissivity architectural glazing as municipal building codes tighten.
- Automotive OEM glass integration:Laminated windscreen specifications are converging with head-up display compatibility requirements, opening premium tier expansion.
- Japan's METI efficiency benchmarks:JIS-standard procurement specifications for electronics glass are redirecting volume toward suppliers with certified low-carbon production credentials.
Industry Challenges
- Float-line engineer scarcity:Specialized technical talent gaps across China and India constrain furnace commissioning speed and quality yield optimization.
- BIS certification timeline compression:Thermal transmittance testing bottlenecks are delaying product approval cycles for low-emissivity coatings entering Indian commercial projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flat Glass Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Laminated Glass, Coated Glass, Patterned Glass Application: Automotive, Construction, Furniture, Electronics End User: Architects, Manufacturers, Distributors, Retailers Technology: Heat-Treated, Embeded Films, Tinted, Insulated |
| Companies Covered | Xinyi Glass Holdings Co. Ltd., Fuyao Group, AGC Inc., KIBING GROUP, China Glass Holdings Limited, Nippon Sheet Glass Co. Ltd, Guardian Glass, Jinjing (Group) Co., Ltd., Saint-Gobain, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flat Glass Market Emerging Trajectories
Electrification of float furnaces and digital coating control systems are actively compressing the carbon intensity and optical variance of Asia-Pacific flat glass production.
Electrified float furnace technology is displacing conventional natural gas-fired melting across newbuild lines in Jiangsu and Zhejiang provinces. Commercial developers in Singapore and Sydney are specifying these lower-carbon substrates for LEED-equivalent certifications. The shift is compressing the cost premium between standard and low-carbon architectural glass to under fifteen percentage points.
China's GB standards for building-integrated glazing are tightening minimum thermal transmittance values annually through 2030. Manufacturers are responding with triple-silver low-emissivity coating investments that exceed current code minimums by thirty percent. India's BIS is harmonizing toward these thresholds, forcing import substitution toward domestic coated glass capacity.
Direct procurement contracts between glass fabricators and solar module assemblers are consolidating channel structures across India and Southeast Asia. Distributors are losing share to long-term supply agreements that lock in tempered and coated glass volumes for five-year horizons. This pattern is most visible in India's Tamil Nadu and Karnataka manufacturing corridors where module assembly clusters have formed.
Asia-Pacific Flat Glass Market Segmentation
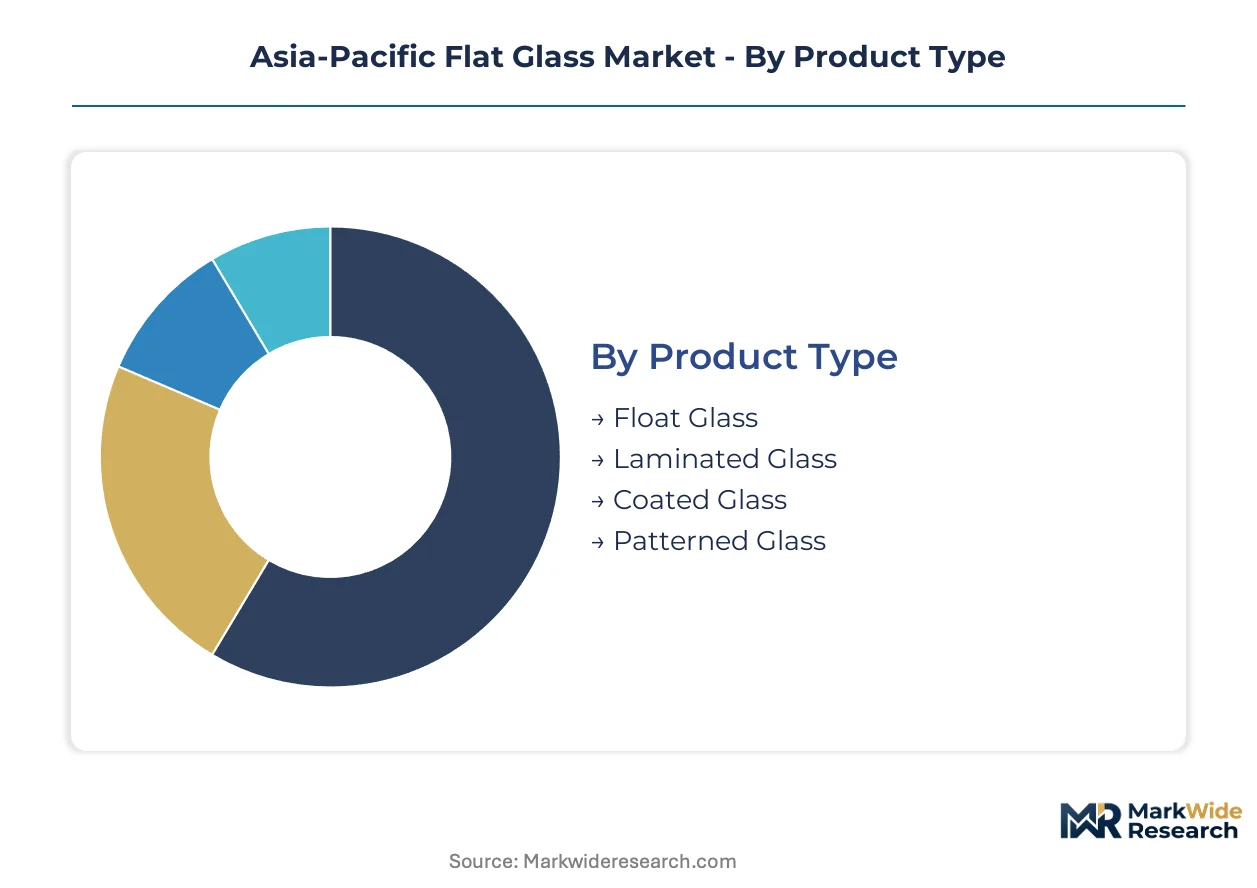
Segmentation in Asia-Pacific flat glass reveals how regulatory divergence across China, India, and Japan fragments procurement specifications and margin structures. Product categories align with distinct compliance pathways—BIS thermal mandates favor coated solutions, while MEE emission ceilings reshape float capacity economics.
Product Type:
China's GB standards and India's BIS certification create divergent performance floors that segment procurement by thermal and optical specifications rather than commodity grades alone.
- Float Glass:Molten silica sand, soda ash, and limestone flow across a tin bath to achieve thickness tolerances between 0.4 mm and 25 mm with uniform optical clarity. Construction corridors across Vietnam, Thailand, and Indonesia absorb the largest architectural volumes as high-rise development concentrates in Ho Chi Minh City and Bangkok.
- Coated Glass:Sputtered metallic oxide layers deliver solar-control and low-emissivity performance exceeding baseline thermal transmittance requirements. India's western and southern state clusters are redirecting procurement toward domestic coated capacity as BIS mandates harmonize toward Chinese GB thresholds.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for automotive windscreen and high-rise safety applications.
- Patterned Glass:Rolled surface textures serve furniture and interior partitioning niches across Japan and South Korea.
Established volume favors Float Glass; emerging adoption favors Coated Glass.
Application:
End-use concentration in automotive OEM channels versus dispersed construction procurement creates divergent margin and contract structures across the value chain.
- Construction:Architectural glazing commands the largest revenue pool across commercial towers, residential high-rises, and municipal infrastructure renewal. India's urban infrastructure programs in western and southern state clusters are accelerating low-emissivity specification penetration as municipal building codes tighten thermal performance floors.
- Automotive:Laminated windscreen and tempered side-lite specifications converge with head-up display compatibility requirements. Fujian and Hubei manufacturing corridors anchor disciplined supply scale to Japanese, Korean, and domestic Chinese OEM assembly plants.
- Electronics:Ultra-thin substrates below 2mm thickness serve display panel covers and touch sensor substrates.
- Furniture:Patterned and tinted volumes serve interior design applications with limited technical specification intensity.
Construction absorbs dominant volume share; automotive commands premium pricing tiers.
End User:
Channel structure consolidation around direct procurement versus distributor intermediation varies sharply by application complexity and contract scale.
- Architects:Specification authority over thermal performance, optical clarity, and LEED-equivalent certification drives coated and low-carbon substrate selection. Singapore and Sydney commercial developers are embedding electrified furnace provenance into procurement criteria.
- Manufacturers:Solar module assemblers in Tamil Nadu and Karnataka manufacturing corridors are locking in five-year direct contracts for tempered and coated glass volumes, displacing traditional distributor channels.
- Distributors:Inventory-bearing intermediaries retain relevance in fragmented furniture and residential construction segments.
- Retailers:End-consumer facing channels serve replacement and small-scale project demand with limited technical consultation.
Manufacturer direct procurement is climbing the fastest; distributor channel share compresses.
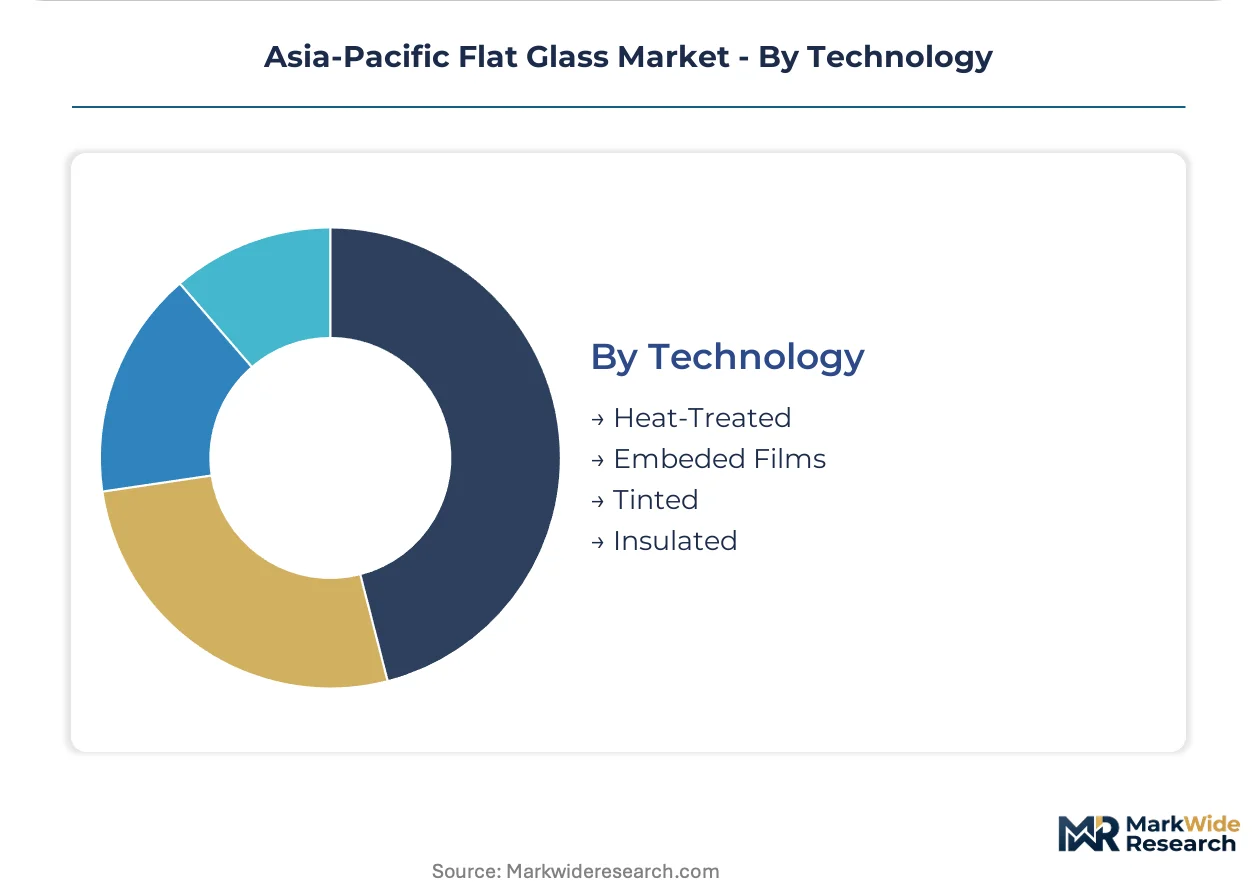
Technology:
Process differentiation determines compliance eligibility for safety-critical and energy-efficiency mandated applications.
- Heat-Treated:Thermal tempering and heat-strengthening processes elevate mechanical resistance and fragmentation safety for automotive and architectural applications. BIS certification timelines for thermal transmittance testing are bottlenecking approval cycles for heat-treated low-emissivity products entering Indian commercial projects.
- Insulated:Gas-filled cavity construction delivers superior thermal transmittance performance exceeding China's tightening GB standards. Triple-silver low-emissivity coating investments are pushing performance thirty percent above current code minimums.
- Embeded Films:Polymer interlayers and functional films enable smart glass and switchable opacity applications.
- Tinted:Bulk coloration reduces solar gain in cost-sensitive architectural applications.
Insulated technology holds steepest expansion trajectory; Tinted applications face specification displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the regulatory framework reshaping flat glass capacity economics across the Asia-Pacific, with dual carbon mandates forcing furnace retrofits that outpace natural gas infrastructure buildout in Shandong and Guangdong provinces.
China
Float furnace electrification and ultra-thin glass output expansion drive capacity investments across Jiangsu and Zhejiang provinces. MEE emission ceilings compress supply elasticity for sub-2mm electronics substrates. Coastal manufacturing corridors near Shanghai face skilled technician scarcity that bottlenecks quality yield optimization.
India
PLI scheme acceleration for solar module manufacturing pulls certified tempered and coated glass demand into Tamil Nadu and Karnataka assembly clusters. BIS thermal transmittance mandates redirect procurement toward domestic low-emissivity capacity. Western state infrastructure gaps delay pipeline-delivered natural gas access for furnace compliance.
Japan
METI efficiency benchmarks filter through JIS standards into electronics and automotive glass procurement specifications. Display panel cover demand concentrates in Kanto manufacturing corridors. Premium laminated volumes serve head-up display compatibility requirements for domestic OEM supply chains.
Vietnam
High-rise development in Ho Chi Minh City corridors lifts solar-control coated glass volumes for commercial tower glazing. Foreign fabricator investments target export positioning toward ASEAN construction markets. Coastal industrial zones absorb float glass imports for local processing and distribution.
Thailand
Bangkok commercial construction concentrates demand for architectural laminated and insulated glass specifications. Japanese automotive OEM assembly plants anchor tempered windscreen procurement volumes in Eastern Seaboard manufacturing corridors. Distributor channel consolidation accelerates around direct fabricator-to-developer contracting.
Asia-Pacific Flat Glass Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific flat glass market. Integrated producers with captive mineral reserves command margin stability against soda ash volatility, while coating specialists capture premium tiers through solar-control and low-emissivity performance. Three archetypes dominate: backward-integrated float giants, regional automotive-focused fabricators, and technology-led coated glass specialists. Competitive moves concentrate on furnace fuel-switching compliance and direct procurement contract consolidation with solar module assemblers.
Within the integrated cost-leadership tier, Xinyi Glass Holdings Co. Ltd. and Fuyao Group exemplify archetypes combining captive raw material access with disciplined manufacturing scale. AGC Inc. occupies a position representing technology-led premium positioning through coating expertise and laminated safety glass specialization. These three anchors illustrate how geographic concentration in coastal China and diversified end-use exposure separate margin-stable volume players from specification-driven premium competitors.
| Leading Market Players |
|---|
| Xinyi Glass Holdings Co. Ltd. |
| Fuyao Group |
| AGC Inc. |
| KIBING GROUP |
| China Glass Holdings Limited |
| Nippon Sheet Glass Co. Ltd |
| Guardian Glass |
| Jinjing (Group) Co., Ltd. |
| Saint-Gobain |
| Others |
Supply Flow & Price Mechanics
China's GB standards for thermal transmittance and India's BIS certification gates simultaneously qualify suppliers for premium architectural projects and stratify price tiers between commodity float and performance-grade coated glass. This dual-gate mechanism concentrates pricing power among integrated producers with captive coating capacity while compressing margins for non-certified import-dependent fabricators.
Pricing Analysis
Price spreads between Jiangsu-produced electrified float glass and conventional natural gas-fired output from Shandong narrow as MEE compliance costs embed into baseline quotes. Pricing stratifies across premium low-carbon certified, standard BIS-compliant, and economy non-coated tiers, with solar-control coatings commanding the widest spread. Cost compression in standard float intensifies as soda ash volatility feeds through to non-integrated producers. Distributor intermediaries in residential construction exhibit highest price sensitivity; architects specifying LEED-equivalent commercial towers show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites silica sand flows from Australian and Indonesian mining concessions to coastal Chinese float complexes. Raw material sourcing draws from captive soda ash production in Inner Mongolia, imported limestone from Vietnam, and metallurgical-grade tin for bath operations. Single-source vulnerability concentrates in skilled furnace technician pools across Jiangsu and Zhejiang provinces. Distribution runs through direct procurement contracts with solar module assemblers in Tamil Nadu and Karnataka, displacing traditional inventory-bearing intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct procurement platforms between glass fabricators and solar module manufacturers signal platform-economics consolidation, with long-term offtake agreements displacing spot-market liquidity and rewiring margin capture toward integrated coating specialists.
For Market Incumbents: Consolidate backward integration into captive silica sand and soda ash reserves to insulate margin stability against input volatility. Accelerate low-carbon furnace certification to meet MEE emission ceilings before infrastructure gaps in Guangdong and Shandong harden competitive disadvantage. Channel control through five-year direct contracts with Tamil Nadu module clusters locks out distributor-dependent challengers. For New Entrants and Emerging Players: BIS fast-track certification for low-emissivity coatings opens white-space penetration in India's western state infrastructure renewal corridors, where thermal mandate enforcement outpaces domestic coated capacity buildout. Target underpenetrated furniture and interior partitioning segments across South Korea and Japan with patterned glass specialization, leveraging lower certification intensity. Go-to-market through architect specification relationships in Singapore commercial towers bypasses distributor channel consolidation. For Investors and Strategic Acquirers: India's PLI scheme acceleration for solar modules reshapes the acquisition landscape toward coated glass specialists with certified tempered substrate capacity in Karnataka and Tamil Nadu manufacturing corridors. Long-term viability centers on fuel-switching compliance positioning ahead of MEE retrofit deadlines. Monitor BIS testing bottleneck resolution as the inflection signal for Indian commercial project procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Furnace Retrofit | MEE emission ceilings in Shandong and Guangdong compress supply elasticity for non-compliant float capacity. |
| Direct Procurement Platform | Tamil Nadu solar module assemblers lock five-year coated glass volumes, displacing distributor intermediaries. |
| BIS Certification Fast-Track | Western India infrastructure renewal accelerates specification penetration for domestic low-emissivity capacity. |
| Captive Mineral Reserve Acquisition | Integrated soda ash and silica sand sourcing insulates margin stability against input price volatility. |
| Triple-Silver Coating Investment | GB standard harmonization pushes thermal performance thirty percent above current code minimums. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with float line engineers, solar module procurement leads, BIS certification officers, and commercial glazing contractors; and secondary validation through customs trade databases, SEC filings of listed glass manufacturers, MEE emission disclosure registries, and BIS product certification listings. Bottom-up volume triangulation from state-level construction permit data and top-down demand modeling from solar module assembly capacity announcements were cross-referenced for convergence.
Across the analysis window, forecasts segmented by product type, application, technology tier, and regional regulatory cluster were constructed. CAGRs derived from historical float furnace commissioning rates, coating line capacity additions, and PLI scheme disbursement trajectories were stress-tested against infrastructure buildout timelines in India's western states. Industry-specific inputs included skilled technician pipeline estimates from Jiangsu vocational training programs and natural gas pipeline completion schedules in Shandong and Guangdong.
Underlying assumptions cover MEE enforcement continuity, BIS testing capacity expansion, and PLI scheme disbursement velocity, with deviation risk concentrated in furnace fuel-switching timeline slippage and solar module assembly cluster formation delays. Practitioners should keep alternative scenarios live as India's natural gas infrastructure buildout and China's dual carbon mandate implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Prepreg Market
Glass
Crystalware and Glassware Market
Glass
Porous Glass Market
Glass
Glass Lined Equipment Market
Glass
Glazing Gel Market
Glass
North America Architectural Flat Glass Market
Glass
Foam Glass Market
Glass
Insulated Glass Market
Glass
Patterned Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Latin America Flat Glass Market
Glass
North America Industrial Silica Sand Market
Glass
United States Flat Glass Market
Glass
Birefringent Crystals Market
Glass
Asia-Pacific Glassware Market
Glass
Europe Flat Glass Market