
 Global Glassware Market | 2026-2036
Global Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glassware Market Foresight
Market Context
Premium artisan glassware is consolidating around hand-blown crystal and designer collaborations, while commodity drinking glasses face margin compression from Asian manufacturing scale. Arc International S.A. leverages automated furnace technology to dominate mass-market tableware across European retail channels. Riedel Glas differentiates through grape-varietal-specific stemware that commands price premiums in fine-dining procurement. Krosno Glass S.A. anchors its position in decorative glassware through Polish craftsmanship heritage and direct-to-hotel channel control.
Technical Definition and Segment Structure
Glassware encompasses vessels, instruments, and decorative objects formed from silica-based melts shaped by blowing, pressing, or casting, with borosilicate formulations tolerating thermal shock up to 165°C for laboratory and professional kitchen applications. Drinking glasses and tableware occupy mature volume positions with thin margins, while laboratory glassware captures concentrated margin pools from research institution procurement contracts. Decorative glassware competes on aesthetic differentiation, with hospitality end users driving specification upgrades in boutique hotel fit-outs.
Regulatory Frame and Outlook
EU REACH restrictions on lead crystal leaching and FDA food-contact surface standards govern material composition and market access for export-oriented manufacturers. ISO 3585 borosilicate specifications and ECHA substance evaluations shape R&D allocation between lead crystal heritage lines and tempered glass innovation. Stakeholders must monitor evolving Ecodesign requirements for lighting fixtures and accelerating scientific research funding cycles that reorder laboratory glassware procurement priorities.
Market Dynamics
EU REACH lead-content restrictions are forcing crystal glassware manufacturers to reallocate R&D toward soda-lime formulations, compressing heritage product lines while opening margin pools for compliant alternatives. This regulatory pivot intersects with hospitality procurement teams prioritizing thermal durability in high-turnover settings.
Growth Catalysts
- Borosilicate thermal performance:Laboratory and professional kitchen applications drive specification upgrades. Research institution procurement contracts prioritize ISO 3585-compliant vessels tolerating thermal shock up to 165°C.
- REACH compliance investment:ECHA substance evaluations redirect manufacturer capital from lead crystal heritage lines. Soda-lime alternatives capture redirected demand from export-oriented producers.
- German precision exports:Regional production clusters anchor laboratory glassware demand. Precision instrument exports sustain specialized furnace capacity and skilled craft labor pools.
Market Restraints
- Energy input volatility:Natural gas prices govern furnace operating economics. European manufacturers face margin compression from input cost spikes relative to Asian competitors.
- Supply concentration risk:Automated furnace technology concentrates mass-market tableware production among capital-intensive operators. Smaller hand-blown producers lack scale to compete on unit economics.
- Substitution by polymers:Polycarbonate and Tritan copolyester displace glassware in outdoor hospitality and healthcare settings. Weight and breakage risk drive material switching in specific end-uses.
Strategic Opportunities
- Indian hospitality expansion:Boutique hotel fit-outs in Mumbai and Bangalore drive specification upgrades for artisan decorative glassware. Direct-to-hotel channel control rewards early entrants.
- EU Ecodesign lighting integration:Decorative glassware converges with LED fixture manufacturing. Hand-blown shade production captures cross-category margin pools from lighting retrofit cycles.
- Scientific research funding cycles:National science foundation budgets in Germany, France, and the UK reorder laboratory glassware procurement priorities. Timing capital allocation to funding announcements captures contract volumes.
Industry Challenges
- Master glassblower scarcity:Traditional craft skills face generational attrition. Training pipelines fail to replace retiring artisans in Bohemian and Polish heritage clusters.
- Furnace certification timelines:FDA food-contact surface standards and ISO 3585 compliance extend new product qualification cycles. Small-batch producers lack resources to parallel-track multiple certification paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glassware Market |
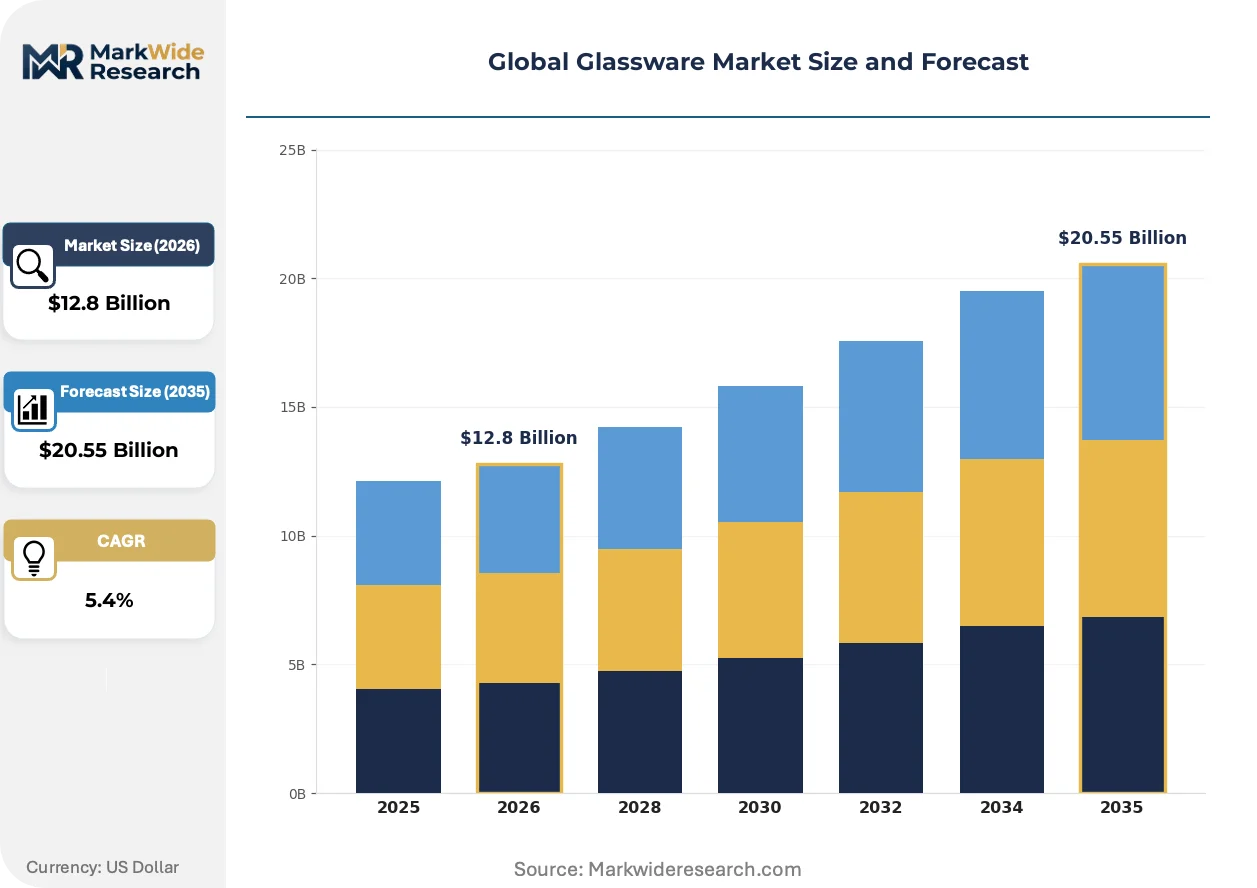
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drinking Glasses, Laboratory Glassware, Decorative Glassware, Tableware, Lighting Fixtures Material: Borosilicate, Soda Lime, Lead Crystal, Tempered Glass, Annealed Glass Application: Food Service, Scientific Research, Home Décor, Hospitality, Lighting Solutions End User: Restaurants, Research Institutions, Residential Homes, Event Management, Commercial Spaces |
| Companies Covered | Krosno Glass S.A., Corelle Brands, Arc International S.A., Riedel Glas, Luigi Bormioli, Bormioli Rocco S.p.A., Libbey Glass, Schott Zwiesel, Zwiesel Kristallglas AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glassware Market Shifts & Advancements
Automation in furnace control systems is compressing unit economics for mass-market tableware while simultaneously elevating the scarcity premium for heritage hand-blown techniques. These intersecting forces are fragmenting competitive strategy across price tiers.
Laser-based quality inspection is integrating into high-volume production lines. Automated defect detection systems reduce downstream breakage rates in hospitality supply chains. European retail distributors are adopting these systems to defend margin position against Asian imports with superior unit costs but higher in-service failure rates.
EU REACH restrictions on lead crystal leaching are tightening material composition standards for export market access. ECHA substance evaluations now cover additional heavy metal migratory limits beyond lead. Crystal glassware manufacturers in the Czech Republic and Slovakia are accelerating tempered glass innovation to preserve heritage design aesthetics under compliant formulations.
Direct sourcing from artisan workshops is displacing traditional wholesale distribution in boutique hospitality procurement. Hotel design firms now contract directly with Bohemian and Polish glassblowers for custom fit-out specifications. This channel compression is most visible in German and Austrian alpine resort developments where localized craft provenance commands premium positioning.
Global Glassware Market Segmentation
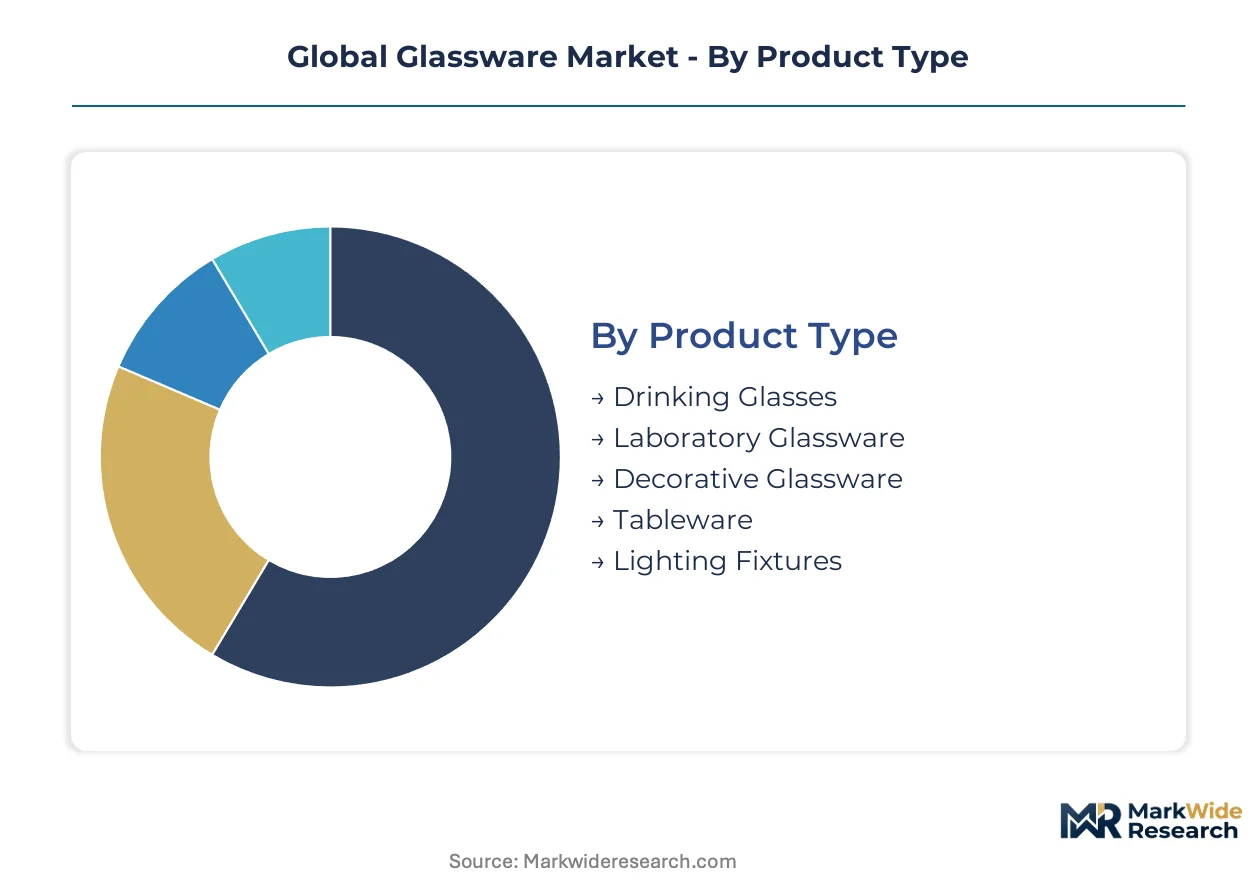
Glassware segmentation reveals divergent margin structures across material formulations and end-use specifications. Procurement patterns in hospitality and laboratory verticals now override traditional channel-based purchasing, reshaping how manufacturers allocate furnace capacity and certification investments.
Product Type:
Thermal shock tolerance and aesthetic durability separate volume leaders from margin capturers across glassware categories.
- Drinking Glasses:Soda-lime formulations dominate mass-market tableware with thin-wall pressing technology. European retail distributors prioritize automated defect detection to reduce breakage rates in hospitality supply chains against Asian import competition.
- Laboratory Glassware:ISO 3585-compliant borosilicate vessels tolerate thermal shock up to 165°C for research applications. German precision exports anchor regional production clusters serving institutional procurement contracts in France and the UK.
- Decorative Glassware:Hand-blown crystal commands premium positioning in boutique hotel fit-outs. Polish and Bohemian heritage clusters face generational craft attrition.
- Tableware:Automated furnace technology concentrates mass-market production among capital-intensive operators. Arc International leverages scale across European retail channels.
- Lighting Fixtures:Decorative glassware converges with LED shade manufacturing. EU Ecodesign requirements drive retrofit demand for hand-blown production.
Drinking Glasses leads on scale; Laboratory Glassware leads on momentum.
Material:
Regulatory compliance costs now exceed raw material differentials in supplier selection decisions.
- Borosilicate:Low thermal expansion coefficient enables laboratory and professional kitchen applications. ECHA substance evaluations reinforce specification premiums for compliant formulations.
- Soda Lime:REACH lead-content restrictions redirect manufacturer R&D from heritage crystal lines. Czech and Slovak producers accelerate tempered glass innovation to preserve design aesthetics.
- Lead Crystal:EU migratory limits compress heritage product volumes. Export-oriented manufacturers face market access barriers in North American and Asian jurisdictions.
- Tempered Glass:Thermal strengthening expands hospitality applications with reduced breakage risk. Polycarbonate substitution threatens outdoor segments.
- Annealed Glass:Cost positioning serves decorative and architectural applications with lower mechanical stress requirements. Energy input volatility compresses margins for European furnace operators.
Soda Lime captures redirected volume; Borosilicate commands specification premiums.
Application:
End-use durability requirements now dictate material selection ahead of aesthetic considerations.
- Food Service:High-turnover restaurant operations prioritize thermal durability and dishwasher compatibility. FDA food-contact surface standards extend qualification cycles for new product introductions.
- Scientific Research:National science foundation budgets in Germany, France, and the UK reorder procurement priorities. Timing capital allocation to funding announcements captures contract volumes.
- Home Décor:Direct-to-consumer channels displace wholesale distribution for artisan specifications. E-commerce logistics constraints favor lighter-weight alternatives.
- Hospitality:Boutique hotel fit-outs in Mumbai and Bangalore drive specification upgrades for decorative glassware. Direct sourcing from artisan workshops compresses traditional distribution margins.
- Lighting Solutions:LED fixture integration creates cross-category margin pools. Hand-blown shade production captures retrofit cycle demand.
Food Service anchors volume absorption; Scientific Research shows steepest expansion trajectory.
End User:
Procurement centralization versus fragmented specification authority determines channel strategy.
- Restaurants:Chain operators consolidate purchasing through approved vendor programs. Independent operators remain accessible to direct artisan sales.
- Research Institutions:German precision instrument exports sustain specialized furnace capacity. Contract timing aligns with national funding cycles.
- Residential Homes:E-commerce penetration shifts volume toward mass-market pressed glass. Premium hand-blown segments retain specialty retail dependence.
- Event Management:Rental and disposable specifications favor cost-optimized soda-lime production. Breakage risk drives material switching to polymers for outdoor deployment.
- Commercial Spaces:Corporate procurement teams prioritize standardized specifications across property portfolios. Design firms specify custom artisan pieces for flagship locations.
Restaurants concentrate volume throughput; Research Institutions concentrate margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master glassblowers in Bohemia and Polish heritage clusters anchor European artisan capacity, while German precision instrument exports sustain specialized laboratory glassware production. These workforce concentrations shape competitive positioning across material formulations and end-use specifications.
Germany
Precision laboratory glassware exports from Thuringia and Bavaria drive regional furnace capacity allocation. ECHA REACH substance evaluations on heavy metal migratory limits redirect R&D investment toward compliant borosilicate formulations. Jena and Mainz production clusters supply ISO 3585-compliant vessels to French and UK research institutions under national science foundation procurement cycles.
Czech Republic
Heritage crystal manufacturers in Bohemia face generational craft attrition as EU lead-content restrictions compress traditional product volumes. ECHA evaluations on crystal glassware leaching accelerate tempered glass innovation in Nový Bor and Železný Brod workshops. These northern Bohemian clusters preserve hand-blown techniques through direct-to-hotel contracts with German and Austrian alpine resort developers.
Poland
Krosno glassblowers anchor decorative glassware supply for boutique hospitality fit-outs across Mumbai and Bangalore. EU Ecodesign requirements for lighting fixtures create cross-category demand in Lower Silesian shade production. The Podkarpackie Voivodeship cluster controls direct-to-hotel channels, bypassing traditional wholesale distribution for artisan specifications.
United States
FDA food-contact surface standards extend qualification cycles for soda-lime tableware imports from Asian manufacturers. Restaurant chain consolidation through approved vendor programs concentrates volume absorption in Ohio and Pennsylvania distribution hubs. Toledo, Ohio retains historical furnace expertise serving mass-market pressed glass demand through automated production lines.
India
Boutique hotel development in Maharashtra and Karnataka drives specification upgrades for imported artisan decorative glassware. BIS standards on food-contact materials govern domestic soda-lime production for food service applications. Mumbai design firms contract directly with European glassblowers, compressing traditional import distributor margins in western India hospitality procurement.
Global Glassware Market Competitive Landscape
Capital-heavy furnace operators compete with asset-light design houses across divergent margin structures. Automated production lines concentrate mass-market tableware among three to four scale-driven players, while hand-blown segments fragment across Bohemian and Polish craft workshops. Strategic archetypes separate into automated furnace specialists, heritage craft houses, and precision laboratory instrument exporters. Competitive moves center on direct-to-hotel channel compression and ISO 3585 certification acquisition for institutional procurement access.
Among European heritage craft houses, Krosno Glass S.A. and Riedel Glas occupy positions exemplifying divergent specialization vectors. Krosno represents the Polish decorative glassware archetype with channel control in hospitality fit-outs. Riedel exemplifies grape-varietal-specific stemware differentiation commanding procurement premiums in fine-dining segments. Arc International S.A. anchors the automated furnace tier, representing mass-market scale economics across European retail distribution. These three illustrate how competitive positioning fragments across thermal performance specifications, craft provenance, and unit cost optimization.
| Leading Market Players |
|---|
| Krosno Glass S.A. |
| Corelle Brands |
| Arc International S.A. |
| Riedel Glas |
| Luigi Bormioli |
| Bormioli Rocco S.p.A. |
| Libbey Glass |
| Schott Zwiesel |
| Zwiesel Kristallglas AG |
| Others |
Supply & Pricing Matrix
EU REACH substance evaluations on heavy metal migratory limits gate qualified supply for premium crystal glassware while compressing margin pools for non-compliant heritage lines. This regulatory filter redirects manufacturer capital toward soda-lime and tempered glass formulations, stratifying pricing access across certification tiers.
Pricing Analysis
Bundled certification and channel services separate premium artisan glassware from unbundled commodity tableware transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 3585 compliance grade and hand-blown provenance as primary differentiation drivers. Cost compression in mass-market soda-lime segments is intensifying because Asian automated furnace operators undercut European unit economics. Chain restaurant procurement teams exhibit highest price sensitivity, while boutique hospitality design firms absorb premiums for direct artisan sourcing.
Supply Chain Analysis
Natural gas supply rests on Norwegian pipeline flows and spot LNG markets, exposing European furnace operators to input cost volatility against Asian competitors. Silica sand draws from Belgian and German deposits, while boron oxide sources concentrate in Turkish and US specialty chemical producers. Single-source vulnerability in borosilicate precursor supply threatens laboratory glassware contract fulfillment. Distribution runs through hospitality procurement consortia and research institution approved vendor programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA REACH heavy metal evaluations continuously reorder compliant formulation demand and redirect manufacturer R&D investment.
For Market Incumbents: Deepen backward integration into borosilicate precursor supply to defend against Turkish and US specialty chemical concentration risk. Secure ISO 3585 certification maintenance capacity to preserve institutional procurement access against emerging precision instrument exporters.
For New Entrants and Emerging Players: Capture direct-to-hotel channel compression in Indian boutique hospitality fit-outs by establishing artisan workshop relationships in Bohemian and Polish heritage clusters. Lead with custom specification capability rather than catalog standard products.
For Investors and Strategic Acquirers: Roll-up economics work for fragmented hand-blown craft workshops because generational attrition concentrates skilled labor scarcity in Bohemia and Podkarpackie Voivodeship. Watch ECHA substance evaluation expansion timelines as inflection indicators for compliant formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Supply | Captive precursor sourcing insulates German precision exporters from Turkish specialty chemical volatility. |
| ISO 3585 Certification Acquisition | Compliance credential unlocks French and UK research institution procurement contract access. |
| Direct-to-Hotel Channel Development | Bypassing wholesale distribution captures premium positioning in Mumbai and Bangalore boutique fit-outs. |
| Automated Defect Detection Deployment | Laser-based quality systems reduce downstream breakage rates in hospitality supply chains. |
| Tempered Glass R&D Acceleration | Thermal strengthening innovation preserves Bohemian design aesthetics under REACH-compliant soda-lime formulations. |
Research Methodology
Direct dialogue with furnace operations managers, hospitality procurement directors, research institution laboratory coordinators, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from EU TARIC customs data, ECHA substance evaluation registers, SEC filings of listed glassware manufacturers, and national science foundation budget disclosures. Bottom-up production capacity modeling triangulated against top-down end-use demand segmentation.
Output projections across material formulation, end-use application, and geographic production cluster dimensions anchored the analytical framework. CAGRs derived from regression analysis of historical furnace capacity utilization correlated with regulatory compliance cost trajectories. Borosilicate thermal shock tolerance specifications and REACH substance evaluation timelines served as industry-specific forecast inputs throughout the modeling period.
Natural gas price spikes, ECHA evaluation scope expansion, and polycarbonate substitution acceleration in outdoor hospitality are the dominant revision risks to output projections. Forecasts reflect documented assumptions on furnace fuel economics and regulatory enforcement intensity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Low Iron Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Pharma Glass Tubing Market
Glass
Double Glazing Glass Market
Glass
Impact Resistant Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Flexible Glass Market
Glass
Glass Grade Dolomite Market
Glass
North America Industrial Silica Sand Market
Glass
Coated Solar Control Glass Market
Glass
Coated Glass Market
Glass
Global Flat Glass Market
Glass
Paper Glass Maker Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Asia Pacific Flexible Glass Market
Glass
East Africa Flat Glass Market