
 Glass Manufacturing Market | 2026-2036
Glass Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Manufacturing Market Analysis
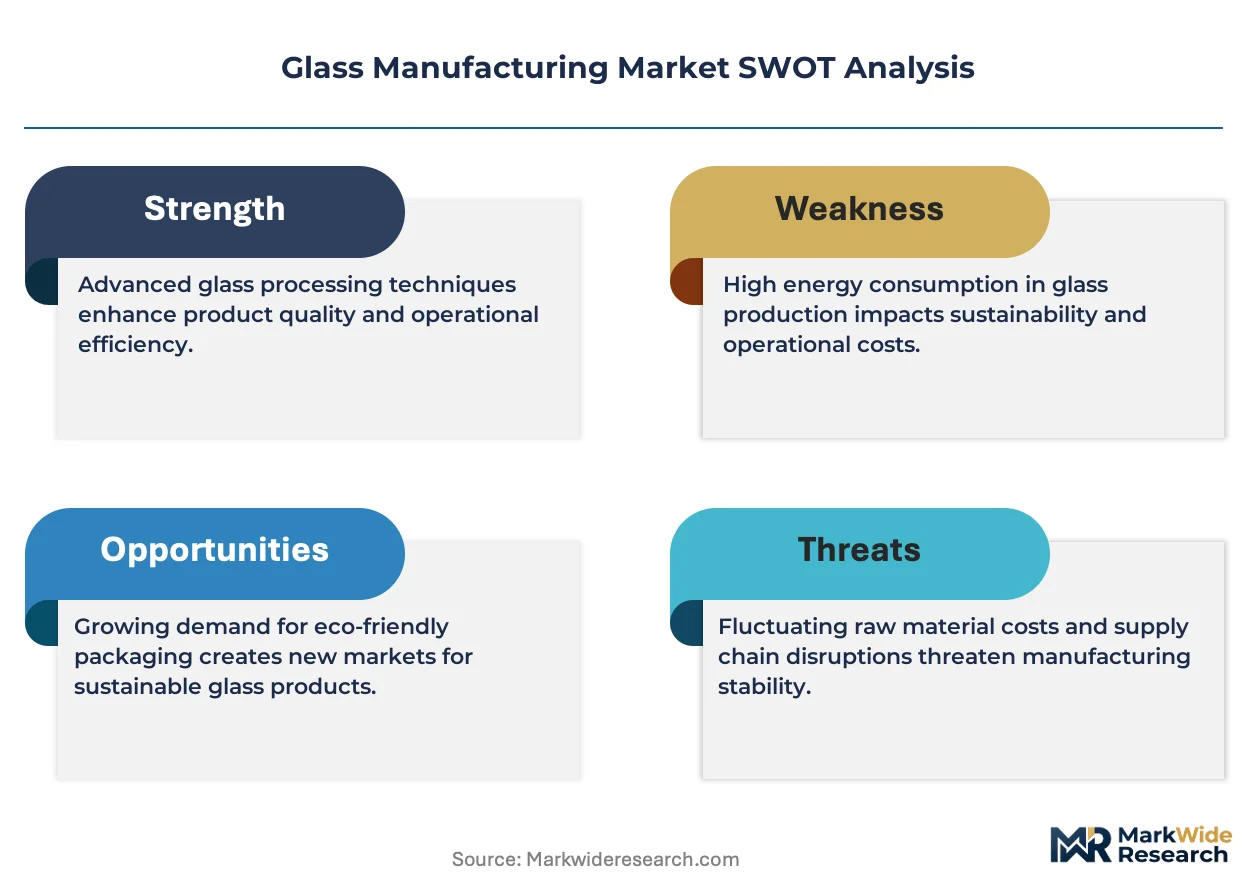
Modular glass panel systems is shifting procurement patterns across the construction industry. Saint-Gobain leverages its integrated flat-to-finished glass pipeline to capture specification-driven projects. Corning Incorporated anchors the specialty glass segment through fused silica substrates for semiconductor lithography. Guardian Glass competes on coated architectural products that meet stringent thermal codes.
Glass manufacturing encompasses the conversion of silica sand, soda ash, and limestone into amorphous solid structures through controlled melting at temperatures exceeding 1500°C, followed by forming via float, blowing, drawing, or pressing methods to achieve optical clarity, chemical durability, and mechanical strength for structural, protective, or functional applications. Flat glass commands the largest value pool as float process scale economies dominate volume production, while specialty glass generates the highest margins due to precision tolerances in electronics and medical optics. Container glass remains mature with recycling mandates sustaining circular feedstock requirements across beverage and pharmaceutical packaging.
The EPA enforces emissions limits on glass melting furnaces under the National Emission Standards for Hazardous Air Pollutants, compelling capital upgrades to oxy-fuel and electric boosting technologies. OSHA mandates silica exposure controls in raw material handling, elevating automation investments across batch plants. ISO 12543 certification for laminated safety glass shapes automotive and architectural market access. Stakeholders must weigh furnace fuel switching timelines against carbon border adjustment mechanisms before committing to regional capacity additions.
Market Dynamics
Flat glass capacity concentration in China is compressing regional pricing power while Europe's F-Gas Regulation forces furnace technology retrofits that reshape capital allocation timelines across integrated producers.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA fuel economy standards in the US and similar EU CO2 targets for vehicle fleets accelerate demand for thin laminated windshields and side glazing that cuts vehicle mass without sacrificing structural integrity.
- Solar panel manufacturing scale-up:Photovoltaic module assembly lines in China, India, and Southeast Asia consume tempered solar glass at volumes that outpace traditional architectural offtake, pulling float glass capacity toward dedicated solar specifications.
- Oxy-fuel furnace conversion:The EPA's National Emission Standards for Hazardous Air Pollutants drives glassmakers to replace air-fuel combustion with oxygen-enriched systems that cut NOx emissions and improve thermal efficiency in melting operations.
Market Restraints
- Silica sand supply concentration:High-purity silica deposits suitable for optical and specialty glass concentrate in limited geographies, exposing batch plants to logistics bottlenecks and quality variance.
- Natural gas price volatility:Melting furnaces remain dependent on natural gas as primary fuel, and input cost spikes compress margins faster than pass-through mechanisms adjust in contract pricing.
- Polymer glazing substitution:Polycarbonate and advanced polymer composites penetrate automotive rear windows and sunroof applications where weight reduction outweighs optical clarity requirements.
Strategic Opportunities
- Electronics substrate demand:Fused silica and borosilicate glass for semiconductor lithography masks and display substrates offer margin expansion as chip fabrication nodes shrink below 3nm.
- India building code modernization:BIS adoption of laminated safety glass standards for high-rise construction creates specification-driven demand as urban verticalization accelerates in Mumbai, Delhi, and Bangalore.
- Digital printing on glass:Ceramic inkjet decoration technology enables mass customization of facade panels, allowing fabricators to capture premium architectural projects without dedicated screen printing lines.
Industry Challenges
- Furnace rebuild cycle compression:Campaign life extension beyond 15 years requires advanced refractory materials and predictive maintenance systems that strain technical staffing and capital reserves.
- ISO 12543 certification timelines:Laminated safety glass qualification for automotive OEM supply involves 18-24 month testing protocols that delay market entry for new production lines.
- Silica exposure compliance:OSHA permissible exposure limits for respirable crystalline silica mandate automated batch handling systems that disrupt legacy plant layouts and require significant floor space reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Manufacturing Market |
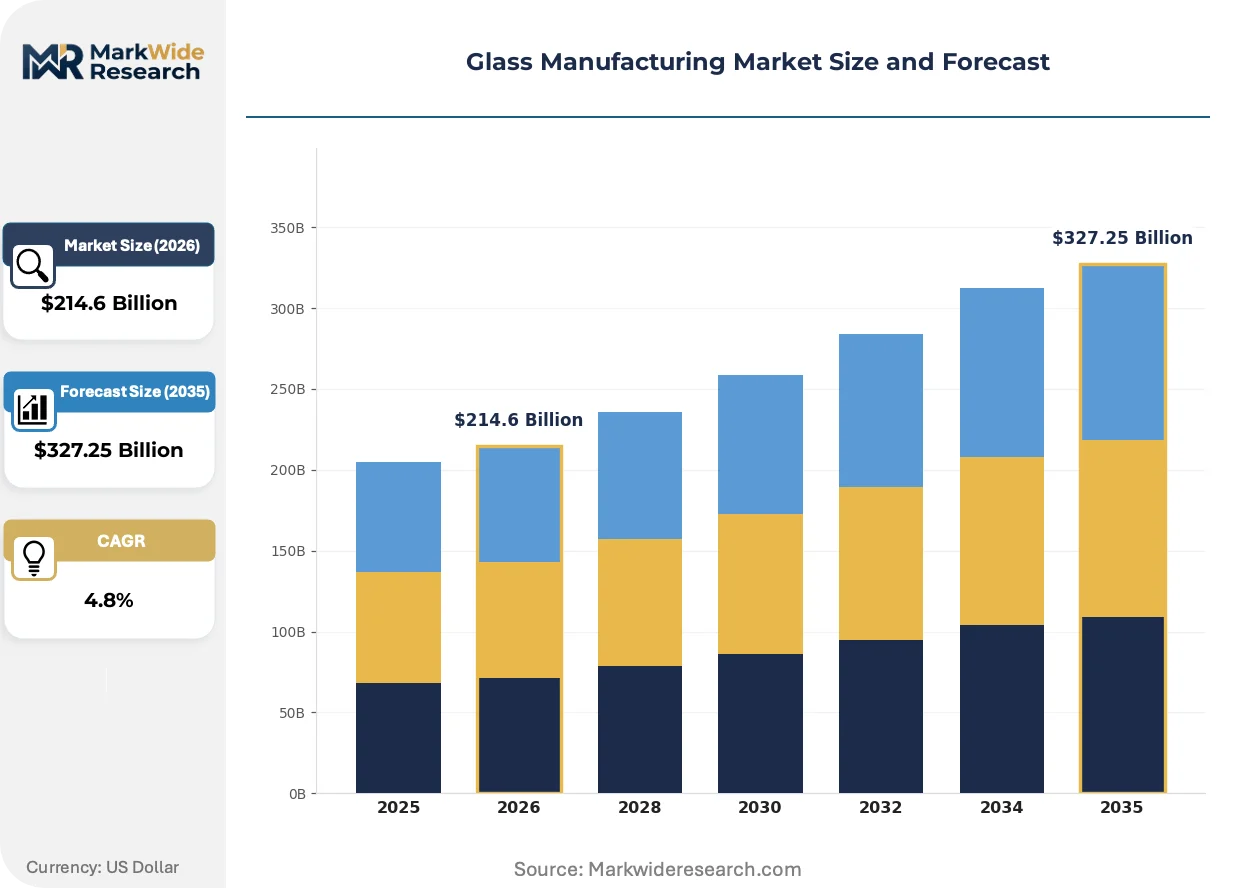
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $327.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Glass, Container Glass, Specialty Glass, Fiberglass End User: Automotive Sector, Construction Industry, Packaging Sector, Electronics Sector Manufacturing Stage: Raw Material Processing, Glass Melting, Forming, Surface Treatment Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Saint-Gobain, Corning Incorporated, AGC Inc., Schott AG, Nippon Electric Glass Co., Ltd., Guardian Glass LLC, Nippon Sheet Glass Co., Ltd., Fuyao Glass Industry Group Co Ltd, Şişecam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Manufacturing Market Emerging Trajectories
Electrification of melting technology and digital process control are converging to decarbonize production while enabling precision forming for next-generation applications.
Electro-boosting and full-electric melting systems are overtaking conventional fossil-fuel furnaces in new European capacity investments. Container glass producers in Germany and France pilot 100% electric furnaces powered by renewable grid connections. This transition compresses carbon intensity metrics for export-bound products facing EU carbon border adjustment mechanisms.
Europe's F-Gas Regulation tightens thermal performance requirements for insulating glass units used in commercial facades and residential windows. Manufacturers must reformulate low-emissivity coatings and gas fills to meet declining U-value thresholds. Architectural specification teams in France, Germany, and the Netherlands now exclude non-compliant systems from tender shortlists.
Direct procurement relationships between solar module assemblers and glass fabricators are displacing traditional merchant distribution channels. Long-term offtake agreements with volume commitments and technical co-development clauses lock capacity years ahead of production. This pattern concentrates most visibly in China where integrated photovoltaic giants secure dedicated float lines through equity partnerships.
Glass Manufacturing Market Segmentation
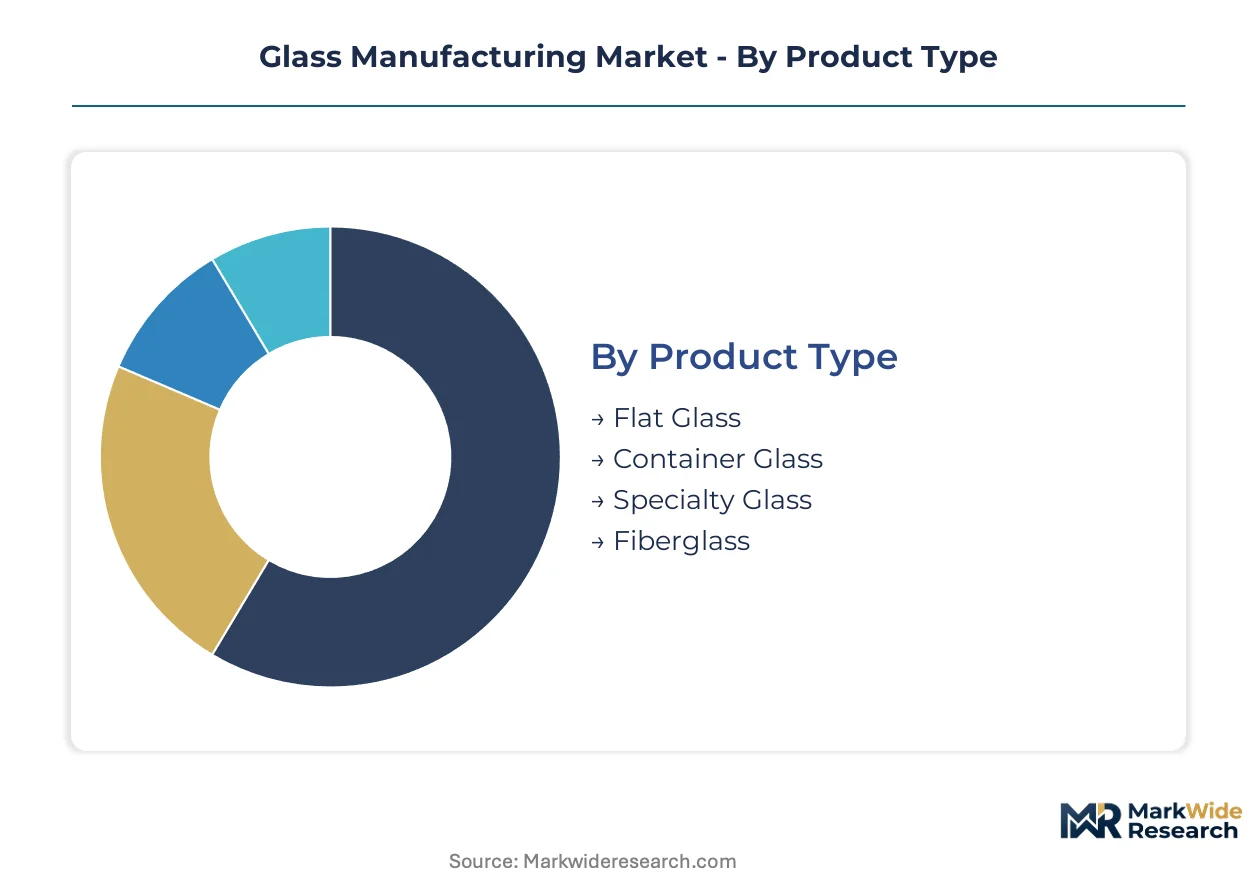
Glass manufacturing segmentation reveals divergent margin profiles across product categories, with commodity volume production competing against precision-engineered specialty grades. End-use fragmentation demands distinct technical specifications, furnace configurations, and certification protocols that reshape capital allocation priorities.
Product Type:
Volume concentration favors float-process flat glass, while premium capture concentrates in specialty formulations demanding tighter tolerances.
- Flat Glass:Float process production dominates architectural glazing and automotive windshields, leveraging continuous ribbon forming at 1100°C for optical uniformity. Demand concentrates in China where solar panel manufacturers pull capacity toward dedicated tempered specifications for photovoltaic modules.
- Specialty Glass:Borosilicate and fused silica formulations serve semiconductor lithography masks and display substrates with coefficient-of-expansion tolerances below 5×10⁻⁷/°C. Electronics fabricators in Taiwan and South Korea drive specification escalation as chip nodes shrink below 3nm.
- Container Glass:Soda-lime compositions for beverage and pharmaceutical packaging operate under mandated recycling feedstock quotas across EU member states.
- Fiberglass:E-glass and S-glass rovings reinforce wind turbine blades and automotive composites, with length-weighted demand clustering in Texas and Jilin province manufacturing corridors.
Mature deployment sits with container glass. Newer deployment is concentrated in specialty glass.
End User:
Automotive lightweighting mandates and building code modernization are redrawing demand concentration across customer categories.
- Automotive Sector:OEMs specify thin laminated windshields and acoustic interlayers to meet NHTSA fleet economy standards and EU CO₂ reduction targets. Side glazing applications face polycarbonate substitution pressure in rear window and sunroof segments.
- Construction Industry:Commercial facade specifications now exclude non-compliant insulating glass units under Europe's F-Gas Regulation tightening U-value thresholds. Modular panel systems are shifting procurement toward direct fabricator relationships.
- Packaging Sector:Beverage brands and pharmaceutical manufacturers face circular economy mandates requiring post-consumer recycled content minimums.
- Electronics Sector:Display substrate and semiconductor mask blank demand generates the steepest expansion trajectory as wafer fabrication capacity scales.
Specification-driven procurement dominates automotive. Volume contracting characterizes packaging.
Manufacturing Stage:
Regulatory pressure on emissions and silica exposure is forcing capital reallocation toward melting and surface treatment capabilities.
- Glass Melting:Oxy-fuel and electric boosting retrofits respond to EPA National Emission Standards for Hazardous Air Pollutants and EU carbon border adjustment exposure. Furnace rebuild cycles compress as campaign life extension demands advanced refractory materials.
- Surface Treatment:Low-emissivity sputter coating and ceramic inkjet decoration enable mass customization of architectural panels without dedicated screen printing infrastructure.
- Raw Material Processing:Automated batch handling systems address OSHA permissible exposure limits for respirable crystalline silica, disrupting legacy plant layouts.
- Forming:Float, blowing, drawing, and pressing methods align with end-use optical and mechanical requirements.
Environmental compliance investment clusters in melting. Precision capability expansion targets surface treatment.
Distribution Channel:
Solar module assemblers are displacing traditional merchant channels through direct procurement relationships with volume commitments.
- Direct Sales:Long-term offtake agreements with technical co-development clauses lock float glass capacity years ahead of production, concentrated in China-integrated photovoltaic partnerships.
- Distributors:Regional inventory positioning serves fragmented construction and automotive aftermarket demand with specification support.
- Online Sales:Digital platforms capture replacement windshield and architectural retrofit orders with configuration tools for laminated safety glass options.
- Retailers:Big-box and specialty outlets serve consumer DIY glazing and decorative glass applications.
Contractual volume flows through direct sales. Speculative inventory sits with distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces over half of global flat glass output yet consumes an even larger share through solar panel manufacturing and construction. Germany and the United States maintain specialized capacity in automotive and architectural coatings. India and Japan concentrate on electronics substrates and container glass respectively.
China
Photovoltaic module assembly lines in Anhui and Jiangsu provinces pull float glass capacity toward dedicated solar specifications. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate furnace electrification pilots. Integrated photovoltaic giants in Changzhou and Hefei secure dedicated float lines through equity partnerships with fabricators.
Germany
Container glass producers in Bavaria and North Rhine-Westphalia pilot 100% electric furnaces powered by renewable grid connections. The F-Gas Regulation tightens thermal performance requirements for insulating glass units used in commercial facades. Stuttgart and Munich anchor automotive glazing specification teams that exclude non-compliant systems from OEM tender shortlists.
United States
NHTSA fuel economy standards accelerate demand for thin laminated windshields from Detroit-area automotive suppliers. The EPA enforces emissions limits on glass melting furnaces under the National Emission Standards for Hazardous Air Pollutants. Toledo, Ohio and Carlisle, Pennsylvania concentrate architectural coating capacity serving commercial facade projects.
India
Bureau of Indian Standards adoption of laminated safety glass standards for high-rise construction creates specification-driven demand in Mumbai and Delhi. The PLI scheme incentivizes domestic solar glass manufacturing capacity. Gujarat and Maharashtra host emerging float lines targeting photovoltaic module assembly for export markets.
Japan
Display substrate demand from semiconductor fabricators in Kyushu and Chubu drives borosilicate and fused silica specification escalation. METI coordinates supply chain resilience initiatives for critical electronics materials. Osaka and Nagoya anchor precision glass machining clusters serving lithography mask blank production.
Glass Manufacturing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value pools in glass manufacturing. The market structure consolidates around integrated producers commanding float process scale economies while fragmenting across specialty niches demanding precision tolerances. Three archetypes dominate: capital-intensive flat glass integrators, technology-driven specialty formulators, and regionally anchored container specialists. Competitive moves concentrate on oxy-fuel furnace retrofits for emissions compliance and direct procurement relationships displacing traditional distribution channels.
Among diversified European-based producers, Saint-Gobain and Schott AG exemplify contrasting strategic positions within the competitive landscape. Saint-Gobain represents the integrated flat-to-finished pipeline archetype, while Schott AG occupies a specialist position in high-performance materials. Corning Incorporated anchors the North American specialty glass segment through its fused silica substrate capabilities. These three companies collectively illustrate how geographic origin and organizational structure map to distinct competitive vectors in global glass manufacturing.
| Leading Market Players |
|---|
| Saint-Gobain |
| Corning Incorporated |
| AGC Inc. |
| Schott AG |
| Nippon Electric Glass Co., Ltd. |
| Guardian Glass LLC |
| Nippon Sheet Glass Co., Ltd. |
| Fuyao Glass Industry Group Co Ltd |
| Şişecam |
| Others |
Supply Flow & Price Mechanics
Automotive OEM consolidation around thin laminated windshield specifications is compressing supplier margins and forcing float glass producers to absorb coating technology investments without full price recovery.
Pricing Analysis
Margin tightening in architectural flat glass reflects China's solar panel manufacturers locking capacity through long-term offtake agreements with fixed-price clauses. Three-tier pricing structure across premium, standard, and economy levels separates ISO 12543-certified automotive grades from merchant architectural stock. Price differentiation hinges on thermal performance certification under Europe's F-Gas Regulation and volume scale in direct procurement relationships. Packaging sector buyers exhibit highest price sensitivity due to mandated recycled content quotas that elevate feedstock costs.
Supply Chain Analysis
Skilled furnace operations talent scarcity in Germany and the United States is extending oxy-fuel retrofit timelines and inflating project labor premiums. Supply concentrates in China, Germany, and the United States for float-process flat glass, while specialty fused silica production anchors in Japan and Taiwan. Raw material flows draw from high-purity silica deposits in Wisconsin and Shanxi province, soda ash from Wyoming and Inner Mongolia, and limestone from regional quarries. Single-source vulnerability sits with China's dominance of solar-grade tempered glass capacity. Distribution runs through direct sales channels for photovoltaic module assemblers and regional distributors for construction aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass manufacturing is consolidating around emissions-compliant capacity as EPA enforcement and EU carbon border mechanisms strand legacy air-fuel furnace assets.
For Market Incumbents: Cement market position by accelerating oxy-fuel and electric boosting retrofits ahead of regulatory deadlines, locking in automotive OEM supply relationships before ISO 12543 certification timelines delay competitor entry. Prioritize backward integration into high-purity silica sourcing to defend against supply concentration in limited geographies.
For New Entrants and Emerging Players: Solar module assemblers represent the most penetrable channel partner type for new float capacity, given their displacement of traditional merchant distribution through direct procurement relationships. Target India's PLI-incentivized domestic solar glass manufacturing corridor in Gujarat and Maharashtra. Pursue technical co-development clauses in long-term offtake agreements to secure foundational volume.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty glass formulators given semiconductor lithography mask demand escalation as chip nodes shrink below 3nm. Long-term viability favors precision-tolerance capabilities over commodity float exposure. Watch for furnace electrification pilot success in Germany as inflection indicator for stranded asset risk in fossil-fuel dependent capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | EPA National Emission Standards compliance preserves market access for US-based melting capacity. |
| Direct Procurement Partnership | Long-term offtake agreements with Chinese photovoltaic giants lock float capacity years ahead of production. |
| Electric Melting Pilot | Container glass producers in Germany and France compress carbon intensity for EU carbon border adjustment exposure. |
| Specialty Glass Capacity Addition | Fused silica substrate production captures margin expansion from Taiwan and South Korea semiconductor fabricators. |
| Automotive Certification Investment | ISO 12543 qualification opens OEM supply relationships with 18-24 month competitive moats. |
Methodological Framework
Trade statistics from national customs authorities, SEC 10-K filings from publicly traded glass manufacturers, and industry association production surveys formed the secondary backbone of this analysis. Primary interviews with float glass plant managers, automotive OEM glazing procurement leads, solar module assembler supply chain directors, and architectural specification consultants validated volume and pricing assumptions. Bottom-up capacity modeling and top-down demand segmentation triangulated market size estimates across product categories.
Bottom-up modeling of furnace-level production capacity and top-down consumption analysis by end-use sector converged on volume projections across the analysis window. Segmentation dimensions included product type, manufacturing stage, end-user industry, and regional production hub. CAGRs were derived from regression analysis of historical production trends against regulatory phase-in schedules and technology substitution curves. Key inputs incorporated natural gas price volatility scenarios and solar panel manufacturing capacity build-out trajectories.
Caveats apply where furnace fuel switching timelines, silica sand logistics disruptions, or polymer glazing substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Pharmaceutical Glass Tubing Market
Glass
Global Vitrification Market
Glass
Insulating Glass Market
Glass
Glass Tableware Market
Glass
Europe Flat Glass Market
Glass
Coated Solar Control Glass Market
Glass
Coated Glass Market
Glass
North America and Australia Silica Market
Glass
Glass Like Carbon Market
Glass
Asia-Pacific Silica Sand Market
Glass
Paper Glass Maker Market
Glass
Low-E Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Solar Control Glass Market
Glass
Spherical Silica Market
Glass
India Flat Glass Market