
 Metallic Glass Market | 2026-2036
Metallic Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Glass Market Intelligence
Specialized metallurgist and materials science talent is collapsing across advanced alloy foundries, constraining batch consistency and scale-up velocity for amorphous metal production. Hitachi Metals Ltd. leverages its integrated R&D-to-production footprint across Japanese industrial corridors to sustain premium ribbon output for transformer cores. Materion Corporation anchors North American supply through controlled specialty compositions serving aerospace and defense specifications. Liquidmetal Technologies Inc. competes in injection-molded amorphous alloys for consumer electronics enclosures, differentiating through near-net-shape capability.
Metallic glass denotes a non-crystalline solid metal alloy, typically formed from zirconium, titanium, or iron-based systems with critical cooling rates exceeding one million Kelvin per second to suppress nucleation. Its absence of grain boundaries yields tensile strengths reaching two gigapascals and exceptional elastic strain limits, positioning it for precision springs, surgical instruments, and corrosion-resistant coatings. Bulk metallic glass commands the highest value per kilogram among product categories, though ribbon metallic glass dominates volume through electrical transformer lamination demand. Powder metallic glass represents the fastest-expanding format, driven by additive manufacturing adoption among aerospace fabricators and medical device companies seeking complex geometries.
FDA device classification rules and EU MDR biocompatibility requirements shape metallic glass adoption in surgical and implantable applications, while REACH chemical restrictions govern alloying element selection across European supply chains. China's SAMR enforces GB standards on transformer efficiency that directly reference amorphous core materials, accelerating domestic procurement. Japan's METI coordinates national R&D consortia advancing rapid solidification techniques. Stakeholders must monitor evolving rare earth element export controls and alloy composition patent cliffs, as these determine feedstock access and freedom-to-operate across key manufacturing jurisdictions.
Market Dynamics
The metallic glass market pivots on a severe metallurgical talent shortage that constrains batch-to-batch consistency and throttles scale-up velocity across advanced alloy foundries. This structural chokepoint shapes competitive positioning more than raw material costs or patent portfolios.
Growth Catalysts
- Transformer efficiency mandates:China's SAMR enforces GB standards on amorphous core materials, accelerating domestic procurement for grid infrastructure.
- Additive manufacturing adoption:Powder metallic glass is reshaping aerospace fabrication workflows, enabling complex turbine geometries previously unattainable through conventional casting.
- Surgical instrumentation demand:FDA device classification pathways for biocompatible alloys are streamlining market entry for precision medical tools in North American hospital systems.
Market Restraints
- Critical cooling rate requirements:Processing zirconium-based systems demands cooling rates exceeding one million Kelvin per second, limiting viable production geometries and yield economics.
- Rare earth element concentration:Feedstock access concentrates in Chinese export-controlled supply chains, exposing non-domestic fabricators to quota volatility and price spikes.
- Crystalline alloy substitution:High-performance titanium aluminides and nickel superalloys retain cost advantages for turbine applications where metallic glass properties are non-critical.
Strategic Opportunities
- Underpenetrated defense electronics:South Korea's precision component fabricators are expanding amorphous alloy procurement for electromagnetic shielding in satellite systems.
- Bioresorbable implant convergence:The intersection of metallic glass with magnesium-based bioresorbable platforms opens orthopedic fixation applications beyond permanent hardware.
- Japan's METI R&D coordination:National consortia advancing rapid solidification techniques offer technology licensing pathways for foreign entrants seeking process IP.
Industry Challenges
- Specialized foundry talent scarcity:The collapse of academic metallurgy programs has thinned the pipeline for amorphous alloy process engineers, extending qualification timelines for new production lines.
- EU MDR certification complexity:Biocompatibility testing protocols for implantable metallic glass devices now require extended clinical follow-up periods, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Glass Market |
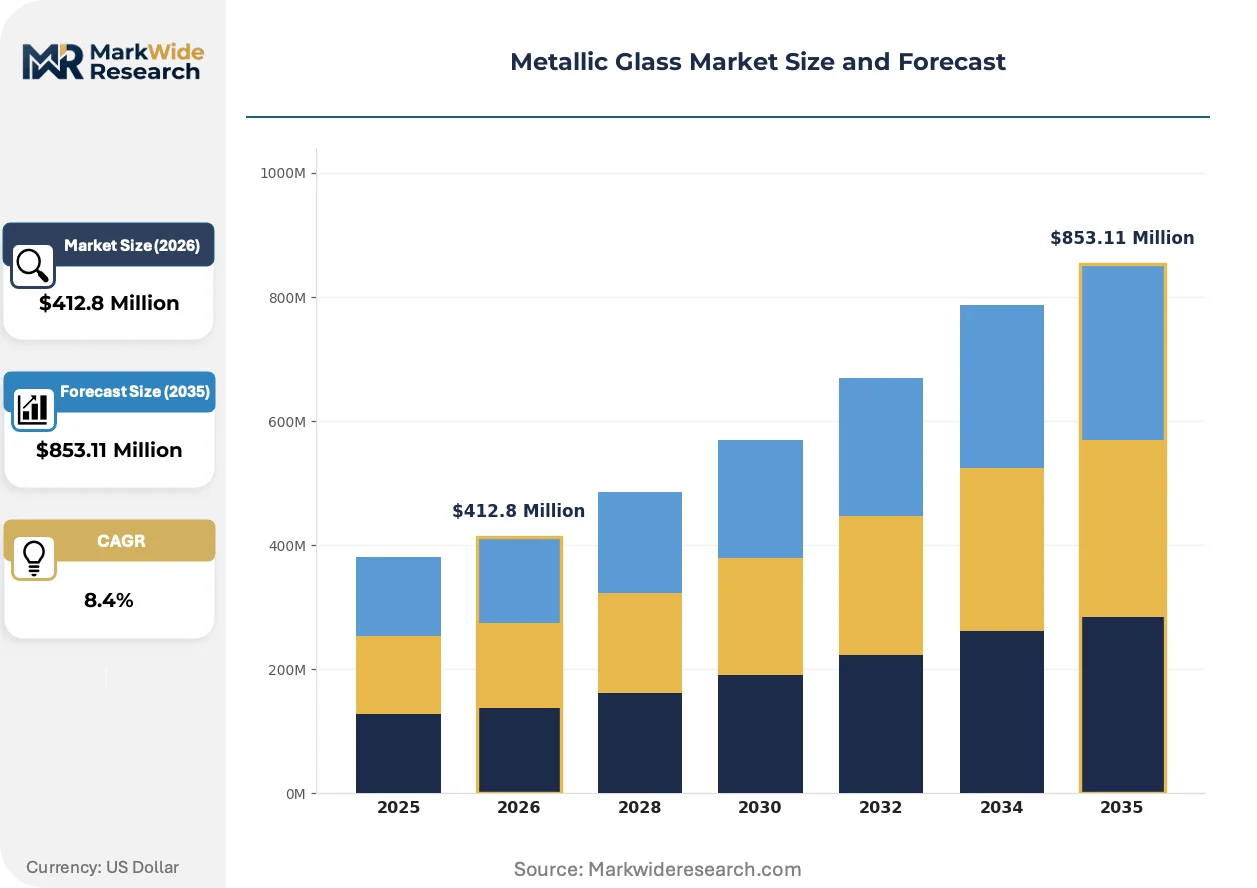
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $853.11 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Metallic Glass, Ribbon Metallic Glass, Powder Metallic Glass, Coated Metallic Glass Technology: Rapid Solidification, Physical Vapor Deposition, Sputtering, Laser Melting Application: Sports Equipment, Electronics Enclosures, Aerospace Components, Jewelry Manufacturing End User: Consumer Goods Manufacturers, Aerospace Fabricators, Electronics Producers, Medical Device Companies |
| Companies Covered | Hitachi Metals Ltd., Materion Corporation, Heraeus Holding GmbH, Liquidmetal Technologies Inc., Usha Amorphous Metals Limited, Metglas Inc., Antai Technology Co., Ltd., EPSON ATMIX Corporation, Exmet AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Glass Market Strategic Shifts & Innovations
Processing technology and regulatory frameworks are actively restructuring how metallic glass moves from laboratory formulations to industrial-scale deployment. Three distinct vectors dominate this transformation.
Additive manufacturing of powder metallic glass is supplanting conventional investment casting for aerospace turbine vanes and medical device enclosures. GE Aviation and precision orthopedic fabricators in Japan are accelerating adoption timelines from prototype to production qualification. This technology is compressing lead times for complex geometries while reducing material waste rates inherent to subtractive machining of bulk amorphous billets.
REACH chemical restrictions across European supply chains are constraining alloying element selection for zirconium and titanium-based systems. ECHA substance evaluations now require extended toxicity documentation for novel amorphous compositions, extending formulation-to-market cycles by 18-24 months. Medical device manufacturers serving EU markets are responding by pre-certifying alternative iron-based glassy alloys with established safety profiles.
Buyer consolidation among East Asian electronics assemblers is concentrating procurement leverage for amorphous ribbon transformer cores. Tier-one suppliers in Japan and South Korea now specify multi-year volume commitments with embedded price adjustment mechanisms, displacing spot-market purchasing. This pattern is most visible in precision electronics clusters around Osaka and Suwon, where transformer lamination demand anchors regional metallic glass consumption.
Metallic Glass Market Segmentation
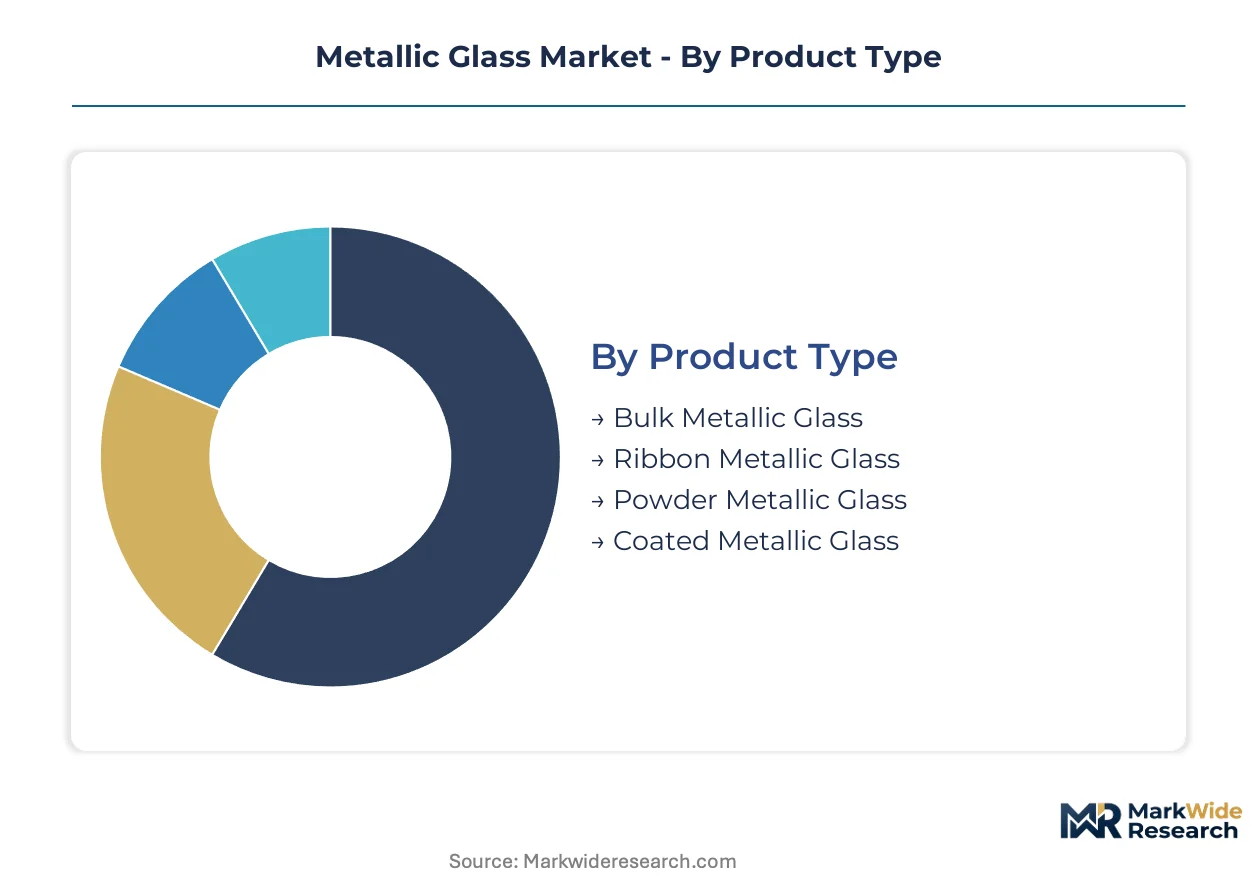
Metallic glass segmentation reveals how cooling rate thresholds and processing economics partition value capture across industrial applications. Regulatory frameworks governing transformer efficiency, biocompatibility, and aerospace certification reshape demand concentration within each category.
Product Type:
Regulatory differentiation separates volume-driven electrical applications from premium structural uses. China's SAMR GB standards on transformer efficiency directly reference amorphous core materials, privileging formats compatible with lamination geometries.
- Ribbon Metallic Glass:Continuous cast strips of iron-based amorphous alloys, typically 20-50 micrometers thick, produced through melt spinning at cooling rates exceeding one million Kelvin per second. Grid infrastructure procurement in China and Japan concentrates demand for distribution transformer cores. Established volume favors ribbon metallic glass; emerging adoption favors powder metallic glass.
- Powder Metallic Glass:Atomized spherical particles enabling additive manufacturing of complex geometries previously unattainable through conventional casting. Aerospace fabricators in Japan and medical device producers in South Korea are accelerating qualification timelines for turbine vanes and orthopedic enclosures. Expanding most quickly among product formats.
- Bulk Metallic Glass:Centimeter-scale amorphous billets formed through copper mold casting of zirconium or palladium-based systems with reduced critical cooling rates. Jewelry manufacturers and precision instrument fabricators value its mirror-like surface finish and elastic strain capacity.
- Coated Metallic Glass:Sputtered or plasma-sprayed amorphous layers providing corrosion resistance and wear protection onto crystalline substrates. Oilfield equipment and chemical processing infrastructure in the US Gulf Coast represent primary demand concentration.
Cost tier separation distinguishes commodity transformer ribbon from specialty bulk and powder formats commanding premium valuations.
Technology:
Application requirements dictate process selection, with aerospace and medical segments driving precision-oriented methods over high-throughput approaches.
- Rapid Solidification:Melt spinning and planar flow casting dominate ribbon production for electrical applications. Japanese industrial corridors host the most concentrated installed base of production lines.
- Laser Melting:Selective laser sintering of pre-alloyed powders enables near-net-shape fabrication of topology-optimized components. GE Aviation and Japanese orthopedic device producers are advancing process qualification for flight-critical and implantable applications.
- Physical Vapor Deposition:Evaporation-based thin film deposition creates sub-micrometer amorphous coatings for electronics shielding and optical applications. South Korean precision component fabricators leverage this for satellite electromagnetic protection.
- Sputtering:Ion bombardment of targets produces conformal amorphous coatings on complex substrate geometries. Medical device manufacturers favor this for biocompatible surface modifications meeting FDA and EU MDR requirements.
Volume maturity favors rapid solidification; technology licensing activity favors laser melting.
Application:
End-use certification requirements fragment addressable markets, with medical and aerospace applications demanding extended qualification timelines compared to consumer goods.
- Aerospace Components:Turbine vanes, structural brackets, and fasteners exploiting high specific strength and fatigue resistance. Powder metallic glass additive manufacturing is displacing investment casting for complex geometries in Japanese and US supply chains.
- Electronics Enclosures:Injection-molded amorphous alloy housings for smartphones, wearables, and precision instruments. Liquidmetal Technologies and East Asian molders compete on near-net-shape capability and surface finish quality.
- Sports Equipment:Golf club heads, tennis racket inserts, and bicycle components leveraging elastic energy storage. Premium positioning depends on brand association rather than performance differentiation.
- Jewelry Manufacturing:Bulk metallic glass rings and watch cases exploiting scratch resistance and distinctive luster. Swiss and Japanese luxury goods houses anchor niche demand.
Margin concentration favors aerospace components; customer acquisition cost efficiency favors electronics enclosures.
End User:
Procurement sophistication varies dramatically, with medical and aerospace buyers imposing stringent quality systems compared to consumer goods manufacturers.
- Electronics Producers:Transformer manufacturers and device assemblers in Japan, South Korea, and China drive ribbon and molded component demand. Multi-year volume commitments with price adjustment mechanisms now predominate over spot purchasing.
- Medical Device Companies:Orthopedic and surgical instrument fabricators requiring biocompatibility documentation under FDA and EU MDR frameworks. Extended clinical follow-up periods compress product launch windows.
- Aerospace Fabricators:Tier-one suppliers and OEMs qualifying powder metallic glass for turbine and structural applications. GE Aviation and Japanese precision manufacturers lead adoption timelines.
- Consumer Goods Manufacturers:Sporting goods and jewelry producers with lower technical barriers to entry and price-sensitive procurement. Supply relationships emphasize logistics reliability over metallurgical collaboration.
Supply concentration favors electronics producers; specification influence favors aerospace fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards on transformer efficiency anchor demand concentration in China, while METI-coordinated R&D consortia and FDA device pathways shape competitive positioning across Japan and North American hospital systems respectively.
China
Dual carbon goals and distribution grid upgrades drive amorphous core procurement for transformer infrastructure. SAMR enforces GB standards that directly reference metallic glass materials, accelerating domestic ribbon consumption. Manufacturing clusters in Jiangsu and Zhejiang provinces host concentrated melt-spinning capacity serving state grid procurement.
Japan
Precision electronics fabricators and orthopedic device producers anchor powder and bulk metallic glass demand. METI coordinates national R&D consortia advancing rapid solidification techniques for aerospace qualification. Industrial corridors around Osaka and Nagoya concentrate transformer lamination and medical instrument production.
United States
FDA device classification pathways streamline biocompatible alloy entry for surgical instrumentation in hospital systems. Aerospace fabricators qualify powder metallic glass for turbine applications through FAA-coordinated certification frameworks. Greater Boston and Pacific Northwest clusters concentrate medical device and defense electronics prototyping.
South Korea
Satellite electromagnetic shielding applications expand amorphous alloy procurement among precision component fabricators. MFDS biocompatibility requirements shape medical device adoption timelines for implantable hardware. Suwon and Seoul Capital Area electronics assemblers specify multi-year volume commitments for transformer cores.
Germany
ECHA REACH restrictions constrain zirconium and titanium-based alloying element selection for European supply chains. Industrial machinery producers evaluate coated metallic glass for corrosion-resistant oilfield components. Ruhr industrial region and Baden-Württemberg precision engineering clusters pilot additive manufacturing qualification.
Metallic Glass Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding process IP and captive raw material access while the lower tier competes on format-specific geometries and regional logistics. Three archetypes dominate: diversified materials conglomerates with backward integration into rare earth feedstocks, precision metals specialists focused on single-format mastery, and additive manufacturing enablers bridging powder supply to aerospace qualification. Competitive moves concentrate on technology licensing from Japanese R&D consortia and multi-year procurement contracting with East Asian electronics assemblers.
Within the integrated materials tier, Hitachi Metals Ltd. and Materion Corporation exemplify archetypes spanning R&D-to-production footprints and controlled specialty compositions respectively. Liquidmetal Technologies Inc. occupies a distinct position among injection-molding specialists competing on near-net-shape capability for consumer electronics enclosures.
| Leading Market Players |
|---|
| Hitachi Metals Ltd. |
| Materion Corporation |
| Heraeus Holding GmbH |
| Liquidmetal Technologies Inc. |
| Usha Amorphous Metals Limited |
| Metglas Inc. |
| Antai Technology Co., Ltd. |
| EPSON ATMIX Corporation |
| Exmet AB |
| Others |
Cost & Logistics Intelligence
China's SAMR GB standards on transformer efficiency gate both supplier qualification and price differentiation simultaneously, compressing margins for non-certified ribbon producers while rewarding integrated foundries with captive rare earth access. Buyers in East Asian electronics clusters now bundle multi-year offtake commitments with technical collaboration requirements, reshaping how pricing power distributes across the value chain.
Pricing Analysis
Long-term offtake contracts dominate procurement for amorphous ribbon transformer cores, with Japanese and South Korean electronics assemblers embedding volume-price adjustment mechanisms that extend three to five years. Price differentiation separates aerospace-grade powder certified for FAA turbine applications from commodity ribbon serving grid infrastructure, with certification tier and volume scale as the primary drivers. Cost compression in standard-grade ribbon is intensifying because Chinese state grid procurement favors domestic suppliers with backward integration into rare earth feedstocks. Consumer goods manufacturers exhibit the highest price sensitivity, while aerospace fabricators prioritize qualification reliability over unit cost.
Supply Chain Analysis
China and Japan anchor metallic glass supply, with Jiangsu and Zhejiang provinces hosting concentrated melt-spinning capacity for transformer ribbon while Osaka and Nagoya industrial corridors specialize in powder and bulk formats for precision applications. Feedstock draws from Chinese export-controlled rare earth supply chains, particularly neodymium and dysprosium for high-performance magnetic alloys. Single-source vulnerability concentrates in zirconium sponge processing, where non-domestic fabricators face quota volatility from Chinese export licensing. Distribution runs through direct mill relationships for high-volume electrical applications and specialized distributors for aerospace and medical qualified materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are expanding as additive manufacturing adoption splinters demand across format-specific niches, creating entry points for specialists unburdened by legacy ribbon infrastructure.
For Market Incumbents: Shield process IP advantages in rapid solidification by accelerating technology licensing from METI-coordinated R&D consortia before patent cliffs erode exclusivity. Deepen backward integration into rare earth feedstocks to offset Chinese export quota volatility threatening margin stability in standard-grade ribbon production. For New Entrants and Emerging Players: FDA breakthrough device designation for biocompatible surgical instruments offers the fastest certification pathway to bypass extended clinical follow-up periods compressing launch windows for permanent implants. Target South Korean precision component fabricators expanding amorphous alloy procurement for satellite electromagnetic shielding, where specification influence remains underdeveloped relative to Japanese supply chains. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across powder metallic glass additive manufacturing as aerospace qualification timelines compress and equipment utilization improves. Acquisition candidates with established laser melting process IP and existing relationships with GE Aviation or Japanese orthopedic device producers offer the strongest five-to-ten year viability. Monitor rare earth export licensing patterns from Chinese authorities as the primary inflection signal for feedstock cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing from METI Consortia | Accelerates foreign entrant access to rapid solidification IP without indigenous R&D investment. |
| Backward Integration into Rare Earth Feedstocks | Reduces exposure to Chinese SAMR export quotas governing neodymium and dysprosium access. |
| FDA Breakthrough Device Pathway Investment | Compresses biocompatibility certification timelines for surgical instrumentation in North American hospital systems. |
| Powder Format Capacity Expansion | Captures additive manufacturing adoption among aerospace fabricators qualifying turbine vanes. |
| Multi-Year Procurement Contracting | Locks in volume commitments with East Asian electronics assemblers specifying transformer lamination demand. |
Research Approach
A standing panel of melt-spinning process engineers, aerospace procurement specialists at Tier 1 suppliers, biomedical engineers at orthopedic device manufacturers, and transformer manufacturing plant managers provided ongoing calibration across primary fieldwork. Secondary validation drew from SAMR GB standard filings, METI R&D consortium disclosures, FDA 510(k) and PMA submissions for metallic glass devices, and customs trade data tracking rare earth alloy imports. Bottom-up volume estimates from individual production line capacities were triangulated against top-down demand aggregation from end-use sector procurement patterns.
Consistency checks validated volume and value outputs against external benchmarks including installed transformer base growth in China, aerospace additive manufacturing equipment shipments, and medical device regulatory filing trajectories. The analytical framework modeled product type, application, technology, and end-user segmentation across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from crystalline titanium aluminides and nickel superalloys. Industry-specific forecast inputs included critical cooling rate thresholds for viable production geometries and rare earth export quota allocation patterns.
Underlying assumptions cover sustained SAMR enforcement of transformer efficiency standards, stable rare earth export licensing from Chinese authorities, and continued FAA coordination on powder metallic glass aerospace qualification, with deviation risk concentrated in regulatory relaxation or feedstock trade restriction escalation. Recalibration cycles align with material shifts in GB standard revisions, patent cliff timing for rapid solidification IP, and breakthrough device designation approvals for biocompatible alloys.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Heat Resistant Glass Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Coated Solar Control Glass Market
Glass
Tempered Glass Market
Glass
Foam Glass Granulate Market
Glass
Asia-Pacific Flat Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Global Scratch Resistant Glass Market
Glass
Glass Lined Equipment Market
Glass
Glass Forming Machine Market
Glass
Glass Alternative Materials Market
Glass
Coated Glass Market
Glass
Cellular Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Glass Balustrade Lamination Market
Glass
Antibacterial Glass Market