
 Insulating Glass Market | 2026-2036
Insulating Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Insulating Glass Market Outlook
Buyer concentration among large-scale commercial developers is expanding as institutional investors consolidate portfolios across urban cores. Saint-Gobain leverages integrated float-glass-to-fabrication operations across multiple continents. Guardian Industries sustains dominance in coated glass technology for high-performance facades. Cardinal Glass Industries anchors North American supply through captive distribution networks serving regional window fabricators.
Insulating glass consists of two or more glass lites separated by a hermetically sealed air or gas-filled cavity, typically employing desiccant-filled spacers and dual-seal construction to achieve U-values below 1.0 W/m²K. This assembly reduces thermal conductivity and condensation risk in building envelopes, cutting HVAC loads by limiting heat transfer across opaque and transparent envelope sections. Low-E coatings command premium positioning as architects specify solar heat gain coefficients below 0.25 for commercial curtain walls. Triple glazed units represent the fastest-growing product category as passive house standards penetrate Nordic and Alpine construction markets. Residential application volume remains structurally mature in Western Europe, with margin pools shifting toward professional installation channels that bundle performance warranties.
EPA Energy Star certification and the EU Green Deal's building renovation requirements shape product specifications across both markets, forcing manufacturers to certify whole-window U-factors rather than center-of-glass values. Germany's KBA and France's ANSM do not regulate this sector; instead, the EEA and national building codes in Italy and Spain enforce CE-marked performance declarations. Stakeholders must monitor evolving carbon border adjustments and embodied-carbon disclosure rules that threaten import competitiveness for Asian-sourced float glass.
Market Dynamics
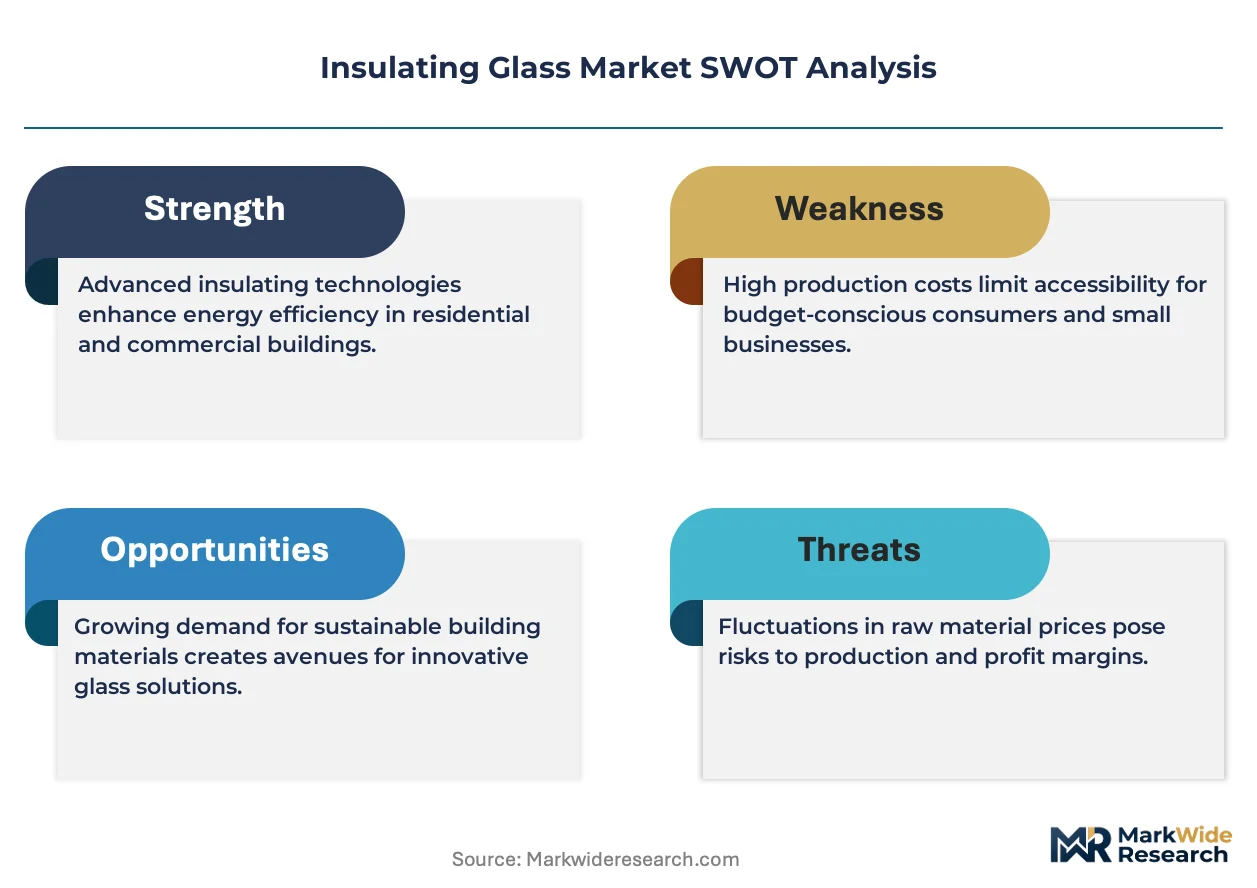
Energy code ratchets across Germany, the United States, and France are compressing allowable U-factors, forcing fabricators to retool toward triple-glazed and suspended-film assemblies. This regulatory acceleration is consolidating procurement power among institutional developers capable of certifying whole-system performance.
Growth Catalysts
- EU Green Deal renovation mandates:France, Italy, and Spain now require CE-marked performance declarations for facade retrofits, pulling replacement volume toward high-performance insulating glass units.
- Passive house construction:Nordic and Alpine markets specify triple-glazed assemblies with whole-window U-factors below 0.80 W/m²K, expanding the addressable premium product base.
- Commercial high-rise development:Urban core construction in Chicago, Toronto, and Frankfurt is specifying low-E coated curtain walls with solar heat gain coefficients below 0.25.
Market Restraints
- Float glass supply concentration:Asian-sourced soda-lime silica faces escalating carbon border adjustment exposure under EU CBAM implementation timelines.
- Argon and krypton gas cost volatility:Noble gas pricing fluctuations directly compress margin on gas-filled cavity units, particularly for triple-glazed configurations.
- Technical limitation of edge thermal bridging:Conventional aluminum spacer systems degrade center-of-glass performance gains, capping realizable whole-window U-factors.
Strategic Opportunities
- India existing building retrofit:Concentrated urban stock in Mumbai and Delhi offers untapped replacement demand as BIS energy efficiency codes tighten.
- Warm-edge spacer technology convergence:Thermoplastic hybrid spacers combining desiccant integration with improved psi-values enable premium positioning against conventional aluminum.
- Professional installation channel bundling:Performance warranty packaging through certified installer networks captures margin pools shifting from product-only sales.
Industry Challenges
- IGCC and NFRC certification timelines:Whole-window thermal performance testing creates months-long product qualification delays for new coating formulations.
- Dual-seal equipment capex intensity:Automated spacer application and gas-filling lines require substantial capital deployment for quality-compliant volume scale.
- Desiccant saturation control:Hermetic seal integrity depends on precise moisture vapor transmission rate management across fabrication environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulating Glass Market |
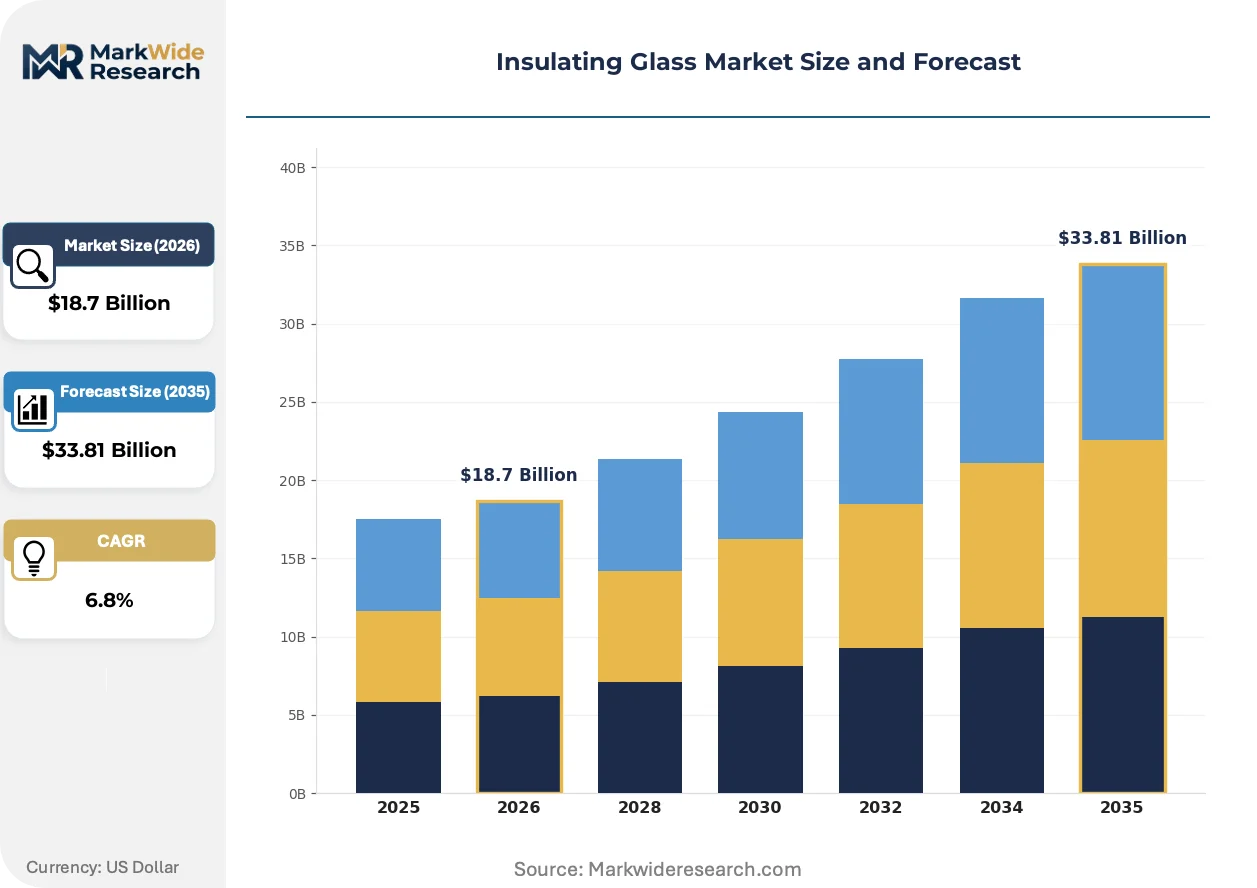
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Glazed, Triple Glazed, Low-E, Vacuums Application: Residential, Commercial, Automotive, Skylights Material: Aluminium, PVC, Wood, Composite Installation Type: New Construction, Retrofit, DIY, Professional |
| Companies Covered | Saint-Gobain, AGC Inc., Guardian Industries, NSG Group, Central Glass Co., Ltd., Nippon Sheet Glass Co., Ltd., Cardinal Glass Industries, Sika AG, Viracon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulating Glass Market Strategic Shifts
Vacuum insulating glass and suspended film technologies are compressing the performance gap between double and triple glazing without equivalent weight penalties. Fabrication automation and coating advances are simultaneously reducing unit cost curves.
Thin triple glazing with warm-edge spacers and low-E coatings is consolidating market share among mid-rise commercial developers seeking passive house performance without structural reinforcement. Architects in Germany and Austria specify these assemblies for retrofit projects where frame depth constraints prohibit conventional triple units. The technology is consolidating procurement specifications around whole-window U-factor certification rather than center-of-glass metrics.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in warm-edge spacer manufacturing, forcing suppliers toward CO₂-based physical foaming alternatives. This transition raises capital intensity for European fabricators while creating compliance differentiation against imported units. Nordic markets face the tightest phase-down schedules, accelerating local supply chain reconfiguration.
Institutional developers are consolidating direct procurement relationships with insulating glass fabricators, disintermediating traditional window manufacturer intermediaries. Large-scale commercial projects in Chicago and Toronto now specify glass performance requirements directly, sourcing fabrication through captive distributor networks. This channel compression concentrates volume among vertically integrated suppliers capable of float-to-fabrication traceability documentation.
Insulating Glass Market Segmentation
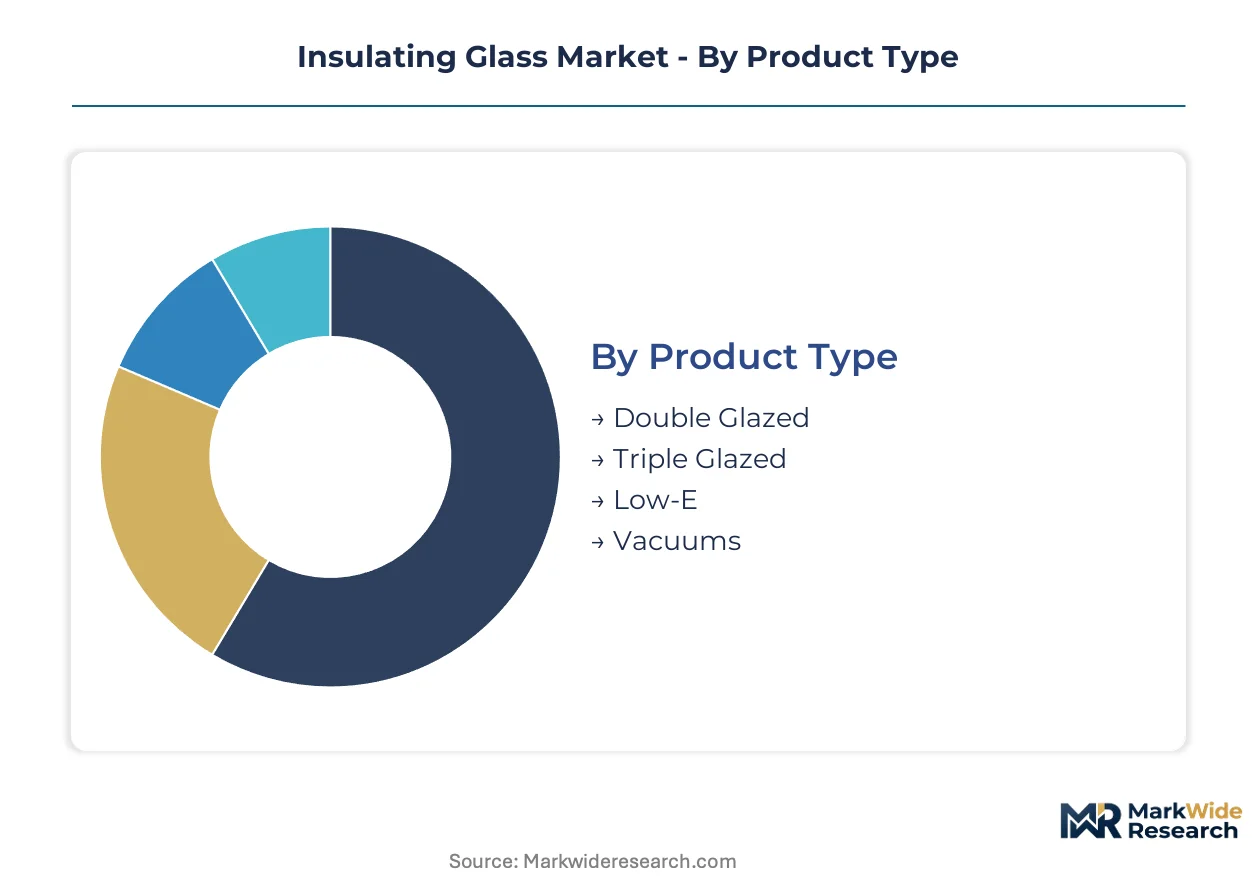
Segmentation in insulating glass reveals how capital deployment, regulatory thresholds, and installation economics allocate margin across distinct technical configurations. Fabricators must align product mix with the specific thermal performance mandates and structural constraints governing each end-use environment.
Product Type:
Capital intensity escalates sharply with cavity complexity and coating sophistication, separating commodity double-glazed volume from precision-manufactured vacuum and suspended-film assemblies.
- Double Glazed:Two glass lites separated by a sealed air or gas-filled cavity with desiccant-filled spacers. Residential construction in Germany and the United States consumes the majority of volume as building codes mandate baseline thermal performance upgrades.
- Triple Glazed:Three glass lites with dual cavities, achieving whole-window U-factors below 0.80 W/m²K. Nordic and Alpine passive house construction in Sweden, Norway, and Austria is pulling specification toward these assemblies despite weight and frame-depth constraints.
- Low-E:Sputtered metallic coatings on glass surfaces that reduce emissivity and solar heat gain. Commercial curtain wall projects in Chicago and Toronto specify solar heat gain coefficients below 0.25.
- Vacuums:Evacuated cavities between glass lites eliminating gas conduction entirely. Thin-profile retrofits in heritage building envelopes where frame replacement is prohibited.
Double glazed absorbs the bulk of installed capacity; triple glazed is expanding most quickly.
Application:
Margin structure diverges across application types based on certification burden, warranty terms, and the balance between new construction volume and replacement pricing power.
- Residential:Single-family and multi-family building envelopes with standardized window openings. Western European markets exhibit mature replacement cycles while Indian urban stock in Mumbai and Delhi presents concentrated retrofit opportunity under tightening BIS codes.
- Commercial:High-rise curtain walls and storefront systems requiring whole-system thermal certification. Institutional developers in Frankfurt and Toronto are consolidating direct procurement relationships with fabricators.
- Automotive:Heated windshields and acoustic laminated assemblies for electric vehicle cabins. OEM thermal management specifications are integrating glass U-factor targets with battery range optimization.
- Skylights:Sloped glazing assemblies with enhanced structural loading and condensation resistance requirements. Alpine hospitality and Nordic public building retrofits specify triple-glazed configurations with warm-edge spacers.
Commercial applications command premium pricing through certified performance warranties; residential retrofit channels are climbing the fastest as EU Green Deal renovation mandates accelerate replacement timelines.
Material:
Frame material selection determines thermal bridging characteristics, structural span capability, and the compatibility with triple-glazed unit weights in high-performance assemblies.
- Aluminium:High-strength extrusions with thermal break inserts for commercial facades. German and Austrian fabricators dominate specification for large-span curtain wall projects.
- PVC:Multi-chamber extrusions with inherent thermal resistance for residential volume markets. French and Italian window manufacturers specify these for CE-marked performance declarations.
- Wood:Solid timber or engineered lumber frames with natural thermal properties. Alpine and Nordic heritage building retrofits where aesthetic continuity is mandated.
- Composite:Aluminum-clad wood or fiberglass-reinforced profiles combining structural performance with thermal efficiency. Passive house certification programs in Germany and Switzerland are driving specification.
Aluminium frames retain the largest share of commercial project value; composite materials are gaining share fastest as passive house standards penetrate mid-rise construction.
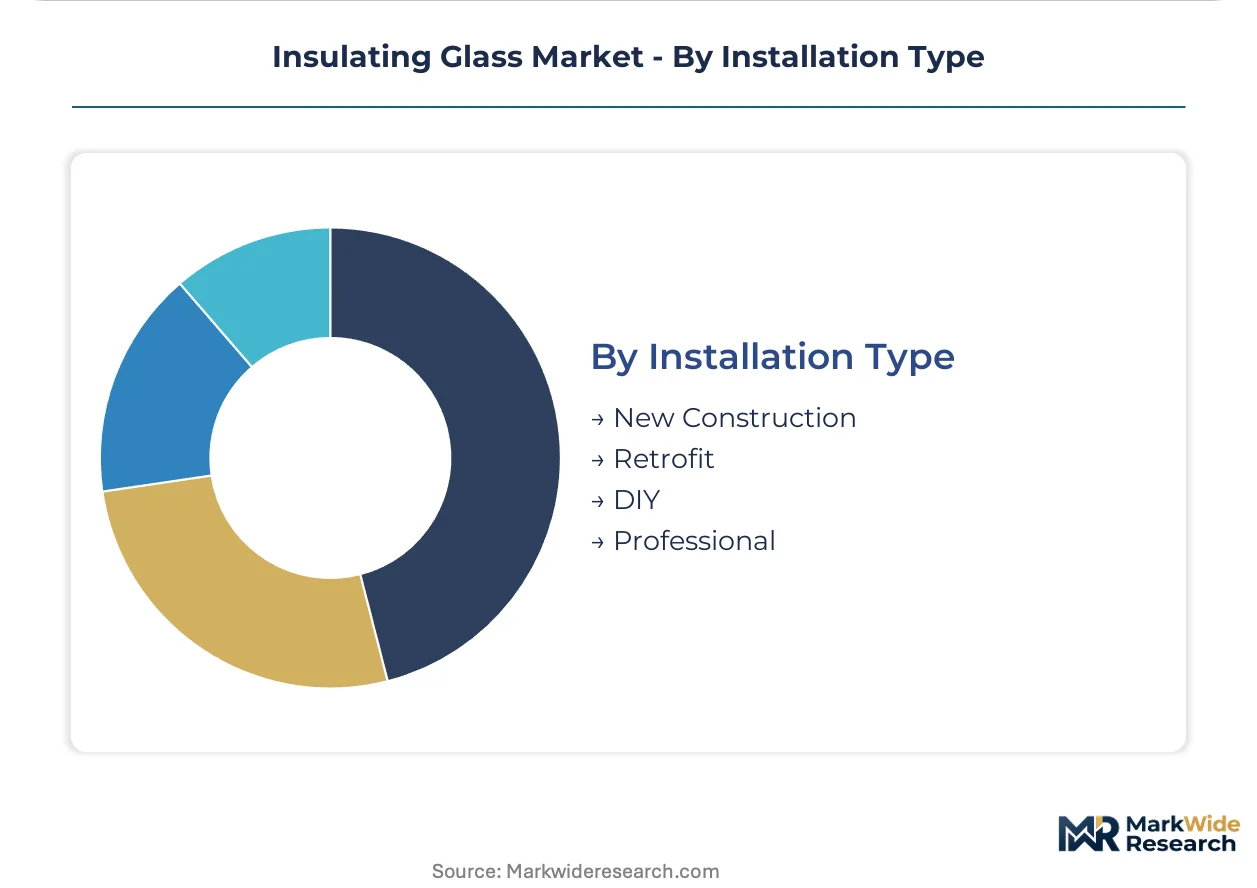
Installation Type:
Channel economics separate professional installation networks with performance warranties from product-only sales through retail and contractor supply.
- New Construction:Specified during design phase with whole-system thermal modeling. Institutional developers in Chicago and Frankfurt are compressing procurement timelines through direct fabricator relationships.
- Retrofit:Replacement of existing glazing within constrained frame depths. Thin triple glazing with warm-edge spacers is penetrating German and Austrian markets where structural reinforcement is cost-prohibitive.
- DIY:Consumer-purchased units through retail channels without installation service. Standard double-glazed residential sizes dominate this price-sensitive segment.
- Professional:Certified installer networks bundling product, labor, and performance warranties. Margin pools are shifting toward these channels in Western Europe as warranty terms extend.
Professional installation captures expanding margin through warranty bundling; retrofit activity is climbing the fastest as EU and Indian regulatory frameworks tighten energy efficiency requirements for existing building stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial high-rise construction concentrates procurement power among institutional developers in Germany, the United States, and China, while retrofit mandates in India and France accelerate replacement demand across existing building stock.
Germany
Passive house construction in Berlin and Munich specifies triple-glazed assemblies with whole-window U-factors below 0.80 W/m²K. The KBA does not regulate this sector; instead, national building codes enforce CE-marked performance declarations. Bavarian fabricators dominate specification for large-span curtain wall projects across Alpine construction markets.
United States
Urban core development in Chicago and Toronto specifies low-E coated curtain walls with solar heat gain coefficients below 0.25. EPA Energy Star certification shapes product specifications, forcing manufacturers to certify whole-window U-factors rather than center-of-glass values. Midwest fabricators anchor North American supply through captive distribution networks serving regional window manufacturers.
China
Concentrated retrofit activity targets existing building stock in Beijing and Shanghai as MIIT energy efficiency codes tighten. GB standards govern thermal performance requirements for facade systems. Yangtze River Delta fabricators face escalating carbon border adjustment exposure under EU CBAM implementation timelines.
India
Urban stock in Mumbai and Delhi offers untapped replacement demand as BIS energy efficiency codes tighten. The CEA mandates higher thermal performance for commercial building envelopes. Maharashtra-based fabricators are consolidating procurement relationships with institutional developers for large-scale commercial retrofits.
France
EU Green Deal renovation mandates pull replacement volume toward high-performance insulating glass units in Paris and Lyon. ANSM does not regulate this sector; instead, national building codes enforce CE-marked performance declarations for facade retrofits. Île-de-French fabricators specialize in thin triple glazing with warm-edge spacers for heritage building envelopes where frame replacement is prohibited.
Insulating Glass Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue suspended-film and vacuum insulating glass technologies. The vendor base concentrates around vertically integrated float-glass-to-fabrication operations and regional specialists with captive distribution networks. Three archetypes dominate: multinational glass conglomerates with coating capabilities, mid-scale regional fabricators serving professional installation channels, and technology specialists advancing warm-edge spacer systems. Competitive moves center on backward integration into float glass supply and certification-driven capacity expansion for triple-glazed assemblies.
Among multinational glass conglomerates, Saint-Gobain and AGC Inc. exemplify the integrated archetype with operations spanning multiple continents. Guardian Industries occupies a position within the coated glass technology tier for high-performance facades. These three represent the concentration of procurement power among institutional developers capable of certifying whole-system performance across North American and European commercial high-rise markets.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Guardian Industries |
| NSG Group |
| Central Glass Co., Ltd. |
| Nippon Sheet Glass Co., Ltd. |
| Cardinal Glass Industries |
| Sika AG |
| Viracon |
| Others |
Value Chain & Pricing Dynamics
Thin triple glazing adoption simultaneously compresses manufacturing cost curves and concentrates procurement leverage among vertically integrated fabricators capable of float-to-fabrication traceability documentation. This production-method transition reshapes margin distribution as German and Austrian passive house standards force specification shifts toward warm-edge spacer configurations.
Pricing Analysis
Volume concentrates in double-glazed residential replacement while margin pools shift toward triple-glazed commercial assemblies. Three-tier pricing structure across premium, standard, and economy levels separates whole-window certified units from center-of-glass commodity volume. Cost compression in standard double-glazed tiers intensifies because Asian-sourced float glass faces escalating carbon border adjustment exposure under EU CBAM timelines. Institutional developers in Frankfurt and Toronto exhibit lowest price sensitivity; DIY retail channels in Western Europe remain most price-sensitive.
Supply Chain Analysis
Freight cost escalation from Yangtze River Delta fabricators to European curtain wall projects is reshaping regional sourcing strategies. Supply concentrates in China, Germany, and the United States for float glass and coating operations. Raw material dependencies center on soda-lime silica, argon and krypton noble gases, and desiccant-filled spacer systems. Single-source vulnerability in Asian float glass supply threatens import competitiveness. Distribution runs through captive distributor networks serving regional window fabricators in North America and professional installation channels in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulating glass market operates as a cost-of-compliance story where EU F-Gas Regulation phase-down schedules create a barrier-to-entry moat for European fabricators with CO₂-based physical foaming capabilities.
For Market Incumbents: Deploy warm-edge spacer technology convergence as the priority lever. Backward integration into captive float glass supply secures margin against carbon border adjustment exposure. Certification investment in IGCC and NFRC whole-window testing creates differentiation against Asian import competition. Channel control through professional installer network expansion captures warranty-bundled margin pools shifting from product-only sales.
For New Entrants and Emerging Players: Certified installer networks represent the most penetrable channel partner type for market entry. India existing building retrofit in Mumbai and Delhi offers concentrated white-space demand as BIS energy efficiency codes tighten. Suspended-film technology specialization enables premium positioning against conventional triple-glazed weight constraints. Direct procurement relationships with institutional developers bypass traditional window manufacturer intermediaries.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational glass conglomerates seeking coating and fabrication capabilities. Long-term viability favors vertically integrated operations with float-to-fabrication traceability documentation. Target archetypes include mid-scale regional fabricators with captive distribution networks and warm-edge spacer technology specialists. Watch for EU CBAM implementation acceleration as the inflection signal for supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass Supply | Carbon border adjustment exposure under EU CBAM threatens Asian import competitiveness. |
| Warm-Edge Spacer Technology Certification | EU F-Gas Regulation phase-down forces CO₂-based physical foaming transition. |
| Professional Installer Network Expansion | Performance warranty bundling captures margin pools shifting from product-only channels. |
| Whole-Window U-Factor Certification Investment | EPA Energy Star and EU Green Deal mandate whole-system performance declarations. |
| India Market Entry Through Retrofit Specialization | BIS energy efficiency code tightening accelerates Mumbai and Delhi replacement demand. |
Study Parameters
Trade databases, national building code filings, and SEC 10-K disclosures formed the secondary backbone for volume and value estimation. Primary interviews with insulating glass fabricators, window manufacturer procurement leads, commercial developer specification managers, and warm-edge spacer technology suppliers validated secondary assumptions. Bottom-up and top-down triangulation reconciled unit shipment data with regional construction permit analysis.
Bottom-up modeling tracked cavity complexity, coating sophistication, and frame material combinations across the projection horizon. Segmentation dimensions included product type, application, material, and installation channel. CAGRs derived from regression analysis against energy code ratchet timelines and passive house construction penetration. Forecast inputs incorporated noble gas pricing volatility and carbon border adjustment implementation schedules.
Caveats apply where EU CBAM acceleration, F-Gas Regulation phase-down delays, or float glass supply disruption could materially shift the outlook. Forecasts reflect documented assumptions around regulatory enforcement and construction cycle timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Antiglare Glass Market
Glass
Heat Resistant Glass Market
Glass
Optical Glass Market
Glass
Europe Glassware Market
Glass
Global Self-Cleaning Glass Market
Glass
Middle East and Africa Glassware Market
Glass
Glass Recycling Market
Glass
Solar PV Glass Market
Glass
Solar Control Glass Market
Glass
Technical Glass Market
Glass
Float Glass Market
Glass
Glass Reactors Market
Glass
Silica Sol Market
Glass
Flexible Glass Market
Glass
Global Laminated Glass Market
Glass
Crystalware and Glassware Market