
 HPLC Fused Silica Tube Market | 2026-2036
HPLC Fused Silica Tube Market Size, Share, and Industry Trends Forecast 2026-2036
HPLC Fused Silica Tube Market Analytics
Germany is narrowing its capacity gap in high-purity fused silica drawing for analytical instrumentation. Agilent Technologies leverages vertical integration across chromatography system manufacturing to secure captive tube supply. Thermo Fisher Scientific anchors North American demand through its laboratory consumables distribution network. Waters Corporation specializes in ultra-performance liquid chromatography configurations that impose exacting bore tolerance specifications on silica suppliers.
HPLC fused silica tube denotes synthetic amorphous silicon dioxide tubing drawn to precise internal diameters, typically 50–530 microns, with polyimide or PEEK external coating to prevent hydration-induced brittleness; manufacturers achieve surface silanol group deactivation through thermal and chemical treatments to minimize analyte adsorption during liquid-phase separations. Capillary tubes dominate procurement volumes due to their ubiquity in gas and liquid chromatography interfaces, while tubing assemblies command premium positioning by integrating ferrule connections and guard columns that reduce installation labor for pharmaceutical quality control laboratories. The high-performance liquid chromatography technology segment sustains the largest installed base, though ultra performance liquid chromatography applications are displacing legacy configurations where sub-two-micron particle columns require elevated pressure ratings exceeding 15,000 psi.
FDA method validation guidelines and EMA GMP Annex 1 revisions both mandate material certificates of origin for consumables contacting drug substances during analytical testing. EPA SW-846 methods for environmental contaminant monitoring specify fused silica inertness standards that filter non-compliant suppliers from bid pools. Stakeholders must monitor evolving pharmacopeial monographs from USP and EP regarding surface activity limits, as these standards will determine which drawing and deactivation processes remain commercially viable.
Market Dynamics
Ultra-performance liquid chromatography adoption is compressing legacy HPLC replacement cycles, forcing fused silica suppliers to certify tubes for pressure ratings exceeding 15,000 psi while maintaining sub-micron bore tolerances.
Growth Catalysts
- FDA Method Validation Guidelines:The updated guidelines mandate material certificates of origin for consumables contacting drug substances, driving pharmaceutical laboratories toward certified domestic suppliers with full traceability documentation.
- Biopharma Quality Control Expansion:Contract research organizations in Germany's Rhine-Main cluster and the Boston-Cambridge corridor are scaling chromatography infrastructure for monoclonal antibody characterization workflows.
- Surface Deactivation Chemistry:Advanced thermal and chemical treatments that minimize silanol group activity are expanding addressable applications to polar analyte separations previously requiring stainless steel alternatives.
Market Restraints
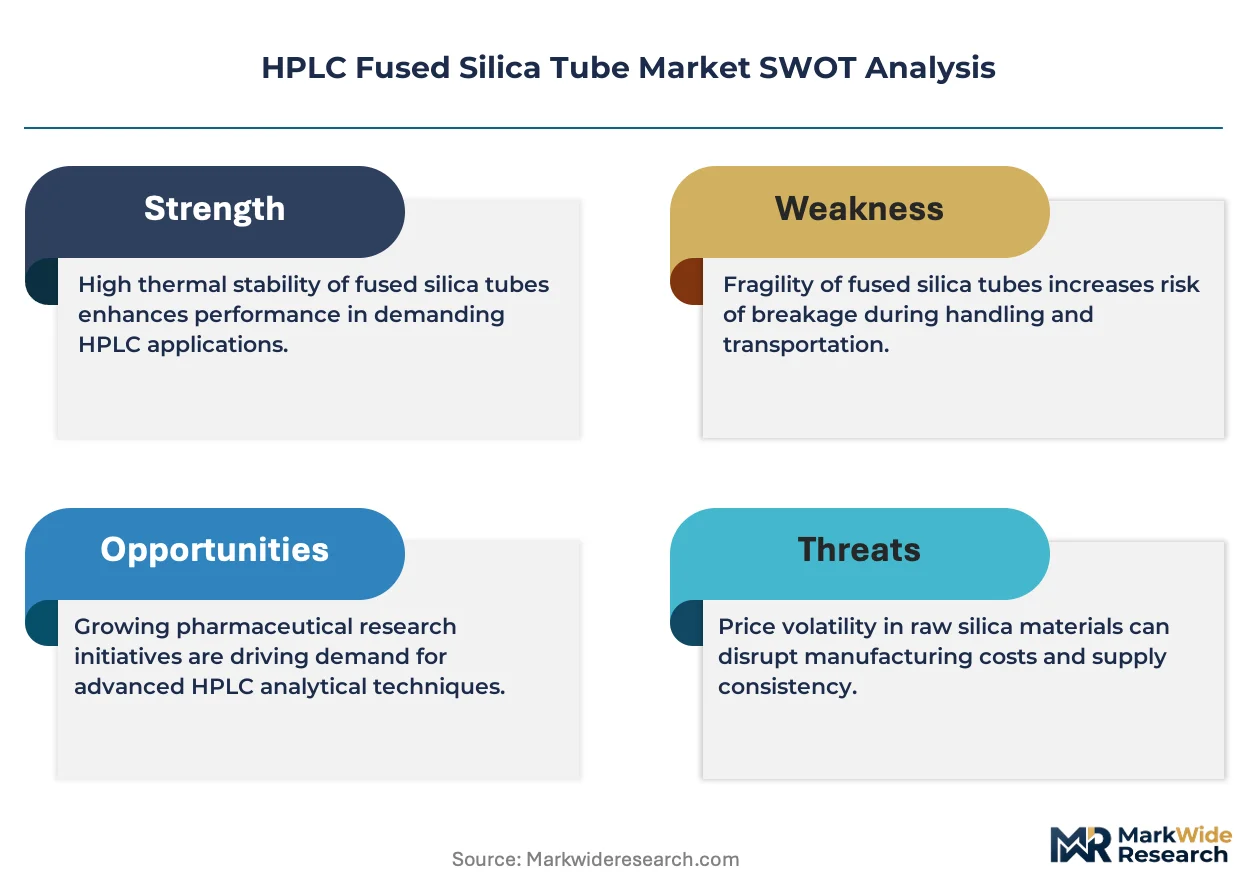
- High-Purity Silica Feedstock Concentration:Semiconductor-grade silicon tetrachloride supply concentrates among a limited number of German and Japanese chemical producers, creating input cost volatility for tube manufacturers.
- REACH Compliance Burden:ECHA registration requirements for synthetic amorphous silicon dioxide impose documentation costs that disproportionately burden smaller drawing operations without dedicated regulatory affairs functions.
- PEEK-Coated Stainless Steel Substitution:Metal capillary tubing with polymer exterior coatings offers comparable pressure ratings at lower unit costs for applications where absolute inertness is not critical.
Strategic Opportunities
- India CDMO Infrastructure Buildout:Contract development and manufacturing organizations under India's PLI scheme for pharmaceuticals are establishing analytical method transfer capabilities that require certified chromatography consumables.
- Environmental Monitoring Mandates:EPA SW-846 methods for contaminant detection specify fused silica inertness standards, creating a regulatory tailwind for suppliers serving state and municipal testing laboratories.
- Pre-Assembled Tubing Kits:Integrated ferrule connections and guard columns reduce installation labor for quality control technicians, commanding premium positioning against commodity capillary sales.
Industry Challenges
- Precision Drawing Specialist Scarcity:The intersection of glassblowing craft knowledge and semiconductor-grade cleanroom protocols creates a narrow talent pipeline for bore tolerance control below 10 microns.
- Pharmacopeial Monograph Uncertainty:Pending USP and EP revisions regarding surface activity limits threaten to invalidate existing deactivation process investments without warning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HPLC Fused Silica Tube Market |
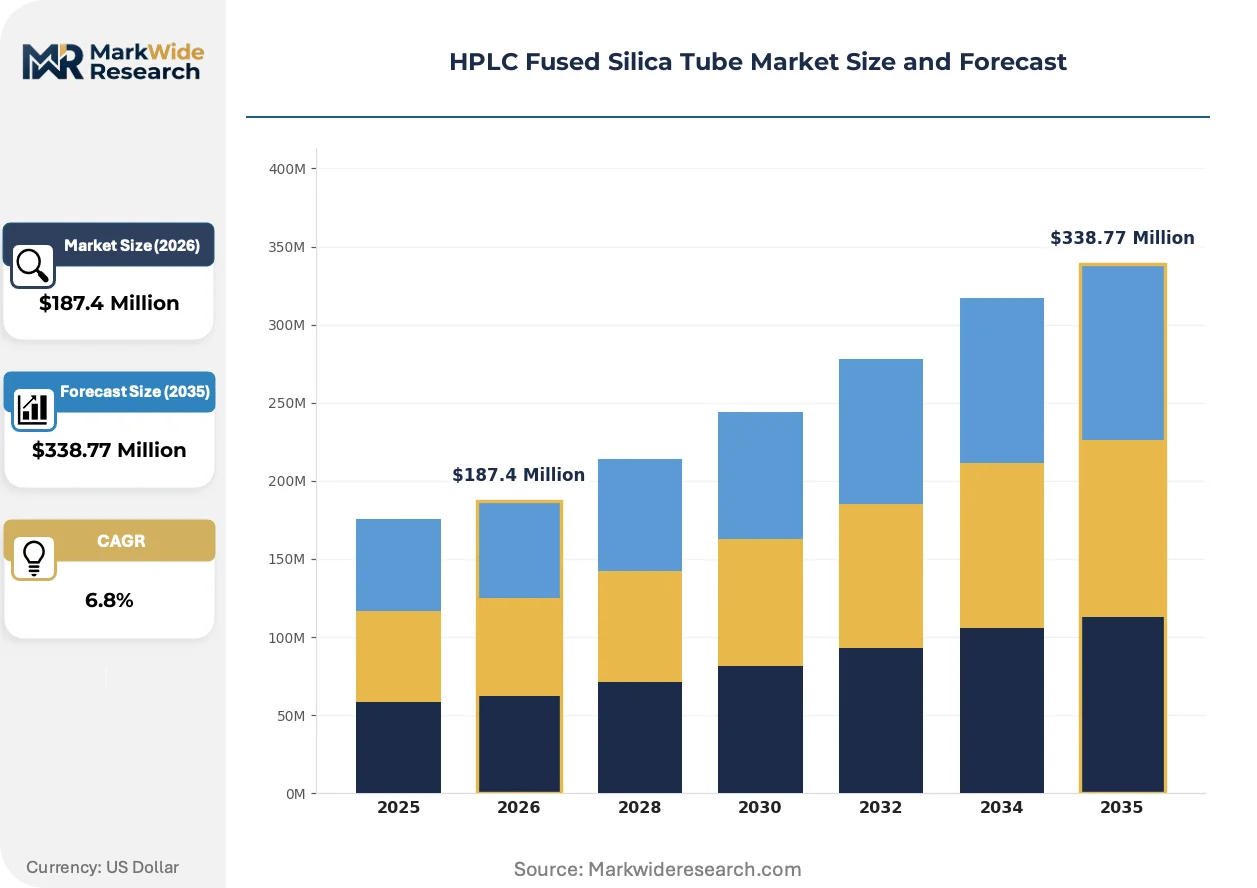
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Tubes, Optical Fibers, Tubing Assemblies, Injection Tubes Application: Chromatography, Sample Preparation, Chemical Analysis, Solvent Delivery End User: Laboratories, Pharmaceutical Industry, Research Institutions, Quality Control Technology: Static Column, Liquid Chromatography, High-Performance Liquid Chromatography, Ultra Performance Liquid Chromatography |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Waters Corporation, PerkinElmer Inc., Merck KGaA, Restek Corporation, Trajan Scientific and Medical, Valco Instruments Co. Inc., Scientific Instrument Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HPLC Fused Silica Tube Market Evolving Landscape
Sub-two-micron stationary phase particles are rewriting pressure and dimensional specifications across analytical consumables, compressing the viable supplier base to those with precision manufacturing capabilities.
Laser-based internal diameter measurement systems combined with real-time drawing tension control are rendering obsolete manual bore verification methods that introduced batch-to-batch variability. Pharmaceutical quality control laboratories in Germany and the United States are specifying these advanced tubes for high-throughput screening workflows where column-to-column reproducibility directly impacts regulatory submission timelines. The technology is compressing acceptable tolerance windows from ±5 microns to ±2 microns, disqualifying legacy suppliers from premium bid pools.
EMA GMP Annex 1 revisions now require environmental monitoring of cleanroom conditions during consumables manufacturing, extending quality system obligations to component suppliers previously exempt from direct oversight. This regulatory expansion forces fused silica drawing operations to install continuous particle counting and viable monitoring infrastructure. Contract research organizations in the Boston-Cambridge corridor are auditing supplier facilities against these standards, filtering non-compliant vendors from approved vendor lists.
Direct sourcing relationships between pharmaceutical manufacturers and specialized drawing houses are displacing distributor-mediated procurement for high-volume applications. Thermo Fisher Scientific's laboratory consumables network and similar channels still dominate smaller laboratory accounts, but multi-site pharmaceutical operators are negotiating frame contracts with domestic silica suppliers. This pattern concentrates most visibly in Germany's Rhine-Main biotech cluster, where proximity preferences reinforce supply chain regionalization.
HPLC Fused Silica Tube Market Segmentation
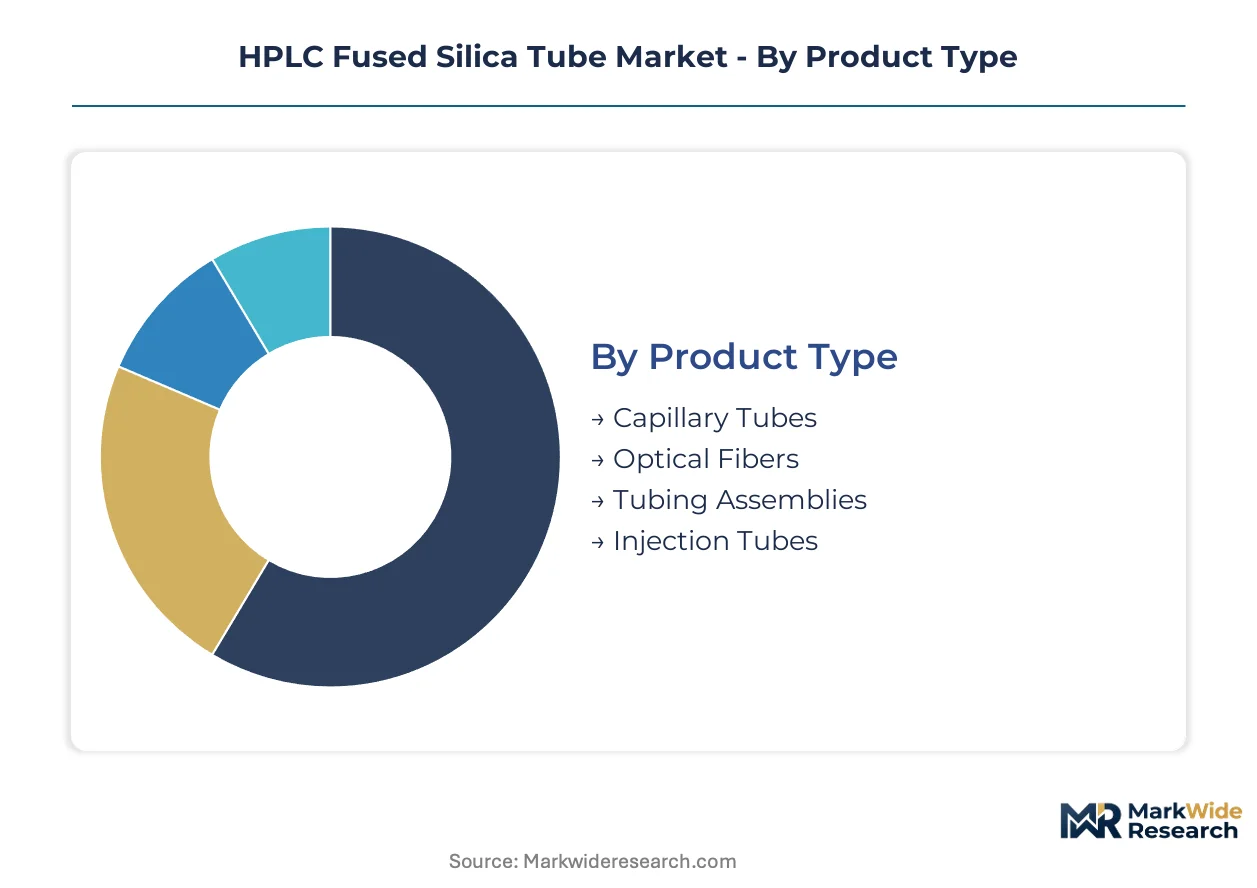
Segmentation in the HPLC fused silica tube market reveals how pressure ratings, coating specifications, and connection geometries align with distinct analytical workflows. Procurement patterns diverge sharply between routine quality control operations and specialized biopharma characterization tasks.
Product Type:
Application requirements span from single-use capillary replacements to integrated system components that reduce installation time.
- Capillary Tubes:Drawn to internal diameters between 50 and 530 microns with polyimide exterior coatings preventing hydration-induced fracture. Pharmaceutical quality control laboratories in Germany's Rhine-Main cluster procure these in volume for high-throughput screening workflows where column-to-column reproducibility affects regulatory submission timelines.
- Tubing Assemblies:Pre-configured with ferrule connections and guard columns that eliminate manual fitting labor. Boston-Cambridge contract research organizations specify these for monoclonal antibody characterization workflows where installation errors risk batch contamination.
- Optical Fibers:Specialized silica waveguides for spectroscopic detection interfaces in chromatography systems.
- Injection Tubes:Precision-bore components for autosampler fluid paths requiring sub-micron tolerance control.
The dominant share belongs to Capillary Tubes, while Tubing Assemblies is closing the gap fastest.
Application:
Workflow differentiation separates commodity replacement demand from specialized analytical method development.
- Chromatography:Gas and liquid phase separation systems utilizing deactivated silica surfaces to minimize analyte adsorption. Ultra-performance configurations now displace legacy HPLC where sub-two-micron particle columns require pressure ratings exceeding 15,000 psi.
- Sample Preparation:Solid-phase extraction and microfluidic pre-concentration steps preceding analytical separation.
- Chemical Analysis:Environmental contaminant monitoring under EPA SW-846 methods that specify fused silica inertness standards, filtering non-compliant suppliers from state and municipal laboratory bid pools.
- Solvent Delivery:High-pressure fluid routing in pump modules and gradient mixing systems.
Chromatography commands the largest installed base, though Sample Preparation is climbing the fastest as automated pre-analytical workflows expand.
End User:
Procurement scale and certification requirements create distinct customer tiers with diverging supplier relationship models.
- Pharmaceutical Industry:Multi-site manufacturers negotiating frame contracts directly with domestic silica suppliers to satisfy FDA method validation guidelines mandating material certificates of origin. EMA GMP Annex 1 revisions now extend quality system obligations to component suppliers through cleanroom environmental monitoring requirements.
- Laboratories:Academic and industrial research facilities with lower volume requirements.
- Quality Control:Dedicated analytical groups within manufacturing organizations prioritizing batch-to-batch consistency.
- Research Institutions:Exploratory method development with flexible specification tolerance.
Pharmaceutical Industry holds the dominant procurement volume, while Quality Control is gaining share fastest as in-house analytical capabilities expand.
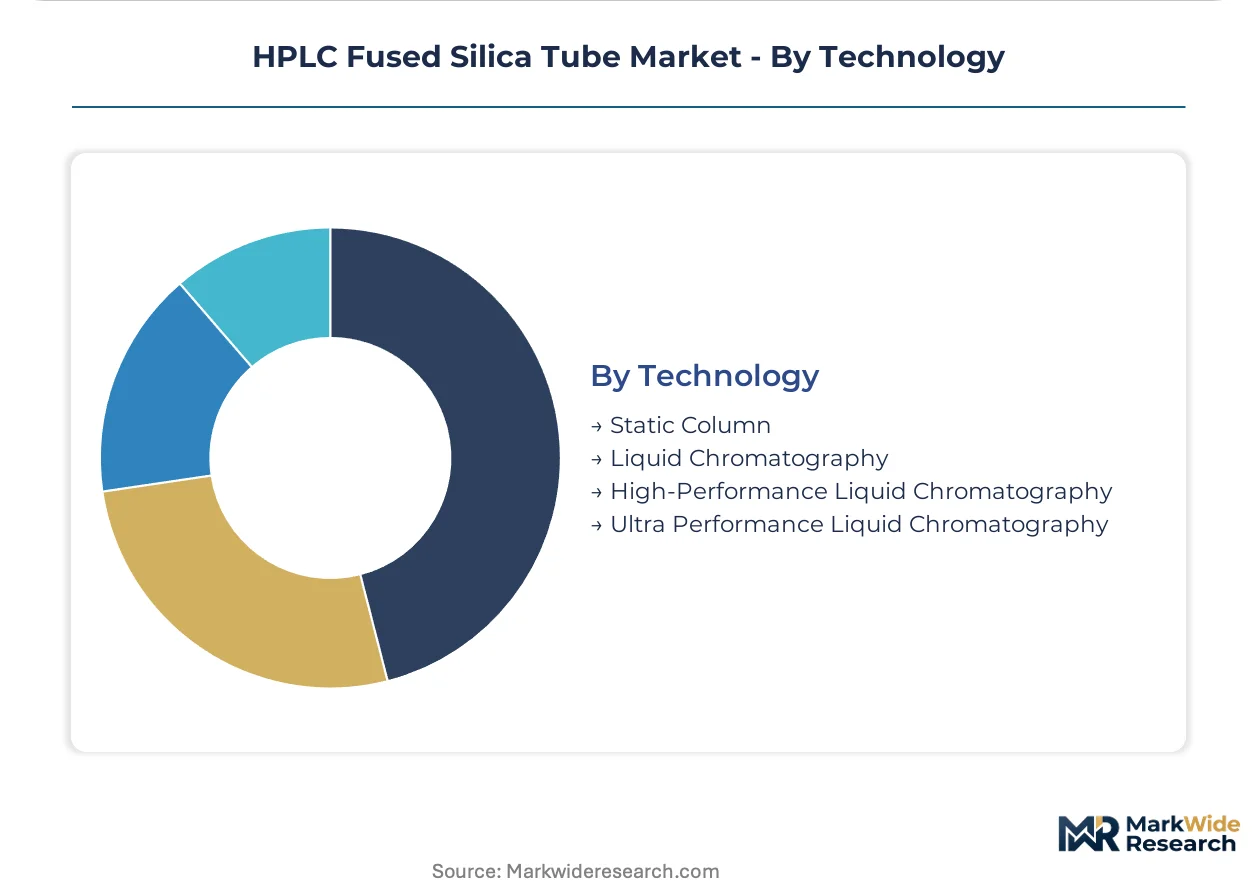
Technology:
Pressure tolerance and particle size compatibility segment the technology landscape into distinct equipment generations.
- Ultra Performance Liquid Chromatography:Systems operating above 15,000 psi with sub-two-micron stationary phases. Waters Corporation configurations impose exacting bore tolerance specifications that compress acceptable windows from ±5 microns to ±2 microns, disqualifying legacy suppliers from premium bid pools.
- High-Performance Liquid Chromatography:Established installed base with moderate pressure requirements and broader supplier qualification.
- Liquid Chromatography:General-purpose analytical systems with standardized connection geometries.
- Static Column:Pre-packed separation media in fused silica housings for specific analytical methods.
High-Performance Liquid Chromatography sustains the largest installed base, though Ultra Performance Liquid Chromatography is expanding most quickly as biopharma quality control workflows upgrade infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity fused silica drawing capacity clusters in Germany and the United States, where precision manufacturing infrastructure and pharmaceutical demand concentration create self-reinforcing supply advantages. Japan and China maintain significant positions through semiconductor-grade feedstock production and expanding domestic analytical instrumentation markets. India represents an emerging demand center as contract development organizations build quality control capabilities under national production-linked incentive schemes.
United States
FDA method validation guidelines mandate material certificates of origin for consumables contacting drug substances, driving pharmaceutical laboratories toward certified domestic suppliers. The EPA's SW-846 environmental monitoring methods specify fused silica inertness standards that filter non-compliant vendors from state laboratory procurement pools. The Boston-Cambridge pharmaceutical corridor concentrates contract research organization demand for ultra-high-purity tubing in monoclonal antibody characterization workflows.
Germany
EMA GMP Annex 1 revisions extend cleanroom environmental monitoring requirements to component suppliers, forcing drawing operations to install continuous particle counting infrastructure. ECHA REACH registration requirements for synthetic amorphous silicon dioxide impose documentation costs that favor larger manufacturers with dedicated regulatory affairs functions. The Rhine-Main biotech cluster anchors European procurement volume as multi-site pharmaceutical operators negotiate direct frame contracts with domestic silica suppliers.
Japan
METI industrial standards for analytical instrumentation components reinforce domestic quality benchmarks that limit import penetration in precision consumables. PMDA pharmaceutical manufacturing guidelines align with international traceability requirements while preserving preference for domestically sourced critical materials. The Chubu region around Nagoya maintains specialized drawing operations serving both chromatography system manufacturers and semiconductor equipment suppliers.
China
NMPA pharmaceutical regulator emphasis on supply chain security for analytical consumables accelerates import substitution programs in high-purity silica processing. GB standards for laboratory equipment specify performance criteria that domestic manufacturers must meet to qualify for government-funded research facility procurement. The Yangtze River Delta concentration of contract manufacturing organizations drives demand for certified tubing in method transfer and quality control applications.
India
CDSCO pharmaceutical quality guidelines increasingly reference international material traceability standards as domestic manufacturers seek export market access. The PLI scheme for pharmaceuticals incentivizes contract development organizations to establish analytical method transfer capabilities requiring certified chromatography consumables. Maharashtra and Gujarat host the fastest-growing concentration of quality control laboratories serving both domestic production and international client method validation requirements.
HPLC Fused Silica Tube Market Competitive Landscape
Chromatography system integrators and specialized consumables suppliers split the market along vertical integration boundaries. Three strategic archetypes dominate: diversified analytical instrumentation conglomerates with captive tube production, independent precision drawing houses serving multiple OEMs, and regional fabricators competing on proximity and customization speed. Competitive moves concentrate on backward integration into high-purity feedstock sourcing and geographic expansion through distributor network partnerships in emerging pharmaceutical manufacturing clusters.
Among diversified instrumentation conglomerates, Agilent Technologies, Thermo Fisher Scientific, and Waters Corporation exemplify distinct strategic positions. Agilent leverages in-house production of chromatography consumables to secure supply chain control for its system installations. Thermo Fisher anchors North American distribution through laboratory consumables networks spanning research and quality control segments. Waters occupies a specialized position in ultra-performance liquid chromatography configurations that impose exacting specifications on component suppliers. Independent drawing houses and regional specialists compete against this integrated tier by offering customization flexibility and regional proximity to mid-scale pharmaceutical operators.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Waters Corporation |
| PerkinElmer Inc. |
| Merck KGaA |
| Restek Corporation |
| Trajan Scientific and Medical |
| Valco Instruments Co. Inc. |
| Scientific Instrument Services, Inc. |
| Others |
Value Network & Pricing Analysis
The Rhine-Main logistics corridor connects German precision drawing operations to pharmaceutical clusters across Western Europe, with freight cost dynamics amplifying the pricing power of domestic suppliers holding REACH-compliant certification tiers against Asian imports facing documentation burden.
Pricing Analysis
FDA method validation guidelines dictate the pricing tier structure across the HPLC fused silica tube market. Three-tier pricing structure across premium, standard, and economy levels separates pharma-grade certified tubes with full traceability documentation from general laboratory grades and uncertified commodity capillaries. Price differentiation hinges on bore tolerance precision and EMA GMP Annex 1 cleanroom certification status. Cost compression in the standard tier is intensifying because PEEK-coated stainless steel substitutes offer comparable pressure ratings at lower unit costs. Academic and industrial research facilities demonstrate highest price sensitivity, while multi-site pharmaceutical manufacturers negotiating direct frame contracts prioritize certification over unit cost.
Supply Chain Analysis
Semiconductor-grade silicon tetrachloride feedstock concentrates among specialized chemical producers in Germany and Japan, creating upstream dependency for tube manufacturers. High-purity silica drawing operations in Germany, the United States, and Japan anchor global supply, with precision coating chemistries and polyimide extrusion capabilities resting on specialized polymer suppliers. Single-source vulnerability runs through the limited number of semiconductor-grade feedstock producers capable of meeting pharmaceutical traceability requirements. Distribution runs through direct frame contracts between pharmaceutical manufacturers and domestic drawing houses for high-volume applications, supplemented by laboratory consumables networks serving smaller accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HPLC fused silica tube market sits in early-cycle expansion as ultra-performance liquid chromatography adoption accelerates replacement cycles and compresses supplier qualification windows.
For Market Incumbents: Harden certification moats by investing in continuous cleanroom particle counting infrastructure to satisfy EMA GMP Annex 1 environmental monitoring extensions. Deepen backward integration into semiconductor-grade silicon tetrachloride sourcing to buffer feedstock cost volatility from German and Japanese chemical producers. Lock in multi-year frame contracts with Boston-Cambridge and Rhine-Main pharmaceutical clusters before precision drawing specialist scarcity worsens. For New Entrants and Emerging Players: Establish a beachhead in India's contract development and manufacturing organization segment under the PLI scheme for pharmaceuticals, where analytical method transfer capabilities are expanding fastest. Target quality control laboratories in Maharashtra and Gujarat with pre-assembled tubing kits that reduce installation labor and command premium positioning. Lead with domestic certification partnerships that satisfy CDSCO pharmaceutical quality guidelines referencing international material traceability standards. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision drawing houses with captive deactivation chemistry capabilities and established pharma audit relationships over commodity capillary suppliers facing stainless steel substitution pressure. Long-term viability hinges on UPLC pressure rating certification above 15,000 psi as legacy HPLC replacement cycles compress. The signal to watch is USP and EP pharmacopeial monograph revisions regarding surface activity limits, which threaten to invalidate existing process investments without warning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Secures semiconductor-grade silicon tetrachloride supply against German and Japanese producer concentration. |
| Cleanroom Infrastructure Upgrade | Satisfies EMA GMP Annex 1 environmental monitoring extensions for component supplier qualification. |
| Pre-Assembled Tubing Kit Development | Reduces installation labor for Boston-Cambridge monoclonal antibody characterization workflows. |
| India CDMO Partnership Expansion | Captures PLI scheme-driven analytical method transfer demand in Maharashtra and Gujarat clusters. |
| Laser-Based Diameter Measurement Deployment | Compresses bore tolerance windows from ±5 microns to ±2 microns for UPLC qualification. |
Research Methodology
Cross-validation between primary field engagement and secondary regulatory documentation anchors the qualitative findings in this study. Interviews with chromatography system engineers, pharmaceutical quality control managers, regulatory affairs specialists at consumables manufacturers, and procurement leads at contract research organizations combined with FDA method validation guidance documents, EMA GMP Annex 1 revisions, EPA SW-846 method specifications, and USP pharmacopeial monograph drafts. Bottom-up demand modeling from individual laboratory procurement patterns and top-down supply assessment from drawing capacity installations were reconciled to establish market sizing.
Calibration against historical replacement cycle data and UPLC infrastructure deployment rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application workflow, end-user procurement scale, and technology generation pressure requirements. CAGRs were derived from weighted average of equipment installed base growth and consumables per-system attachment rates, with specific inputs from biopharma quality control expansion in Germany's Rhine-Main cluster and the Boston-Cambridge corridor.
Sensitivities concentrate around pharmacopeial monograph revisions, feedstock supply disruptions, and stainless steel substitution acceleration in non-critical applications. Cross-checking against customs trade data for high-purity silica tube movements and pharmaceutical capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Global Hydraulic Thermoplastic Hose and Couplings Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market